
 United States Sports Bags Market | 2026-2036
United States Sports Bags Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sports Bags Market Analytics
ASTM F963 toy safety certification is bifurcating the competitive landscape into qualified mass-market suppliers and excluded fringe entrants. Nike Inc. leverages its domestic distribution network to sustain shelf dominance at Dick's Sporting Goods and Academy Sports. Under Armour Inc. anchors its position through team-sport channel partnerships with NCAA programs. Adidas AG competes via specialized soccer and basketball bag lines engineered for club-level athletes.
Sports bags are portable containment systems engineered from woven synthetic textiles or treated natural fibers, typically incorporating ventilated compartments, reinforced stress points, and ergonomic load distribution to transport athletic equipment, footwear, and apparel between training and competition venues. Backpacks lead volume shipments due to cross-appeal across student and recreational segments, while duffel bags command premium positioning in professional and collegiate team channels. Nylon and polyester segments dominate material demand because of abrasion resistance and moisture-wicking properties, though leather maintains a defensible niche in executive fitness and luxury gym categories.
The Consumer Product Safety Commission enforces flammability and chemical content standards that elevate testing costs for new entrants, while California's Department of Toxic Substances Control administers stricter phthalate and PFAS restrictions that reshape material sourcing decisions for brands selling into the Western region. The Federal Trade Commission's Green Guides further constrain environmental marketing claims, forcing verification of recycled content assertions. Stakeholders must monitor evolving state-level chemical disclosure mandates and assess whether centralized or distributed manufacturing configurations better absorb compliance cost dispersion.
Market Dynamics
California's SB 54 extended producer responsibility law is decomposing virgin polyester supply chains by mandating post-consumer recycled content minimums, forcing manufacturers to reconfigure feedstock procurement and certification workflows.
Growth Catalysts
- Youth sports participation:Texas and Florida counties report participation rates exceeding national averages, concentrating equipment replacement cycles and team-sport bag demand in these metropolitan corridors.
- Collegiate equipment budget expansion:NCAA athletic departments are increasing capital allocations for travel gear, directly lifting institutional duffel and rolling bag procurement volumes.
- Recycled polyester infrastructure:Mechanical recycling capacity investments in the Southeast are reducing rPET price premiums, enabling cost-competitive sustainable product lines.
Market Restraints
- Petrochemical feedstock volatility:Nylon 6,6 and polyester chip prices fluctuate with crude oil derivatives, compressing margin predictability for mid-tier suppliers lacking long-term supply agreements.
- Regional regulatory fragmentation:California's Department of Toxic Substances Control enforces phthalate and PFAS restrictions stricter than federal Consumer Product Safety Commission baselines, forcing dual SKUs or Western-market exclusion.
- Concentrated retail gatekeeping:Dick's Sporting Goods and Academy Sports control shelf access in the Southeast and Southwest, extracting slotting fees that disadvantage emerging brands.
Strategic Opportunities
- Underpenetrated youth leagues:Midwestern states with rising lacrosse and rugby adoption lack specialized bag availability, creating first-mover positioning for sport-specific designs.
- Federal Trade Commission Green Guides compliance:Verified recycled content claims that withstand FTC scrutiny command shelf placement premiums as retailers face their own ESG disclosure pressures.
- Direct-to-team digital channels:Customization platforms enabling logo embroidery and color-matching bypass retail markups while capturing collegiate and club program loyalty.
Industry Challenges
- ASTM F963 certification timelines:Toy safety testing protocols for youth-targeted bags extend product development cycles by 8-14 weeks, delaying seasonal launches.
- Multi-state chemical disclosure mandates:Washington's Safer Products program and New York's emerging PFAS restrictions create overlapping compliance documentation requirements.
- Legacy ERP integration:Recycled content traceability systems require retrofitting existing inventory management infrastructure to satisfy extended producer responsibility audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sports Bags Market |
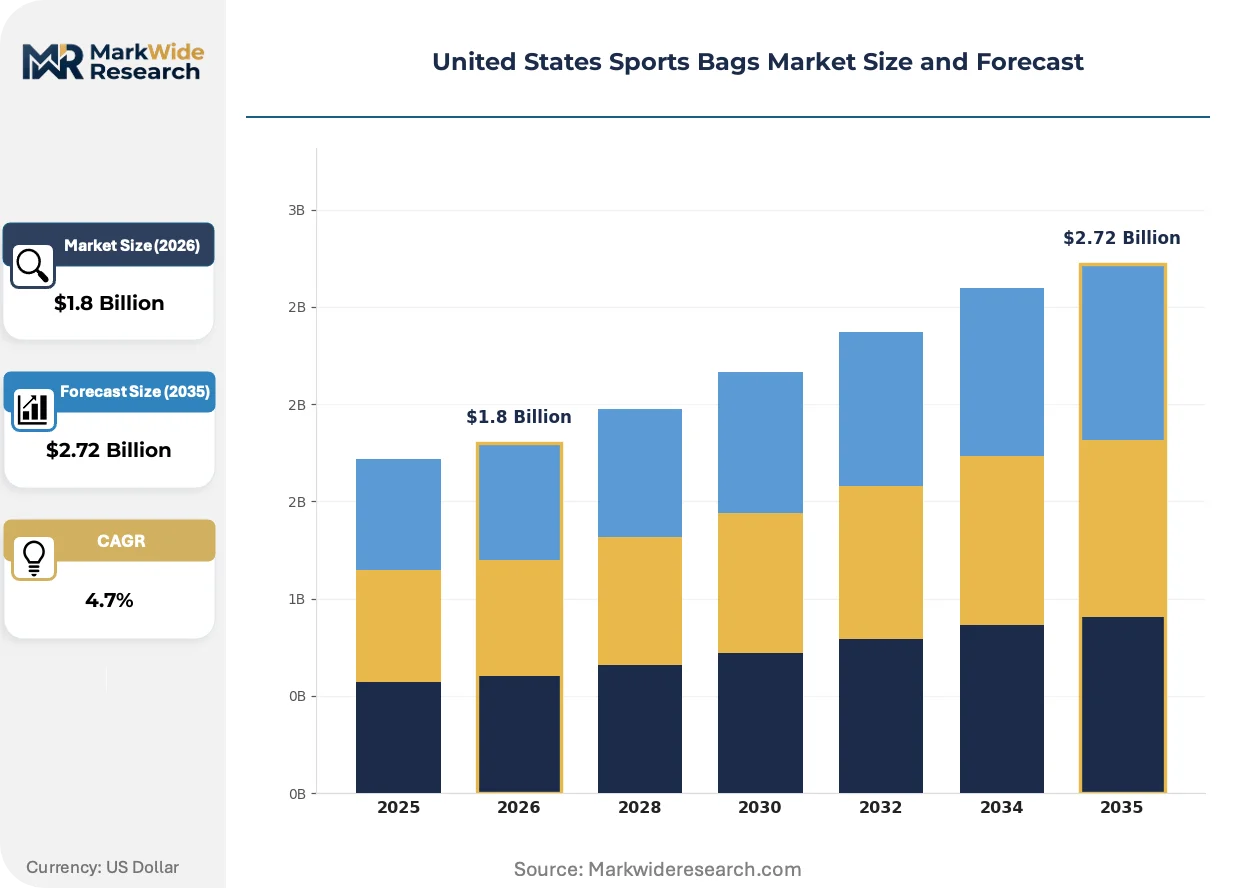
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpacks, Duffel Bags, Tote Bags, Gym Bags Material: Nylon, Polyester, Leather, Canvas End User: Athletes, Gym Enthusiasts, Recreational Users, Students Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Puma SE, Franklin Group, Nike Inc., Sport Maska Inc., Select Sport AS, Adidas AG, Rawlings Sporting Goods Company Inc., The North Face, Under Armour Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sports Bags Market Evolving Landscape
Material science breakthroughs and regulatory disclosure mandates are converging to reshape how sports bags are specified, sourced, and sold across institutional and consumer channels.
Modular compartment architecture is decomposing the traditional single-purpose bag category. Interchangeable pod systems allow athletes to reconfigure storage for gym, court, or field use within one chassis. Collegiate programs in Texas are piloting these systems to reduce equipment room inventory complexity. The technology is compressing SKUs while raising average transaction values through accessory attach rates.
The Federal Trade Commission's Green Guides enforcement is tightening environmental claim substantiation. Brands must document recycled content percentages through chain-of-custody certification or face civil penalty exposure. California retailers are demanding third-party verification before shelf placement, shifting competitive advantage toward suppliers with pre-audited supply chains.
Team-sport procurement officers are consolidating vendor relationships to reduce administrative burden. Multi-year equipment agreements that bundle bags with uniforms and protective gear are displacing transactional purchasing. This concentration is most visible in Florida high school athletic conferences, where cooperative purchasing agreements aggregate demand across districts.
United States Sports Bags Market Segmentation
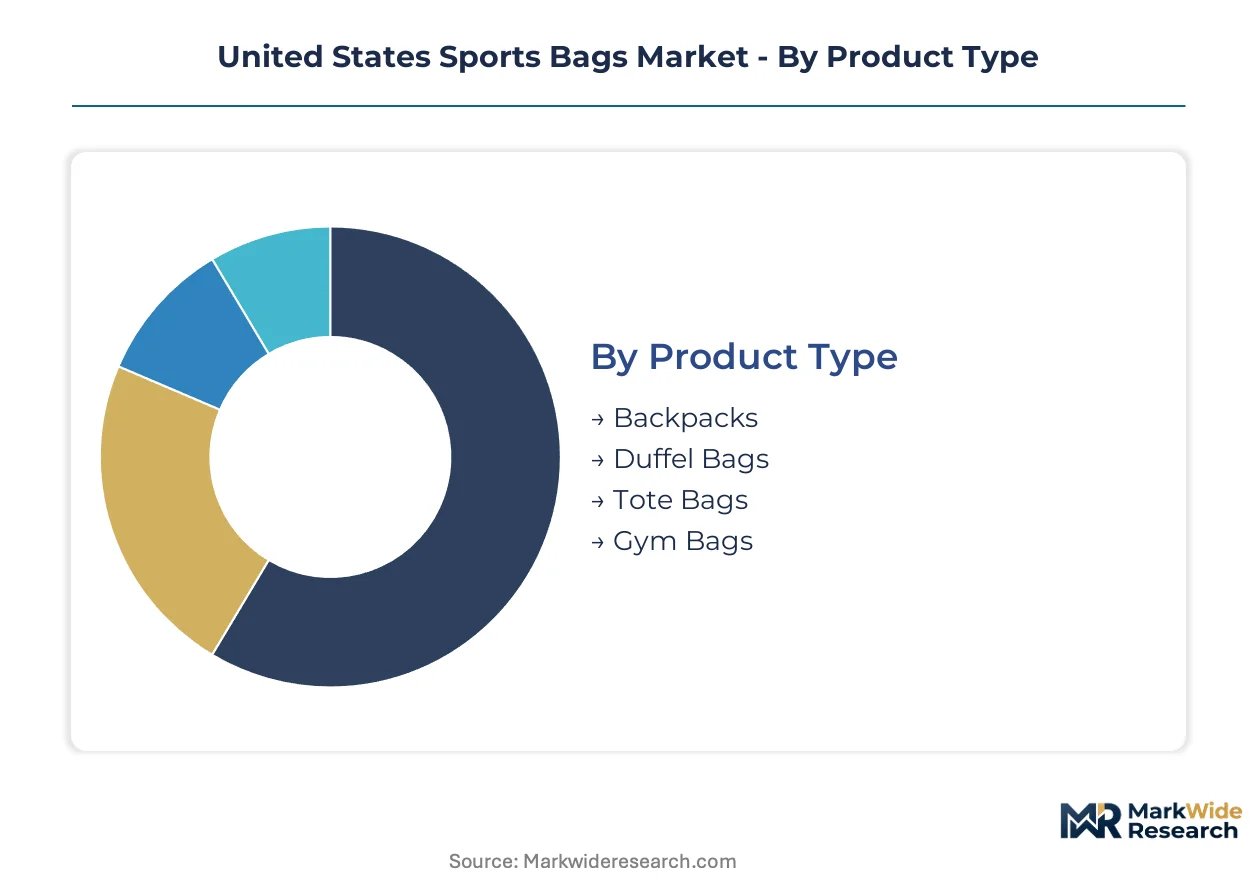
Product differentiation across the United States Sports Bags Market determines compliance burden, margin structure, and channel access. Manufacturers must align specifications with end-use intensity, material certification requirements, and retail partner expectations.
Product Type:
ASTM F963 certification timelines and ventilated compartment requirements split this category into youth-regulated and adult-unregulated design pathways.
- Duffel Bags:Reinforced stress points and oversized compartments accommodate team equipment transport for collegiate and professional programs. Texas and Florida athletic departments drive institutional procurement volumes through multi-year equipment agreements.
- Backpacks:Ergonomic load distribution systems with padded straps serve student and recreational crossover demand. Cross-appeal across academic and athletic use cases sustains volume leadership in retail channels.
- Gym Bags:Compact footprints with ventilated shoe compartments target executive fitness and boutique studio clientele. Moisture-wicking linings address post-workout storage requirements.
- Tote Bags:Open-top accessibility and lightweight construction appeal to yoga practitioners and recreational swimmers. Limited structural rigidity constrains equipment-heavy applications.
Established volume favors backpacks; emerging adoption favors duffel bags.
Material:
California's SB 54 extended producer responsibility law and the FTC Green Guides are restructuring feedstock procurement economics.
- Polyester:Abrasion-resistant woven synthetics with moisture-wicking properties dominate mass-market production. Southeast mechanical recycling capacity investments are compressing rPET price premiums for sustainable product lines.
- Nylon:High-tenacity fibers deliver superior tear resistance for professional-grade equipment transport. Petrochemical feedstock volatility compresses margin predictability for suppliers lacking long-term supply agreements.
- Leather:Full-grain and top-grain hides maintain positioning in executive fitness and luxury gym categories. California's phthalate restrictions constrain tanning chemical formulations for Western market access.
- Canvas:Treated cotton duck fabric offers biodegradable positioning for sustainability-focused consumers. Weight penalties and moisture absorption limit competitive viability in performance segments.
Volume concentration sits with polyester; sustainability premiums are climbing fastest for recycled variants.
End User:
Participation intensity and replacement frequency separate commercial-grade from consumer-grade durability requirements.
- Athletes:Competitive and professional users demand reinforced construction for daily equipment transport. NCAA program expansion in Texas and Florida concentrates team-sport bag procurement.
- Students:Cross-functional academic-athletic use drives backpack preference with price-sensitive specification. Youth sports participation rates in metropolitan corridors accelerate replacement cycles.
- Gym Enthusiasts:Boutique fitness studio attendance patterns favor compact, style-forward designs. Executive fitness segments sustain leather material premiums.
- Recreational Users:Infrequent participation permits lighter construction and lower price points. Seasonal activity patterns produce irregular demand timing.
Frequency of use favors athletes; household penetration expansion favors students.
Distribution Channel:
Slotting fee structures and ESG disclosure pressures are reconfiguring channel economics for emerging brands.
- Specialty Stores:Dick's Sporting Goods and Academy Sports control shelf access in the Southeast and Southwest, extracting fees that disadvantage unproven entrants. Staff expertise and fitting services sustain premium positioning.
- Online Retail:Direct-to-team customization platforms bypass retail markups while capturing collegiate and club program loyalty. FTC Green Guides compliance documentation enables verified environmental claim presentation.
- Department Stores:Seasonal promotional calendars and co-op advertising requirements compress margin structures. Foot traffic dependency limits athletic-specialist brand presence.
- Supermarkets:Impulse purchase placement and mass-market pricing target recreational users with undifferentiated specifications. Quality perception constraints premium brand distribution.
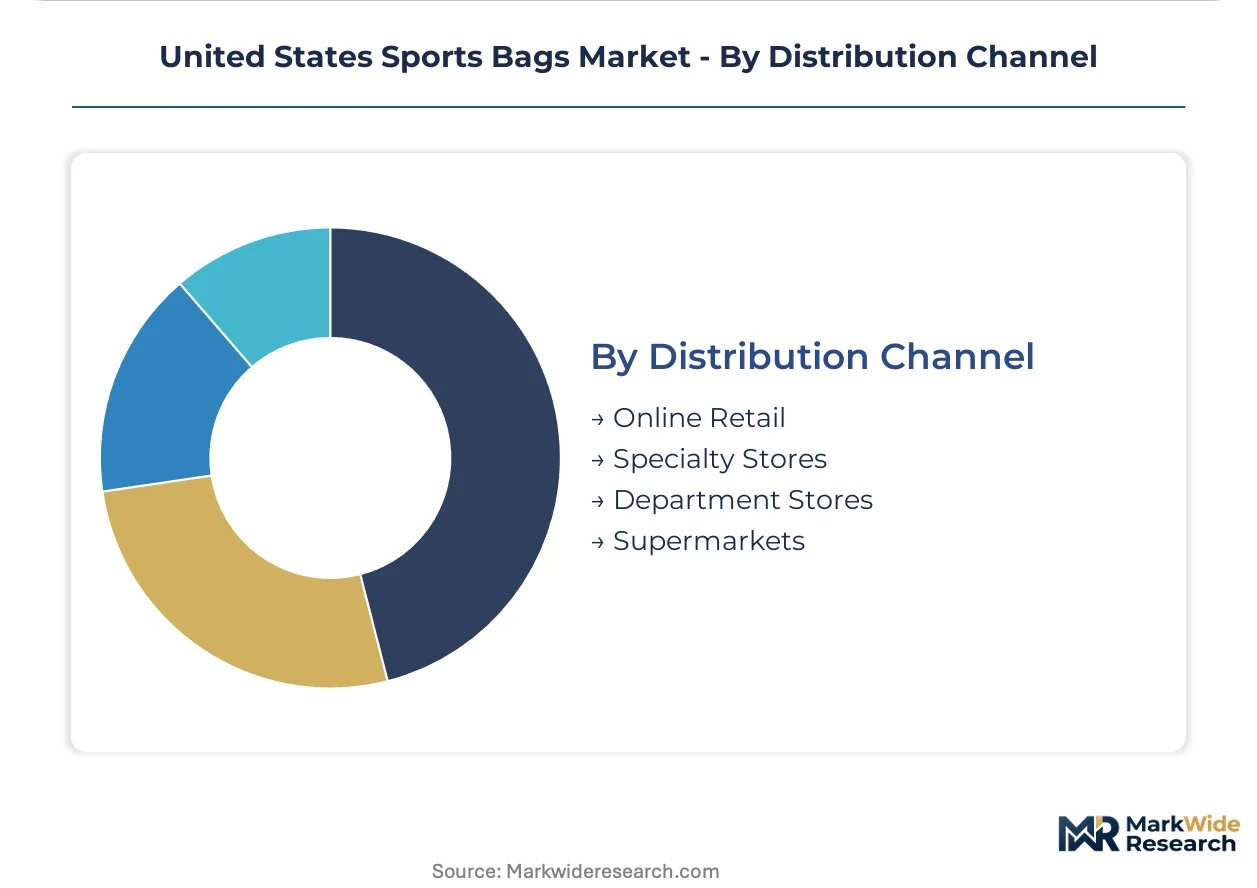
Margin protection favors online retail; volume throughput favors specialty stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles container complex processes the majority of imported synthetic textiles and finished sports bags entering the Western United States, anchoring California's role as the primary distribution gateway for national retail networks.
California
Los Angeles County and Orange County host the nation's densest concentration of action sports brands and specialty bag distributors. The state's Department of Toxic Substances Control enforces phthalate and PFAS restrictions that exceed federal Consumer Product Safety Commission baselines, forcing manufacturers to maintain dual material specifications for Western market access. SB 54 extended producer responsibility mandates are accelerating mechanical recycling infrastructure investments in the Central Valley to serve rPET feedstock requirements.
Texas
Dallas-Fort Worth and Houston metropolitan corridors report youth sports participation rates substantially above national averages, driving institutional procurement volumes for team duffel bags and rolling equipment cases. The Texas Education Agency's expanded athletics funding allocations support multi-year equipment agreements across suburban school districts. Austin's emerging outdoor recreation cluster is incubating specialized bag startups targeting collegiate and club program channels.
Florida
Miami-Dade, Broward, and Orange counties concentrate year-round youth league activity that compresses equipment replacement cycles versus seasonal Northern markets. The Florida High School Athletic Association's cooperative purchasing programs aggregate demand across districts, favoring suppliers with direct-to-team digital platforms. Tampa Bay's logistics infrastructure supports Southeast regional distribution for specialty sporting goods retailers.
New York Metro
The Port of New York and New Jersey serves as the secondary entry point for European-branded sports bags targeting Northeast retail channels. New York's emerging PFAS disclosure restrictions are creating compliance documentation requirements that overlap with Washington's Safer Products program. Manhattan's boutique fitness studio density sustains premium positioning for compact gym bag and tote categories.
Southeast
Georgia and the Carolinas host expanding mechanical recycling capacity for post-consumer polyester, reducing rPET price premiums for sustainable product lines serving Atlantic Coast markets. The region's collegiate athletic conference headquarters in Atlanta and Charlotte facilitate team-sport vendor relationship consolidation. Charleston's port modernization is improving import logistics efficiency for specialty sporting goods distributors.
United States Sports Bags Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access, creating a tiered structure where public company scale advantages confront agile private label responsiveness. The vendor base separates into three strategic archetypes: diversified sportswear conglomerates with captive bag lines, pure-play equipment specialists with deep team-sport relationships, and private label contractors serving price-sensitive retail tiers. Dominant competitive moves include direct-to-team digital platform development and recycled content supply chain certification to satisfy retailer ESG disclosure pressures.
Within the diversified sportswear tier, Nike Inc., Adidas AG, and Under Armour Inc. exemplify scale-driven positioning that leverages domestic distribution networks and collegiate athletic partnerships to sustain shelf presence at major sporting goods retailers. These listed entities anchor competitive dynamics through brand equity and procurement volume concentration, while private specialists including Franklin Group and Rawlings Sporting Goods Company Inc. occupy positions emphasizing sport-specific equipment heritage and team-channel relationships. The North Face represents outdoor-specialist crossover positioning that captures recreational and adventure-adjacent demand segments.
| Leading Market Players |
|---|
| Puma SE |
| Franklin Group |
| Nike Inc. |
| Sport Maska Inc. |
| Select Sport AS |
| Adidas AG |
| Rawlings Sporting Goods Company Inc. |
| The North Face |
| Under Armour Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles at specialty sporting goods retailers concentrate pricing power with Dick's Sporting Goods and Academy Sports, compressing margin capture for emerging brands while rewarding suppliers with certified recycled content streams and direct-to-team digital fulfillment capabilities.
Pricing Analysis
Volume-discount tiering structures separate institutional procurement from consumer retail, with NCAA programs and Florida high school athletic conferences capturing 15-25% unit cost advantages through multi-year equipment agreements. Certification grade—specifically FTC Green Guides compliance and ASTM F963 toy safety approval—drives price differentiation between mass-market and premium positioning. Pricing pressure stems from petrochemical feedstock volatility, which erodes margin predictability for mid-tier suppliers lacking long-term nylon and polyester chip contracts. Students represent the most price-sensitive segment, while collegiate athletic departments exhibit lowest sensitivity due to budgeted capital allocations.
Supply Chain Analysis
China, Vietnam, and Bangladesh anchor woven synthetic textile production for mass-market polyester and nylon segments, with finished goods consolidation occurring at the Port of Long Beach and Los Angeles. Raw material dependencies center on virgin and recycled polyester chips, high-tenacity nylon fibers, and specialized moisture-wicking coatings. Tariff exposure on Chinese imports creates structural risk for brands without diversified Southeast Asian sourcing. Distribution runs through specialty sporting goods retailers in the Southeast and Southwest, with direct-to-team digital platforms emerging as margin-protective alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-audited recycled content traceability represents the scarce capability separating shelf-eligible suppliers from excluded fringe competitors, as California's SB 54 mandates and retailer ESG disclosure pressures harden certification requirements.
For Market Incumbents: Fortify supply chain resilience by securing mechanical recycling partnerships in Georgia and the Carolinas to reduce rPET cost premiums, while deepening direct-to-team digital platform investments to bypass retail slotting fee extraction. The threat of consolidated vendor relationships at Florida high school athletic conferences demands proactive multi-year agreement positioning with cooperative purchasing programs. For New Entrants and Emerging Players: Direct-to-team customization services represent the most penetrable service-layer gap, as incumbents under-serve Midwestern lacrosse and rugby programs with sport-specific modular compartment designs. Target underpenetrated youth leagues in rising-adoption states through digital platforms enabling logo embroidery and color-matching, bypassing Dick's Sporting Goods and Academy Sports gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recycled polyester infrastructure, as mechanical recycling capacity investments in the Southeast require dedicated feedstock procurement and certification workflow integration. Long-term viability favors suppliers with pre-audited chain-of-custody documentation. The signal to watch is FTC Green Guides enforcement intensity, which determines shelf placement premiums and civil penalty exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Supply Chain Certification | FTC Green Guides compliance enables verified environmental claims that command retailer shelf placement premiums. |
| Direct-to-Team Digital Platform Development | Customization capabilities bypass Dick's Sporting Goods slotting fees while capturing collegiate program loyalty. |
| Modular Compartment Architecture Investment | Interchangeable pod systems reduce equipment room inventory complexity for Texas collegiate programs. |
| Mechanical Recycling Capacity Partnership | Southeast rPET infrastructure investments compress sustainable product line cost premiums versus virgin polyester. |
| Multi-Year Equipment Agreement Positioning | Florida cooperative purchasing programs aggregate district demand, favoring bundled bag-uniform-protective gear vendors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with brand managers, category buyers at Dick's Sporting Goods and Academy Sports, collegiate equipment managers, and mechanical recycling facility operators with secondary validation. Secondary sources included customs and trade data, SEC 10-K filings from listed sportswear conglomerates, California Department of Toxic Substances Control regulatory filings, and Nielsen retail audit data. Bottom-up shipment estimates by product type and material were triangulated against top-down market sizing derived from petrochemical feedstock consumption patterns and youth sports participation rate correlations.
Across the analysis window, the forecast framework models volume and value outputs through segmentation by product type, material certification tier, end-user intensity, and distribution channel structure. CAGRs were derived from elasticity-adjusted demand projections tied to collegiate equipment budget expansion rates and mechanical recycling capacity buildout timelines. Industry-specific inputs include NCAA athletic department capital allocation surveys and Florida High School Athletic Association cooperative purchasing program aggregation data.
Underlying assumptions cover sustained youth sports participation rates in Texas and Florida, California SB 54 compliance cost absorption, and specialty retail shelf access stability, with deviation risk concentrated in petrochemical feedstock price volatility and multi-state chemical disclosure mandate fragmentation. Recalibration cycles align with material shifts in FTC Green Guides enforcement intensity and mechanical recycling infrastructure commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
School Bags Market
Luggage
Sports Luggage Market
Luggage
Bags Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Global Luggage Market
Luggage
Global Premium Luggage Market
Luggage
Travel Bag Market
Luggage
Trolley Bags Market
Luggage
Camera Bag Market
Luggage
Kids Backpack Market
Luggage
Backpack Market
Luggage
Smart Bags Market
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Laptop Carry Case Market
Luggage
Sewing Bags Market
Luggage
Second Hand Bag Market