
 Landscaping and Gardening Service Market | 2026-2036
Landscaping and Gardening Service Market Size, Share, and Industry Trends Forecast 2026-2036
Landscaping and Gardening Service Market Foresight
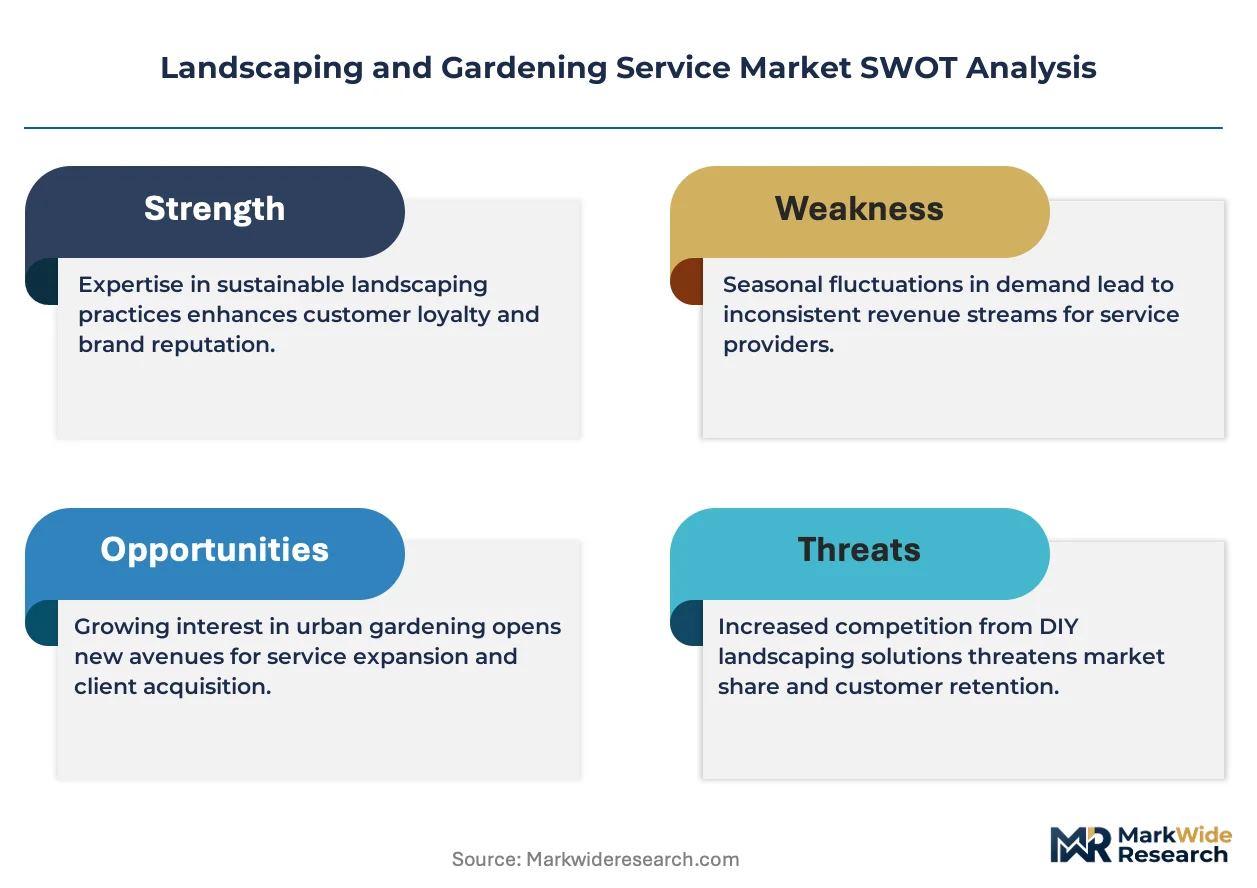
Recurring maintenance revenue is tilting toward technology-enabled subscription models that lock in multi-year client relationships. BrightView Holdings dominates commercial portfolio contracts through its national footprint and centralized routing systems. SavATree specializes in high-value arboriculture segments where technical certification creates pricing power. TruGreen leverages direct-to-consumer channels and proprietary turf science programs to sustain residential recurring revenue density.
Landscaping and gardening services encompass the planning, installation, and ongoing maintenance of vegetated outdoor environments using soil amendments, irrigation infrastructure, and integrated pest management protocols to achieve aesthetic, ecological, or property-value objectives. Lawn care and tree trimming constitute the mature volume base where equipment standardization keeps unit costs predictable. Landscape design commands premium margins as project scale expands into custom commercial and institutional builds. Municipal clients anchor steady seasonal demand cycles, while residential weekly maintenance represents the most fragmented competitive tier.
The US EPA regulates pesticide application through Worker Protection Standard mandates that shape technician training and certification requirements. OSHA governs equipment operation and heat-exposure protocols for outdoor crews. State-level water boards in California, Texas, and Florida enforce irrigation efficiency standards that accelerate smart-controller retrofit demand. Stakeholders must monitor how municipal sustainability procurement criteria and evolving chemical-restriction lists reshape service bundling and equipment investment priorities.
Market Dynamics
Smart irrigation mandates from the US EPA and state water boards are forcing capital retooling across service fleets, while recurring revenue models lock in multi-year client relationships that reshape competitive stability.
Growth Catalysts
- Water-efficiency mandates:California, Texas, and Florida state water boards enforce smart-controller retrofit requirements that accelerate equipment upgrade cycles across commercial portfolios.
- Commercial property management:Portfolio standardization drives bundled grounds maintenance contracts toward national providers with centralized routing capabilities.
- Arboriculture certification premiums:Technical credentialing in tree care segments creates pricing power that lifts margin structures above commodity lawn maintenance tiers.
Market Restraints
- Equipment capital intensity:Smart-controller installation fleets and precision application machinery require upfront investment that strains regional operator balance sheets.
- Labor supply concentration:Seasonal crew availability clusters in Sun Belt metropolitan areas, creating wage pressure spikes during peak growing months.
- Chemical restriction friction:Municipal sustainability procurement criteria and evolving EPA chemical-restriction lists force continuous formulation and training adjustments.
Strategic Opportunities
- Residential subscription penetration:Direct-to-consumer channels remain underdeveloped relative to commercial segments, offering recurring revenue density expansion.
- Integrated pest management convergence:Biological control agents and precision monitoring systems are hybridizing into bundled service offerings that command premium positioning.
- Municipal sustainability procurement:City-level green infrastructure mandates create anchored demand cycles for erosion control and native planting specifications.
Industry Challenges
- Certified arborist scarcity:Technical tree care qualifications require multi-year training pipelines that lag current demand intensity in high-value segments.
- Legacy irrigation infrastructure:Existing commercial controller bases require complex retrofit integration with cloud-based management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscaping and Gardening Service Market |
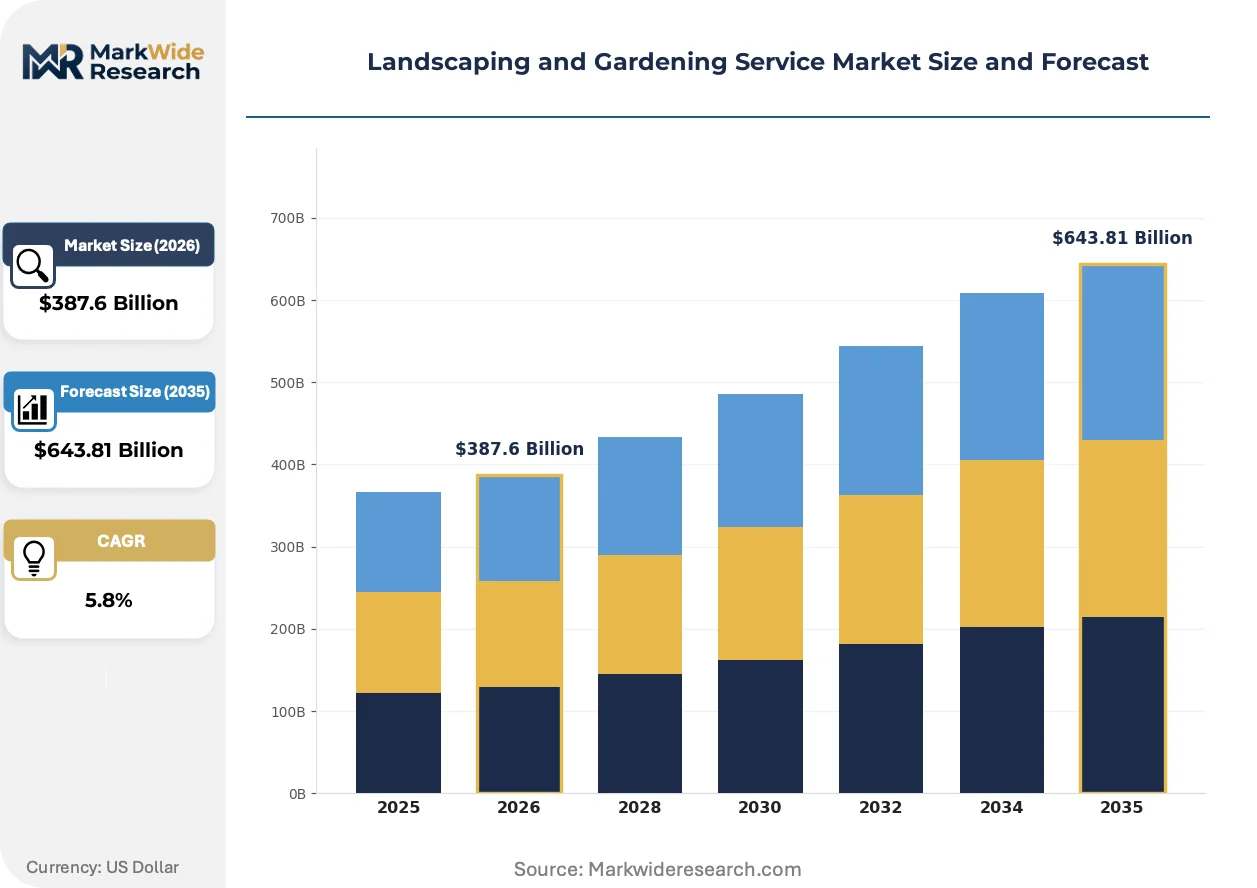
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Lawn Care, Tree Trimming, Landscape Design, Pest Control Client Type: Residential, Commercial, Municipal, Institutional Maintenance Frequency: Weekly, Bi-weekly, Monthly, Seasonal Project Scale: Small, Medium, Large, Custom |
| Companies Covered | The F.A. Bartlett Tree Expert Company, SavATree, BrightView Holdings, LandCare USA, Ruppert Landscape, TruGreen, Yellowstone Landscape, HeartLand, The Davey Tree Expert Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscaping and Gardening Service Market Shifts & Advancements
Service delivery models are compressing around technology-enabled subscription structures that merge predictive maintenance with automated scheduling systems.
Soil moisture sensing and weather-station integration is hybridizing irrigation management into autonomous water budgeting that eliminates manual zone adjustments. Large commercial property managers in Sun Belt metros are deploying these systems across portfolio scales exceeding five hundred acres. The technology is hybridizing route density economics by reducing technician visit frequency while maintaining coverage guarantees.
The US EPA Worker Protection Standard mandates reshape technician training protocols and certification renewal cycles for pesticide application crews. Equipment manufacturers must embed compliance documentation into spray system diagnostics to satisfy audit requirements. Residential and municipal segments face the steepest compliance cost absorption as crew sizes and application volumes compress margin buffers.
Buyers are consolidating vendor relationships around multi-service bundled contracts that subsume design, installation, and maintenance under single-provider accountability. National commercial portfolios are displacing fragmented local contractor networks with centralized procurement and performance benchmarking. This pattern concentrates most visibly in Texas, Florida, and Arizona metropolitan clusters where year-round growing seasons sustain continuous service engagement.
Landscaping and Gardening Service Market Segmentation
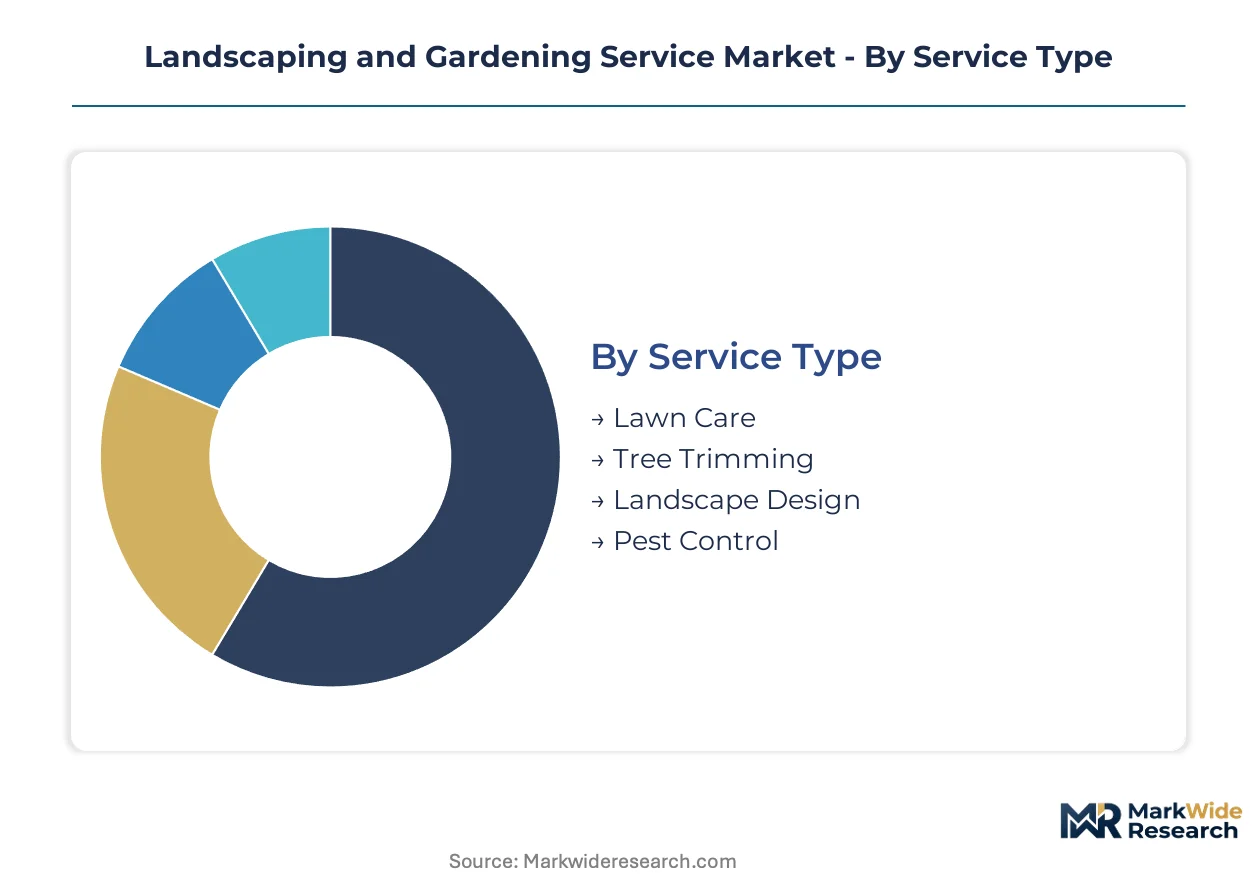
Service segmentation in landscaping and gardening reveals divergent margin structures and capital requirements across technical complexity tiers. Mature volume segments compete on route density and equipment standardization, while emerging specialty tiers extract premiums through certification barriers and design intellectual property.
Service Type:
Mature maintenance services anchor volume throughput, while emerging technical specialties command pricing power through credential scarcity and regulatory compliance depth.
- Lawn Care:Mowing, fertilization, and turf health management using standardized ride-on equipment and broadcast spreaders. Demand concentrates in Sun Belt residential subdivisions and commercial office parks where weekly cutting cycles sustain year-round crew utilization.
- Tree Trimming:Canopy management, hazard removal, and health assessment requiring certified arborist oversight and specialized aerial lift equipment. Municipal contracts in Texas and Florida metropolitan clusters drive steady demand for storm-damage response and right-of-way clearance programs.
- Landscape Design:Site planning, hardscape integration, and planting specifications for aesthetic and ecological outcomes.
- Pest Control:Integrated management protocols combining biological agents, precision application, and monitoring systems.
Lawn care retains volume leadership; integrated pest control holds the steepest expansion curve.
Client Type:
Customer segmentation traces contract scale and procurement sophistication, from fragmented household decision-making to centralized portfolio management with performance benchmarking.
- Commercial:Property management portfolios, retail centers, and corporate campuses requiring bundled grounds maintenance with centralized vendor accountability. National providers with routing optimization systems capture expanding contract values as portfolio standards tighten across Sun Belt metropolitan clusters.
- Residential:Single-family homeowners and multi-family associations purchasing recurring maintenance or one-time installation projects. Subscription model penetration remains underdeveloped relative to commercial segments, offering recurring revenue density expansion through direct-to-consumer channels.
- Municipal:City and county contracts for parks, medians, and public facilities with sustainability procurement criteria.
- Institutional:Universities, hospitals, and government complexes with specialized aesthetic and accessibility requirements.
Commercial contracts dominate revenue concentration; residential subscription penetration offers the most expansion headroom.
Maintenance Frequency:
Scheduling segmentation determines crew allocation efficiency and equipment utilization rates across seasonal demand curves.
- Weekly:High-frequency turf maintenance for premium commercial properties and affluent residential zones requiring pristine presentation standards. Year-round growing seasons in Florida, Arizona, and Texas sustain continuous engagement without winter dormancy gaps.
- Bi-weekly:Standard residential maintenance balancing cost sensitivity with appearance standards.
- Monthly:Lower-intensity ornamental care and seasonal bed maintenance for budget-conscious properties.
- Seasonal:Spring cleanup, fall leaf removal, and winterization services with concentrated labor demand spikes.
Weekly service locks in the highest lifetime value per account; seasonal work creates the most severe capacity bottlenecks.
Project Scale:
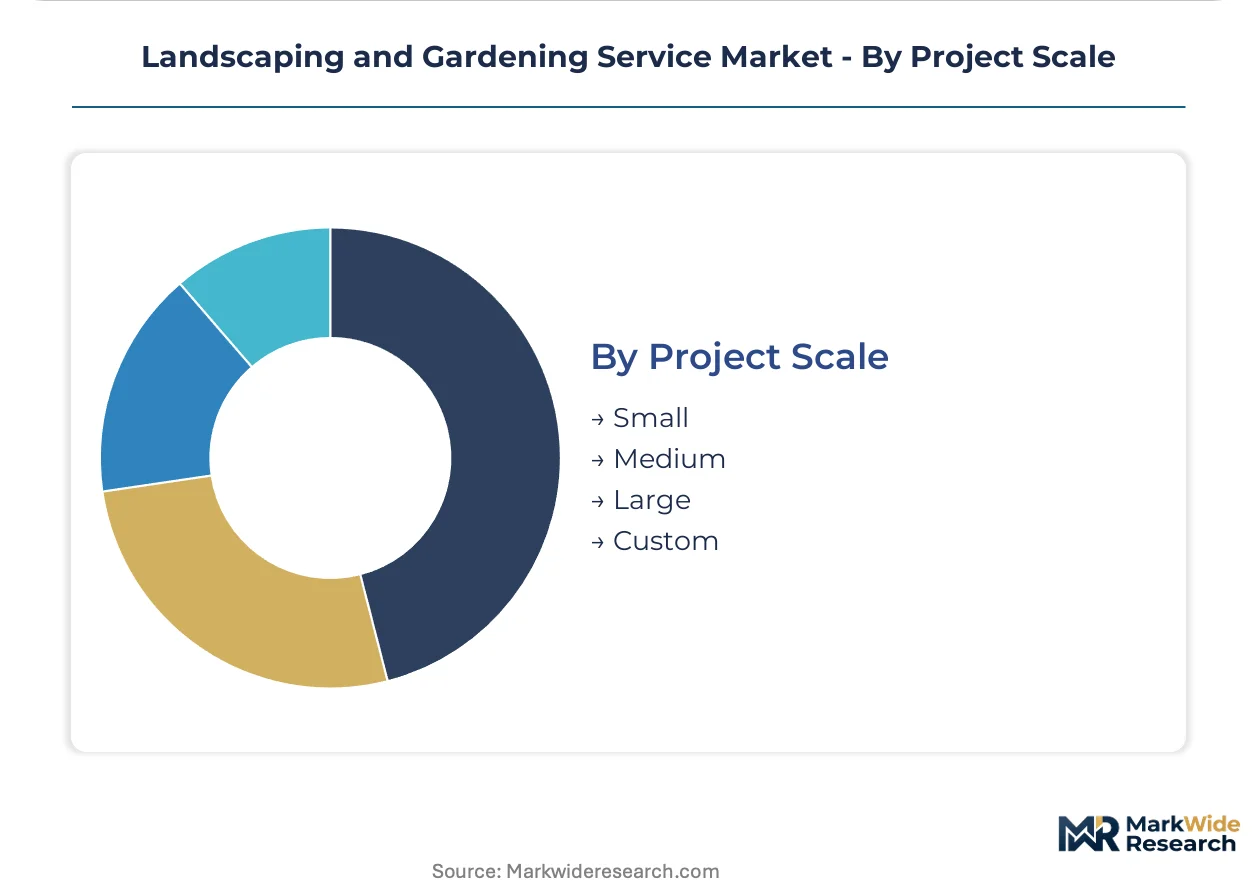
Scale segmentation separates commodity maintenance from capital-intensive design-build operations with distinct margin profiles and risk structures.
- Custom:Bespoke commercial and institutional builds integrating hardscape, irrigation infrastructure, and mature specimen planting with architect-specified outcomes. Project complexity demands bonded performance guarantees and multi-phase completion schedules that filter out undercapitalized regional operators.
- Large:Campus-scale installations and portfolio-wide renovation programs exceeding fifty-acre footprints.
- Medium:Subdivision entry features, retail pad sites, and multi-family amenity zones.
- Small:Residential foundation planting and backyard renovation projects with minimal design fees.
Custom projects carry the highest margin potential; small residential work provides the most predictable cash conversion cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies: Sun Belt metropolitan buyers absorb premium weekly service rates without volume compression, while Northeast residential segments trade frequency for cost containment.
United States
Commercial property management portfolios in Texas, Florida, and Arizona metropolitan clusters sustain year-round weekly maintenance contracts without seasonal dormancy gaps. The US EPA Worker Protection Standard mandates reshape technician certification requirements for pesticide application crews. Dallas-Fort Worth and Phoenix anchor the densest concentrations of smart-irrigation retrofit activity as municipal water ordinances tighten.
Germany
Precision landscaping for commercial campuses and industrial parks drives demand for integrated design-build services with bonded performance guarantees. The EU Green Deal and national sustainability procurement criteria reshape municipal contract specifications toward native planting and erosion control. The Rhine-Ruhr metropolitan region concentrates the highest service contract values as portfolio standardization displaces fragmented local operators.
United Kingdom
Institutional clients including university estates and hospital grounds anchor steady demand for high-frequency maintenance with aesthetic compliance requirements. The Environment Agency's water abstraction regulations accelerate smart-controller adoption across commercial irrigation infrastructure. London and the Southeast corridor dominate revenue concentration as property management firms consolidate vendor relationships under single-provider accountability.
Canada
Seasonal demand compression in Ontario and Quebec creates severe capacity bottlenecks during spring startup and fall winterization windows. Health Canada's PMRA governs pesticide registration and application protocols that shape technician training investments. The Greater Toronto Area anchors the largest commercial portfolio contracts, though shorter growing seasons limit recurring revenue density relative to southern US benchmarks.
Australia
Water scarcity in New South Wales and Victoria drives premium pricing for drought-tolerant landscape design and soil moisture sensing integration. The country's national environmental regulator enforces irrigation efficiency standards that accelerate equipment upgrade cycles across municipal and commercial segments. Sydney and Melbourne metropolitan clusters concentrate demand for native planting specifications aligned with urban green infrastructure mandates.
Landscaping and Gardening Service Market Competitive Landscape
Capability concentration sits with certified arboriculture specialists; scale advantage sits with national maintenance platforms with centralized routing systems. The market structures around three tiers: technology-enabled subscription providers, portfolio-scale commercial contractors, and regional design-build specialists. Dominant competitive moves include multi-service contract bundling and geographic densification through acquisition.
Among national-scale commercial contractors, BrightView Holdings and TruGreen occupy positions exemplifying divergent strategic archetypes. BrightView Holdings represents the portfolio-scale platform with centralized procurement capabilities, while TruGreen anchors the direct-to-consumer subscription model with proprietary turf science programs. SavATree sits within the certified-specialist tier where technical credentialing creates pricing power above commodity maintenance rates.
| Leading Market Players |
|---|
| The F.A. Bartlett Tree Expert Company |
| SavATree |
| BrightView Holdings |
| LandCare USA |
| Ruppert Landscape |
| TruGreen |
| Yellowstone Landscape |
| HeartLand |
| The Davey Tree Expert Company |
| Others |
Supply & Pricing Matrix
Equipment manufacturing concentration in China and Mexico for commercial-grade mowers and precision application machinery feeds directly into margin distribution across North American service tiers. Where capital equipment sources cluster dictates which operator archetypes capture value from technology-enabled subscription transitions.
Pricing Analysis
Multi-year maintenance contracts and equipment-as-a-service attachments generate lifetime value exceeding initial installation revenue by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates certified arborist crews from commodity lawn maintenance from seasonal residential crews. Pricing pressure stems from smart-controller retrofit mandates in California, Texas, and Florida that force capital absorption without immediate rate recovery. Residential weekly maintenance shows highest price sensitivity; commercial portfolio contracts demonstrate lowest elasticity due to bundled accountability requirements.
Supply Chain Analysis
Extended payment terms from commercial property managers strain regional operator cash conversion cycles, forcing supply-chain finance facility adoption. Equipment manufacturing concentrates in China, Mexico, and the United States; fertilizer and amendment sourcing draws from Canada and domestic production. Single-source vulnerability runs through smart-controller chipsets and precision spray nozzles. Distribution runs through national rental fleets, regional dealer networks, and direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Landscaping and gardening services function as a service-attach market where recurring maintenance revenue expands faster than one-time installation hardware. Technology-enabled subscription layers and multi-year contract structures justify valuation premiums over transactional project economics.
For Market Incumbents: Entrench portfolio positions by deepening backward integration into equipment leasing and captive maintenance supply chains. Acquire certified arborist capacity in Texas and Florida metropolitan clusters where technical credential scarcity creates pricing power. Defend against national platform consolidation by embedding proprietary soil science and irrigation optimization IP into client contracts.
For New Entrants and Emerging Players: Mid-market commercial buildings in Arizona and Nevada metropolitan clusters represent the most penetrable entry point for subscription-based maintenance without incumbent national contract lock-in. Residential direct-to-consumer channels in Sun Belt subdivisions remain underdeveloped relative to commercial saturation. Lead with smart-controller retrofit bundling to differentiate from commodity mowing competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward regional design-build specialists with bonded performance guarantee capabilities and municipal sustainability procurement relationships. Long-term viability across the analysis window favors operators with technology-enabled route density and multi-service bundling infrastructure. Watch for EPA chemical-restriction list expansion as an inflection signal for biological control agent adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Irrigation Retrofit Program | California, Texas, and Florida water board mandates accelerate equipment upgrade cycles across commercial portfolios. |
| Certified Arborist Capacity Expansion | Technical credentialing in tree care segments creates pricing power above commodity lawn maintenance tiers. |
| Multi-Service Contract Bundling | National commercial portfolios displace fragmented local contractors with centralized procurement and performance benchmarking. |
| Direct-to-Consumer Subscription Launch | Residential channels remain underdeveloped relative to commercial segments, offering recurring revenue density expansion. |
| Biological Control Agent Integration | EPA chemical-restriction list evolution forces continuous formulation adjustments favoring integrated pest management convergence. |
Research Methodology
A spread of perspectives from commercial property managers, municipal procurement officers, certified arborists, and equipment manufacturer product managers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through EPA Worker Protection Standard documentation, state water board ordinance filings, OSHA equipment safety protocols, and commercial portfolio contract disclosure patterns. Bottom-up crew allocation models and top-down market sizing triangulated on segment-level revenue estimates.
Demand-supply balance dynamics across the projection horizon anchored forecast construction, with segmentation modeled across service type, client archetype, maintenance frequency, and project scale dimensions. CAGRs derived from historical contract value growth rates adjusted for smart-controller mandate acceleration and subscription model penetration curves. Industry-specific inputs included irrigation equipment replacement cycles, certified arborist training pipeline durations, and seasonal labor availability patterns.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate occupancy rates, Sun Belt construction permitting velocity, or municipal budget allocation priorities would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Preserved Flowers Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Wine Racks Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Candle Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Lawn and Gardening Consumables Market