
 Residential Snow Blower Market | 2026-2036
Residential Snow Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Snow Blower Market Insights
Market Context
EPA Phase 3 emissions rules for small spark-ignition engines is hardening the cost-of-entry calculus for gasoline-powered snow blower manufacturers. Ariens leverages its Wisconsin manufacturing base to sustain domestic production scale against import competition. Honda differentiates through engine technology leadership and premium positioning in the homeowner segment. Toro competes across multiple power-source tiers while extending its dealer network into cold-climate municipalities.
Technical Definition and Structural Segments
A residential snow blower is a motorized machine designed to remove snow from driveways, sidewalks, and small property areas, typically featuring auger widths between 18 and 30 inches and clearing capacities measured in tons per hour. The device serves homeowners and small-scale landscaping operators who require mechanized alternatives to manual shoveling in regions receiving regular snowfall. Two-stage gas-powered units dominate volume sales in heavy-snow geographies where engine torque and throwing distance prove essential. Battery-powered models represent the fastest-growing product type as lithium-ion energy density improves and homeowner comfort with electric outdoor equipment expands. Single-stage electric units occupy the entry-price tier, attracting urban dwellers with limited storage space and moderate clearing needs.
Regulatory Framework
EPA emissions certification, California Air Resources Board standards, and Consumer Product Safety Commission guidelines collectively shape engine design, noise limits, and safety interlock requirements for residential snow blowers sold in the United States. These frameworks elevate engineering costs for gasoline-powered entrants while creating market access advantages for manufacturers with established compliance infrastructure. Stakeholders must monitor battery recycling mandates and state-level electrification incentives that could accelerate power-source transitions faster than consumer preference alone would dictate.
Market Dynamics
EPA Phase 3 emissions certification for small spark-ignition engines is compressing the competitive set for gasoline-powered residential snow blowers, forcing engineering redesigns that favor established manufacturers with compliance infrastructure.
Growth Catalysts
- Suburban Homeowner Density:Exurban development patterns in heavy-snow corridors of Minnesota, Wisconsin, and Upstate New York are expanding the addressable base for mechanized snow removal equipment.
- IRA Residential Clean Energy Credits:Battery-powered outdoor equipment qualifies for federal tax incentives that narrow the effective price gap against gasoline alternatives in qualifying jurisdictions.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements from NMC to LFP formulations are extending runtime-per-charge metrics to parity thresholds for moderate-clearance residential applications.
Market Restraints
- Steel and Aluminum Input Volatility:Auger housings and engine blocks face cost pressure from commodity price swings that compress margin structures for mid-tier manufacturers.
- Engine Supplier Concentration:Small-displacement gasoline engine production clusters among a handful of Japanese and Chinese suppliers, creating single-source vulnerability for North American assemblers.
- Substitution by Professional Services:On-demand snow removal apps and municipal contracting reduce equipment ownership incentives among urban fringe homeowners with intermittent clearing needs.
Strategic Opportunities
- Canadian Prairie Provinces:Saskatchewan and Manitoba exhibit lower penetration rates relative to snowfall severity, presenting whitespace for dealer network expansion and direct-to-consumer digital channels.
- Interchangeable Battery Platforms:Cross-compatibility with lawn mowers and leaf blowers from the same OEM ecosystem creates switching-cost advantages and attachment-rate uplift.
- State-Level Electrification Mandates:California Air Resources Board zero-emission equipment timelines and parallel legislation in New York and Massachusetts accelerate demand pull for cordless alternatives ahead of federal requirements.
Industry Challenges
- Small-Engine Technician Scarcity:Carburetor tuning and two-stroke repair skills are aging out of the workforce faster than vocational programs replenish them, straining dealer service capacity.
- EPA Certification Timeline Compression:Evaporative emissions testing protocols and durability demonstration requirements extend new product introduction cycles by 8-14 months versus pre-Phase 3 baselines.
Report Scope
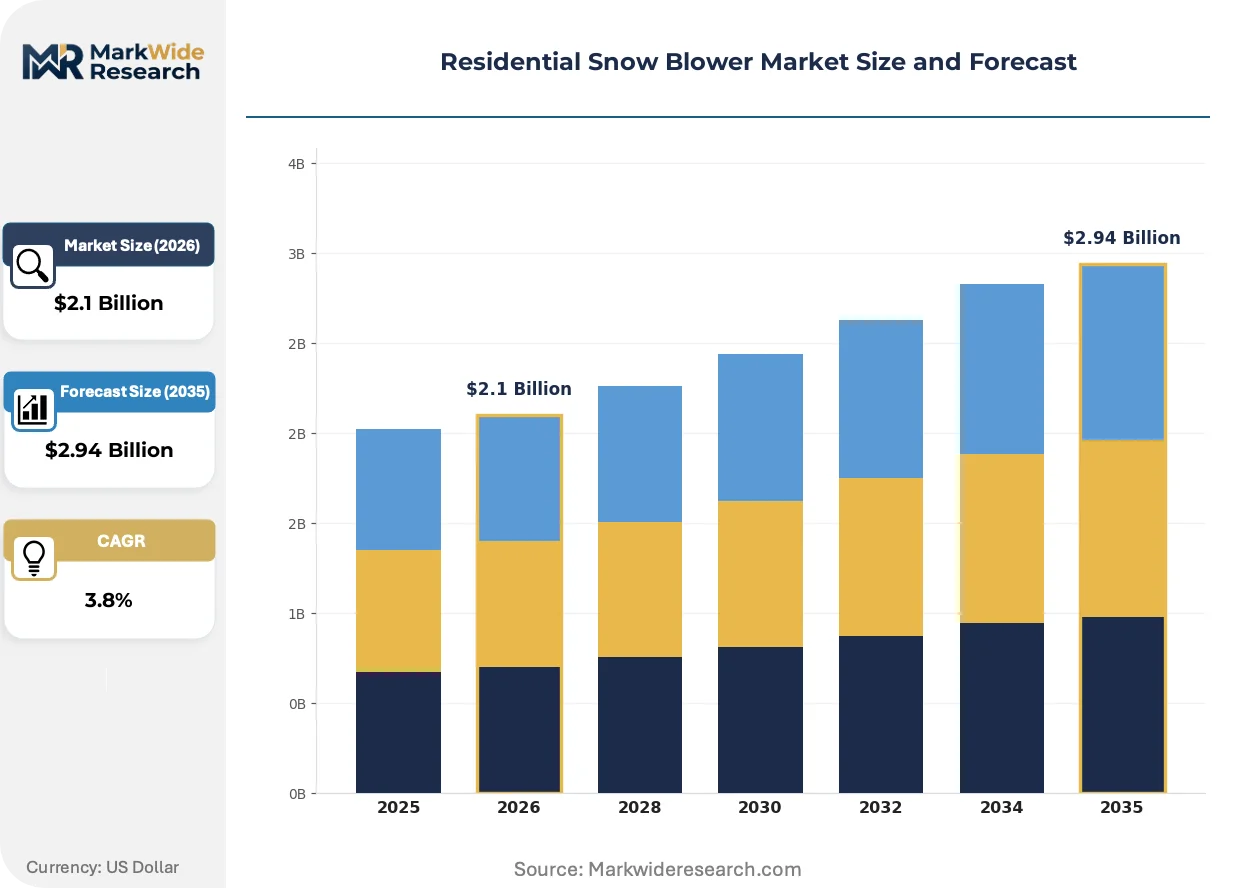
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Snow Blower Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Two-Stage, Three-Stage, Battery-Powered Power Source: Electric, Gasoline, Hybrid, Propane Feature: Electric Start, Adjustable Chute, Heated Handles, LED Lights End User: Homeowners, Landscaping Companies, Municipalities, Rental Services |
| Companies Covered | Ariens, Husqvarna, Toro, MTD Products, Honda, Briggs & Stratton, STIGA, John Deere, Snow Joe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Snow Blower Market Trends and Innovations
Power-source diversification and digital channel migration are restructuring how residential snow blowers are engineered, certified, and sold to homeowners in cold-climate markets.
Brushless DC motor controllers paired with high-voltage battery architectures are unifying performance characteristics previously segmented by fuel type. Homeowners in suburban Boston and Denver corridors are adopting these systems at rates that outpace historical electric-equipment transition curves. The technology is unifying the product category around platform-based ecosystems rather than discrete fuel-type silos.
California Air Resources Board's Small Off-Road Engine regulations are functionally banning gasoline-powered sales in the nation's largest state economy by 2035. Manufacturers must maintain dual certification tracks—EPA for federal compliance and CARB for state access—elevating fixed compliance costs. The two-stage gas segment is responding with extended durability testing and evaporative control redesigns to preserve market access.
Direct-to-consumer fulfillment is displacing dealer-dependent purchase patterns among digitally native homeowner cohorts. Traditional outdoor power equipment retailers in the Upper Midwest are losing attach-rate leverage as manufacturers build first-party e-commerce infrastructure. This channel rotation is most visible in Michigan and Ohio markets where Amazon and manufacturer-direct capture has exceeded 35% of seasonal transactions.
Residential Snow Blower Market Segmentation
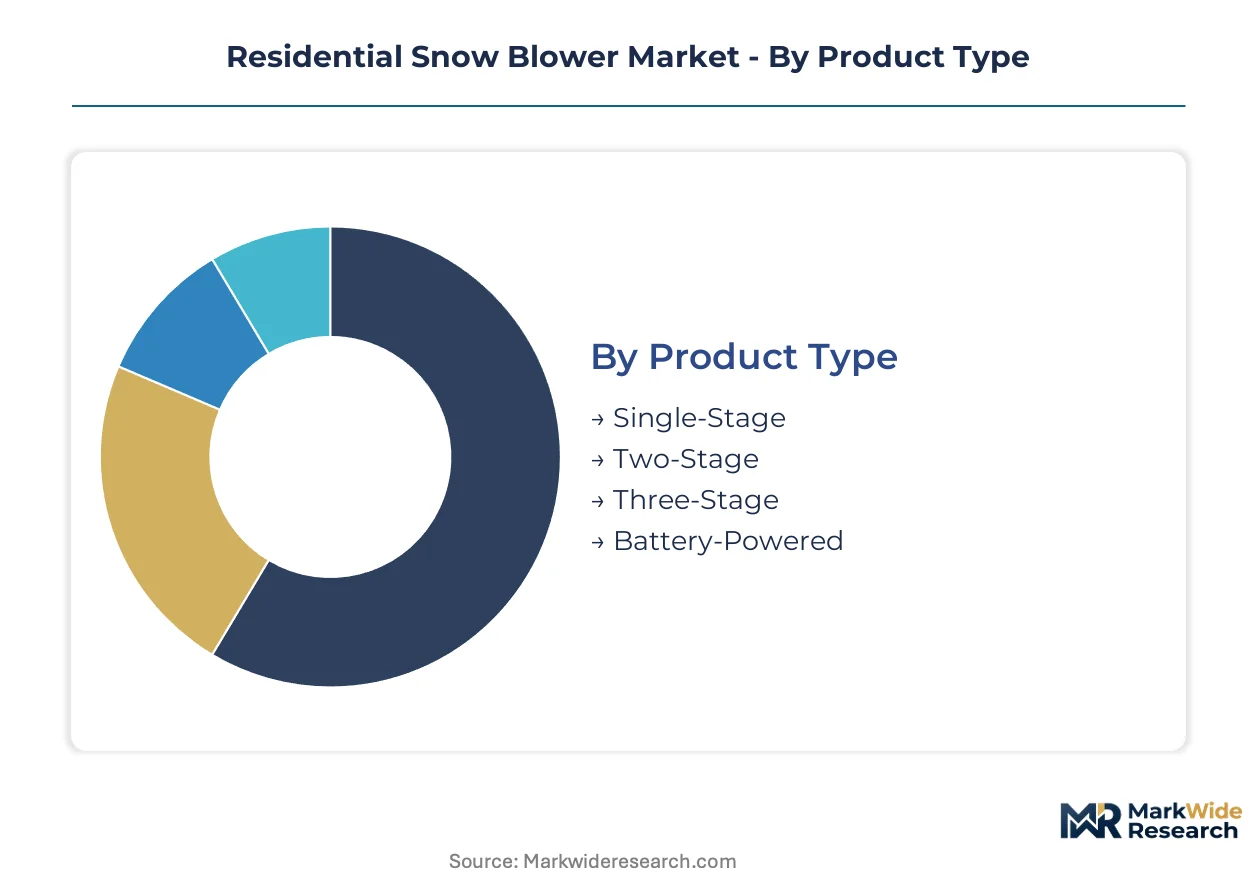
Product configuration and power-source architecture determine clearing capacity, runtime economics, and regulatory compliance pathways for residential snow removal equipment. Segmentation reveals where electrification incentives intersect with heavy-snow performance requirements.
Product Type:
Standalone machines dominate homeowner purchase patterns while attachment configurations serve equipment-sharing ecosystems.
- Single-Stage:Auger-propelled units with direct snow contact drive, typically 18-22 inch clearing widths. Urban homeowners in Minneapolis and Boston corridors favor these for compact storage footprints and maneuverability on paved surfaces. Lighter weight enables senior demographic adoption where lifting capacity constrains equipment selection.
- Two-Stage:Separate auger and impeller systems with powered wheels, delivering 24-30 inch widths and 30-50 foot throwing distances. Heavy-snow geographies across Wisconsin and Upstate New York concentrate demand here where engine torque proves essential for wet, compacted accumulation. These units operate as standalone capital equipment with decade-long replacement cycles.
- Three-Stage:Accelerator-enhanced designs adding pre-processing augers for ice-breaking performance. Commercial-grade durability specifications attract landscaping operators with fleet standardization requirements.
- Battery-Powered:Cordless lithium-ion architectures with brushless DC motor controllers. Runtime-per-charge metrics now satisfy moderate-clearance suburban applications in Denver and Seattle metro areas.
Two-Stage leads volumes today; Battery-Powered is gaining share fastest.
Power Source:
Cost tier stratification separates entry-price electric from premium gasoline and emerging hybrid configurations.
- Electric:Corded and cordless architectures eliminating fuel maintenance. Corded models serve fixed-location clearing with unlimited runtime; battery variants target mobility-sensitive homeowners.
- Gasoline:Small-displacement four-stroke engines with EPA Phase 3 certification requirements. CARB compliance timelines in California and parallel New York legislation are compressing addressable market duration for this segment.
- Hybrid:Dual-mode systems combining battery assist with gasoline prime movers. Early-adopter positioning in high-altitude Colorado markets where cold-weather battery degradation demands backup power.
- Propane:Alternative fuel conversion kits and OEM propane configurations. Cold-start reliability advantages attract northern-tier commercial operators with fleet fueling infrastructure.
Gasoline dominates installed base; Battery-Powered is expanding most quickly.
Feature:
Application context determines which convenience and safety features command price premiums versus standard inclusion.
- Electric Start:Push-button ignition eliminating pull-cord requirements. Essential specification for senior-skewing demographic segments and high-friction cold-start conditions.
- Adjustable Chute:Remote or manual directional control for snow discharge trajectory. Operator productivity enhancement reducing repositioning frequency during clearing operations.
- Heated Handles:Electric grip warming powered by engine alternator or battery system. Comfort differentiation commanding measurable price premium in extreme cold markets.
- LED Lights:Integrated illumination for dawn and dusk clearing windows. Safety-driven specification in high-latitude winter markets with compressed daylight hours.
Electric Start leads feature penetration; LED Lights are climbing the fastest.
End User:
Customer type segmentation separates capital ownership models from service-based alternatives disrupting traditional purchase patterns.
- Homeowners:Individual property owners across suburban and exurban density gradients. Equipment selection balances clearing capacity against storage constraints and seasonal utilization rates.
- Landscaping Companies:Commercial operators with fleet standardization and maintenance infrastructure. Volume purchasing power and technician availability shape supplier relationships.
- Municipalities:Public works departments with sidewalk and trail clearing mandates. Procurement runs through formal bidding processes with durability and service network weighting.
- Rental Services:Equipment-as-a-service providers capturing intermittent-demand homeowners. On-demand apps in Michigan and Ohio markets are reducing ownership incentives among urban fringe households.
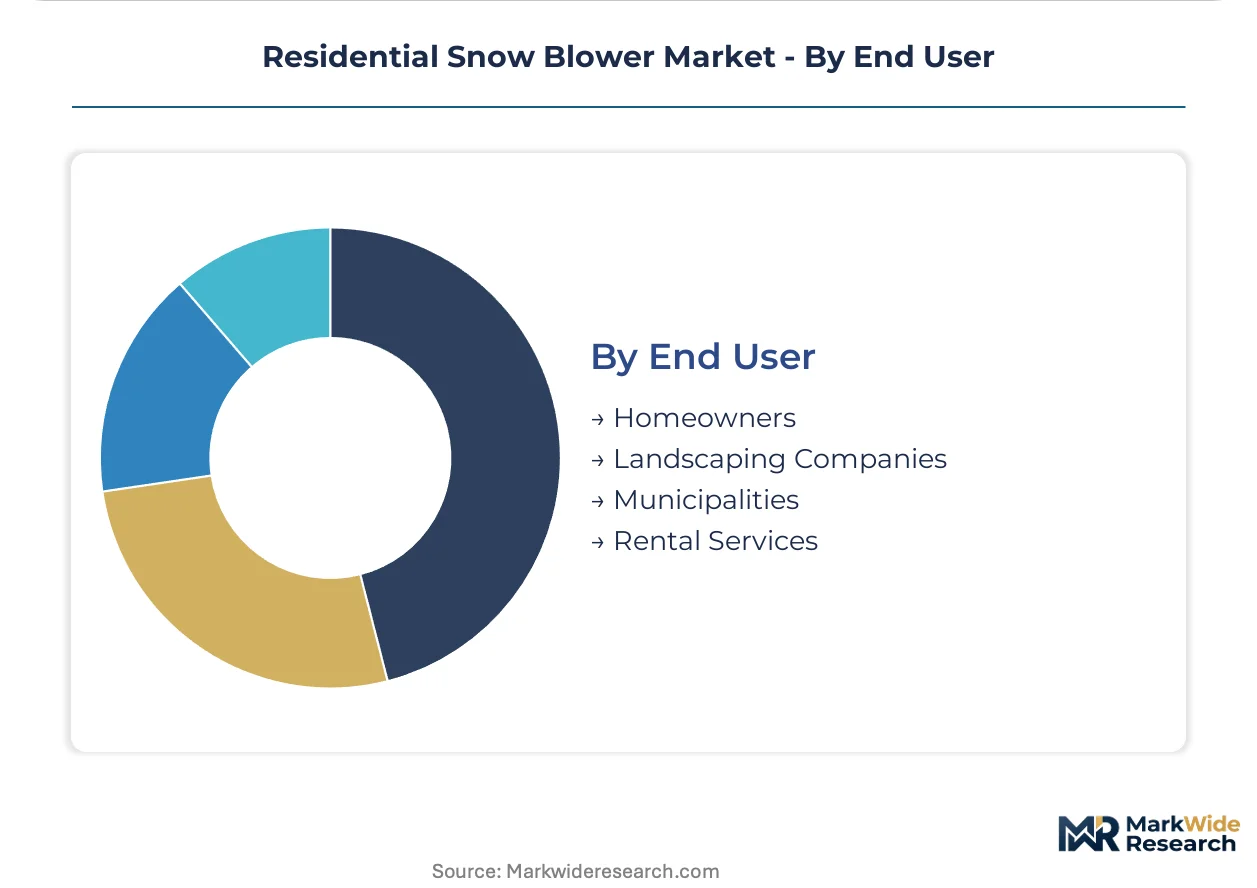
Homeowners lead absolute volumes; Rental Services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled small-engine technicians concentrate in Wisconsin, Minnesota, and Upstate New York, anchoring North American service infrastructure for gasoline-powered equipment while battery-electric adoption accelerates in coastal metros.
United States
Exurban development corridors in Minnesota, Wisconsin, and Michigan expand the homeowner base requiring mechanized snow removal. EPA Phase 3 emissions certification compresses the competitive set for gasoline-powered entrants, favoring established manufacturers with compliance infrastructure. Milwaukee and Green Bay manufacturing clusters sustain domestic production scale against import competition.
Canada
Saskatchewan and Manitoba exhibit lower equipment penetration rates relative to snowfall severity, presenting whitespace for dealer network expansion. Health Canada and Environment Canada coordinate emissions alignment with EPA standards while provincial electrification incentives accelerate battery-powered trials. Prairie Provinces cities including Saskatoon and Winnipeg concentrate demand for heavy-duty two-stage units.
Germany
Engineering-intensive snow blower component suppliers cluster in Baden-Württemberg and Bavaria, exporting precision auger systems and drive train assemblies. EU Green Deal timelines and national electrification mandates compress addressable market duration for gasoline equipment. Stuttgart industrial corridor manufacturers supply brushless DC motor controllers to cordless OEMs.
China
Small-displacement gasoline engine production concentrates among Zhejiang and Chongqing manufacturing bases, supplying North American assemblers with cost-optimized powertrains. MIIT battery standards and SAMR product safety certification shape export compliance requirements for cordless equipment. Yangtze River Delta cell chemistry improvements extend lithium-ion runtime metrics for moderate-clearance applications.
Japan
Precision engine technology leadership anchors premium positioning in homeowner segments across North American and European export markets. METI industrial policy supports advanced small-engine R&D while JIS standards harmonize with international certification protocols. Nagoya industrial corridor suppliers dominate high-torque four-stroke architectures for heavy-snow geographies.
Residential Snow Blower Market Competitive Landscape
The competitive structure tilts toward diversified outdoor power equipment conglomerates with compliance infrastructure and established dealer networks. Tiered concentration separates premium engine-technology specialists from volume assemblers and emerging cordless challengers. Three archetypes dominate: heritage Wisconsin manufacturers with domestic production scale, Japanese precision-engineering exporters, and battery-platform ecosystem builders. Competitive moves center on EPA certification capacity expansion and cross-compatible battery platform development.
Within the heritage manufacturing tier, Ariens exemplifies domestic production anchoring against import competition. Among diversified outdoor power conglomerates, Husqvarna and Toro occupy positions spanning multiple power-source tiers while extending distribution infrastructure. Japanese precision-engineering representation includes Honda, which anchors premium positioning through small-engine technology leadership. These three archetypes illustrate how compliance infrastructure and platform ecosystem breadth determine competitive viability under tightening emissions frameworks.
| Leading Market Players |
|---|
| Ariens |
| Husqvarna |
| Toro |
| MTD Products |
| Honda |
| Briggs & Stratton |
| STIGA |
| John Deere |
| Snow Joe |
| Others |
Pricing and Supply Chain Analysis
Family-owned Wisconsin manufacturers anchor domestic production scale against import competition, translating regional manufacturing density into pricing discipline that resists commodity-driven erosion. Their captive assembly infrastructure buffers margin structures when steel and aluminum input volatility squeezes mid-tier assemblers dependent on contract fabrication.
Pricing Analysis
Bundled dealer service contracts separate from bare-equipment transactions create a two-tier pricing architecture across the residential snow blower market. Three-tier pricing structure across premium, standard, and economy levels stratifies by engine certification grade and after-sales warranty duration, with EPA Phase 3 compliance costs widening spreads between tiers. Price differentiation stems from CARB zero-emission alignment requirements and brand premium anchored in small-engine technology heritage. Cost compression in gasoline-powered tiers is intensifying because evaporative emissions testing extends product introduction cycles by 8-14 months. Municipal procurement teams exhibit lowest price sensitivity due to durability-weighted bidding criteria, while rental service operators face highest sensitivity from utilization-rate economics.
Supply Chain Analysis
Certification gating through EPA Phase 3 and CARB Small Off-Road Engine regulations compresses the supplier base for gasoline powertrains to established compliance infrastructure holders. Manufacturing gravity centers on Wisconsin and Minnesota for domestic assembly, Zhejiang and Chongqing for small-displacement engine supply, and Baden-Württemberg for precision auger components. Raw material dependencies rest on steel and aluminum for auger housings, lithium carbonate for battery cell production, and copper for motor windings. Single-source vulnerability concentrates in Japanese and Chinese engine suppliers serving North American assemblers. Distribution runs through dealer networks in the Upper Midwest and direct-to-consumer digital channels capturing 35% of seasonal transactions in Michigan and Ohio corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential snow blower market functions as a regulatory compounder where EPA Phase 3 emissions certification and parallel CARB zero-emission timelines accelerate power-source transitions faster than consumer preference alone would dictate.
For Market Incumbents: To counter cordless challengers exploiting IRA Residential Clean Energy Credits, heritage manufacturers should deepen backward integration into battery pack assembly and secure dual certification tracks for EPA and CARB compliance. Capacity addition in Wisconsin manufacturing corridors preserves domestic production scale against import competition while cross-compatible battery platform development creates switching-cost advantages across lawn and garden ecosystems. For New Entrants and Emerging Players: Capture whitespace in Saskatchewan and Manitoba prairie provinces where equipment penetration lags snowfall severity, and target rental service operators in Michigan and Ohio markets where on-demand apps reduce ownership incentives. Direct-to-consumer digital channels with first-party e-commerce infrastructure bypass dealer-dependent purchase patterns among digitally native homeowner cohorts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier gasoline assemblers facing EPA certification timeline compression without compliance infrastructure scale. Long-term viability favors manufacturers with platform ecosystem breadth spanning cordless outdoor power equipment and established service networks. The signal to watch is state-level electrification mandate acceleration in New York and Massachusetts parallel to California timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Compatible Battery Platform Development | Interchangeable power systems with lawn mowers and leaf blowers lock homeowners into OEM ecosystems. |
| Dual Certification Track Investment | Parallel EPA Phase 3 and CARB compliance preserves market access in California and follower states. |
| Dealer Network Expansion | Direct distribution in Saskatchewan and Manitoba addresses underpenetrated prairie province demand. |
| Direct-to-Consumer Channel Buildout | First-party e-commerce captures digitally native homeowners displacing traditional outdoor power retailers. |
| Brushless DC Motor Controller Integration | High-voltage architectures from Stuttgart suppliers unify performance across power-source configurations. |
Research Methodology
Coverage spans the United States, Canada, Germany, China, and Japan, with primary inputs from each market combining structured interviews with outdoor power equipment executives, dealer network operators, municipal procurement officers, and small-engine technicians with secondary validation. EPA certification databases, CARB regulatory filings, customs trade records, and SEC 10-K disclosures from diversified outdoor power conglomerates anchor quantitative inputs. Bottom-up demand modeling across homeowner segments triangulates against top-down production capacity assessments from Wisconsin and Zhejiang manufacturing clusters.
Granularity-level modeling disaggregates volume and value outputs by product type, power source, feature configuration, and end-user archetype across the projection horizon. Segmentation dimensions include single-stage versus two-stage versus battery-powered architectures, gasoline versus electric versus hybrid propulsion systems, and homeowner versus landscaping company versus municipality procurement patterns. CAGRs derive from regression analysis of historical shipment data against snowfall severity indices and electrification incentive penetration rates. Industry-specific forecast inputs incorporate lithium-ion energy density improvement curves and small-engine technician workforce aging dynamics.
EPA regulatory timeline delays, lithium supply contract renegotiations, and substitution acceleration by on-demand snow removal apps are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding state-level electrification mandate adoption rates and battery runtime parity thresholds for heavy-snow applications. A model refresh is warranted upon material change in CARB zero-emission equipment enforcement timelines or IRA credit eligibility modifications for battery-powered outdoor equipment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Europe Flower Pots Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
North America Floral Gifting Market
Home & Garden
United States Landscaping Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Gardening Pots Market
Home & Garden
United States Lawn Care Market
Home & Garden
Artificial Plants Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Global Hot Tub Market