
 Incense Market | 2026-2036
Incense Market Size, Share, and Industry Trends Forecast 2026-2036
Incense Market Insights
Natural fragrance extraction and clean-burning formulation science is rewriting how incense products achieve premium positioning. Mysore Deep Perfumery House leverages its Karnataka manufacturing base to dominate domestic Indian distribution. Nippon Kodo Co., Ltd. anchors its competitiveness on centuries-old Kyoto blending techniques that command shelf space in specialty retail. Shoyeido Co., Ltd. differentiates through direct control over raw material sourcing from Southeast Asian resin suppliers.
Incense comprises combustible aromatic biocomposites—typically 21–23 cm stick formats containing bamboo core, charcoal powder, binding gum, and essential oil loads of 8–15% by weight—designed for controlled release of fragrance through slow combustion in ritual, therapeutic, or ambient settings. The stick segment leads volume globally due to standardized production economics and established religious consumption patterns across South Asia. Aromatherapy usage type captures the fastest expansion as wellness consumers in Germany and the United States substitute incense for synthetic air fresheners. Raw material stratification shows resins and therapeutic-grade oils concentrating margin pools, while bamboo and commodity herb inputs compete primarily on scale.
India's BIS certification requirements for agarbathi safety and emissions, the EU REACH regulation on aromatic chemical disclosure, and the U.S. EPA guidelines on indoor air quality collectively shape product formulation standards and market access conditions for exporters. Stakeholders must monitor evolving fragrance allergen labeling rules in multiple jurisdictions to anticipate reformulation costs and certification timelines.
Market Dynamics
Clean-burning formulation mandates from India's BIS and the EU's REACH framework are forcing manufacturers to reformulate binding gums and charcoal bases, compressing margins for commodity producers while rewarding certified clean-label specialists.
Growth Catalysts
- EU REACH aromatic chemical disclosure:Wellness retailers in Germany and France now stock compliant incense as a synthetic air-freshener substitute, pulling premium volumes through pharmacy and spa channels.
- Aromatherapy end-use expansion:Yoga studios and meditation apps in the United States bundle incense with subscription wellness kits, creating recurring demand outside traditional religious consumption.
- Karnataka-Tamil Nadu manufacturing concentration:Clustered agarbathi production achieves 40% lower logistics costs than dispersed facilities, reinforcing India's export competitiveness to Middle Eastern and Southeast Asian markets.
Market Restraints
- Resin supply concentration:Somalian frankincense and Omani myrrh harvests face climate volatility and export licensing delays, squeezing margin pools for therapeutic-grade oil formulations.
- BIS certification friction:Indian domestic manufacturers report 8-14 month approval timelines for new product variants, freezing SKU expansion for mid-tier players.
- Electric diffuser substitution:Plug-in ultrasonic oil diffusers capture ambient fragrance occasions in urban Japanese and South Korean households, displacing stick incense in non-ritual settings.
Strategic Opportunities
- Direct-to-consumer channel innovation:Subscription box services in Canada and Australia bypass fragmented retail distribution, capturing full margin on artisanal and small-batch incense lines.
- EU Green Deal bio-based materials mandate:Incense producers using FSC-certified bamboo and plant-derived binders qualify for preferential procurement by European hospitality chains.
- Functional fragrance convergence:Blending traditional resin bases with nootropic or adaptogenic essential oils targets productivity-focused consumers in Singapore and the United Arab Emirates.
Industry Challenges
- Master blender skill scarcity:Kyoto-style incense compounding requires 10-15 year apprenticeships; Japanese and Taiwanese manufacturers compete for a shrinking pool of trained artisans.
- Clean-label reformulation capex:Replacing synthetic fixatives with natural alternatives demands new drying and curing equipment, straining balance sheets for family-owned Indian agarbathi operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incense Market |
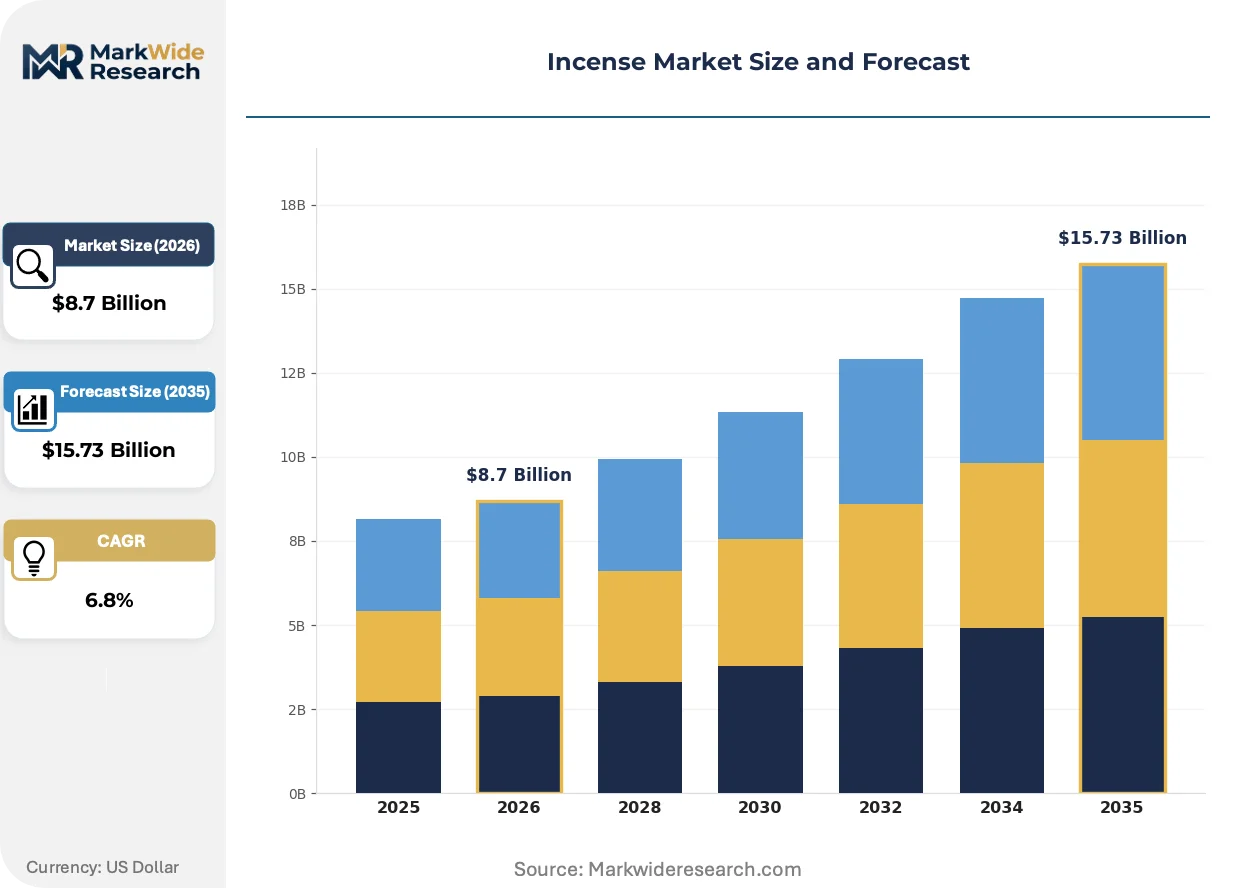
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stick, Cone, Coil, Powder Raw Material: Bamboo, Herbs, Resins, Oils Usage Type: Aromatherapy, Religious, Medicinal, Recreational Distribution Channel: Online, Retail, Wholesale, Specialty Store |
| Companies Covered | HEM Corporation, Mysore Deep Perfumery House, Nippon Kodo Co., Ltd., Himalaya Agarbathies Private Limited, Hari Darshan Sevashram Pvt. Ltd., Shoyeido Co., Ltd., Cycle Pure Agarbathies Pvt. Ltd., Gonesh, Inc., Shrinivas Sugandhalaya LLP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incense Market Trends and Innovations
Formulation science and combustion engineering are redefining product safety credentials and premium positioning, separating certified clean-burning specialists from legacy commodity producers.
Low-smoke charcoal replacement technology is collapsing the traditional trade-off between fragrance intensity and particulate emissions. Japanese manufacturers adopting compressed wood-powder cores with modified combustion agents now supply hotel chains in Tokyo and Osaka that previously banned incense over air-quality concerns. This shift compresses demand for conventional bamboo-charcoal sticks in institutional settings.
India's BIS agarbathi safety standards are tightening particulate matter and heavy-metal thresholds for domestic sale and export certification. Manufacturers in Mysore and Bengaluru must retest entire product lines, diverting R&D budgets from fragrance innovation toward compliance documentation. Smaller exporters without in-house testing facilities face exclusion from European retail procurement lists.
Specialty retail buyers now demand batch-level allergen disclosure and origin tracing for resin inputs. Independent apothecaries in Portland and Berlin reject anonymous supply chains, forcing Southeast Asian resin traders to implement digital tagging systems. This behavioral pivot favors vertically integrated producers with captive sourcing relationships over commodity brokers.
Incense Market Segmentation
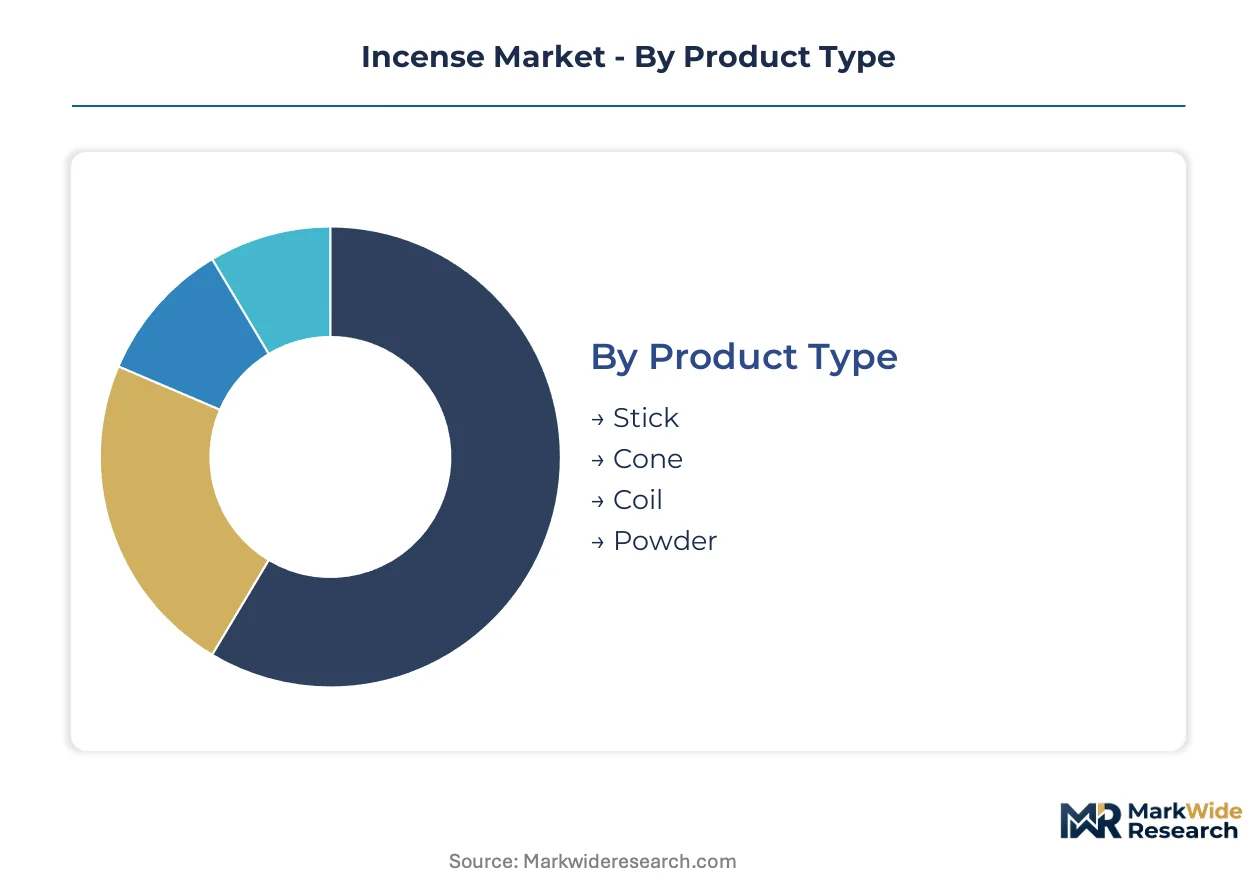
Incense market segmentation reveals how manufacturing economics, combustion engineering, and distribution logistics create distinct margin pools. Product format and raw material stratification determine which producers capture premium positioning versus commodity pricing.
Product Type:
After-sales intensity varies sharply across formats, with coil and powder variants requiring specialized burner accessories and replacement cycles that lock consumers into branded ecosystems.
- Stick:Standardized 21–23 cm formats with bamboo cores and charcoal powder bases dominate manufacturing economics through automated rolling and drying lines. Religious consumption across South Asia and the Middle East sustains volume leadership, though clean-burning reformulations now command price premiums in German pharmacy channels.
- Cone:Compressed aromatic biocomposites with modified combustion agents enable controlled burn rates without external supports. Demand concentrates in Japanese temple supply and North American meditation studio segments where low-smoke credentials determine procurement decisions.
- Coil:Extended-duration spiral formats serve institutional settings requiring multi-hour continuous fragrance release. Mosques and meditation centers in Southeast Asia represent core demand clusters.
- Powder:Loose granular formulations enable custom blending and ceremonial scattering applications. Specialist apothecaries in Portland and Berlin stock traceable-origin powders for ritual practitioners.
Stick holds the largest share; momentum sits with Cone as low-smoke mandates reshape institutional procurement.
Raw Material:
Cost tier stratification separates captive resin suppliers from commodity bamboo processors, with therapeutic-grade oil extraction commanding the widest margin spreads.
- Bamboo:FSC-certified culm sourcing from Karnataka plantations underpins India's export competitiveness to Middle Eastern markets. Clustered processing achieves scale efficiencies that commodity herb suppliers cannot match.
- Herbs:Dried botanical inputs compete primarily on volume and drying consistency. Domestic Indian agarbathi manufacturers source palmarosa and vetiver through Tamil Nadu agricultural cooperatives.
- Resins:Somalian frankincense and Omani myrrh harvests face climate volatility and export licensing delays that squeeze therapeutic-grade oil formulations. Vertically integrated Japanese houses with Southeast Asian sourcing relationships capture premium positioning.
- Oils:Therapeutic-grade essential oil loads of 8–15% by weight enable aromatherapy applications in German wellness retail and United States subscription box channels.
Bamboo holds the largest share; momentum sits with Oils as wellness consumers substitute natural fragrance for synthetic alternatives.
Usage Type:
Application maturity varies from millennia-old religious practice to emerging wellness positioning, with regulatory frameworks fragmenting across end-use categories.
- Aromatherapy:Wellness-oriented consumers in Germany and the United States substitute incense for synthetic air fresheners, pulling volumes through pharmacy and spa channels. Yoga studios and meditation apps bundle products with subscription kits, creating recurring demand outside traditional consumption patterns.
- Religious:Temple and household ritual consumption across India, Thailand, and Indonesia sustains volume foundations. Standardized production economics and established distribution networks reinforce incumbent positioning.
- Medicinal:Traditional Ayurvedic and TCM practitioners prescribe specific resin combinations for respiratory and stress indications. Regulatory classification varies across jurisdictions, constraining cross-border marketing claims.
- Recreational:Ambient fragrance occasions in urban households face substitution pressure from electric diffusers in Japanese and South Korean markets. Artisanal and small-batch positioning defends margin in specialty retail.
Religious holds the largest share; momentum sits with Aromatherapy as wellness positioning captures fastest expansion.
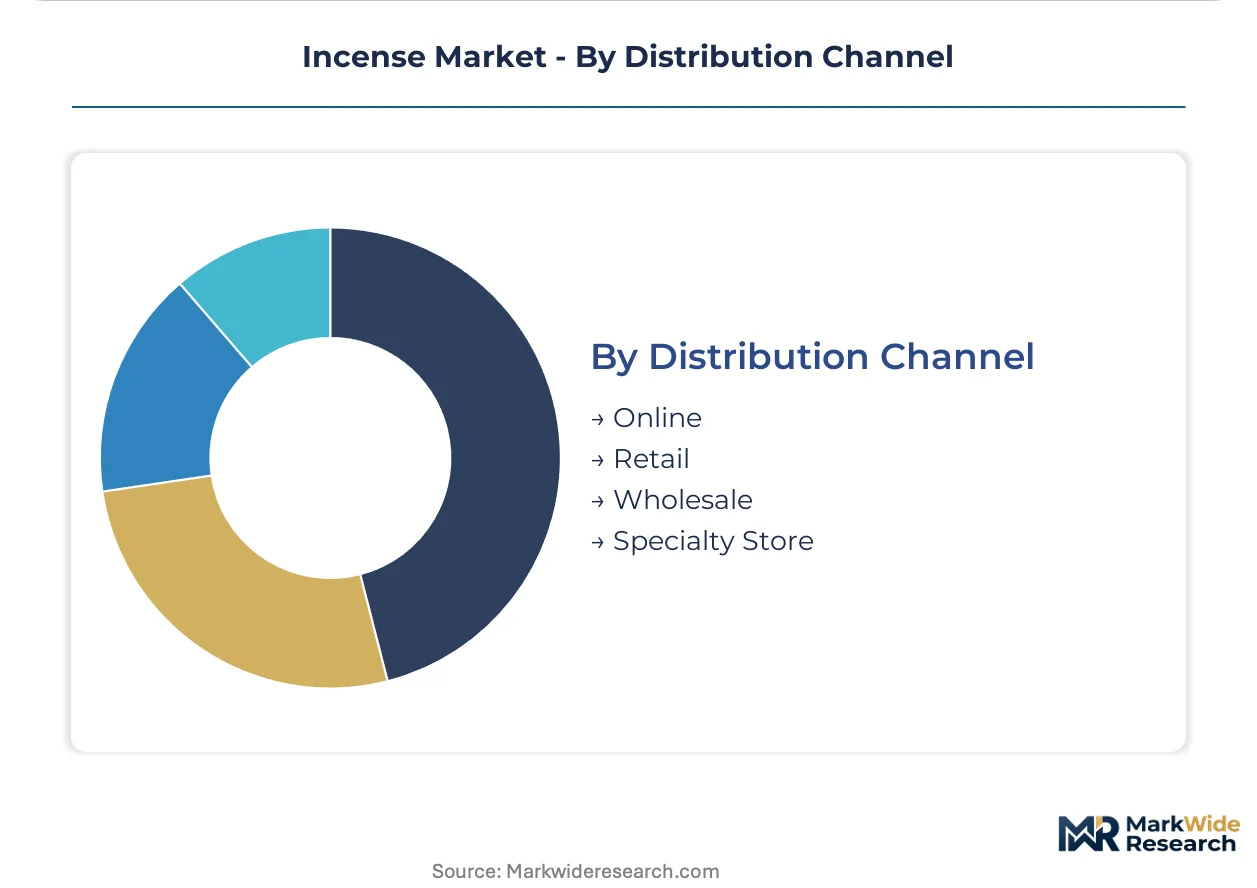
Distribution Channel:
Customer type fragmentation separates price-sensitive bulk procurement from experience-driven specialty purchases, with digital channels collapsing traditional wholesale margins.
- Online:Subscription box services in Canada and Australia bypass fragmented retail distribution, capturing full margin on artisanal lines. Direct-to-consumer models enable batch-level allergen disclosure that specialty retail buyers now demand.
- Retail:Mass-market shelf space in Indian kirana stores and Middle Eastern supermarkets moves commodity-grade agarbathi through high-velocity, low-margin turnover.
- Wholesale:Institutional procurement by hotel chains and temple administrations concentrates volume in standardized formats. EU Green Deal bio-based materials mandates now shape supplier qualification.
- Specialty Store:Independent apothecaries in Berlin and Portland reject anonymous supply chains, forcing digital tagging implementation by Southeast Asian resin traders.
Retail holds the largest share; momentum sits with Online as subscription models reshape purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wellness-oriented buyers in Germany and the United States drive premium aromatherapy demand, while religious consumption anchors volume in India and Southeast Asia. Regulatory fragmentation across BIS, REACH, and EPA frameworks shapes export compliance costs. Manufacturing clusters in Karnataka and Tamil Nadu supply global distribution networks.
India
Religious household consumption and temple procurement sustain volume leadership for agarbathi products. BIS certification mandates for particulate emissions and heavy-metal thresholds extend approval timelines to 8-14 months for new variants. Karnataka's Mysore-Bengaluru corridor hosts concentrated manufacturing operations serving Middle Eastern export markets.
Germany
Wellness retailers and pharmacy channels substitute natural incense for synthetic air fresheners, pulling premium volumes through spa and apothecary networks. EU REACH aromatic chemical disclosure requirements determine supplier qualification for institutional procurement. Berlin's independent apothecaries reject anonymous supply chains, forcing batch-level allergen documentation.
United States
Yoga studios and meditation apps bundle incense with subscription wellness kits, creating recurring demand outside traditional religious patterns. EPA indoor air quality guidelines influence formulation standards for imported products. Portland specialty retailers stock traceable-origin powders for ritual practitioners.
Japan
Kyoto-style blending techniques command shelf space in specialty retail and temple supply channels. METI standards and traditional craft preservation programs support artisan apprenticeship systems. Tokyo and Osaka hotel chains now source low-smoke compressed wood-powder cores after previous bans on conventional stick formats.
United Arab Emirates
Mosque and hospitality procurement concentrates demand for extended-duration coil formats and luxury resin blends. MOHAP product safety registration requirements shape import documentation for frankincense and myrrh formulations. Dubai's retail infrastructure distributes Indian and Omani origin products across Gulf Cooperation Council markets.
Incense Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into scale-driven commodity manufacturers, heritage craft houses, and wellness-positioned specialists. Three archetypes dominate: vertically integrated resin sourcers, automated agarbathi producers, and artisanal apothecary suppliers. Competitive moves concentrate on clean-label certification acquisition and direct-to-consumer channel bypass of traditional wholesale margins.
Among heritage craft specialists, Nippon Kodo Co., Ltd. and Shoyeido Co., Ltd. occupy positions exemplifying centuries-old blending traditions and captive Southeast Asian resin relationships. Scale-driven Indian manufacturers include Mysore Deep Perfumery House, which represents clustered Karnataka production economics serving domestic distribution networks. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors—Japanese craft preservation versus Indian manufacturing scale.
| Leading Market Players |
|---|
| HEM Corporation |
| Mysore Deep Perfumery House |
| Nippon Kodo Co., Ltd. |
| Himalaya Agarbathies Private Limited |
| Hari Darshan Sevashram Pvt. Ltd. |
| Shoyeido Co., Ltd. |
| Cycle Pure Agarbathies Pvt. Ltd. |
| Gonesh, Inc. |
| Shrinivas Sugandhalaya LLP |
| Others |
Pricing and Supply Chain Analysis
Somalian frankincense harvest concentration and Omani myrrh licensing bottlenecks concentrate therapeutic-grade resin pricing power with vertically integrated Japanese houses, while Karnataka bamboo processors compete on scale-driven commodity margins.
Pricing Analysis
Cost-plus contracts with Somali resin indexation govern premium therapeutic-grade formulations, while spot purchasing dominates commodity bamboo-charcoal sticks. Price differentiation rests on BIS certification grade and EU REACH compliance tier, with clean-label variants commanding premiums in German pharmacy channels. Pricing pressure intensifies in the standard tier as Indian mid-tier manufacturers absorb reformulation capex for natural binder substitution. Religious procurement in Indian temple networks shows highest price sensitivity; wellness subscription buyers in North American direct-to-consumer channels exhibit lowest.
Supply Chain Analysis
Contract manufacturing concentrates with Mysore Deep Perfumery House and Cycle Pure Agarbathies in Karnataka, plus Nippon Kodo's Kyoto facilities for heritage craft output. Raw material sourcing draws from Somalian resin harvesters, Karnataka FSC-certified bamboo plantations, and Tamil Nadu herb cooperatives. Single-source vulnerability in frankincense supply chains exposes formulators to climate-induced harvest volatility. Distribution runs through Indian domestic kirana networks, Middle Eastern wholesale importers, and North American subscription box aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards producers who control scarce master blender apprenticeships and captive Southeast Asian resin relationships, while penalizing commodity players facing BIS certification delays and clean-label reformulation costs.
For Market Incumbents: Harden defensible positioning by acquiring in-house resin sourcing relationships in Vietnam and Cambodia to offset Somalian supply volatility. Accelerate BIS pre-certification for extended SKU lines before approval timelines lengthen further. Electric diffuser substitution in Japanese households threatens non-ritual incense occasions; counter through aromatherapy bundling with meditation app partnerships. For New Entrants and Emerging Players: Australian wellness subscription channels show geographic underpenetration relative to North American saturation, offering white-space for artisanal small-batch positioning. Target Portland and Berlin apothecary networks demanding batch-level allergen disclosure that legacy commodity exporters cannot satisfy. Launch through direct-to-consumer digital channels to bypass fragmented retail wholesale margins. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian agarbathi manufacturers facing 8-14 month BIS approval friction. Five-to-ten year viability favors vertically integrated houses with Kyoto-style craft preservation and Southeast Asian resin control over scale-driven commodity processors. Monitor EU REACH aromatic chemical disclosure enforcement intensity as inflection signal for clean-label premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captive supply from Vietnamese and Cambodian harvesters insulates margin from Somalian climate volatility. |
| BIS Pre-Certification Investment | Early approval locks in domestic Indian shelf space before competitors clear 14-month queues. |
| Direct-to-Consumer Channel Launch | Subscription models in Canada and Australia capture full margin bypassing fragmented wholesale networks. |
| Clean-Label Reformulation Program | Natural binder substitution qualifies products for EU Green Deal preferential procurement by hospitality chains. |
| Master Blender Apprenticeship Expansion | Kyoto-style training pipelines defend heritage positioning against Japanese-Taiwanese artisan competition. |
Research Methodology
The analysis maps agarbathi manufacturing clusters, aromatherapy wellness channels, and heritage craft production tiers, each validated through master blenders, temple procurement officers, and resin trading specialists. Primary interviews with Karnataka plant managers, German pharmacy category buyers, and Southeast Asian agricultural cooperatives combined with secondary validation from BIS certification records, EU REACH substance databases, and Indian customs export filings. Bottom-up production capacity modeling and top-down demand segmentation triangulate volume estimates.
Assumptions held fixed include BIS particulate emission thresholds and EU aromatic chemical disclosure requirements; variables tested encompass resin supply disruption scenarios and electric diffuser substitution rates across the projection horizon. Segmentation dimensions modeled cover product format, raw material tier, usage type, and distribution channel. CAGRs derive from regression analysis against historical production volumes and wellness consumer expenditure patterns, with inputs from yoga studio procurement surveys and meditation app partnership disclosures.
Practitioners should monitor EU REACH enforcement actions and Somalian export licensing delays for early signals of margin compression or supply constraint. Forecasts reflect assumptions on regulatory stability and climate patterns in resin-producing regions. Quarterly review of BIS approval queue lengths and German pharmacy channel stocking rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Global Wind Chime Market
Home & Garden
Residential Snow Blower Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Global Hot Tub Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Lawn and Garden Water Equipment Market
Home & Garden
Gardening Pots Market
Home & Garden
Bird House Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Landscaping Services Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Outdoor Cooking Table Market