
 Wine Racks Market | 2026-2036
Wine Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Racks Market Analytics
E-commerce direct-to-consumer channels is reshaping how wine rack manufacturers reach residential buyers. VintageView leverages its wall-mounted specialization to dominate online visual merchandising. IKEA anchors mass-market accessibility through flat-pack logistics and global retail footprints. Genuwine Cellars sustains premium positioning with custom cellar design services that command higher project values.
A wine rack is a structured storage system engineered to hold bottles horizontally, maintaining cork moisture and preventing oxidation through stable temperature and vibration control. Units typically accommodate 750-milliliter Bordeaux-format bottles with 3- to 4-inch neck spacing, constructed via welded steel framing, hardwood joinery, or thermoformed polymer molding. Freestanding systems capture the largest volume share as consumers prioritize flexible placement in multipurpose living spaces. Metal construction leads commercial installations for durability and load-bearing capacity, while wood materials command premium residential margins where aesthetic integration drives selection.
EPA guidelines on formaldehyde emissions from composite wood products and EU REACH timber traceability requirements constrain material sourcing for wood-intensive manufacturers. The EU F-Gas Regulation indirectly shapes demand by pressuring climate-controlled cellar systems toward lower-GWP refrigerants, altering cooling unit specifications that accompany integrated rack installations. Stakeholders must monitor evolving building code amendments in major wine-consuming states and provinces that govern residential humidity control and electrical load permits for cellar conversions.
Market Dynamics
Residential wine collectors in suburban markets are driving climate-controlled cellar investments, while California's Title 24 building efficiency standards and evolving EU timber regulations tighten material sourcing compliance across manufacturing supply chains.
Growth Catalysts
- Estate Tourism Infrastructure:France's Bordeaux and Burgundy vineyard corridors are expanding direct-to-consumer wine sales, requiring premium cellar infrastructure to support visitor experiences and on-site retail.
- REACH Timber Traceability:The EU's enhanced timber due diligence requirements are accelerating certified sustainable wood sourcing, creating competitive differentiation for compliant manufacturers.
- Wall-Mounted Modular Systems:Thermoformed polymer molding advances are enabling lighter, more adaptable residential installations that integrate with open-concept living spaces.
Market Restraints
- Formaldehyde Emission Controls:EPA guidelines on composite wood products constrain material options for mid-tier manufacturers dependent on engineered substrates.
- F-Gas Refrigerant Transition:The EU F-Gas Regulation pressures climate-controlled cellar systems toward lower-GWP refrigerants, altering cooling unit specifications and supplier relationships.
- Oak and Walnut Price Volatility:Premium hardwood input costs fluctuate with forestry harvest cycles and international shipping rates, compressing margins on aesthetic-driven residential segments.
Strategic Opportunities
- Flat-Pack Logistics Penetration:Mass-market accessibility through optimized packaging and global retail footprints remains underexploited outside established European and North American corridors.
- Integrated Humidity Control:Convergence of IoT sensor networks with rack-mounted microclimate management enables predictive maintenance services for high-value residential collections.
- Japan's Luxury Residential Segment:METI efficiency standards and aging demographics in urban centers create demand for compact, technology-integrated wine storage solutions.
Industry Challenges
- Master Craftsman Shortage:Custom cellar design services require specialized woodworking and climate engineering expertise that training pipelines have not replenished.
- Electrical Load Permitting Complexity:Building code amendments in major wine-consuming states govern residential humidity control installations, extending project timelines and inspection requirements.
- Legacy Rack Retrofit Integration:Existing cellar infrastructure often lacks compatibility with modern cooling specifications, complicating upgrade paths for established collectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Racks Market |
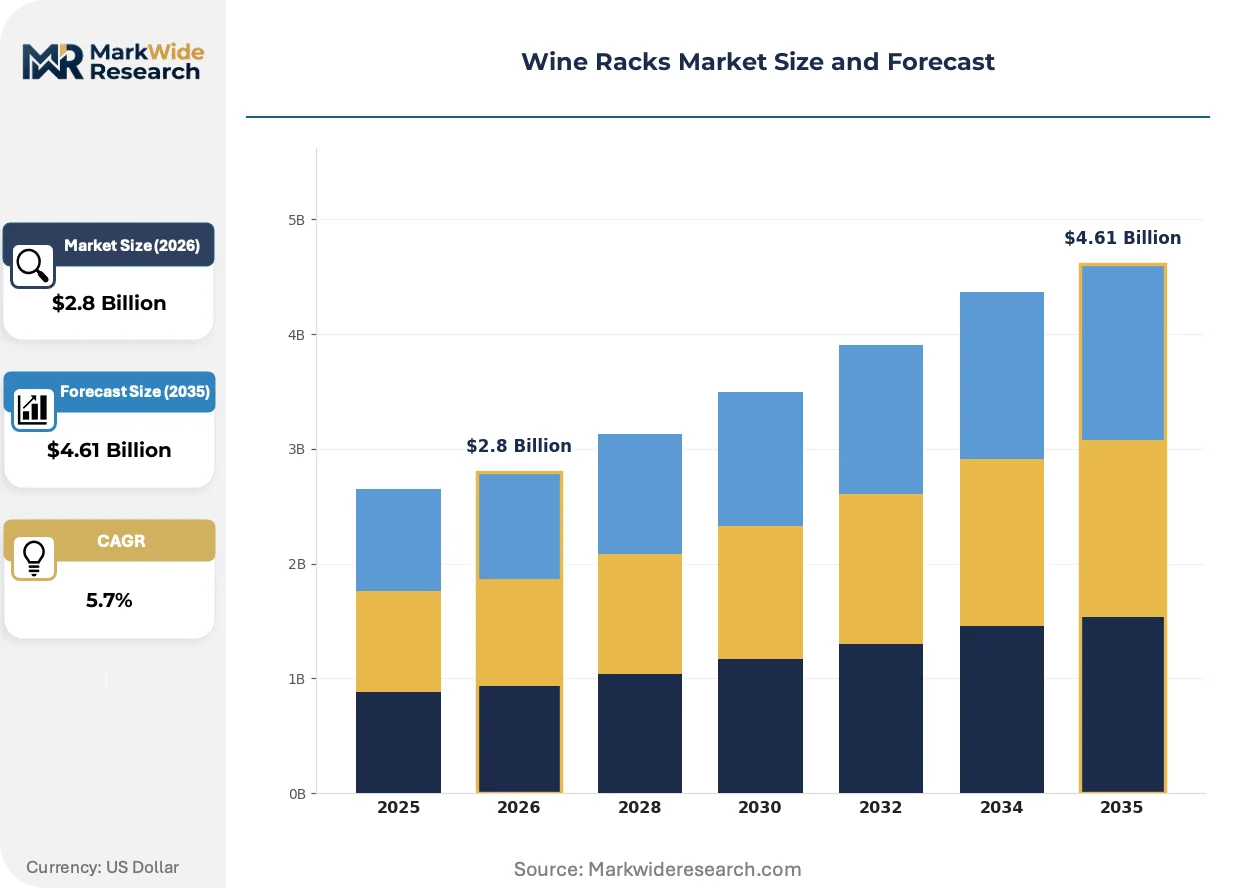
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Freestanding, Tabletop, Commercial Material: Wood, Metal, Plastic, Glass End User: Residential, Hospitality, Retail, Witete Vintners Design Style: Modern, Rustic, Vintage, Minimalist |
| Companies Covered | Wine Racks America, VintageView, IKEA, Genuwine Cellars, Wine Cellar Innovations, Vinotemp, J.K. Adams, Vigilant, Ultra Wine Racks & Cellars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Racks Market Evolving Landscape
Wine rack manufacturing is experiencing material convergence and regulatory acceleration that reshape competitive positioning across residential and commercial segments.
Welded steel framing with hardwood cladding is hybridizing to deliver load-bearing commercial durability alongside residential aesthetic warmth. Hospitality operators in restaurant and hotel verticals are adopting these composite systems at accelerating pace. The technology is compressing the traditional trade-off between structural performance and design flexibility that previously segmented metal and wood suppliers.
The EU F-Gas Regulation is mandating lower-global-warming-potential refrigerants in climate-controlled cellar systems. This industrial consequence cascades into cooling unit specifications that accompany integrated rack installations. Premium residential projects in Germany and France are most affected, with installers requalifying supplier relationships to meet phased compliance deadlines.
Collector purchasing behavior is fragmenting across direct-to-consumer digital channels and specialized retail consultation. Mass-market buyers are displacing traditional furniture store intermediation with visual-first online selection tools. This channel rotation is most visible in North American suburban markets where wall-mounted specialization dominates discovery and comparison shopping.
Wine Racks Market Segmentation
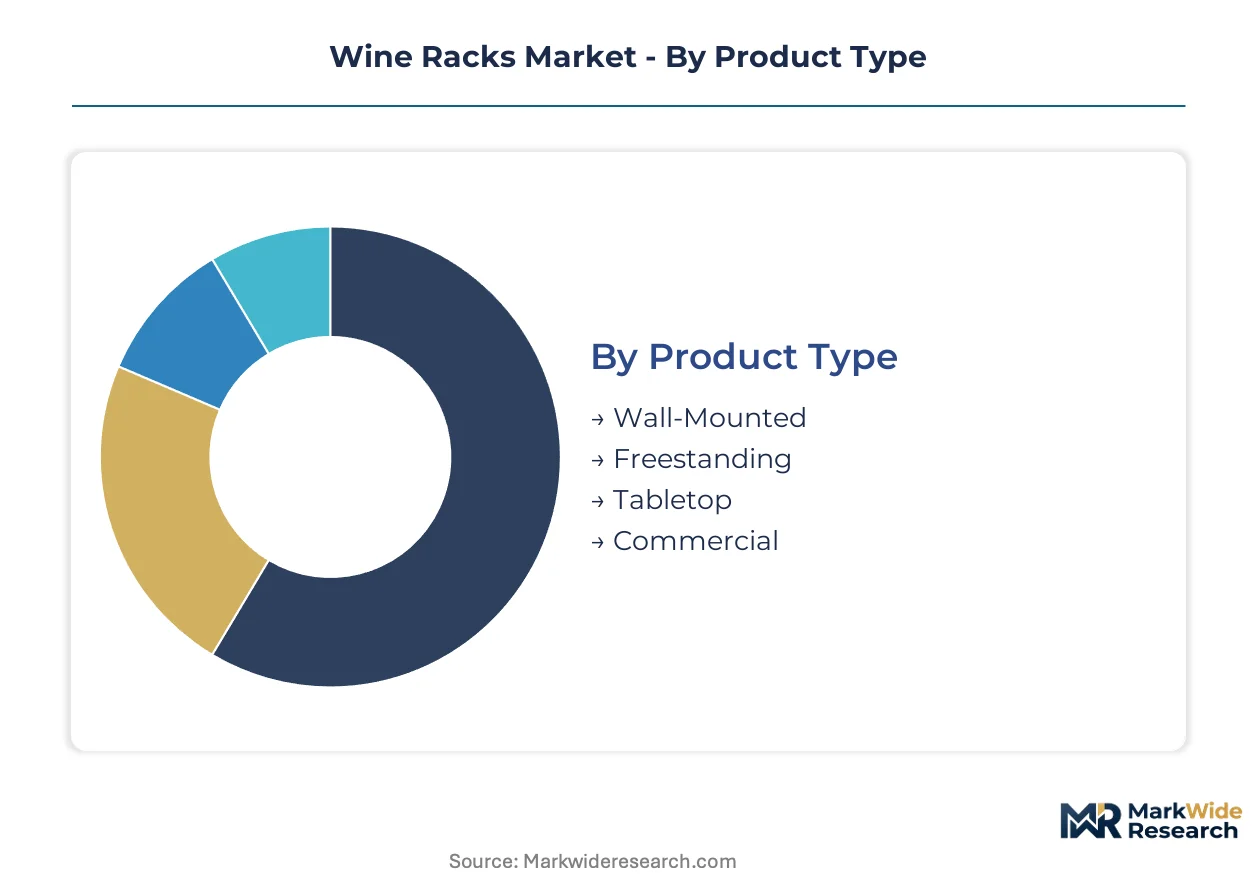
Wine rack segmentation reveals divergent procurement cycles across installation types and material classes. Residential collectors replace tabletop units every 3-5 years while integrated cellar systems persist for 15-20 years, creating distinct aftermarket and replacement revenue streams.
Product Type:
Freestanding systems turn inventory fastest through furniture retail channels, while commercial installations cycle slowly through construction procurement timelines.
- Wall-Mounted:Horizontal bottle orientation with concealed bracket systems supporting 30-300 bottle capacities. Suburban residential markets in California and Texas drive specification as open-concept living spaces prioritize floor area preservation. Thermoformed polymer advances are reducing unit weight by 40% versus legacy steel alternatives.
- Freestanding:Modular cube or columnar structures enabling flexible room placement without structural wall attachment. IKEA and mass-market retailers dominate volume through flat-pack logistics optimized for e-commerce fulfillment. This segment captures the largest volume share as consumers prioritize multipurpose living space adaptability.
- Tabletop:Compact countertop units accommodating 6-24 bottles for immediate consumption staging.
- Commercial:Engineered systems for restaurants, hotels, and tasting rooms requiring seismic bracing and fire-rated materials.
Freestanding dominates installed base. Wall-mounted is where expansion concentrates.
Material:
Premium hardwoods command the widest margin spreads, while metal and plastic compete on cost tier and regulatory compliance velocity.
- Wood:Oak, walnut, and mahogany joinery delivering thermal mass stability and aesthetic warmth for residential cellars. Bordeaux and Burgundy vineyard corridors in France specify certified sustainable sourcing under EU timber due diligence requirements. Formaldehyde emission controls from EPA guidelines constrain engineered substrate options for mid-tier manufacturers.
- Metal:Welded steel or aluminum framing with powder-coated finishes prioritizing load-bearing capacity and commercial durability. Hospitality operators in restaurant and hotel verticals are adopting hybrid steel-hardwood systems at accelerating pace. This construction leads commercial installations for durability and vibration dampening performance.
- Plastic:Thermoformed polymer molding enabling lighter residential installations with corrosion resistance.
- Glass:Tempered shelving with LED integration for display-forward residential applications.
Wood commands premium residential margins. Metal is gaining share fastest in commercial retrofit projects.
End User:
Residential demand fragments across collector sophistication levels, while hospitality procurement centralizes through design-build firms.
- Residential:Climate-controlled cellar investments from suburban collectors prioritizing cork moisture preservation and oxidation prevention. California's Title 24 building efficiency standards govern humidity control electrical load permitting, extending project timelines. Collector purchasing behavior is fragmenting across direct-to-consumer digital channels and specialized retail consultation.
- Hospitality:Restaurant, hotel, and tasting room installations requiring compliance with commercial fire codes and seismic bracing.
- Retail:Wine shop and liquor store fixtures optimizing bottle density and customer browsing flow.
- Witete Vintners:Estate-owned production facilities and visitor center infrastructure supporting direct-to-consumer sales.
Residential dominates installed base. Hospitality is where expansion concentrates.
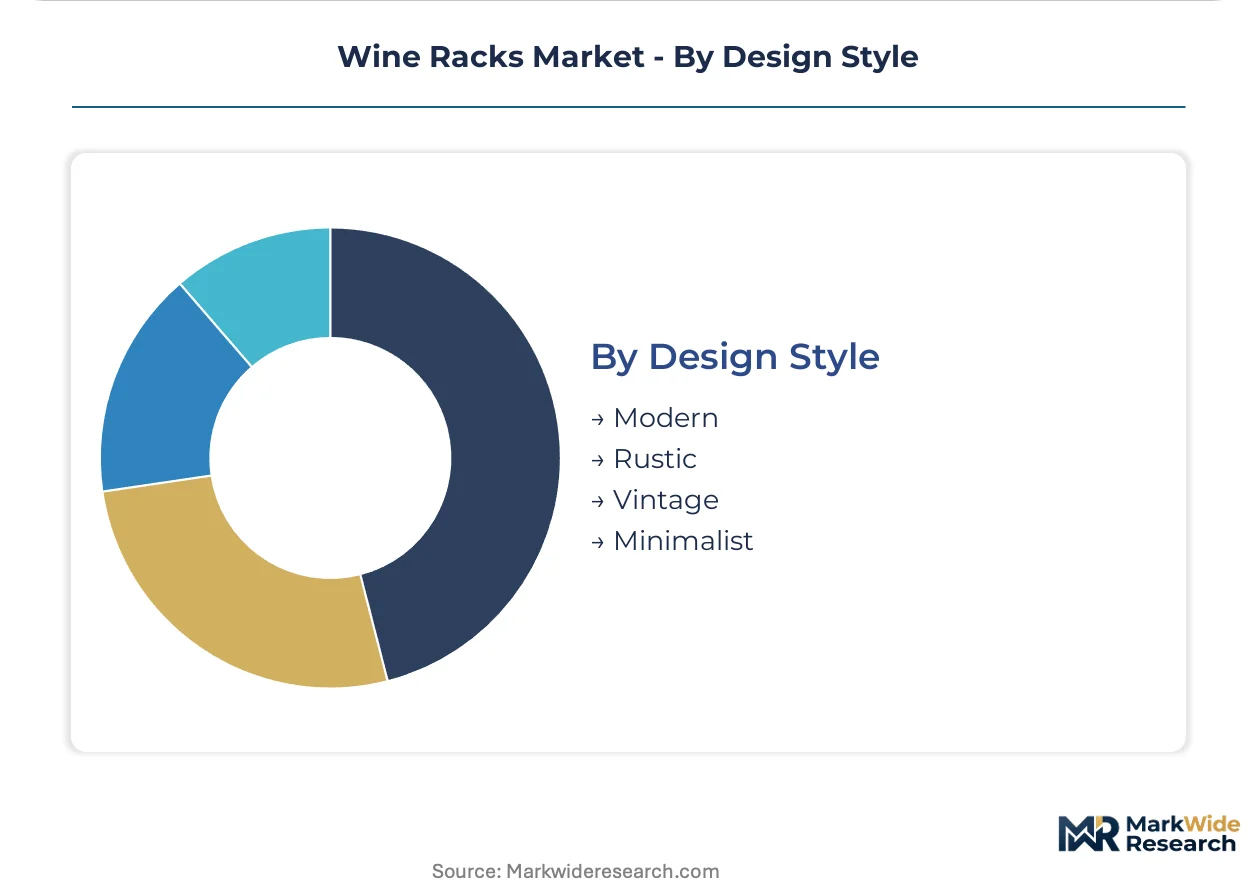
Design Style:
Modern and minimalist aesthetics accelerate through digital discovery channels, while rustic and vintage styles persist in traditional cellar consultation.
- Modern:Clean lines with concealed hardware and integrated LED lighting systems. Visual-first online selection tools favor this aesthetic for e-commerce merchandising and comparison shopping efficiency.
- Rustic:Distressed wood and wrought iron accents emphasizing cellar heritage and traditional wine culture.
- Vintage:Reclaimed materials and antique styling for estate tourism environments in French vineyard corridors.
- Minimalist:Floating wall systems and hidden supports maximizing spatial perception in compact urban residences.
Modern dominates installed base. Minimalist is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American wine rack distribution, handling containerized imports of finished metal and hardwood components from Asian manufacturing centers.
United States
Suburban residential collectors in California and Texas drive climate-controlled cellar investments as open-concept living spaces proliferate. EPA formaldehyde emission guidelines constrain composite wood sourcing for mid-tier manufacturers. The Napa-Sonoma corridor concentrates estate tourism infrastructure requiring premium visitor center displays.
France
Bordeaux and Burgundy vineyard corridors expand direct-to-consumer sales through on-site retail experiences. EU REACH timber traceability requirements accelerate certified sustainable wood sourcing compliance. The Médoc sub-region concentrates estate cellar renovation activity tied to hospitality expansion.
Germany
Premium residential projects in Baden-Württemberg and Bavaria requalify cooling unit specifications under EU F-Gas Regulation phased compliance deadlines. METI-aligned efficiency standards influence technology-integrated storage specifications. The Stuttgart metropolitan area anchors precision metal fabrication for hybrid steel-hardwood systems.
Japan
Compact urban residences in Tokyo and Osaka create demand for minimalist wall-mounted installations preserving floor area. METI efficiency standards govern humidity control electrical specifications. The Kansai region concentrates luxury condominium development integrating technology-enabled wine storage.
Canada
Vancouver and Toronto metropolitan markets prioritize seismic-braced commercial installations for hospitality operators. Health Canada building code amendments govern residential humidity control permitting timelines. The Okanagan Valley concentrates winery visitor center infrastructure requiring display-forward rack systems.
Wine Racks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying fabricated metal and finished hardwood elements. The vendor base distributes across three tiers: mass-market flat-pack distributors, mid-tier modular system manufacturers, and custom cellar design houses. Three strategic archetypes dominate: visual-merchandising specialists leveraging wall-mounted formats, logistics-optimized retailers exploiting global footprint density, and project-based firms capturing premium residential margins through climate engineering integration. Competitive moves concentrate on flat-pack logistics penetration and IoT-enabled humidity control convergence.
Within the visual-merchandising archetype, VintageView exemplifies wall-mounted specialization through online discovery optimization. IKEA anchors mass-market accessibility through flat-pack logistics and retail footprint density. Genuwine Cellars occupies the premium project tier, representing custom cellar design services that command higher residential installation values.
| Leading Market Players |
|---|
| Wine Racks America |
| VintageView |
| IKEA |
| Genuwine Cellars |
| Wine Cellar Innovations |
| Vinotemp |
| J.K. Adams |
| Vigilant |
| Ultra Wine Racks & Cellars |
| Others |
Value Network & Pricing Analysis
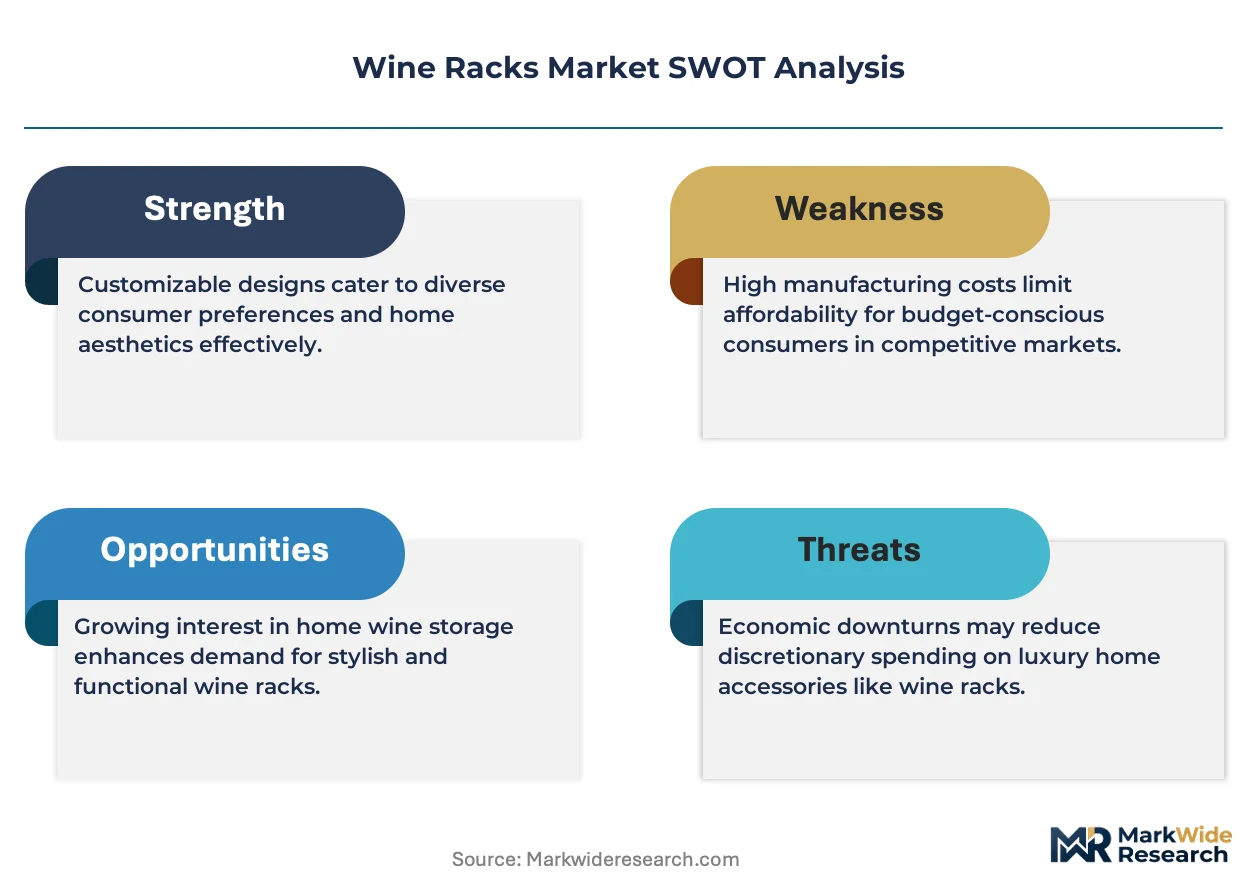
Oak and walnut price volatility determines both tiered pricing spreads and supply chain configuration, compressing margins on aesthetic-driven residential segments while forcing mid-tier manufacturers toward engineered substrates constrained by EPA formaldehyde guidelines.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with project-based custom cellar contracts commanding premium positioning against flat-pack mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Genuwine Cellars' climate-engineered installations from IKEA's logistics-optimized units from tabletop import alternatives. Cost compression in mid-tier wood-intensive segments is intensifying because EU REACH timber traceability requirements add compliance overhead. Mass-market suburban collectors exhibit highest price sensitivity, while estate tourism operators in French vineyard corridors demonstrate lowest sensitivity due to visitor experience ROI requirements.
Supply Chain Analysis
Contract manufacturing concentration rests with precision metal fabricators in Germany's Stuttgart metropolitan area and thermoformed polymer molders in Asian manufacturing centers serving flat-pack distributors. Raw material dependencies draw from certified sustainable oak harvests in French forestry cooperatives, powder-coated steel from German foundries, and corrosion-resistant polymer resins from specialized chemical suppliers. Single-source vulnerability concentrates in certified hardwood certification bodies approved under EU timber due diligence frameworks. Distribution runs through the Port of Long Beach for North American containerized imports, with secondary consolidation through European distribution hubs serving Bordeaux and Burgundy estate corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine rack incumbents face substitution pressure from integrated smart-home storage systems that embed climate control within cabinetry, eroding the distinct value proposition of standalone cellar infrastructure.
For Market Incumbents: Insulate premium positioning by deepening certified sustainable wood sourcing partnerships under EU REACH frameworks, locking in compliant supply ahead of regulatory tightening. Counter smart-home substitution threats through backward integration into IoT-enabled humidity sensor networks that enable predictive maintenance services for high-value collections.
For New Entrants and Emerging Players: Establish a beachhead in Japan's compact urban luxury residential segment, where METI efficiency standards and aging demographics create unmet demand for technology-integrated minimalist wall-mounted systems. Penetrate through direct-to-consumer digital channels with visual-first online selection tools, bypassing traditional furniture retail intermediation that dominates established markets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors custom cellar design houses with climate engineering capabilities over mass-market flat-pack distributors. Long-term viability hinges on regulatory compliance velocity rather than scale economics. Watch EU F-Gas Regulation phased compliance deadlines as inflection indicator for cooling unit supplier requalification activity and premium residential project delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Certified Sustainable Sourcing Program | EU REACH timber traceability requirements accelerate competitive differentiation for compliant manufacturers. |
| IoT-Enabled Humidity Control Integration | Convergence with sensor networks enables predictive maintenance services for high-value residential collections. |
| Flat-Pack Logistics Expansion | Optimized packaging and global retail footprints penetrate underexploited corridors outside Europe and North America. |
| Master Craftsman Training Pipeline | Specialized woodworking and climate engineering expertise shortages constrain custom cellar design service capacity. |
| Hybrid Steel-Hardwood System Development | Welded steel framing with hardwood cladding compresses the structural performance versus design flexibility trade-off. |
Research Methodology
Cross-validation between primary interviews with cellar design architects, hospitality procurement directors, and certified wood sourcing managers and secondary validation through EPA formaldehyde emission filings, EU timber certification registries, and customs import records anchors the qualitative findings. Bottom-up demand modeling from residential construction permits and estate tourism visitor metrics triangulates against top-down market sizing from manufacturer production disclosures.
Calibration against historical replacement cycles and regulatory implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include installation type, material class, end-user vertical, and design aesthetic tier. CAGRs derive from elasticity-adjusted demand curves incorporating California Title 24 building efficiency standard adoption rates and EU F-Gas Regulation compliance phase-ins. Industry-specific forecast inputs include suburban residential climate-controlled cellar investment surveys and Bordeaux-Burgundy estate infrastructure expansion pipelines.
Stress conditions across oak price volatility bands, tariff exposure on Asian-manufactured polymer components, and electrical load permitting timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and collector demographic shift rates. Quarterly review of EU timber certification approval backlogs and California residential humidity control permit issuance volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Incense Market
Home & Garden
Candle Market
Home & Garden
United Kingdom Homeware Market
Home & Garden
Christmas Decorations Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Preserved Flowers Market
Home & Garden
Gardening Pots Market
Home & Garden
North America Floral Gifting Market
Home & Garden
US Garden Planter Market
Home & Garden
Global Wind Chime Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Aquarium LED Lighting Market
Home & Garden
Bird House Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Asia-Pacific Bonsai Market