
 Japan Flower Pots Market | 2026-2036
Japan Flower Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Flower Pots Market Foresight
Kyushu ceramic production clusters is reconfiguring supply dynamics for Japanese flower pot manufacturers. Izawa Seito Co. Ltd. anchors high-fired porcelain output from its Saga Prefecture kilns, leveraging centuries-old ceramic techniques for premium indoor collections. MEIZAN Ceramics Industry Co., Ltd. competes through specialized glaze formulations that differentiate its modern-style offerings in metropolitan retail channels. Maruhiro Inc. sustains design-forward positioning through Hasami ware aesthetics that occupy distinct shelf space in lifestyle boutiques.
Flower pots are rigid containers engineered from clay composites, thermoformed polymers, or pressed metal alloys, designed to house root systems while managing drainage and aeration through calibrated perforation patterns. Ceramic and plastic material types dominate unit volume, with ceramic commanding margin pools in the premium segment due to firing energy costs and artisan labor inputs, while plastic scales efficiently across mass-market balcony usage applications. Small and medium sizes lead transaction frequency in dense urban settings where space constraints limit container dimensions, though large-format garden pots retain higher per-unit profitability for specialized retailers.
METI establishes industrial standards for chemical migration in food-contact-grade ceramics that extend to decorative pottery production, while JIS standards govern dimensional tolerances and load-bearing specifications for injection-molded plastic containers. The Ministry of the Environment's plastic resource circulation targets are forcing reformulation of virgin petroleum-based resins toward recycled or bio-derived alternatives. Stakeholders must monitor evolving prefectural waste sorting mandates and their impact on end-of-life collection infrastructure for composite material pots.
Market Dynamics
METI's resource circulation mandates are forcing domestic manufacturers to reconfigure material sourcing, while urban balcony gardening adoption among Tokyo apartment dwellers is compressing product development cycles toward smaller, lighter formats.
Growth Catalysts
- Urban Balcony Gardening:Dense metropolitan housing in Greater Tokyo drives transaction frequency for compact container formats, with apartment dwellers prioritizing space-efficient designs over traditional garden-scale products.
- Hasami Ware Aesthetic Premium:Design-forward positioning through heritage ceramic techniques commands distinct shelf placement in lifestyle boutiques, differentiating domestic production from mass-imported alternatives.
- METI Resource Circulation Policies:Regulatory pressure on virgin petroleum-based resins is accelerating manufacturer investment in recycled and bio-derived polymer formulations for balcony applications.
Market Restraints
- Ceramic Firing Energy Costs:Natural gas and electricity inputs for high-fired porcelain production in Saga Prefecture kilns create persistent margin pressure that plastic competitors avoid.
- Kyushu Supply Concentration:Ceramic output clusters in Saga and Nagasaki prefectures expose manufacturers to localized logistics disruptions and single-region dependency risks.
- Prefectural Waste Sorting Fragmentation:Inconsistent end-of-life collection infrastructure across Japan's 47 prefectures complicates composite material pot recovery and circularity claims.
Strategic Opportunities
- Kansai Corridor Expansion:Osaka and Kyoto metropolitan areas show underpenetrated demand relative to Kanto saturation, offering white-space growth for specialized retailers.
- Smart Irrigation Convergence:Integration of moisture sensors and connected watering systems with premium ceramic containers targets tech-forward urban gardeners.
- Ministry of Environment Plastic Targets:Mandatory recycled content thresholds create first-mover advantage for manufacturers with established bio-resin supply chains.
Industry Challenges
- Artisan Labor Scarcity:Traditional ceramic technique transmission faces generational gaps in Saga Prefecture production clusters, threatening quality consistency for heritage-positioned brands.
- JIS Certification Timelines:Dimensional tolerance and load-bearing testing for injection-molded plastic containers creates 4-6 month product launch delays that outpace seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Flower Pots Market |
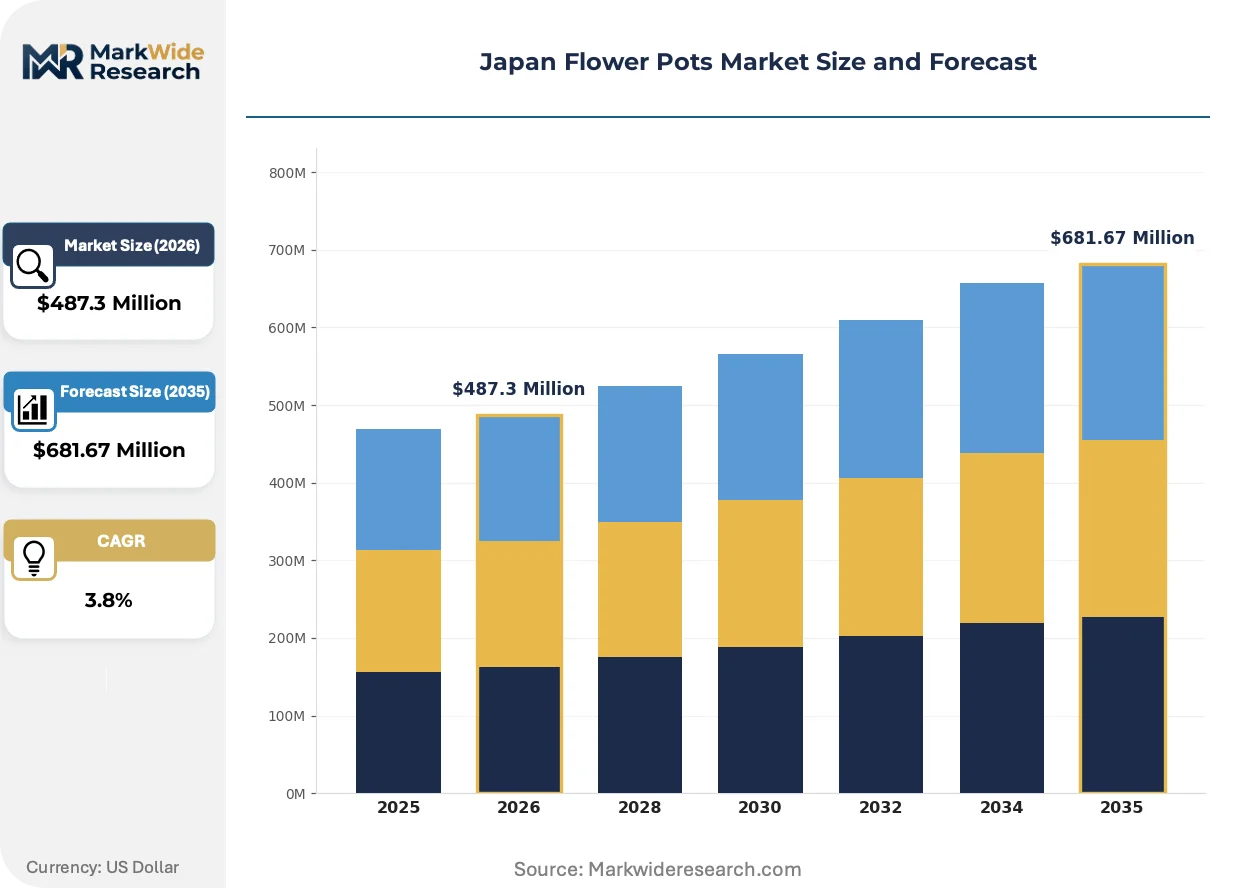
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ceramic, Plastic, Metal, Terra Cotta Size: Small, Medium, Large, Extra Large Style: Modern, Vintage, Rustic, Minimalist Usage: Indoor, Outdoor, Garden, Balcony |
| Companies Covered | Daiso Industries, Etsy, Maruhiro Inc., Izawa Seito Co. Ltd., MEIZAN Ceramics Industry Co., Ltd., Anhui Bochen Eco Co., Lechuza, ELHO, Keter Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Flower Pots Market Shifts & Advancements
Material science breakthroughs and regulatory pressure on petroleum-based inputs are converging to reshape competitive positioning across ceramic and polymer segments simultaneously.
Lightweight composite clays incorporating recycled glass and industrial byproducts are rendering obsolete traditional earthenware density standards. Tokyo-based balcony gardeners are adopting these formats at accelerating rates due to weight restrictions on high-rise installations. The structural consequence is compression of firing energy requirements and logistics costs for manufacturers serving metropolitan channels.
METI's chemical migration standards for food-contact-grade ceramics now extend to decorative pottery production, forcing glaze reformulation across Saga and Arita production zones. Industrial consequence includes elevated R&D expenditure for domestic manufacturers relative to import competitors. Small-format indoor collections face the steepest compliance burden due to surface-area-to-volume ratios.
Subscription-based plant-and-pot pairing services are displacing traditional retail purchasing in Greater Tokyo. Specialized e-commerce platforms and direct-to-consumer channels are capturing share from hardware stores and garden centers. This behavioral shift is most visible among millennial apartment dwellers in Setagaya and Shibuya wards who prioritize curation over ownership.
Japan Flower Pots Market Segmentation
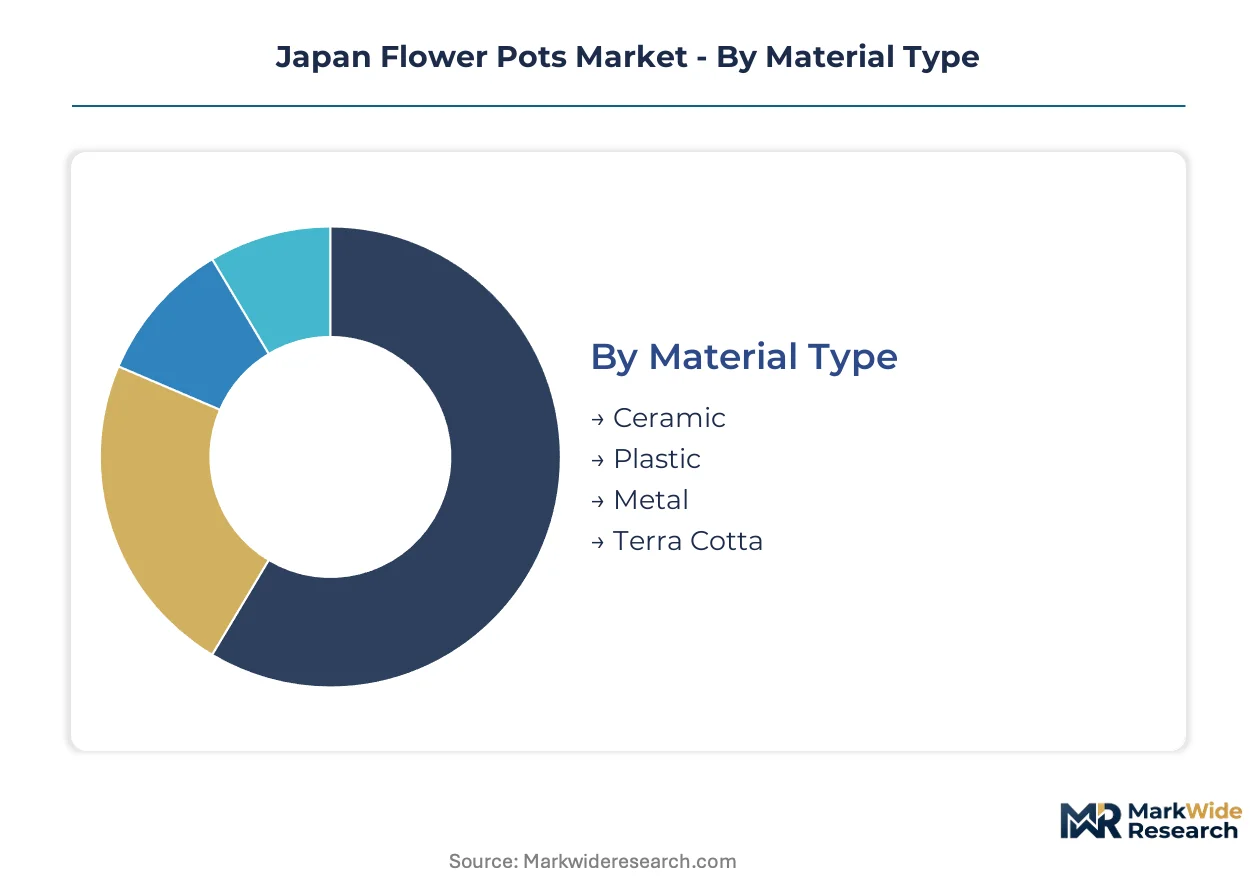
Segmentation in the Japan Flower Pots Market reveals distinct service intensity patterns across material and application boundaries. Ceramic formats demand specialized handling protocols and breakage replacement programs, while polymer segments prioritize volume logistics and seasonal replenishment cycles.
Material Type:
After-sales-service intensity varies dramatically across material categories, with ceramic requiring artisan repair networks and plastic emphasizing warranty standardization.
- Ceramic:High-fired porcelain and stoneware compositions from Saga Prefecture kilns demand temperature-controlled logistics and specialized breakage insurance programs. Tokyo apartment dwellers drive premium transaction frequency for hand-glazed indoor collections, though firing energy costs compress margins relative to polymer alternatives.
- Plastic:Injection-molded polypropylene and recycled resin formulations scale efficiently across mass-market balcony applications with minimal service touchpoints. METI's resource circulation mandates are accelerating manufacturer migration toward bio-derived alternatives for Kanto corridor distribution.
- Metal:Powder-coated aluminum and corten steel containers target commercial landscaping with extended durability warranties and corrosion resistance specifications.
- Terra Cotta:Unglazed earthenware from traditional production zones retains niche positioning for Mediterranean-style garden aesthetics with porous moisture management properties.
Ceramic holds the largest share; momentum sits with Plastic.
Size:
Cost tier stratification separates compact formats for dense urban housing from garden-scale containers commanding premium logistics expenditure.
- Small:Under-15cm diameter formats dominate transaction velocity in Setagaya and Shibuya ward balcony installations, with lightweight composites displacing traditional earthenware density standards.
- Medium:15-30cm containers balance root volume capacity with weight restrictions on high-rise installations, capturing the broadest household penetration across Greater Tokyo.
- Large:30-50cm formats retain higher per-unit profitability for specialized retailers serving suburban garden segments with dedicated delivery infrastructure.
- Extra Large:Above-50cm specimens require crane-assisted placement and custom substrate consultation, limiting addressable market to commercial landscaping and estate properties.
Medium formats anchor volume; Small formats are climbing the fastest.
Style:
Application context determines aesthetic selection, with metropolitan retail channels prioritizing design-forward positioning over traditional garden-center assortments.
- Modern:Clean geometric lines and matte finishes from Hasami ware production clusters occupy distinct shelf space in lifestyle boutiques targeting millennial curation preferences.
- Vintage:Reproduction Meiji-period motifs and distressed glaze techniques serve heritage-positioned collectors with specialized authentication requirements.
- Rustic:Unglazed textures and irregular firing marks from Kyushu artisan workshops appeal to wabi-sabi aesthetic adherents in Kyoto metropolitan areas.
- Minimalist:Monochrome palettes and concealed drainage systems integrate with contemporary interior design schemes for indoor plant-and-pot subscription services.
Modern styling commands premium positioning; Minimalist formats gain share fastest.
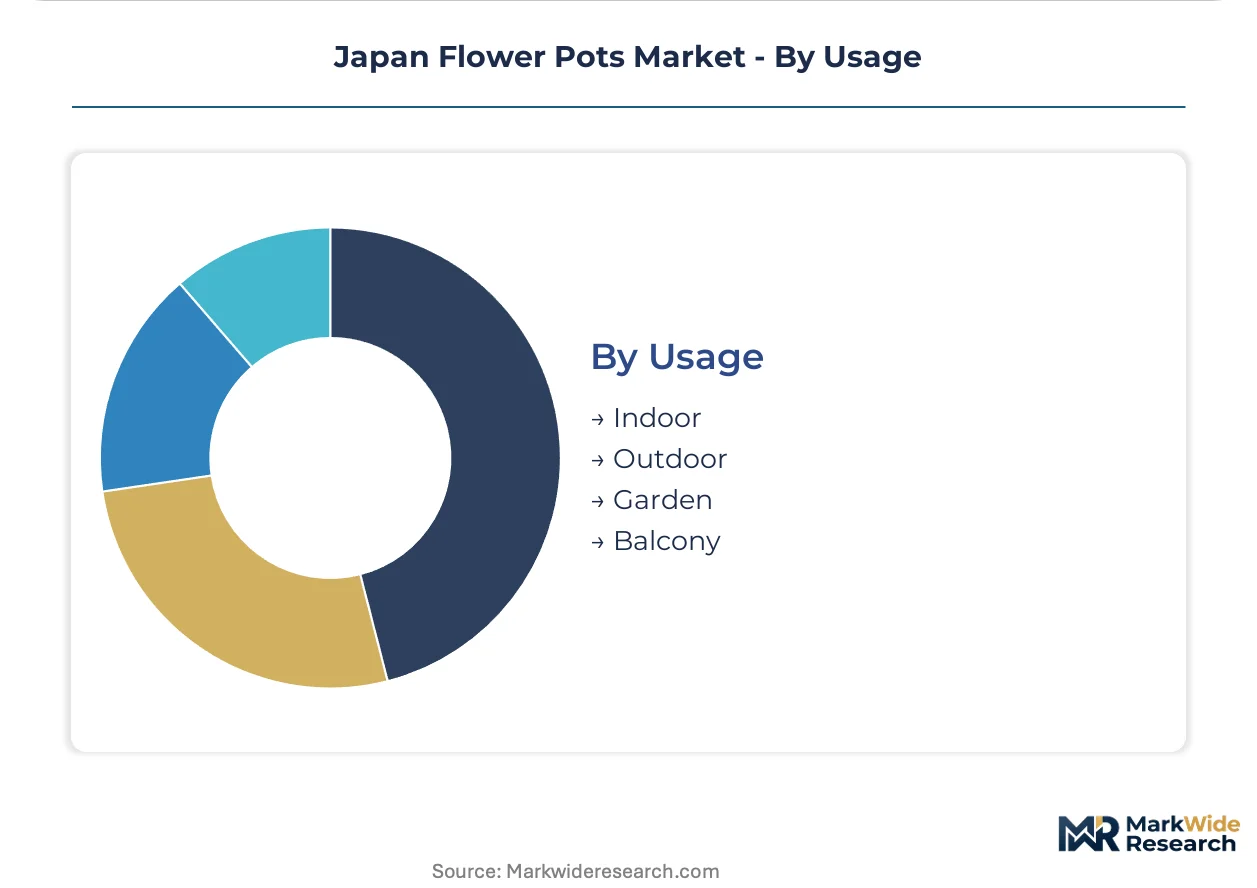
Usage:
Customer type fragmentation separates subscription-service millennials from traditional garden-center patrons across indoor and outdoor application boundaries.
- Indoor:Small-format collections with calibrated drainage and furniture-protection features target apartment dwellers prioritizing curation over ownership through direct-to-consumer channels.
- Outdoor:Weather-resistant glazes and frost-proof formulations serve suburban homeowners with seasonal storage and replacement cycle expectations.
- Garden:Large-scale installations with integrated irrigation compatibility retain specialized retailer relationships and landscape architect specification influence.
- Balcony:Weight-restricted, wind-stable designs with modular stacking capability dominate the fastest-expanding usage segment across Tokyo high-rise housing stock.
Outdoor usage holds established volume; Balcony applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Japan diverge sharply between dense metropolitan balcony installations and suburban garden-scale deployments, with regulatory pressure from METI and the Ministry of the Environment reshaping material preferences distinctly in each zone.
Kanto/Tokyo
Greater Tokyo apartment dwellers drive transaction velocity for sub-15cm lightweight formats, prioritizing weight-restricted designs for high-rise balcony installations. METI's resource circulation mandates accelerate manufacturer migration toward recycled resin formulations for this corridor. Setagaya and Shibuya wards anchor direct-to-consumer subscription growth for plant-and-pot pairing services.
Kansai/Osaka
Osaka and Kyoto metropolitan areas exhibit underpenetrated demand relative to Kanto saturation, offering white-space expansion for specialized retailers. The Ministry of the Environment's plastic resource circulation targets create compliance complexity for manufacturers distributing across prefectural boundaries. Kyoto's wabi-sabi aesthetic adherents sustain niche demand for rustic unglazed textures from artisan workshops.
Kyushu
Saga and Nagasaki prefectures concentrate high-fired porcelain production, with centuries-old ceramic techniques commanding premium positioning in metropolitan retail channels. METI's chemical migration standards for food-contact-grade ceramics extend to decorative pottery, forcing glaze reformulation across Arita production zones. Localized logistics dependencies expose manufacturers to single-region disruption risks.
Chubu/Nagoya
Nagoya's industrial manufacturing base supports injection-molded polymer container production for mass-market balcony applications. JIS certification timelines for dimensional tolerance testing create 4-6 month product launch delays that outpace seasonal demand windows. Regional distribution infrastructure serves as a logistical bridge between Kyushu ceramic clusters and Kanto consumption centers.
Hokkaido
Sapporo and surrounding municipalities present distinct seasonal storage requirements for frost-proof outdoor container formulations. Prefectural waste sorting mandates complicate end-of-life collection infrastructure for composite material pots relative to mainland standardization. Limited local production capacity necessitates inbound logistics from Honshu manufacturing centers.
Japan Flower Pots Market Competitive Landscape
Capability concentration sits with heritage ceramic specialists; scale advantage sits with polymer mass-market fabricators. The vendor base stratifies across three tiers: design-forward lifestyle positioning, commodity balcony utility, and commercial landscaping durability. Strategic archetypes include heritage-technique ceramic houses, recycled-resin polymer specialists, and subscription-curation service platforms. Dominant competitive moves encompass geographic corridor expansion and material formulation R&D acceleration.
Among Kyushu-based ceramic producers, Izawa Seito Co. Ltd. and MEIZAN Ceramics Industry Co., Ltd. exemplify the heritage-technique tier, occupying positions defined by centuries-old firing methods and specialized glaze expertise. Maruhiro Inc. represents the design-forward vector through Hasami ware aesthetics. Daiso Industries anchors mass-market scale operations. These entities collectively illustrate the market's structural divide between artisan capability and volume efficiency.
| Leading Market Players |
|---|
| Daiso Industries |
| Etsy |
| Maruhiro Inc. |
| Izawa Seito Co. Ltd. |
| MEIZAN Ceramics Industry Co., Ltd. |
| Anhui Bochen Eco Co. |
| Lechuza |
| ELHO |
| Keter Group |
| Others |
Supply & Pricing Matrix
The Hakata-to-Tokyo maritime corridor's container freight volatility directly compresses margin pools for Saga Prefecture ceramic exporters while amplifying price spreads between Kyushu-sourced heritage collections and Chubu-molded polymer alternatives. Metropolitan retailers exploit this logistics asymmetry to command premium positioning for design-forward ceramic formats against mass-market resin competitors.
Pricing Analysis
Price spreads between Kanto retail channels and Kyushu factory gates exceed those seen in comparable lifestyle goods categories, with freight absorption and breakage insurance driving differentiation. Three-tier pricing structure across premium hand-glazed porcelain, standard injection-molded resin, and economy virgin-polymer tiers reflects material input costs and artisan labor intensity. Pricing pressure stems from METI-mandated bio-resin reformulation R&D expenditure that manufacturers cannot fully pass to price-sensitive balcony gardeners. Subscription-service millennials in Setagaya and Shibuya wards exhibit lowest price sensitivity; mass-market hardware store patrons in suburban Chiba and Saitama prefectures resist premium tier migration.
Supply Chain Analysis
Export-control regimes on advanced ceramic kiln technologies limit technology transfer to competing Asian production zones, preserving Kyushu's heritage-technique moat. Supply concentrates in Japan's Saga and Nagasaki prefectures for high-fired porcelain, Chubu's Nagoya industrial corridor for injection-molded polymers, and coastal Chinese provinces for commodity resin feedstock. Raw material dependencies encompass kaolin clay deposits, petroleum-derived polypropylene resin, and cobalt-based glaze pigments. Single-source vulnerability sits with natural gas supply contracts powering Arita and Hasami district kilns. Distribution runs through specialized lifestyle boutiques for ceramic tiers and home-center retail networks for polymer mass-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-and-pot subscription services represent the fastest-expanding recurring-revenue layer, outpacing hardware transaction velocity as urban millennials prioritize curation continuity over single-unit ownership.
For Market Incumbents: Build artisan-network moats through apprenticeship pipeline investments in Saga Prefecture production clusters. Secure backward integration into bio-resin compound formulation ahead of Ministry of Environment recycled-content mandates. Defend against direct-to-consumer subscription platforms by capturing exclusive cultivar partnerships that lock replacement cycle demand. For New Entrants and Emerging Players: Kansai corridor balcony gardeners in Osaka and Kyoto metropolitan areas represent the most penetrable entry point given relative underpenetration against Kanto saturation. Target tech-forward urban gardeners through smart-irrigation-integrated ceramic formats that bypass established retail shelf competition. Deploy influencer-curated direct-to-consumer launches leveraging Hasami ware aesthetic recognition without heritage production investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified ceramics conglomerates with undermonetized decorative pottery divisions possessing dormant Arita production licenses. Long-term viability hinges on subscription-service platform economics proving durable against seasonal retail cyclicality. Watch for inflection when prefectural waste-sorting standardization enables credible circularity claims that command retail shelf access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Resin Supply Chain Integration | Backward integration into recycled polymer compound formulation secures METI compliance ahead of mandatory thresholds. |
| Artisan Apprenticeship Pipeline Investment | Saga Prefecture kiln technique transmission programs defend quality consistency for heritage-positioned brands. |
| Subscription Platform Launch | Direct-to-consumer plant-and-pot pairing services capture millennial curation preferences in Setagaya and Shibuya wards. |
| Smart Irrigation Convergence | Moisture sensor integration with premium ceramic containers targets tech-forward balcony gardeners. |
| Kansai Corridor Distribution Expansion | Osaka and Kyoto metropolitan penetration addresses white-space demand relative to Kanto saturation. |
Research Methodology
The analysis maps ceramic heritage production, polymer mass-market fabrication, subscription-service platforms, and commercial landscaping supply, each validated through kiln operators, injection-molding plant managers, lifestyle boutique buyers, and home-center category managers. Primary fieldwork combined structured interviews with secondary validation against METI industrial statistics, Ministry of Environment circular economy reports, JIS standards documentation, and prefectural trade association shipment data. Bottom-up unit volume estimates triangulated against top-down consumer expenditure benchmarks.
Assumption sets held METI resource circulation policy trajectories and urban balcony gardening adoption curves fixed while varying natural gas input cost scenarios and bio-resin technology maturation timelines across the projection horizon. Segmentation dimensions encompassed material type, size tier, aesthetic styling, and usage application with regional consumption cluster overlays. CAGRs derived from fitted growth curves calibrated to historical shipment velocities and demographic housing stock projections. Forecast inputs included high-rise residential construction permits and prefectural waste infrastructure investment pipelines.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rate volatility or LNG import pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and consumer behavior stickiness. Material shifts in METI mandate implementation timelines or breakthrough bio-resin cost parity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
North America Floral Gifting Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Wine Racks Market
Home & Garden
Artificial Flowers Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Lawn and Garden Consumables Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Landscaping and Gardening Service Market
Home & Garden
Bird House Market
Home & Garden
Candle Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Global Wind Chime Market
Home & Garden
Artificial Plants Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Global Hot Tub Market
Home & Garden
United States Landscaping Market