
 Gardening Pots Market | 2026-2036
Gardening Pots Market Size, Share, and Industry Trends Forecast 2026-2036
Gardening Pots Market Analysis
Biodegradable polymer formulation is tilting manufacturing priorities across the supply chain as brands respond to landfill diversion mandates. Bloem leverages its domestic injection-molding footprint to control lead times on recycled-content planters. HC Companies anchors its position through exclusive supply agreements with North American big-box retailers. Elho competes from the Netherlands with a fully recyclable polypropylene line certified under stringent EU packaging protocols.
Gardening pots are rigid or semi-rigid containers engineered to hold growing media, drainage systems, and root zones for plants ranging from herbs to specimen trees, typically fabricated through injection molding, rotational molding, or slip-casting depending on material class. Plastic pots command volume leadership due to polypropylene's durability and cost structure, while ceramic planters retain margin concentration among design-conscious home gardeners. Fabric grow bags represent the fastest-expanding material category as aeration benefits and collapsible logistics gain traction with e-commerce retailers shipping to space-constrained consumers.
The EPA regulates volatile organic compound emissions from solvent-based coatings applied to decorative metal planters, pushing finishers toward waterborne alternatives. REACH restricts certain phthalate plasticizers in European-sourced polypropylene, compelling molders to reformulate or source certified virgin resin. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions reshape collection infrastructure and recyclate quality standards for post-consumer pots.
Market Dynamics
The EU Green Deal's circular economy mandates are redirecting manufacturing investment toward recycled and bio-based feedstocks, compressing lead times for virgin polypropylene while elevating certified recyclate premiums across European supply chains.
Growth Catalysts
- REACH plasticizer restrictions:Phthalate limitations in European-sourced polypropylene are compelling molders to reformulate with certified virgin resin, accelerating bio-based polymer R&D pipelines.
- Urban apartment cultivation:Container gardening adoption among balcony and patio dwellers in dense metropolitan zones is sustaining premium planter consumption for space-constrained horticulture.
- Fabric grow bag aeration:E-commerce retailers shipping collapsible logistics solutions are expanding distribution reach to apartment consumers previously excluded from rigid-container supply chains.
Market Restraints
- Recyclate quality inconsistency:Post-consumer pot collection infrastructure under extended producer responsibility frameworks yields contaminated feedstock streams, degrading injection-molding yields.
- Solvent-based coating phase-out:EPA volatile organic compound regulations on decorative metal planters are forcing finishers toward waterborne alternatives with inferior durability profiles.
- Ceramic logistics cost:Weight-to-value ratios for slip-cast planters limit e-commerce penetration against injection-molded polypropylene competitors.
Strategic Opportunities
- German municipal greening programs:Dense urban populations and subsidized vertical garden installations are concentrating premium consumption in city-center retail corridors.
- Rotational molding customization:Small-batch color and texture flexibility is enabling direct-to-consumer channels to displace big-box standardization for design-conscious home gardeners.
- EU packaging protocol certification:Fully recyclable polypropylene lines certified under stringent circular economy standards command shelf-space preferencing in Dutch and Belgian retail networks.
Industry Challenges
- Reformulation timeline compression:REACH-compliant plasticizer substitution requires mold qualification cycles that extend new product introduction schedules beyond traditional seasonal windows.
- Collection infrastructure fragmentation:Inconsistent post-consumer pot sorting standards across municipal waste systems degrade recyclate purity for closed-loop manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gardening Pots Market |
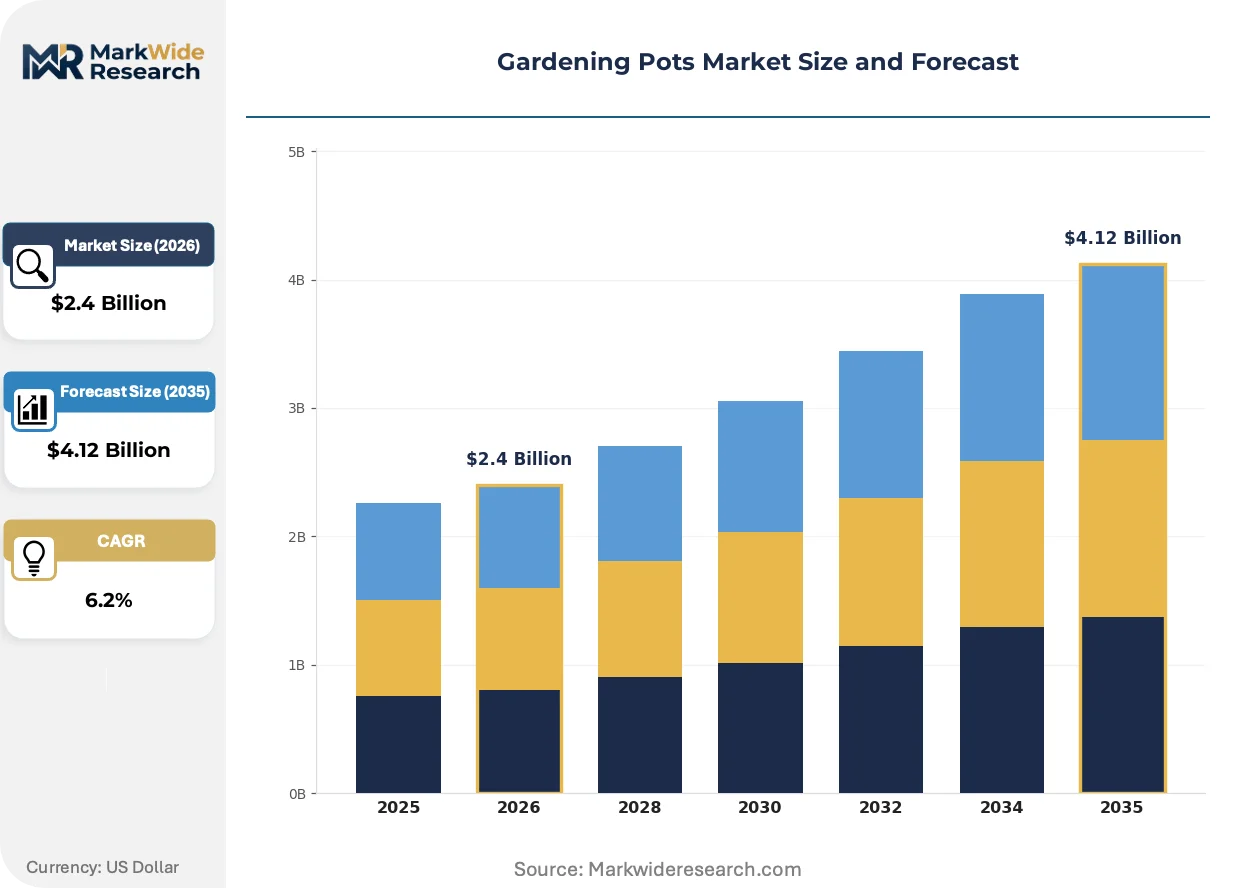
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Pots, Ceramic Pots, Wooden Planters, Fabric Grow Bags End User: Home Gardeners, Professional Landscapers, Nurseries, Retailers Size: Small, Medium, Large, Extra Large Material: Polypropylene, Terracotta, Metal, Biodegradable |
| Companies Covered | Bloem, HC Companies, China Xiamen Roommu Horticulture Co., Ltd., Elho, Pöppelmann TEKU, H Potter, Keter, Landmark Plastic, Lechuza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gardening Pots Market Emerging Trajectories
Material science convergence with regulatory compliance requirements is compressing traditional product development cycles while opening novel feedstock categories previously excluded from horticultural applications.
Biodegradable polymer formulation is hybridizing mechanical performance with end-of-life compostability as brands respond to landfill diversion mandates. Urban composting facilities in the Netherlands and Belgium are accepting certified bio-based planters alongside food waste, creating closed-loop disposal pathways unavailable to conventional polypropylene. Injection molders with in-house compounding capabilities are capturing margin from this technology transition by supplying certified grades to private-label retailers.
REACH restrictions on phthalate plasticizers are forcing European molders toward bio-based alternatives or certified virgin resin sourcing. The industrial consequence is elevated raw material costs for decorative planters relative to utilitarian grades, compressing mid-market positioning. German and French retailers are responding by tiering shelf placement—premium locations reserved for certified-compliant lines, standard placements for grandfathered inventory.
Apartment dwellers are consolidating purchasing decisions through subscription-based plant-and-pot bundles delivered on seasonal cycles. E-commerce specialists are displacing garden-center foot traffic in urban postal codes where storage constraints previously limited bulk buying. This pattern concentrates most visibly in Tokyo and Singapore, where balcony square footage averages under four square meters and collapsible fabric grow bags dominate last-mile logistics.
Gardening Pots Market Segmentation
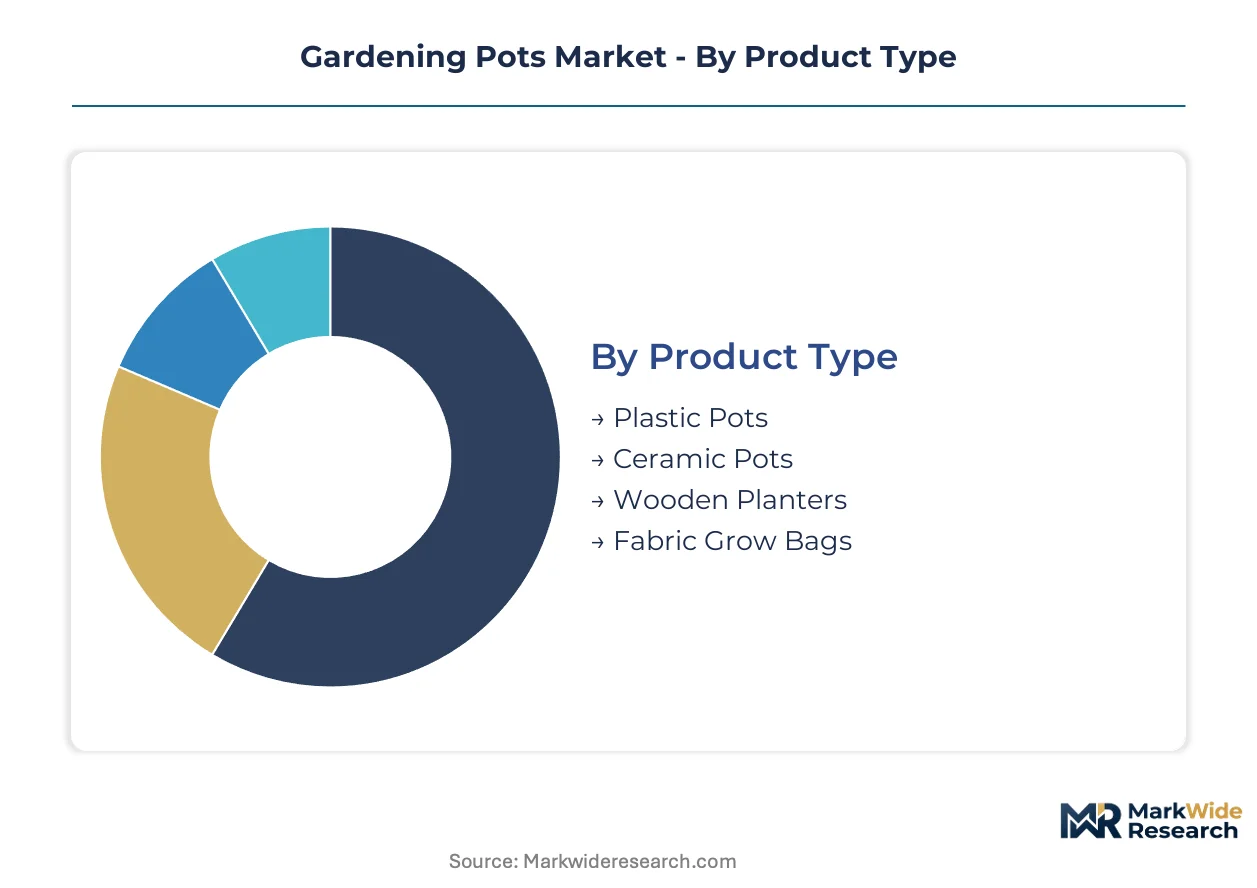
Gardening pot manufacturers configure production lines around material handling characteristics and end-use durability requirements. Segmentation reveals where injection molding economies clash with artisanal ceramic finishing, and which customer channels sustain premium pricing.
Product Type:
Mature categories dominate volume throughput while emerging formats exploit logistics advantages in e-commerce channels.
- Plastic Pots:Injection-molded polypropylene containers with integrated drainage channels and UV stabilizers. German municipal greening programs and Dutch retail networks sustain bulk procurement of standardized sizes for urban balcony installations.
- Fabric Grow Bags:Non-woven polypropylene or felt containers providing root zone aeration and collapsible shipping profiles. E-commerce retailers targeting Tokyo and Singapore apartment dwellers with sub-four-square-meter balconies are expanding distribution reach through parcel-friendly logistics.
- Ceramic Pots:Slip-cast terracotta or glazed stoneware with decorative finishes for design-conscious home gardeners.
- Wooden Planters:Cedar or thermally modified timber constructions for patio and deck installations.
Plastic pots handle the majority of throughput; fabric grow bags are gaining share fastest through e-commerce penetration.
End User:
Customer type determines order fragmentation, with direct-to-consumer channels demanding customization that conflicts with big-box standardization.
- Home Gardeners:Individual consumers purchasing through garden centers, hardware stores, and online marketplaces for balcony, patio, and indoor cultivation. Space constraints in dense metropolitan zones drive demand for collapsible and stackable container solutions.
- Retailers:Big-box chains and specialty stores sourcing private-label and branded inventories with seasonal replenishment cycles. HC Companies anchors supply relationships through exclusive distribution agreements with North American mass merchants.
- Professional Landscapers:Commercial installation contractors requiring bulk quantities with consistent specifications.
- Nurseries:Plant propagation operations utilizing standardized containers for root development and transport.
Retailers consolidate procurement volume; home gardeners are expanding fastest through subscription-based plant-and-pot bundle services.
Size:
Dimensional categories align with plant maturity stages and logistics constraints across distribution channels.
- Small:Containers under 15 centimeters diameter for seedlings, herbs, and succulents. Apartment balcony cultivation in dense European and Asian cities sustains premium consumption of compact formats with integrated saucer systems.
- Large:Containers exceeding 30 centimeters diameter for specimen trees and perennial shrubs. Professional landscapers in German municipal greening programs specify these for vertical garden installations and streetscape plantings.
- Medium:Mid-range containers for established houseplants and patio vegetables.
- Extra Large:Oversized planters for commercial installations and estate gardens.
Small sizes move highest unit volume; large containers are climbing fastest through municipal subsidization programs.
Material:
Feedstock selection reflects regulatory pressure on end-of-life pathways and performance requirements for outdoor exposure.
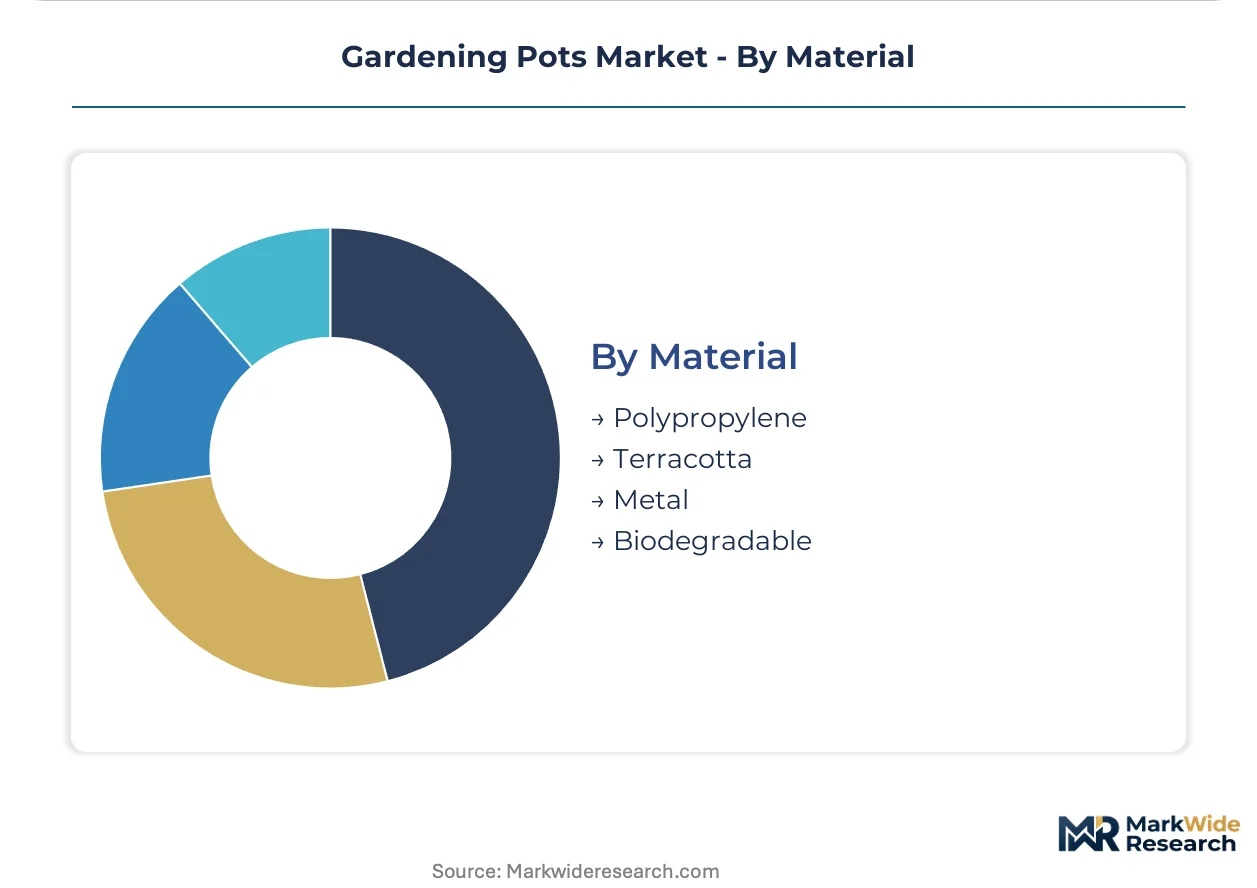
- Polypropylene:Thermoplastic polymer delivering durability, chemical resistance, and injection-molding efficiency. REACH phthalate restrictions are compelling European molders toward certified virgin resin or bio-based alternatives, elevating raw material costs for decorative grades.
- Biodegradable:PLA, PHA, or starch-based polymers engineered for compostable end-of-life. Netherlands and Belgium urban composting facilities accept certified grades alongside food waste, creating closed-loop disposal pathways unavailable to conventional plastics.
- Terracotta:Fired clay with porous walls permitting root zone gas exchange and moisture regulation.
- Metal:Galvanized steel, aluminum, or corten steel with powder-coated or weathering finishes. EPA volatile organic compound regulations on solvent-based coatings are forcing finishers toward waterborne alternatives with modified durability profiles.
Polypropylene commands the installed base; biodegradable formulations are expanding most quickly through EU circular economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Netherlands-based manufacturers export fully recyclable polypropylene lines to German retail networks under EU packaging protocol certification, while Chinese fabricators supply injection-molded containers to North American big-box channels through consolidated maritime freight corridors.
Germany
Municipal greening programs in Berlin and Hamburg subsidize vertical garden installations for dense urban populations, sustaining premium consumption of large-format planters. REACH phthalate restrictions compel molders in North Rhine-Westphalia to reformulate with certified virgin resin or bio-based alternatives. The Stuttgart industrial corridor concentrates rotational molding operations serving direct-to-consumer customization channels.
United States
EPA volatile organic compound regulations on solvent-based coatings push metal finisher operations toward waterborne alternatives across the Midwest manufacturing belt. Domestic injection-molding footprints in Ohio and Indiana control lead times on recycled-content planters for big-box distribution. California's municipal composting infrastructure remains underdeveloped for bio-based pot acceptance, limiting West Coast landfill diversion pathways.
Netherlands
Urban composting facilities in Amsterdam and Rotterdam accept certified bio-based planters alongside food waste, creating closed-loop disposal pathways unavailable to conventional polypropylene. EU Green Deal circular economy mandates redirect manufacturing investment toward recycled feedstocks, compressing lead times for virgin material. The Eindhoven region anchors fully recyclable polypropylene production certified under stringent packaging protocols.
Japan
Tokyo apartment dwellers with sub-four-square-meter balconies drive demand for collapsible fabric grow bags through subscription-based plant-and-pot bundle services. METI guidelines on plastic resource circulation encourage molders to develop lightweight, durable alternatives to ceramic logistics. The Kansai manufacturing cluster around Osaka supplies injection-molded containers optimized for parcel-friendly last-mile delivery.
Belgium
Flemish urban composting networks integrate certified bio-based planters into organic waste streams, supporting manufacturer claims of end-of-life compostability. ECHA enforcement of REACH plasticizer restrictions elevates raw material costs for decorative grades relative to utilitarian lines. The Antwerp port logistics hub facilitates import of Asian-sourced injection-molded containers for redistribution across Benelux retail channels.
Gardening Pots Market Vendor Landscape
On the supply side, the industry is moderately consolidated around injection-molding specialists and rotational molding customizers, with fragmentation persisting among ceramic artisans and fabric grow bag assemblers. Three strategic archetypes dominate: domestic vertically integrated molders controlling resin-to-shelf lead times, European sustainability-certified exporters leveraging regulatory compliance as shelf-space currency, and Asian volume producers capturing standardized container contracts through scale economics. Competitive moves concentrate on exclusive retail distribution agreements and in-house compounding capabilities for certified recyclate grades.
Among Dutch sustainability-certified exporters, Elho occupies a position exemplifying EU packaging protocol compliance as a retail differentiator, while Bloem represents the domestic vertically integrated archetype with captive injection-molding footprints. China Xiamen Roommu Horticulture Co., Ltd. anchors the Asian volume production tier, supplying standardized container formats through consolidated export logistics.
| Leading Market Players |
|---|
| Bloem |
| HC Companies |
| China Xiamen Roommu Horticulture Co., Ltd. |
| Elho |
| Pöppelmann TEKU |
| H Potter |
| Keter |
| Landmark Plastic |
| Lechuza |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European injection-molding facilities is compressing lead times for virgin polypropylene while elevating certified recyclate premiums, forcing molders to pass feedstock volatility through to big-box procurement contracts and direct-to-consumer channels alike.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the gardening pots market. Premium tiers capture certification-compliant polypropylene and bio-based formulations under EU Green Deal mandates, while standard tiers absorb REACH-driven reformulation costs and economy tiers compete on virgin resin scale from Asian volume producers. Cost compression in mid-market decorative grades is intensifying because REACH phthalate restrictions elevate raw material expenses relative to utilitarian lines. Retailers consolidate procurement volume and exhibit lowest price sensitivity, whereas individual home gardeners purchasing through subscription bundles demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculations for injection-molded container sourcing. Manufacturing concentrates in China, the Netherlands, and Germany, with Chinese fabricators supplying standardized formats through consolidated maritime freight corridors and Dutch producers exporting certified recyclable lines to German retail networks. Raw material sourcing rests on polypropylene resin, bio-based polymer feedstocks, and ceramic clay deposits. Distribution runs through exclusive big-box agreements, direct-to-consumer e-commerce platforms, and municipal procurement channels serving urban greening programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among North American big-box retailers through exclusive supply agreements, fragmenting negotiating leverage for mid-tier molders and compressing margin capture across standard container formats.
For Market Incumbents: Entrench shelf-space positioning through in-house compounding capabilities for certified recyclate grades and backward integration into bio-based polymer R&D pipelines. Fabric grow bag entrants from Asian e-commerce specialists threaten rigid-container market share in space-constrained urban segments. Defensive consolidation via rotational molding customization for direct-to-consumer channels counters big-box standardization pressure.
For New Entrants and Emerging Players: Build out subscription-based plant-and-pot bundle services targeting Tokyo and Singapore apartment dwellers with sub-four-square-meter balconies, the most penetrable white-space segment. Municipal greening programs in German city centers offer second entry path through large-format specification contracts. Go-to-market execution should leverage collapsible logistics and parcel-friendly last-mile delivery partnerships with regional e-commerce platforms.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biodegradable polymer formulation as compounding technology matures and batch scales expand. Long-term viability favors molders with captive resin qualification capabilities and EU packaging protocol certification infrastructure. Acquisition targets should display in-house rotational molding flexibility for small-batch customization. Signal to monitor: municipal composting infrastructure buildout rates in Netherlands-adjacent markets indicating closed-loop disposal pathway expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polymer Compounding | Captures margin from EU Green Deal circular economy feedstock transitions. |
| Rotational Molding Customization Capability | Enables direct-to-consumer color and texture flexibility displacing big-box standardization. |
| EU Packaging Protocol Certification | Commands shelf-space preferencing in Dutch and Belgian retail networks under stringent standards. |
| Exclusive Big-box Distribution Agreement | Locks in volume throughput for standardized injection-molded containers across North American mass merchants. |
| Subscription Bundle Service Launch | Consolidates urban apartment purchasing decisions through seasonal plant-and-pot delivery cycles. |
Methodological Framework
Operator-level perspectives from injection-molding plant managers, big-box category buyers, municipal procurement officers, bio-based polymer R&D directors, and e-commerce logistics specialists anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, EU ECHA regulatory filings, EPA coating emission records, and municipal greening program budgets. Bottom-up unit economics across material grades, sizes, and end-use channels triangulated against top-down market sizing from production capacity assessments and retail audit data.
Scenario-bracketing framed analytical outputs across conservative, baseline, and expansion trajectories throughout the forecast period. Segmentation dimensions modeled include material class, product type, end-user channel, size category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year market estimates, incorporating feedstock cost trajectories, REACH compliance timeline assumptions, and e-commerce penetration rates for fabric grow bag formats.
Stress conditions across polypropylene price volatility, REACH enforcement intensity, and municipal composting infrastructure buildout were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory acceleration or feedstock technology breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Residential Snow Blower Market
Home & Garden
US Garden Planter Market
Home & Garden
Artificial Plants Market
Home & Garden
United States Lawn Care Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Christmas Decorations Market
Home & Garden
United States Landscaping Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
Aquarium Decor Market
Home & Garden
Incense Market
Home & Garden
Global Hot Tub Market