
 Global Hot Tub Market | 2026-2036
Global Hot Tub Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hot Tub Market Analysis
Aftermarket service revenue is tilting toward water-care automation and IoT-enabled diagnostics as manufacturers seek recurring income beyond unit sales. Jacuzzi Brands LLC leverages its dealer network to control replacement part flows. Master Spas anchors its position through captive supply of proprietary jet systems. Watkins Wellness competes on R&D intensity in energy-efficient heating technology.
A hot tub is a thermostatically controlled vessel holding 200–1,000 gallons of water, circulated through hydrotherapy jets and maintained by filtration, heating, and chemical treatment systems designed for relaxation, muscle recovery, and hydrothermal therapy. Portable and freestanding units dominate residential channels due to lower installation barriers and relocation flexibility, while acrylic shells command premium positioning for durability and surface finish quality. In-ground installations retain hospitality preference where property integration and aesthetic permanence drive specification decisions.
The EPA sets energy conservation standards under its appliance program, while the EU F-Gas Regulation restricts refrigerants in heat pump systems and REACH governs chemical emissions from shell materials. The CEA in India mandates electrical safety certifications for imported spa equipment, affecting market access timelines. Stakeholders must monitor evolving efficiency thresholds and chemical compliance as certification requirements fragment across export destinations.
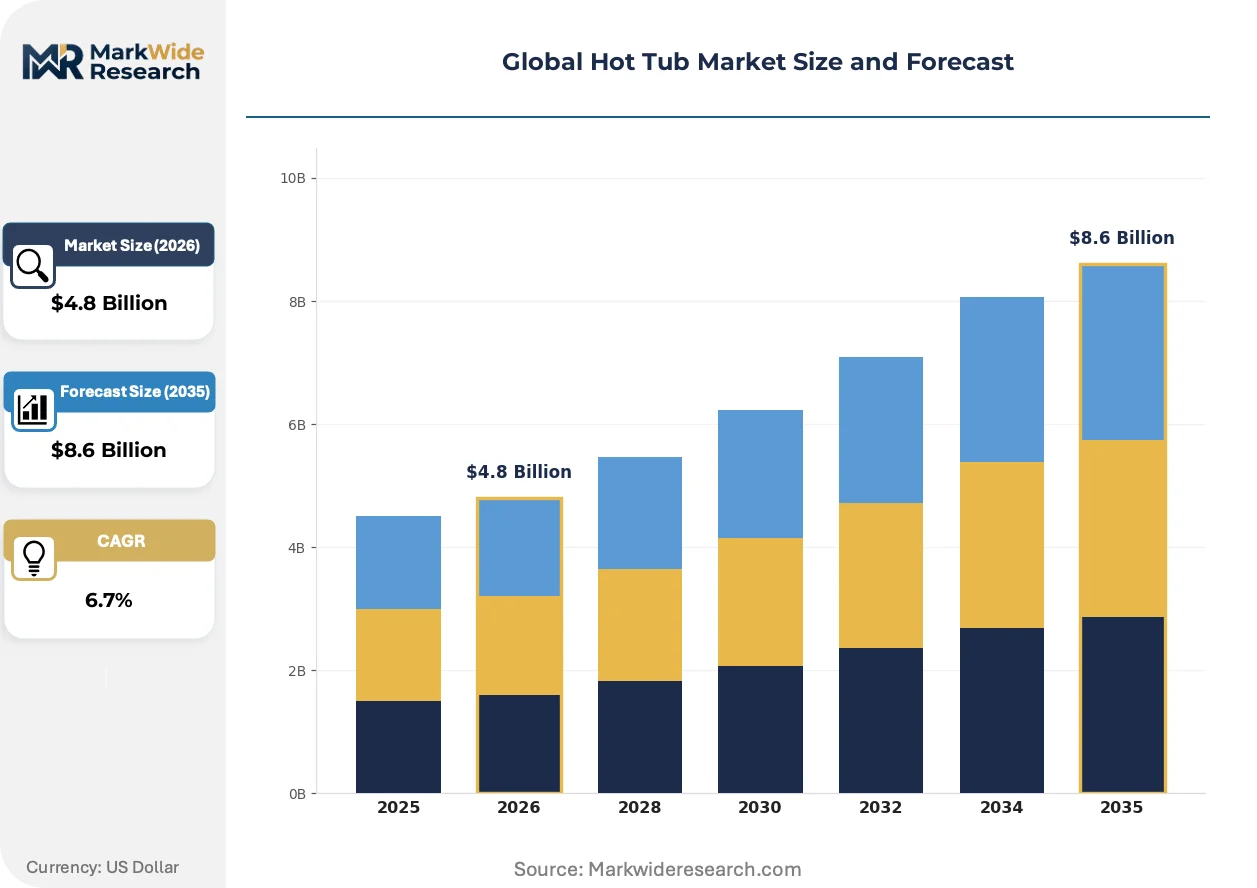
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options for heat pump spa systems while wellness tourism operators accelerate specification of hydrotherapy amenities, creating simultaneous pull and push forces across supply chains.
Growth Catalysts
- REACH chemical compliance:Shell material standards in Europe are filtering out low-grade acrylic suppliers, concentrating procurement among certified manufacturers with verified emission profiles.
- Portable unit flexibility:Residential buyers in second-home markets favor freestanding installations that relocate without construction, expanding addressable demand beyond permanent pool owners.
- IoT diagnostics penetration:Water-care automation systems generate recurring service revenue streams that extend manufacturer relationships beyond initial equipment transactions.
Market Restraints
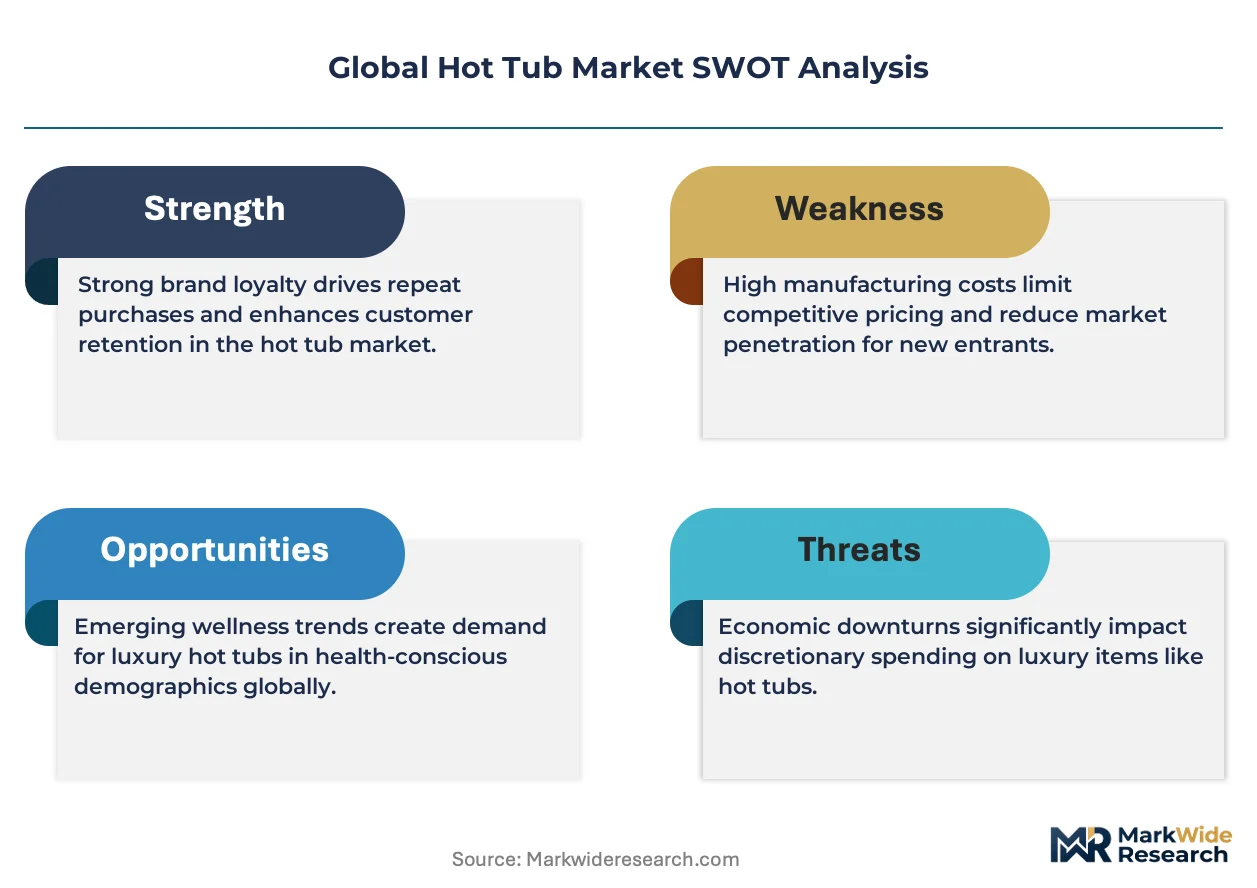
- Acrylic resin price volatility:Shell production costs fluctuate with petrochemical feedstock exposure, compressing margin stability for mid-tier suppliers without long-term supply agreements.
- Heat pump refrigerant restrictions:The EU F-Gas Regulation limits hydrofluorocarbon options, forcing R&D redirection toward CO2 or propane alternatives with higher engineering complexity.
- Above-ground substitute threat:Inflatable cold plunge vessels and recovery-focused alternatives capture budget-conscious wellness consumers seeking hydrotherapy without permanent installation.
Strategic Opportunities
- India electrical safety certification:CEA import mandates create first-mover advantage for manufacturers establishing compliant supply chains ahead of competitor market entry timelines.
- Hospitality specification channel:Luxury property developers integrate hydrotherapy amenities as standard wellness infrastructure, opening direct specification relationships bypassing retail distribution.
- Solar-thermal convergence:Hybrid heating systems combining photovoltaic generation with thermal storage reduce operational energy costs for high-usage commercial installations.
Industry Challenges
- EPA appliance efficiency certification:Evolving energy conservation standards require continuous product retesting, extending redesign cycles and compressing launch windows.
- Dealer network service capability:Water chemistry automation and connected diagnostics demand technician retraining, creating skills gaps in legacy distribution channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hot Tub Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Portable, Freestanding, In-Ground Material: Acrylic, Wood, Fiberglass, Steel Installation Type: Indoor, Outdoor, Semi-Embedded, Embedded End User: Residential, Commercial, Hospitality, Wellness Centers |
| Companies Covered | Master Spas, Bestway, Jacuzzi Brands LLC, Marquis Spas, Coast Spas Manufacturing, Watkins Wellness, Canadian Spa Company, Dimension One Spas, Bullfrog International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hot Tub Market Emerging Trajectories
Product architecture is fragmenting across energy source hybridization, chemical automation, and service revenue unbundling as manufacturers seek differentiation beyond shell aesthetics.
Heat pump technology is hybridizing with traditional electric resistance heating to optimize energy consumption across variable climate conditions. Hospitality operators in Nordic markets are specifying these dual-source systems to maintain operational cost predictability. The technology is hybridizing equipment categories, compressing distinctions between residential and commercial product lines.
REACH chemical emission standards are tightening testing protocols for acrylic shell polymers and adhesive compounds used in structural bonding. European manufacturers are accelerating material substitution programs to maintain CE marking eligibility. Portable spa categories face accelerated compliance timelines compared to in-ground installations with longer replacement cycles.
Subscription water chemistry management is displacing traditional chemical retail purchases among high-usage residential owners. IoT-enabled monitoring systems automatically dispense sanitizers and pH balancers, capturing recurring revenue from previously transactional chemical sales. This pattern concentrates in Sun Belt states with year-round operation and elevated maintenance frequency.
Global Hot Tub Market Segmentation
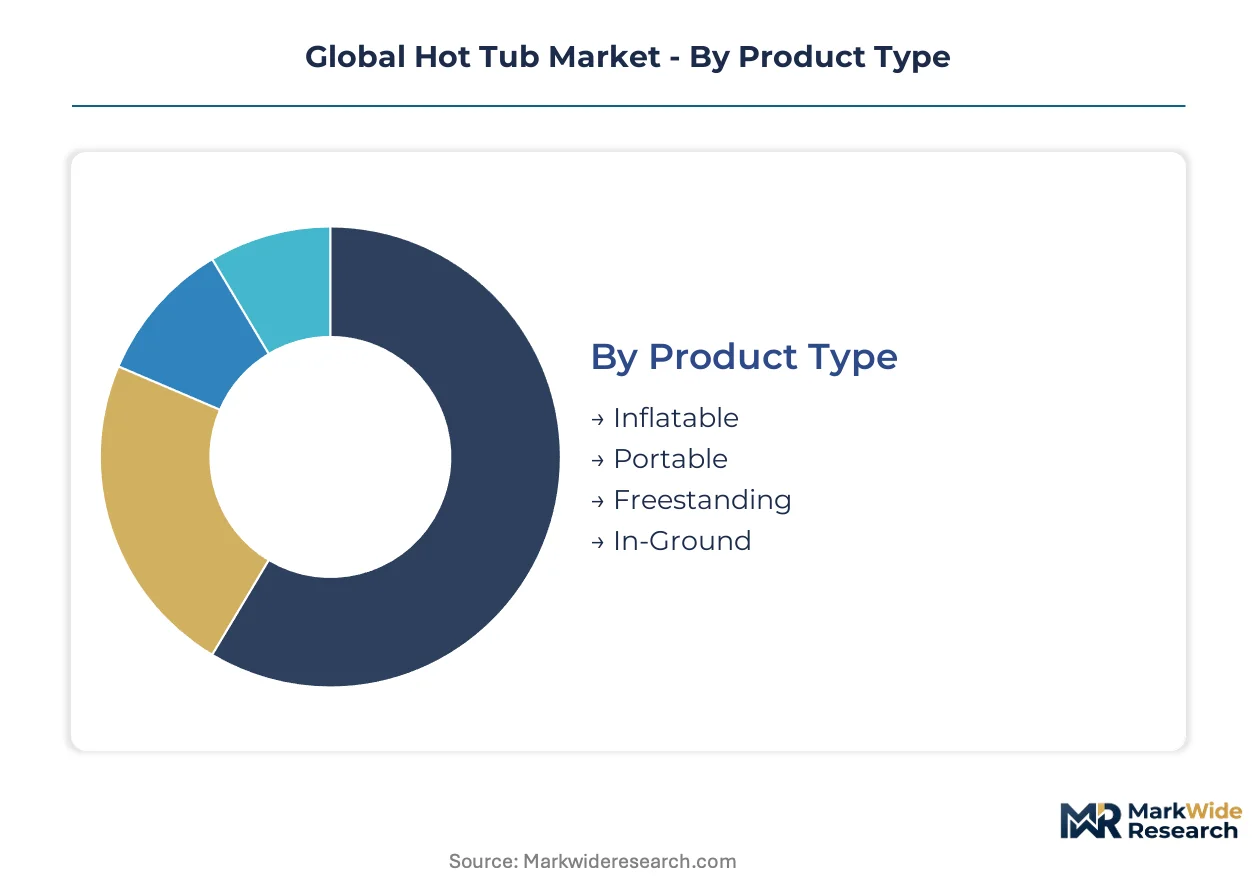
Hot tub segmentation reveals divergent service economics across installation permanence and usage intensity. Portable categories generate recurring chemical and parts revenue, while permanent hospitality installations demand specialized maintenance contracts.
Product Type:
After-sales-service intensity varies sharply across mobility tiers, with permanent installations locking in multi-year maintenance agreements and portable units driving replacement part velocity through dealer networks.
- Inflatable:PVC-reinforced air-chamber construction with integrated pump-heater units. Budget-conscious residential buyers in seasonal climates favor these for storage flexibility, though shorter lifespans compress total ownership economics.
- Portable:Self-contained acrylic or roto-molded shells with plug-and-play electrical connections. Sun Belt second-home owners drive demand for relocation flexibility without construction permits.
- Freestanding:Premium acrylic shells on integrated skirting systems with hardcover integration.
- In-Ground:Custom concrete or gunite vessels with masonry finishes and permanent plumbing.
By volume, Portable leads. By growth pace, Inflatable is ahead.
Material:
Cost tier stratification separates premium shell suppliers from commodity alternatives, with REACH-compliant acrylic commanding procurement premiums in European specification channels.
- Acrylic:Cross-linked polymer sheets thermoformed over ABS backing, offering UV stability and repairable surface damage. REACH emission testing is filtering out uncertified Asian suppliers, concentrating European procurement among verified manufacturers.
- Wood:Cedar or redwood stave construction with traditional joinery. Nordic wellness retreat operators specify these for aesthetic authenticity despite elevated maintenance schedules.
- Fiberglass:Gelcoat-surfaced composite shells with uniform wall thickness.
- Steel:Powder-coated metal frames supporting vinyl liner systems.
By installed base, Acrylic dominates. By specification momentum in hospitality, Wood is climbing fastest.
Installation Type:
Application context determines infrastructure requirements, with embedded systems demanding architectural coordination and indoor installations requiring vapor barrier and ventilation engineering.
- Indoor:Climate-controlled environments with humidity management and structural floor loading. Urban residential retrofits in cold-climate cities concentrate demand where outdoor operation is impractical.
- Outdoor:Exposed installations with weather-resistant cabinetry and thermal covers. Suburban US markets with dedicated patio infrastructure represent core volume.
- Semi-Embedded:Partial deck integration with retained service access.
- Embedded:Full architectural integration with surrounding hardscaping.
By unit shipments, Outdoor leads. By project value per installation, Embedded is expanding most quickly.
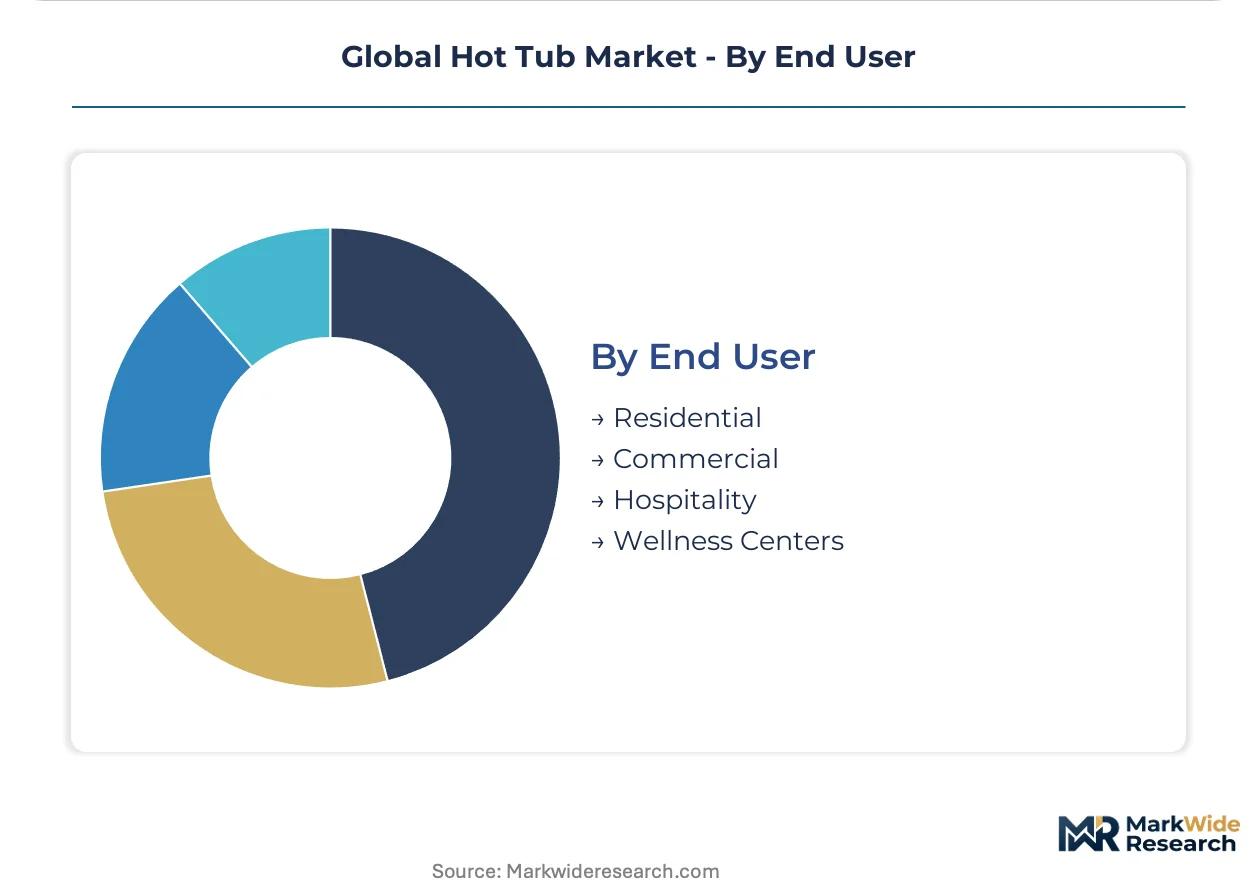
End User:
Customer type dictates purchasing cadence and specification authority, with hospitality procurement bypassing retail channels through direct manufacturer relationships.
- Residential:Individual owners purchasing through dealer networks or direct-to-consumer channels. Sun Belt states with elevated second-home density generate replacement cycle concentration.
- Commercial:Multi-unit operators including apartment complexes and fitness clubs. High-usage patterns drive accelerated component wear and service contract attach rates.
- Hospitality:Luxury property developers integrating hydrotherapy as standard wellness infrastructure.
- Wellness Centers:Dedicated hydrotherapy facilities with clinical positioning.
By absolute units, Residential leads. By specification value and margin capture, Hospitality is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in hot tub procurement varies sharply across geographies, with Sun Belt second-home owners in the United States absorbing premium acrylic shells while European buyers face REACH-driven cost compression and budget-conscious Asian markets gravitate toward inflatable alternatives.
United States
Second-home density across Florida, Arizona, and Texas drives replacement cycles for portable acrylic units with plug-and-play electrical connections. The EPA's appliance efficiency program mandates continuous energy conservation standard updates, forcing manufacturers into retesting protocols. Dealer networks in Phoenix and Orlando concentrate service revenue from IoT-enabled water chemistry automation systems.
Germany
Nordic wellness retreat operators specify cedar and redwood stave construction for aesthetic authenticity despite elevated maintenance schedules. The EU F-Gas Regulation restricts hydrofluorocarbon refrigerant options for heat pump spa systems, redirecting R&D toward CO2 alternatives. Manufacturing clusters in Bavaria concentrate REACH-compliant acrylic shell production for export specification channels.
China
Domestic demand concentrates in tier-one cities where urban residential retrofits favor indoor climate-controlled installations with humidity management infrastructure. GB standards and MIIT oversight govern electrical safety certifications for spa equipment imports. Yangtze River Delta manufacturing zones supply PVC-reinforced inflatable units for seasonal export markets.
India
Luxury hospitality developers in Mumbai and Delhi-NCR integrate hydrotherapy amenities as standard wellness infrastructure, bypassing retail distribution through direct manufacturer relationships. The CEA mandates electrical safety certifications for imported spa equipment, extending market access timelines for non-compliant suppliers. Western India commercial clusters drive specification value for embedded architectural installations.
Australia
Suburban markets with dedicated patio infrastructure represent core volume for outdoor weather-resistant cabinetry with thermal covers. The TGA and national electrical safety frameworks regulate equipment import compliance. New South Wales and Queensland concentrate year-round operation patterns that elevate water-care automation attach rates among high-usage residential owners.
Global Hot Tub Market Vendor Landscape
Capability concentration sits with premium-tier specialists commanding specification channels; scale advantage sits with volume manufacturers serving mass-market portable categories. The vendor base stratifies across three tiers: heritage brands with dealer network control, integrated manufacturers with captive component supply, and contract assemblers serving private-label retail. Two dominant competitive moves define current positioning: backward integration into proprietary jet and heating systems, and geographic expansion through direct specification relationships with hospitality developers.
Within the heritage-brand tier, Jacuzzi Brands LLC and Watkins Wellness exemplify divergent strategic anchors. Jacuzzi leverages its namesake recognition and dealer network infrastructure to control replacement part flows and service revenue capture. Watkins occupies a position defined by R&D intensity in energy-efficient heating technology, competing on product performance rather than distribution scale. Master Spas represents the integrated-manufacturer archetype, with captive supply of proprietary jet systems insulating margin structure from component cost volatility. These three companies collectively illustrate the market's competitive fault lines: brand equity versus technical differentiation versus vertical manufacturing control.
| Leading Market Players |
|---|
| Master Spas |
| Bestway |
| Jacuzzi Brands LLC |
| Marquis Spas |
| Coast Spas Manufacturing |
| Watkins Wellness |
| Canadian Spa Company |
| Dimension One Spas |
| Bullfrog International |
| Others |
Supply Flow & Price Mechanics
Acrylic resin price volatility, tethered to petrochemical feedstock exposure, compresses margin stability for mid-tier suppliers while simultaneously determining the three-tier pricing structure across premium, standard, and economy levels. REACH chemical compliance in Europe and EPA efficiency mandates in the United States force dual certification investments that widen price spreads between verified manufacturers and uncertified competitors.
Pricing Analysis
After-sales service revenue from IoT-enabled water chemistry automation drives lifetime value capture beyond initial unit transactions. Pricing stratifies across premium, standard, and economy tiers based on shell material certification grade and captive jet system integration. Cost compression in the inflatable segment intensifies because PVC-reinforced air-chamber construction faces commodity input pressure. Budget-conscious seasonal buyers in North America exhibit highest price sensitivity, while hospitality developers in India absorb premium positioning for embedded architectural installations.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta facilities producing PVC-reinforced inflatable units and Bavarian clusters handling REACH-compliant acrylic shell thermoforming. Geographic supply concentration centers on China, Germany, and the United States. Raw material dependencies draw from petrochemical-derived acrylic resins, ABS backing polymers, and hydrofluorocarbon refrigerants facing EU F-Gas restrictions. Single-source vulnerability runs through certified acrylic suppliers filtered by REACH emission testing. Distribution runs through dealer networks controlling replacement part flows and direct specification relationships with hospitality developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for IoT diagnostics and water chemistry automation constrains service revenue capture across legacy distribution channels. This capability gap separates manufacturers investing in dealer retraining from competitors losing aftermarket attachment.
For Market Incumbents: Harden dealer network service capability through structured technician certification programs addressing connected diagnostics complexity. Deepen backward integration into proprietary heating systems to insulate margin structure from refrigerant R&D redirection costs. Jacuzzi Brands LLC and Watkins Wellness illustrate divergent defensive anchors: channel control versus technical differentiation.
For New Entrants and Emerging Players: Establish a beachhead in India's luxury hospitality specification channel ahead of CEA compliance mandate saturation. Target embedded architectural installations in Mumbai and Delhi-NCR where direct manufacturer relationships bypass retail distribution. Lead with solar-thermal hybrid heating systems to differentiate on operational cost predictability for high-usage commercial operators.
For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant restrictions reshape the acquisition landscape toward manufacturers with CO2 or propane alternative engineering progress. Long-term viability centers on R&D intensity in energy-efficient heating technology and captive component supply. Monitor REACH compliance certification velocity among Asian acrylic suppliers as inflection indicator for procurement concentration shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Certification Program | Addresses technician skills gaps for IoT diagnostics penetration across Sun Belt service territories. |
| Backward Integration into Proprietary Jet Systems | Insulates margin structure from component cost volatility as Master Spas has demonstrated. |
| CEA Pre-Compliance Supply Chain Establishment | Creates first-mover advantage in India's luxury hospitality specification channel ahead of competitors. |
| Solar-Thermal Hybrid Heating Development | Reduces operational energy costs for Nordic hospitality operators facing F-Gas refrigerant restrictions. |
| REACH-Compliant Acrylic Shell Sourcing | Maintains CE marking eligibility as ECHA tightens emission testing protocols for European market access. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hot tub manufacturer R&D directors, dealer network operations managers, hospitality procurement executives, and aftermarket service technicians; and secondary validation against EPA appliance efficiency filings, ECHA REACH substance databases, CEA import certification records, and customs trade data. Bottom-up triangulation across product type, material grade, installation permanence, and end-user intensity dimensions converged with top-down macroeconomic anchoring.
Forecast inputs incorporated energy conservation standard evolution, wellness tourism infrastructure investment patterns, and refrigerant technology transition timelines across the projection horizon. Segmentation modeling spanned product mobility tiers, shell material compliance grades, installation architecture types, and customer purchasing authority levels. CAGRs derived from regression analysis of historical replacement cycles and specification value trajectories, with particular weighting for second-home density correlations and hospitality amenity integration rates.
Sensitivities concentrate around acrylic resin commodity price swings, EU F-Gas Regulation implementation pace, and CEA certification processing delays. Forecasts embed assumptions regarding technician training scalability and IoT platform adoption curves. Quarterly review of REACH substance restriction proposals, EPA efficiency threshold updates, and Indian hospitality development pipeline announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Bird House Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
Artificial Plants Market
Home & Garden
Preserved Flowers Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Automated Blinds and Shades Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
Europe Robotic Lawn Mower Market
Home & Garden
Gardening Pots Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
Landscaping Services Market
Home & Garden
Electric Lawn Mower Market
Home & Garden
Global Motorized and Smart Awnings Market
Home & Garden
North America Flowerpots Market
Home & Garden
Global Wind Chime Market