
 Italy Manufactured Homes Market | 2026-2036
Italy Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Manufactured Homes Market Foresight
Modular bundling of energy systems with structural shells is consolidating buyer preferences around turnkey configurations. RI Group leverages its vertical integration across steel framing and cladding to control cost positioning in multi-section units. PREFAB Srl anchors its competitiveness through specialized wood-based designs targeting alpine and rural zones. MB Modular Buildings differentiates via manufacturing scale that sustains rapid turnaround for developer clients in Northern Italy.
Italy manufactured homes are prefabricated dwelling units produced off-site under controlled factory conditions, typically incorporating steel or timber frames with insulated envelope assemblies meeting seismic and energy performance criteria, then transported and installed on permanent or semi-permanent foundations for residential or commercial occupancy. Wood-framed single-section products dominate volume in mountainous regions where transport constraints limit module dimensions, while steel multi-section configurations capture margin pools from investor buyers seeking durable rental assets. Concrete and composite materials represent faster-growing construction material categories as fire resistance and acoustic standards tighten under updated building codes.
Italy's Ministry of Infrastructure and Transport enforces national technical standards for structural safety and energy efficiency that determine product eligibility for public incentives, while regional authorities in Lombardy and Veneto layer additional zoning requirements that restrict manufactured home placement in urban cores. The EU Green Deal's building renovation targets and Italy's Superbonus framework collectively push manufacturers toward near-zero energy designs to qualify for fiscal support. Stakeholders must monitor whether pending revisions to regional landscape protection laws will open or constrain rural siting opportunities for prefabricated units.
Market Dynamics
Italy's Superbonus 110% fiscal mechanism is redirecting capital flows toward high-efficiency prefabricated structures, compressing traditional construction timelines while elevating energy performance thresholds for residential and hospitality applications.
Growth Catalysts
- Superbonus 110% retrofit framework:Tax credits covering renovation costs accelerate replacement of aging rural housing stock with manufactured units meeting near-zero energy standards.
- Agritourism operators in Tuscany:Agricultural land conversion rules favor manufactured homes for seasonal hospitality, driving cluster development in wine and olive-producing zones.
- Cross-laminated timber systems:Engineered wood products enable taller modular configurations that satisfy alpine seismic requirements while reducing foundation loads.
Market Restraints
- Steel input cost volatility:Fluctuations in European hot-rolled coil prices compress margins for steel-framed multi-section manufacturers serving investor buyers.
- Regional zoning fragmentation:Lombardy and Veneto municipal codes impose inconsistent setback and aesthetic restrictions that delay project approvals.
- Concrete-based site-built alternatives:Traditional masonry construction retains preference among risk-averse rural lenders evaluating collateral value.
Strategic Opportunities
- Emilia-Romagna agritourism expansion:Favorable landscape protection interpretations in this region open siting opportunities for modular hospitality clusters.
- EU Green Deal building renovation targets:Mandatory efficiency upgrades for existing stock create replacement demand compatible with manufactured housing delivery models.
- Turnkey energy-system bundling:Integration of photovoltaic arrays and heat pumps with structural shells differentiates offerings for developer clients seeking single-contractor solutions.
Industry Challenges
- Seismic certification timelines:National Technical Institute for Earthquake Engineering approval processes extend product launch cycles for innovative structural systems.
- Skilled assembly labor scarcity:Shortages of certified crane operators and module-connection specialists constrain installation capacity during peak construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Manufactured Homes Market |
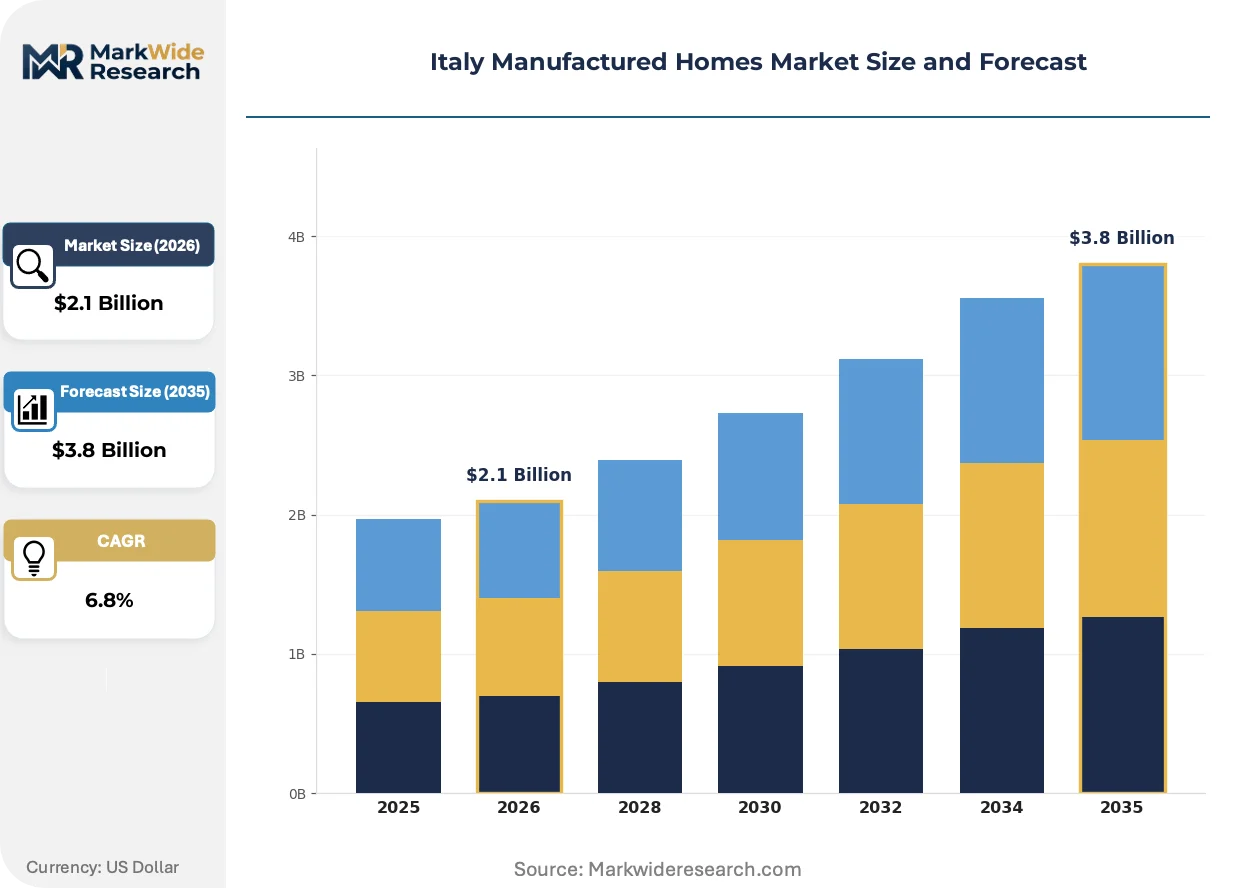
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section, Multi-Section, Modular, Prefabricated Construction Material: Wood, Steel, Concrete, Composite End User: Residential Buyers, Rental Companies, Developers, Investors Sales Channel: Direct Sales, Online Platforms, Distributors, Retail Outlets |
| Companies Covered | RI Group, PREFAB Srl, MB Modular Buildings, LEAPfactory srl, A-FOLD partners, Beneteau Group, Edilsider SpA, Sarda TMC, Corimec Italiana SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Manufactured Homes Market Shifts & Advancements
Digital fabrication and regulatory tightening are converging to transform how manufactured housing is specified, produced, and certified across Italian regions with distinct climatic and seismic profiles.
Building-integrated photovoltaic cladding is rewriting the economics of rural hospitality developments. Alpine lodge operators in Trentino-Alto Adige are specifying factory-applied solar skins that eliminate separate roofing trades. This convergence is compressing total installed cost curves for off-grid capable structures.
EU Green Deal implementation through Italy's National Recovery and Resilience Plan mandates stepped efficiency performance for public incentives. Manufacturers must certify to stricter envelope standards to maintain Superbonus eligibility. Steel-frame producers in Northern Italy are responding with thicker insulation cavities and thermal-bridge-free connection detailing.
Rural property owners are consolidating procurement around design-build contracts that transfer performance risk to manufacturers. Developer clients in Tuscany now specify guaranteed energy outcomes rather than component lists. This behavioral shift privileges vertically integrated suppliers capable of modeling operational costs during pre-construction phases.
Italy Manufactured Homes Market Segmentation
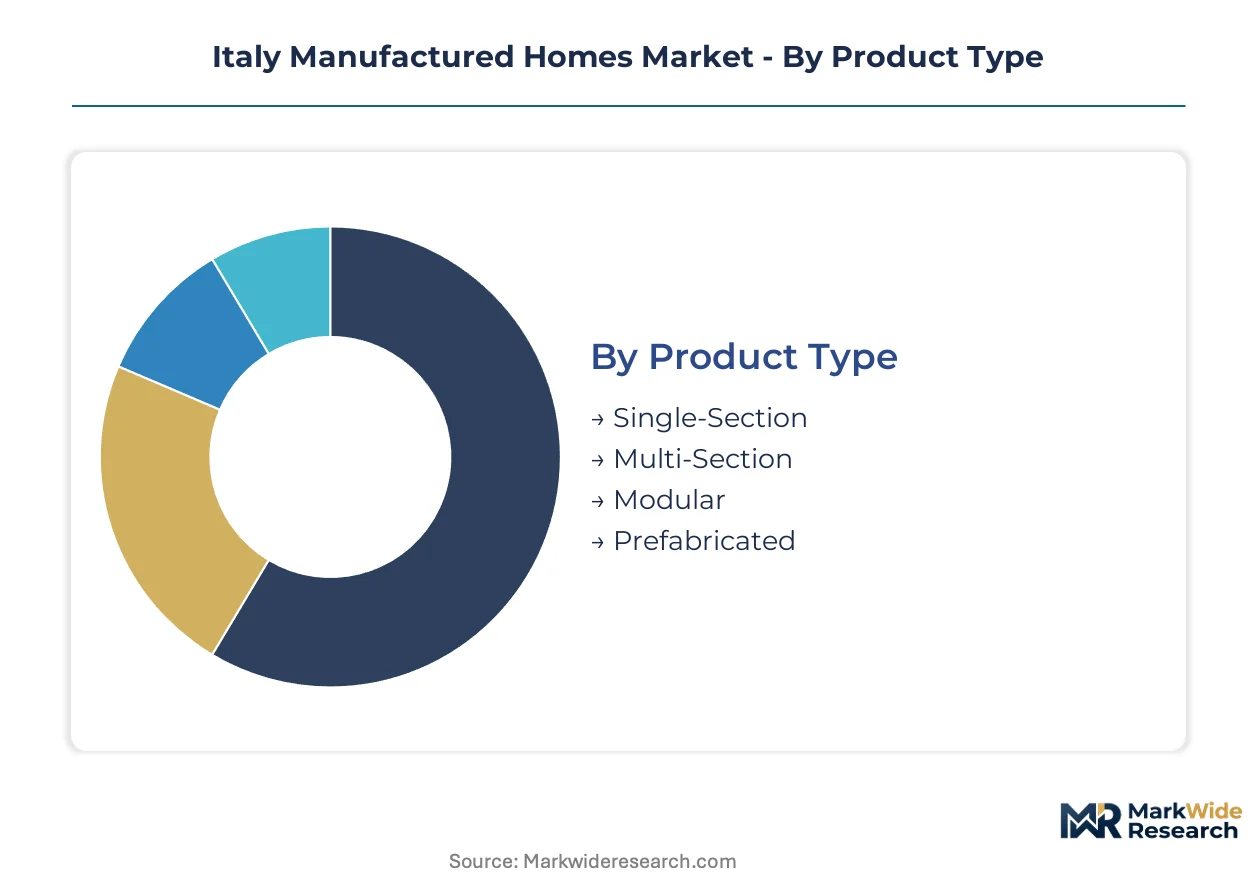
Segmentation in Italy's manufactured homes market reveals how regulatory incentives, regional zoning, and buyer risk profiles fragment demand across product configurations and procurement channels. Understanding these divides clarifies where margin pools concentrate and which structural shifts reshape competitive positioning.
Product Type:
Buyers in this category separate by foundation permanence, transport constraints, and whether they seek turnkey hospitality solutions or customizable residential shells.
- Single-Section:Compact wood-framed units with integrated chassis for road transport, dimensionally constrained by alpine tunnel clearances and rural access roads. Demand clusters in Trentino-Alto Adige and Aosta Valley where seismic isolation requirements favor lighter structural loads and crane-accessible mountain sites limit module size.
- Multi-Section:Steel-framed configurations assembled on-site from two or more modules, enabling larger footprints for agritourism clusters and rental portfolios. Tuscany and Emilia-Romagna investors favor these for wine estate guest accommodations where seasonal occupancy justifies higher capital deployment.
- Modular:Volumetric units with MEP systems pre-installed, specified by developers seeking accelerated construction schedules under Superbonus 110% retrofit timelines.
- Prefabricated:Panelized or hybrid systems offering design flexibility for architect-led residential commissions in Lombardy's design-conscious suburban markets.
Single-Section leads volumes today; Multi-Section is gaining share fastest among hospitality investors.
Construction Material:
Material selection tracks fire code evolution, foundation cost sensitivity, and whether buyers prioritize carbon accounting or collateral liquidity with rural lenders.
- Wood:Cross-laminated timber and glulam frames dominate alpine zones where seismic performance and thermal mass requirements intersect. Cross-laminated timber systems enable taller modular configurations that satisfy seismic requirements while reducing foundation loads in Emilia-Romagna's soft alluvial soils.
- Steel:Cold-formed and hot-rolled framing for multi-section durability in coastal and flood-prone zones where moisture resistance trumps thermal performance. Steel-framed units capture margin pools from investor buyers in Northern Italy seeking durable rental assets with lower maintenance reserves.
- Concrete:Precast or hybrid systems gaining traction where updated building codes tighten fire resistance and acoustic separation standards for multi-unit developments.
- Composite:Fiber-reinforced and engineered polymer panels emerging in experimental builds targeting net-zero operational targets through integrated envelope performance.
Wood dominates current installations; Composite materials are climbing the fastest as efficiency standards tighten.
End User:
Procurement sophistication and performance risk tolerance distinguish buyers, from individual homeowners navigating Superbonus paperwork to institutional investors modeling yield curves.
- Residential Buyers:Owner-occupants purchasing primary or secondary dwellings, concentrated in Veneto and Marche where aging housing stock and energy retrofit incentives align. These buyers favor turnkey solutions that transfer compliance risk to manufacturers.
- Rental Companies:Hospitality operators and seasonal letting specialists scaling modular clusters across agricultural zones with favorable land-use conversions. Tuscany's agritourism sector drives cluster development in wine and olive-producing zones.
- Developers:Project sponsors assembling multi-unit sites under design-build contracts with guaranteed energy outcomes.
- Investors:Yield-focused buyers evaluating manufactured housing as collateral against traditional masonry valuations in risk-averse rural lending markets.
Residential Buyers anchor current demand; Rental Companies show the steepest expansion trajectory as agritourism scales.
Sales Channel:
Channel preference correlates with buyer technical sophistication, project scale, and whether procurement is bundled with installation and certification services.
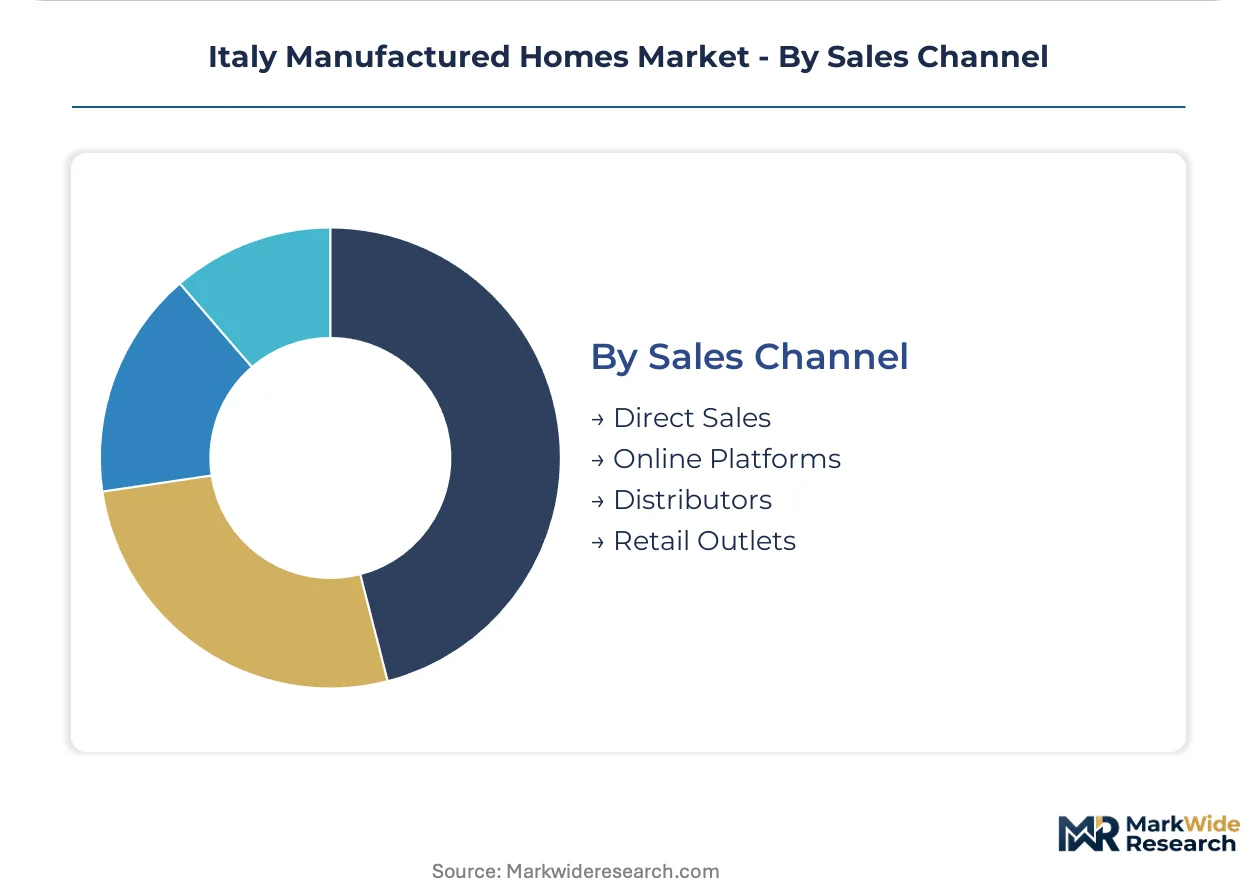
- Direct Sales:Factory-direct relationships for large developers and rental companies negotiating volume terms and guaranteed delivery windows. Northern Italy's developer clients leverage direct channels for rapid turnaround on multi-unit sites.
- Distributors:Regional networks providing local site assessment, foundation coordination, and post-installation service for residential buyers in fragmented municipal markets.
- Online Platforms:Digital configurators and remote quoting tools attracting expatriate buyers and secondary-home purchasers researching from abroad.
- Retail Outlets:Physical showrooms in peri-urban zones where tactile evaluation of finishes and spatial layouts influences owner-occupant decisions.
Distributors capture the largest transaction volume today; Direct Sales is expanding most quickly as developer-scale projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's manufactured housing industry traces its modern origins to post-war reconstruction efforts in the Po Valley, where prefabricated timber systems addressed urgent housing shortages. Regional fragmentation persists today, with distinct demand profiles emerging across Northern industrial zones, Central agricultural regions, and Alpine tourism corridors.
Lombardy
Industrial land scarcity and Milan's commuter belt expansion drive demand for compact modular units on brownfield sites. Regional zoning codes in Monza-Brianza and Bergamo provinces restrict manufactured housing placement near urban cores, pushing development toward peri-urban municipalities. The Milan hinterland hosts a cluster of steel-framing fabricators serving developer clients seeking rapid turnaround on multi-unit residential projects.
Tuscany
Agritourism operators in Chianti and Val d'Orcia wine zones deploy manufactured units for seasonal hospitality under favorable agricultural land conversion rules. The Superbonus 110% incentive accelerates replacement of aging farmworker housing with energy-efficient prefabricated structures. Siena and Florence provinces concentrate design-build contractors bundling structural shells with guaranteed energy performance outcomes.
Emilia-Romagna
Soft alluvial soils in the Po Delta favor lightweight cross-laminated timber systems that reduce foundation loads compared to masonry construction. Regional landscape protection interpretations in Ravenna and Forlì-Cesena provinces open siting opportunities for modular hospitality clusters near coastal wetlands. Bologna's logistics corridor supports just-in-time delivery of volumetric modules to dispersed rural sites.
Veneto
Prosecco vineyard operators in Treviso province adopt single-section wood-framed units for seasonal worker accommodation and tourist rentals. Municipal setback and aesthetic restrictions vary sharply between Padua's dense plains and Belluno's mountain valleys, fragmenting project approval timelines. The Verona-Brescia axis anchors distribution networks supplying finishes and MEP components to regional assembly yards.
Trentino-Alto Adige
Alpine seismic requirements and tunnel clearance constraints limit module dimensions, favoring compact single-section configurations with integrated chassis for road transport. Lodge operators in Bolzano and Trento provinces specify factory-applied building-integrated photovoltaic cladding to eliminate separate roofing trades. Local timber processing clusters supply engineered wood products certified for high-altitude structural performance.
Italy Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across energy certification tiers and project complexity bands. The vendor base spans vertically integrated steel fabricators, specialized timber design houses, and scale-oriented volumetric assemblers. Three archetypes dominate: turnkey solution providers bundling structural shells with MEP systems, component specialists controlling narrow niches in alpine or seismic applications, and developer-facing manufacturers optimizing for rapid multi-unit delivery. Competitive moves concentrate on backward integration into cladding and insulation supply, plus design-build contracting to capture performance risk premiums.
Among Italy-based specialists, RI Group anchors the steel-framing tier through captive production of structural members and envelope assemblies. PREFAB Srl occupies a position within timber-centric design circles, exemplifying how regional material traditions translate into differentiated alpine and rural offerings. MB Modular Buildings represents the scale-driven archetype, sustaining rapid turnaround capacity for Northern Italian developer portfolios. LEAPfactory srl and A-FOLD partners sit within the compact-module segment serving constrained mountain sites.
| Leading Market Players |
|---|
| RI Group |
| PREFAB Srl |
| MB Modular Buildings |
| LEAPfactory srl |
| A-FOLD partners |
| Beneteau Group |
| Edilsider SpA |
| Sarda TMC |
| Corimec Italiana SpA |
| Others |
Supply & Pricing Matrix
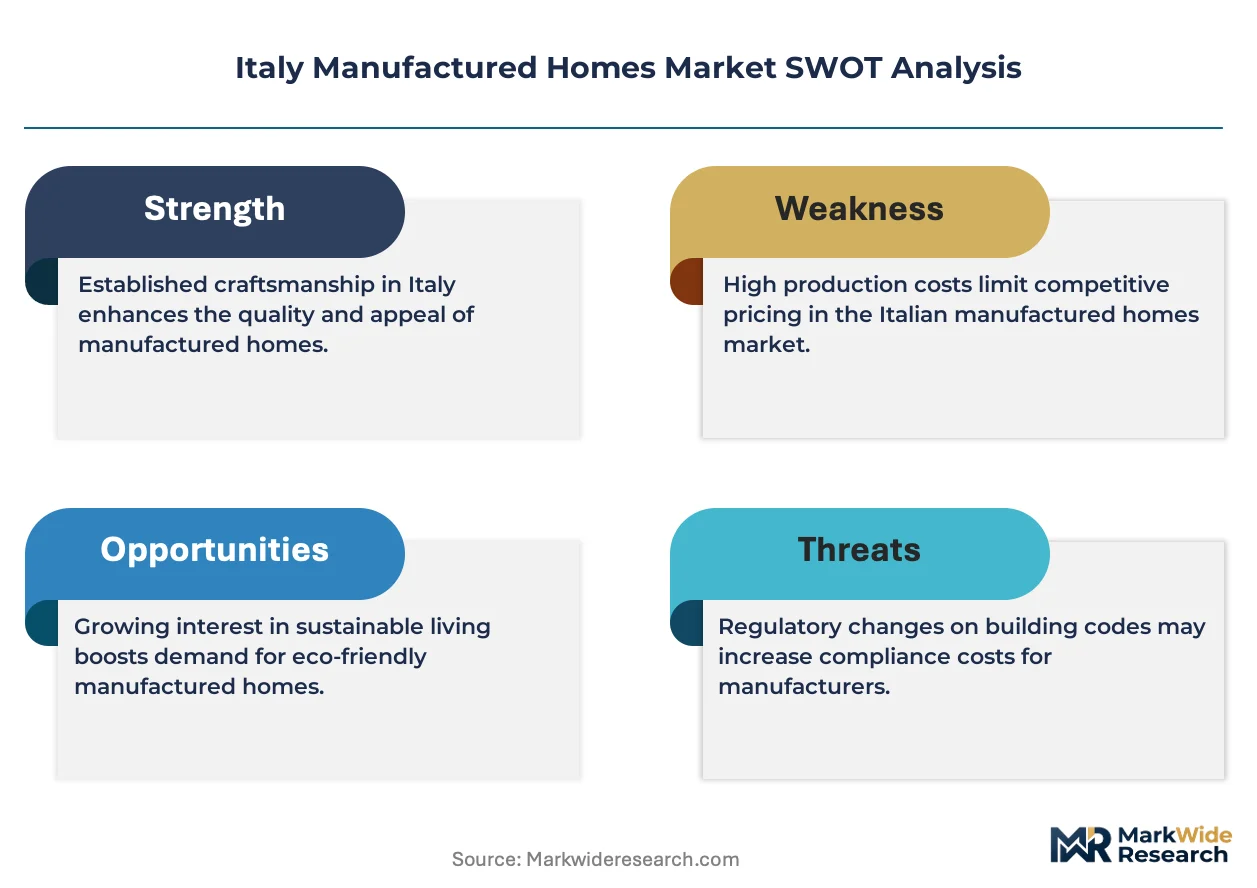
Family-owned mid-cap manufacturers across Northern Italy anchor supply discipline through captive timber processing and long-term steel supply agreements, translating raw material cost predictability into stable project pricing for developer clients while insulating margins from European hot-rolled coil volatility.
Pricing Analysis
Project-based contracting with guaranteed energy outcome clauses dominates procurement for Superbonus-eligible developments, separating premium-tier suppliers certifying to near-zero energy standards from standard-tier competitors meeting baseline code compliance. Price differentiation rests on certification depth and volume scale, with steel-framed multi-section units facing margin compression from input cost swings while wood-framed single-section products maintain pricing stability through regional timber integration. Cost compression in steel-intensive configurations is intensifying because of energy market volatility, with agritourism investors in Tuscany and Emilia-Romagna exhibiting highest price sensitivity and turnkey design-build clients in Lombardy showing lowest.
Supply Chain Analysis
Module refurbishment and redeployment flows remain underdeveloped, constraining circularity despite growing end-of-life unit volumes from early 2000s installations. Manufacturing concentrates in Italy, Austria, and Germany, with engineered timber components drawing from Alpine sawmill clusters and steel structural members sourcing from German and Polish rolling mills. Single-source vulnerability persists in cross-laminated timber certification where Austrian suppliers control seismic-grade supply. Distribution runs through regional distributor networks for residential buyers and direct factory relationships for developer-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Lombardy's stricter urban zoning pushes developer demand toward Emilia-Romagna's permissive rural siting rules, compressing land costs and accelerating approval timelines for equivalent product specifications.
For Market Incumbents: Cement market position through backward integration into engineered wood production and captive supply of building-integrated photovoltaic cladding systems. Steel-framing specialists face substitution pressure from cross-laminated timber systems gaining share in seismic zones, making certification investment in EU Green Deal envelope standards the critical defensive lever for maintaining Superbonus eligibility. For New Entrants and Emerging Players: Seasonal hospitality operators in Marche and Abruzzo represent the most penetrable buyer archetype, with these regions showing agritourism growth without established modular supplier relationships. White-space targets include compact single-section configurations for Prosecco vineyard worker housing and turnkey energy-bundled offerings for first-time agritourism investors lacking technical procurement expertise. A design-build contracting model transferring performance risk to manufacturers offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional timber-frame specialists with underutilized production capacity and unexploited design-build capabilities. Long-term viability over the coming decade hinges on positioning for EU Green Deal building renovation mandates and Superbonus successor mechanisms. The signal to watch is pending revisions to regional landscape protection laws that could expand or contract rural siting opportunities for prefabricated units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Timber | Captive CLT production insulates margins from Austrian supplier concentration and secures seismic-grade certification. |
| Building-Integrated Photovoltaic Certification | Factory-applied solar skins qualify for Superbonus incentives while eliminating separate roofing contractor coordination. |
| Design-Build Contracting Capability | Guaranteed energy outcome contracts capture performance risk premiums from risk-averse agritourism investors. |
| Regional Zoning Intelligence Investment | Specialized compliance teams accelerate project approvals in fragmented municipal markets like Veneto and Lombardy. |
| Cross-Laminated Timber Seismic Certification | National Technical Institute for Earthquake Engineering approval unlocks alpine and soft-soil applications in Trentino and Emilia-Romagna. |
Research Methodology
Direct dialogue with manufactured housing plant managers, agritourism development executives, regional zoning officials, and Superbonus compliance consultants grounded qualitative findings, validated against customs data for engineered timber and steel structural imports, EU Green Deal implementation documents, and National Recovery and Resilience Plan disbursement records. Bottom-up project pipeline analysis triangulated with top-down construction permit data.
Segment-level value and volume trajectories across the analysis window reflect modeled deployment of single-section, multi-section, modular, and prefabricated product types by construction material and end-user category, with CAGRs derived from correlation with Superbonus uptake curves and agritourism investment flows. Forecast inputs incorporated seismic certification timeline assumptions and regional zoning interpretation variance.
Underlying measurement precision varies by segment; modular and multi-section categories with established developer channels carry tighter precision than emerging composite material applications. Forecasts assume continuity of Italy's fiscal incentive framework and EU Green Deal building renovation targets. Practitioners should monitor Superbonus program revisions and regional landscape protection law amendments for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Residential Construction Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
North America Residential Construction Market
Residential Construction
Global Manufactured Homes Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Scandinavia Prefabricated Housing Market
Residential Construction
Global Prefabricated Housing Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
UK Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
US Residential Construction Market