
 Blockchain in Oil and Gas Market | 2026-2036
Blockchain in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain in Oil and Gas Market Insights
Midstream operators are redrawing procurement priorities as upstream exploration companies retreat from blockchain pilot spending. Shell leverages proprietary node architectures to sustain interoperability across North Sea joint ventures. DataGumbo anchors its position through smart contract automation tied to field sensor networks. Equinor competes on hydrocarbon traceability credentials that satisfy EU import certification requirements.
Blockchain in oil and gas deploys cryptographically linked distributed ledgers with consensus mechanisms—typically proof-of-authority or Byzantine fault tolerance—to create immutable records of physical commodity movements, contractual obligations, and emissions data across geographically dispersed extraction, transport, and refining operations. Supply chain transparency applications dominate current deployment value, while consortium blockchain configurations capture the fastest growth as operator coalitions share infrastructure costs and regulatory compliance burdens. Private blockchain deployments retain margin concentration among integrated supermajors seeking captive control over proprietary reservoir and trading data.
The EPA enforces methane emissions reporting under revised Subpart W protocols that reward auditable measurement trails, while FERC's interstate pipeline tariff transparency rules create compliance demand for immutable transaction records. The EU Green Deal's Carbon Border Adjustment Mechanism will soon require verifiable upstream emissions documentation for imported crude and LNG cargoes. Stakeholders must monitor which consensus standards—ISO blockchain frameworks or sector-specific protocols—gain regulator endorsement first, as this determination will shape interoperability investments and market access conditions for platform providers and operators alike.
Market Dynamics
Midstream custody transfer verification demands are compressing deployment timelines for distributed ledger infrastructure as pipeline operators face simultaneous pressure from FERC tariff transparency mandates and EPA methane tracking protocols. The convergence of regulatory audit requirements with sensor-network maturation is forcing infrastructure investment decisions faster than vendor consolidation can stabilize.
Growth Catalysts
- EU Green Deal Carbon Border Adjustment Mechanism:Importers must produce verifiable upstream emissions documentation for crude and LNG cargoes entering European markets, creating compulsory demand for immutable chain-of-custody records.
- Proof-of-authority consensus protocols:Energy-sector consortiums favor permissioned architectures that deliver transaction finality without proof-of-work energy penalties, accelerating deployment across joint venture structures.
- Sensor-to-ledger automation:Field device networks now stream measurement data directly into smart contract triggers, eliminating manual reconciliation delays in hydrocarbon quantity verification.
Market Restraints
- Interoperability protocol fragmentation:Competing standards between ISO blockchain frameworks and sector-specific oil and gas consortia create integration friction for multi-jurisdictional operators.
- Specialized cryptography talent scarcity:The combination of petroleum engineering domain knowledge with distributed systems architecture expertise concentrates in Houston, London, and Singapore hiring markets.
- Legacy SCADA integration costs:Brownfield facilities require substantial capital outlay to bridge decades-old control systems with modern ledger infrastructure without disrupting continuous operations.
Strategic Opportunities
- Brazil pre-salt field developments:ANVISA and environmental regulator requirements for offshore production transparency create first-mover advantage for ledger platforms serving Petrobras-led consortiums.
- Hydrogen carrier traceability:Ammonia and liquid organic hydrogen carrier supply chains demand molecular-level provenance tracking that existing ERP systems cannot provide.
- ISO/TC 307 standards harmonization:Early alignment with emerging international blockchain interoperability frameworks positions platform providers for cross-sector expansion into metals and agriculture commodity tracking.
Industry Challenges
- Smart contract code auditing capacity:The shortage of Solidity and Rust developers with petroleum trading clause expertise delays deployment of complex multi-party settlement logic.
- Key management across joint ventures:Node operator identity verification and private key custody arrangements generate governance disputes among consortium members with unequal equity stakes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain in Oil and Gas Market |
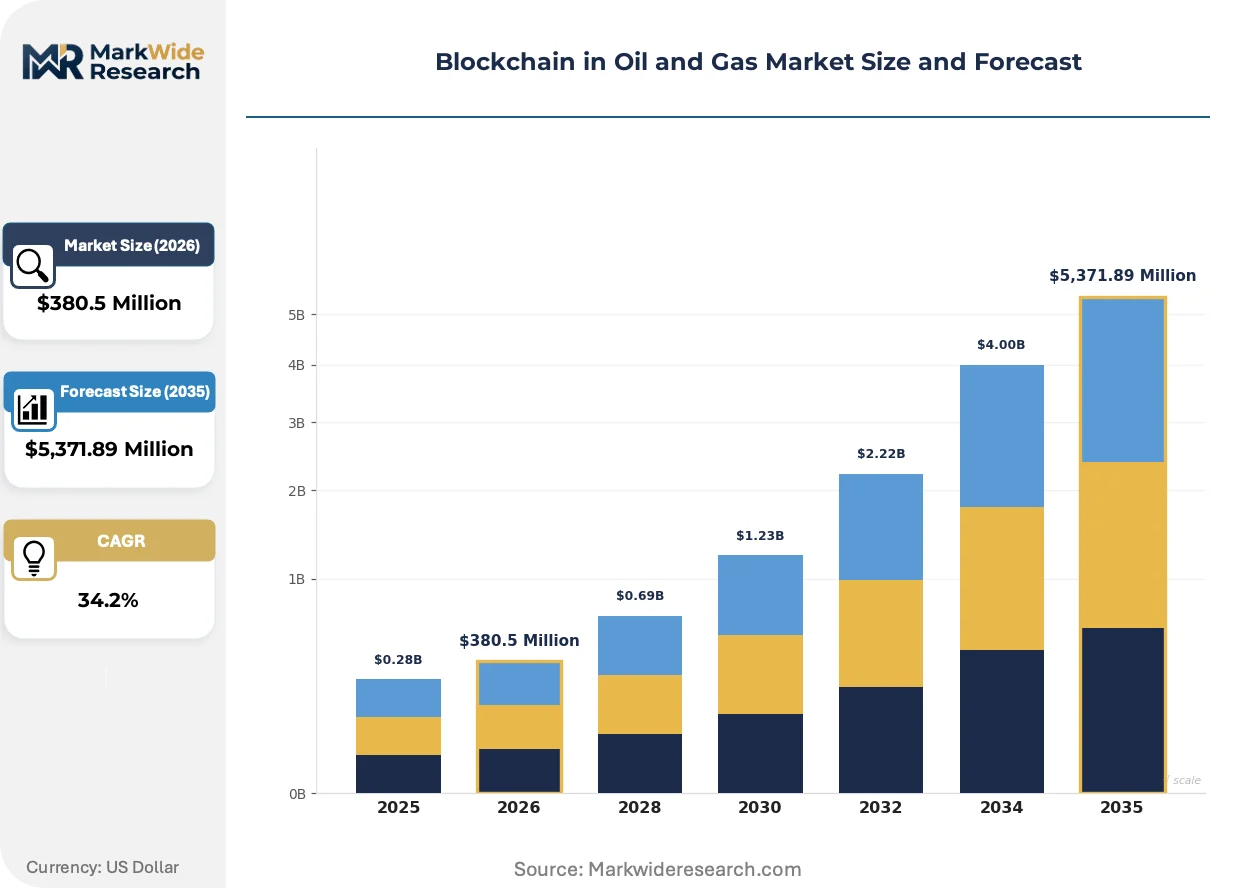
| Market Size in 2026 | $380.5 Million |
| Market Size in 2035 | $5,371.89 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Supply Chain Transparency, Asset Management, Contract Management, Transaction Processing Technology: Private Blockchain, Public Blockchain, Consortium Blockchain, Sidechain End User: Exploration Companies, Production Firms, Midstream Operators, Service Providers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | ExxonMobil, Chevron, ConocoPhillips, Shell, BP, TotalEnergies, Equinor, Eni, DataGumbo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain in Oil and Gas Market Trends and Innovations
Blockchain architectures for hydrocarbon tracking are diverging sharply between permissioned consortium models and captive private deployments, with each path carrying distinct interoperability consequences for multi-operator supply chains.
Consortium blockchain configurations are bifurcating the vendor landscape. Shared infrastructure investments among pipeline operators and terminal owners reduce per-party capital burdens while creating collective governance overhead. Vostok, DataGumbo, and analogous platforms compete to anchor these coalitions. The structural consequence is compressing margins for pure-play software vendors unable to secure anchor operator relationships.
EPA Subpart W methane reporting revisions now mandate auditable measurement trails for pneumatic device emissions and compressor station venting. Operators face enforcement exposure for estimates without sensor-backed documentation. Midstream gatherers in the Permian and Bakken basins are responding fastest, deploying ledger-verified flow measurement to pre-empt regulatory penalties and secure offtake contract premiums.
Buyer concentration among integrated supermajors is reshaping procurement terms for ledger platform subscriptions. Shell, BP, and Equinor now demand source-code escrow and data residency guarantees as standard contract provisions. This shift transfers implementation risk onto vendors while locking smaller operators into standardized configurations they cannot customize. The phenomenon is most visible in North Sea joint ventures where operator unanimity requirements slow technology selection.
Blockchain in Oil and Gas Market Segmentation
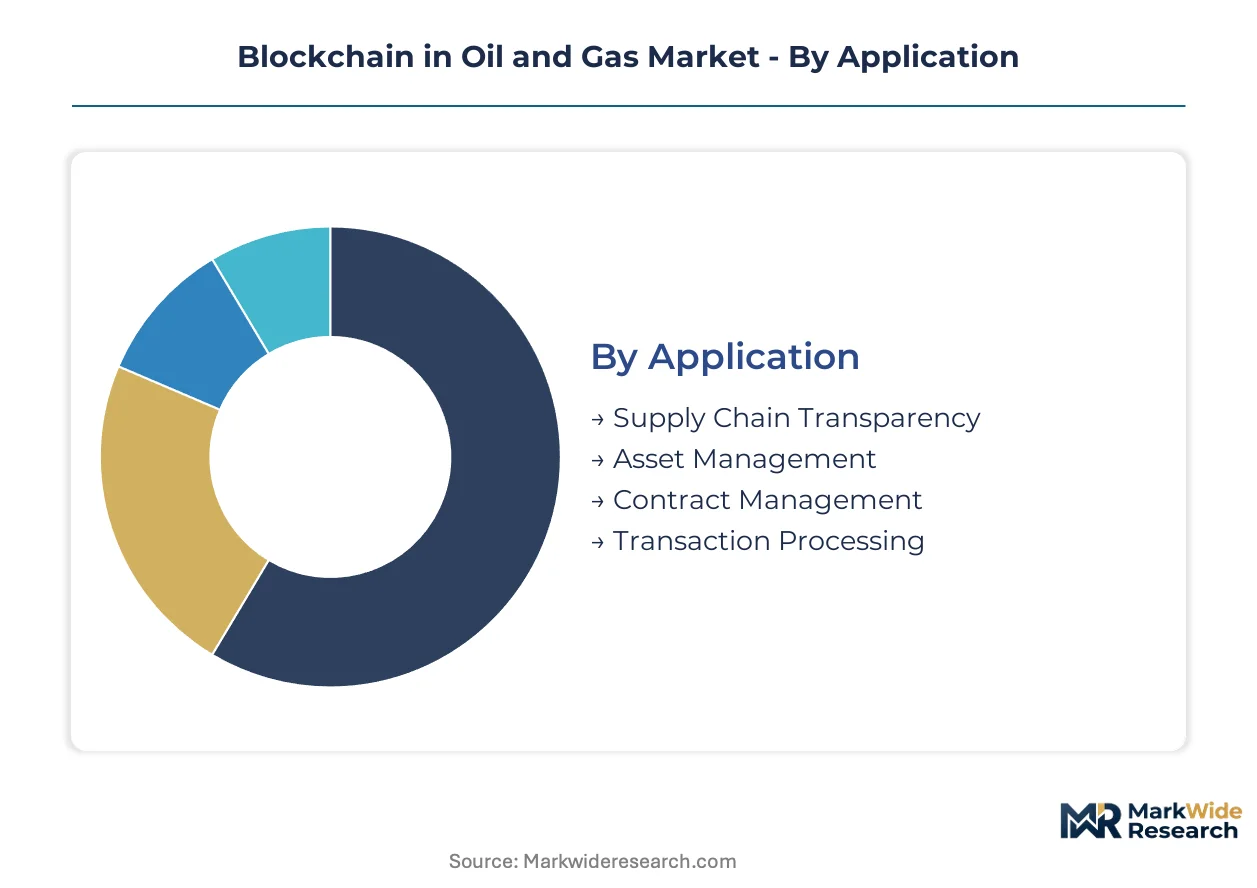
Segmentation in the blockchain oil and gas market reveals how regulatory pressure and infrastructure maturity fragment demand across operator types and deployment models. Procurement patterns diverge sharply between integrated supermajors seeking captive control and consortium members sharing compliance infrastructure costs.
Application:
Supply chain transparency faces intensifying substitution pressure from emerging satellite emissions monitoring and AI-powered audit trails that promise faster verification without distributed ledger overhead.
- Supply Chain Transparency:Distributed ledgers create immutable custody records from wellhead to refinery gate, with EU Carbon Border Adjustment Mechanism documentation requirements driving Permian and North Sea operator deployments. Midstream gatherers in US shale basins leverage sensor-to-ledger automation to satisfy EPA methane tracking mandates.
- Asset Management:Tokenized equipment registries track maintenance histories and warranty status across joint venture boundaries, concentrating demand among North Sea and Brazil pre-salt consortiums where asset handoffs occur frequently.
- Contract Management:Smart contract automation executes payment triggers upon verified delivery milestones.
- Transaction Processing:Settlement finality for physical commodity trades reduces counterparty exposure in volatile crude markets.
Supply chain transparency anchors the volume base while asset management gains share at the steepest rate as equipment digitization accelerates.
Technology:
Cost tier differentiation separates enterprise-grade permissioned architectures from experimental public deployments, with infrastructure ownership models determining governance complexity and capital efficiency.
- Consortium Blockchain:Shared infrastructure investments among pipeline operators and terminal owners distribute capital burdens while creating collective governance overhead, capturing fastest growth as operator coalitions form to meet FERC tariff transparency and EU emissions disclosure mandates.
- Private Blockchain:Captive deployments retain margin concentration among integrated supermajors seeking exclusive control over proprietary reservoir data and trading positions, with Shell and Equinor operating proprietary node architectures.
- Public Blockchain:Open permissionless networks see limited adoption due to energy consumption concerns and transaction finality requirements.
- Sidechain:Auxiliary chains process high-volume sensor data before anchoring to main ledgers for cost efficiency.
Consortium configurations anchor the volume base while private deployments maintain the highest margin concentration.
End User:
Customer type fragmentation reflects divergent regulatory exposure, with midstream operators facing simultaneous EPA and FERC mandates while upstream exploration retreats from pilot spending.
- Midstream Operators:Pipeline and terminal companies deploy distributed ledgers for custody transfer verification under compressed timelines, with Permian and Bakken gatherers responding fastest to EPA Subpart W methane reporting revisions.
- Production Firms:Integrated operators leverage hydrocarbon traceability credentials to satisfy EU import certification requirements and secure offtake premiums.
- Exploration Companies:Upstream drillers reduce blockchain pilot budgets amid capital discipline pressures.
- Service Providers:Oilfield contractors adopt verified work-order records for contract dispute resolution.
Midstream operators anchor the volume base while production firms expand deployment most quickly to capture regulatory compliance premiums.
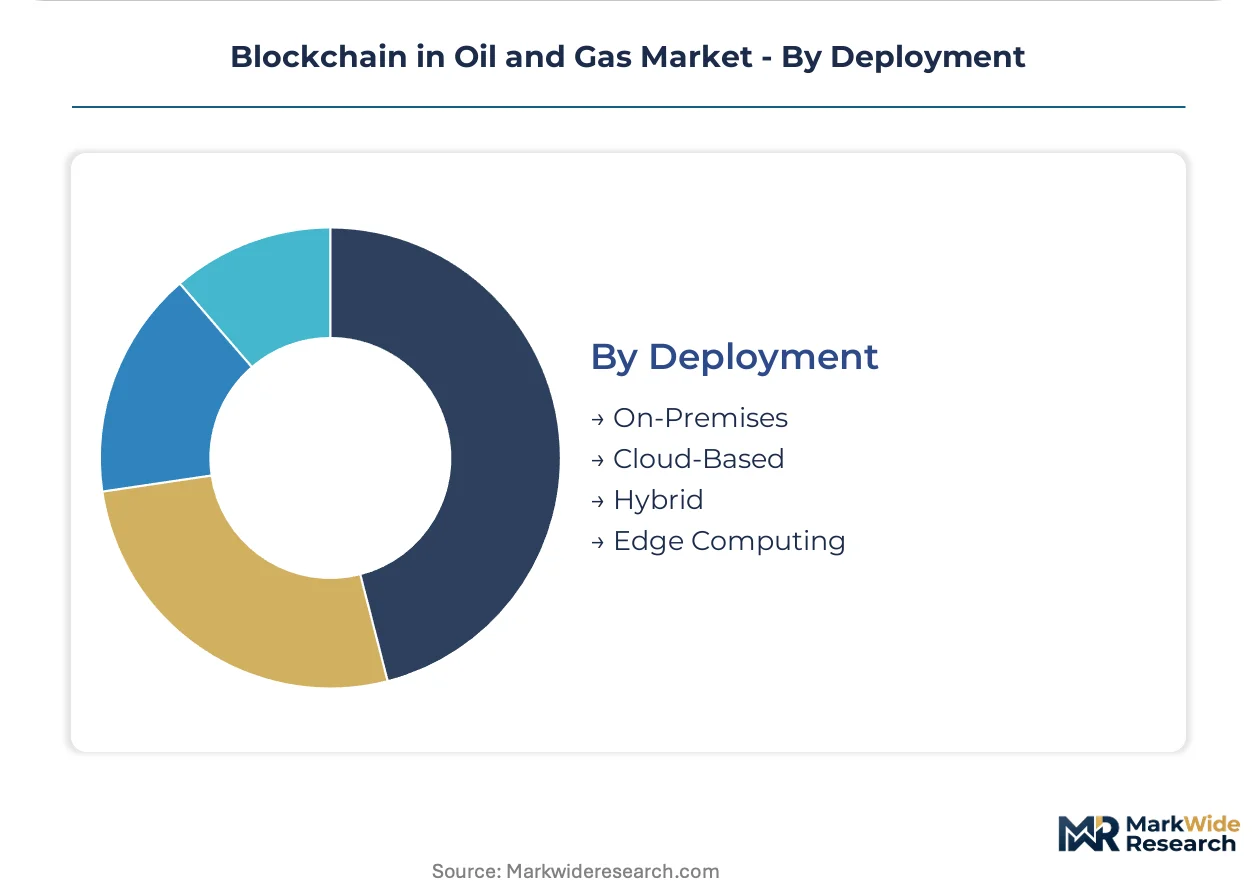
Deployment:
Maturity gradients separate established cloud configurations from emerging edge architectures, with latency requirements and data residency rules shaping infrastructure selection.
- Cloud-Based:Hosted ledger nodes reduce capital expenditure and accelerate deployment for smaller operators lacking dedicated IT infrastructure, dominating among independent midstream gatherers and service providers.
- Hybrid:Split architectures keep sensitive trading data on-premises while leveraging cloud scalability for transaction processing, preferred by supermajors demanding source-code escrow and data residency guarantees.
- On-Premises:Captive server installations satisfy strictest data sovereignty requirements.
- Edge Computing:Field-level ledger nodes enable real-time sensor verification without network latency.
Cloud-based deployment anchors the volume base while hybrid configurations climb the fastest as data residency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor deployment capacity clusters in Houston, London, and Singapore as midstream operators accelerate ledger infrastructure procurement. FERC tariff transparency mandates and EPA methane tracking rules in the United States converge with EU Green Deal disclosure requirements to shape regional demand patterns.
United States
Permian and Bakken basin gatherers deploy sensor-to-ledger automation fastest under EPA Subpart W methane reporting revisions. FERC interstate pipeline tariff transparency rules create compulsory demand for immutable transaction records. Houston anchors vendor development as cryptography talent concentrates with petroleum engineering expertise.
United Kingdom
North Sea joint ventures drive consortium blockchain adoption as operator unanimity requirements slow technology selection. Shell and BP demand source-code escrow and data residency guarantees as standard contract provisions. London serves as the primary European hub for petroleum-distributed systems engineering talent.
Norway
Equinor operates proprietary node architectures to sustain interoperability across North Sea joint ventures. Hydrocarbon traceability credentials satisfy EU import certification requirements and secure offtake premiums. Stavanger and Oslo concentrate development of reservoir-data custody solutions for integrated supermajors.
Germany
Industrial gas consumers prepare for EU Carbon Border Adjustment Mechanism documentation requirements on imported LNG cargoes. REACH compliance frameworks intersect with emissions disclosure mandates to create audit trail demand. Ruhr Valley energy-intensive industries pilot ledger-verified supply chain records.
Brazil
ANVISA and environmental regulator requirements for offshore production transparency create first-mover advantage for ledger platforms serving Petrobras-led consortiums. Pre-salt field developments demand equipment registries tracking maintenance histories across joint venture boundaries. Rio de Janeiro anchors Latin American petroleum blockchain implementation.
Blockchain in Oil and Gas Market Competitive Landscape
Concentration sits with integrated supermajors operating captive private deployments and consortium anchor positions. The vendor landscape bifurcates between pure-play software platforms and operator-backed infrastructure coalitions. Two strategic archetypes dominate: proprietary node architects seeking exclusive data control, and shared-ledger coordinators distributing compliance costs across joint ventures. Competitive moves center on securing anchor operator relationships and establishing governance protocols for multi-party node operations.
Within the integrated supermajor tier, Shell, BP, and Equinor occupy positions that reshape procurement terms through source-code escrow demands and data residency requirements. Among pure-play platform providers, DataGumbo anchors consortium configurations through smart contract automation tied to field sensor networks. These named entities exemplify the structural tension between captive control and shared infrastructure investment that defines vendor selection dynamics across the Permian, North Sea, and Brazil pre-salt developments.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron |
| ConocoPhillips |
| Shell |
| BP |
| TotalEnergies |
| Equinor |
| Eni |
| DataGumbo |
| Others |
Pricing and Supply Chain Analysis
Consortium-scale infrastructure investments among Permian and North Sea operators compress per-party ledger deployment costs while establishing price floors for pure-play platform vendors unable to secure anchor relationships. This scale dynamic concentrates procurement leverage among integrated supermajors demanding source-code escrow and data residency guarantees as standard terms.
Pricing Analysis
Volume-discount tiering structures separate enterprise consortium subscriptions from standalone private deployments, with three-tier pricing stratification across premium, standard, and economy levels based on node count and smart contract complexity. Price differentiation hinges on ISO/TC 307 certification alignment and geographic data residency compliance. Cost compression in mid-tier configurations is intensifying because cloud-hosted alternatives commoditize basic custody-transfer functionality. Independent midstream gatherers exhibit highest price sensitivity, while supermajors prioritize governance control over unit economics.
Supply Chain Analysis
Just-in-time ledger node provisioning dominates cloud-based deployments, though strategic stockpiling of cryptographic talent concentrates in Houston, London, and Singapore hiring markets. Software development capacity draws from the United States, the United Kingdom, and Norway, with hardware infrastructure resting on semiconductor supply from Taiwan and South Korea. Single-source vulnerability sits with concentrated cryptography expertise pools. Distribution runs through operator-led consortium governance structures rather than traditional vendor-reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates formidable switching costs for operators once consortium node architectures achieve critical mass.
For Market Incumbents: Shield proprietary data architectures through accelerated ISO/TC 307 standards alignment and exclusive joint venture node operator agreements. Emerging satellite emissions monitoring technologies threaten ledger-based verification premiums. Vertical integration into field sensor manufacturing hardens custody-transfer data pipelines against substitute audit trails.
For New Entrants and Emerging Players: Lead with Brazil pre-salt field consortiums where ANVISA transparency mandates outpace incumbent platform penetration. Hydrogen carrier traceability applications remain substantially underdeveloped relative to hydrocarbon tracking. A sensor-to-ledger automation specialization offers the clearest go-to-market angle against established custody-transfer incumbents.
For Investors and Strategic Acquirers: Pure-play software vendors with proven consortium anchor relationships and petroleum engineering domain expertise represent the most defensible acquisition archetype. Long-term viability over the coming decade rests on regulatory compliance mandate durability rather than technology differentiation alone. Watch EPA enforcement patterns on Subpart W methane documentation as the critical inflection signal for ledger demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Consortium Node Expansion | Shared infrastructure investments distribute FERC compliance costs across Permian and Bakken operators. |
| Smart Contract Certification | ISO/TC 307 alignment positions platforms for cross-sector expansion into metals and agriculture tracking. |
| Sensor Network Integration | Field device automation eliminates manual reconciliation delays in EPA methane reporting workflows. |
| Source-Code Escrow Negotiation | Data residency guarantees satisfy Shell and BP procurement requirements in North Sea joint ventures. |
| Hydrogen Traceability Development | Molecular-level provenance tracking addresses ammonia supply chain gaps beyond existing ERP capabilities. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filing analysis anchors the qualitative findings in this study. Conversations with midstream operations directors, petroleum trading risk managers, consortium governance leads, and environmental compliance officers combined with FERC tariff dockets, EPA enforcement records, EU Green Deal implementation documents, and ANVISA regulatory guidance. Bottom-up deployment estimates from individual operator announcements triangulate against top-down market sizing from infrastructure investment tracking.
Sensitivity analysis around consensus protocol adoption rates and sensor network penetration shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, operator type, application function, and regional regulatory cluster. CAGRs derive from deployment timeline compression observed under simultaneous EPA and FERC mandate convergence, with inputs from methane measurement technology maturation and EU Carbon Border Adjustment Mechanism implementation pacing.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or consortium governance stability would require recalibration. Forecasts reflect assumptions on mandate durability and interoperability standard emergence. Revision becomes warranted when EPA Subpart W enforcement thresholds or ISO blockchain framework adoption rates cross material inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Cased Hole Logging Services Market
Oil & Gas
Oilfield Services Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Underreamers Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Oil, Gas and Chemicals Software Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Mud Balance Market