
 Coal Seam Gas Market | 2026-2036
Coal Seam Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Seam Gas Market Analysis
Multi-source procurement from independent producers is hardening across eastern Australian gas markets. Origin Energy leverages its integrated upstream-to-retail footprint to secure long-term supply contracts with domestic utilities. Santos anchors its position through stakes in Queensland's largest coal seam gas fields, while Arrow Energy competes via joint-venture partnerships with international majors for LNG export feedstock.
Coal seam gas refers to methane trapped within coal formations at depths typically ranging from 200 to 1,000 metres, extracted through vertical or horizontal drilling and often dewatering to reduce reservoir pressure. Its primary purpose is to supply pipeline-quality natural gas for power generation, industrial heat, and chemical feedstock with lower surface carbon intensity than conventional coal combustion. Unconventional extraction methods now dominate greenfield development as producers target deeper, lower-permeability coal seams that conventional vertical wells cannot economically drain. Power Generation end users command the largest current volume share, though Chemical Production applications are expanding fastest as Asian manufacturers seek alternatives to naphtha-derived feedstocks.
Australia's Environment Protection and Biodiversity Conservation Act intersects with state water licensing regimes to impose multi-year assessment periods on new coal seam gas projects. The Queensland Office of Groundwater Impact Assessment mandates ongoing monitoring of aquifer interference, directly constraining drilling density in priority agricultural zones. Stakeholders must weigh regulatory compliance timelines against the narrowing window for gas-to-power investments before renewable storage economics fully displace baseload fossil contracts.
Market Dynamics
Queensland's water licensing regime under the Office of Groundwater Impact Assessment is compressing drilling density in priority agricultural zones, forcing producers to front-load monitoring infrastructure and extend project timelines before commercial extraction can commence.
Growth Catalysts
- Baseload transition demand:Power generation utilities across Asia-Pacific are executing long-term offtake agreements for coal seam gas as coal plant retirements accelerate.
- Dewatering technology maturation:Advanced horizontal drilling combined with managed aquifer recharge systems is opening deeper, lower-permeability seams previously deemed uneconomic.
- EPBC Act harmonization:Streamlined federal-state environmental assessment pathways in Australia are reducing duplication for projects demonstrating net-neutral groundwater impact.
Market Restraints
- Steel and cement input volatility:Casing and well completion materials face price swings tied to global metallurgical coal and clinker markets, squeezing well economics.
- Pipeline infrastructure chokepoints:Eastern Australian transmission capacity concentrates around Gladstone and Wallumbilla hubs, creating delivery bottlenecks for new field entrants.
- Renewable storage substitution:Battery and pumped hydro deployments are narrowing the window for new gas-fired baseload contracts in national electricity markets.
Strategic Opportunities
- Blue hydrogen feedstock pivot:Coal seam gas with carbon capture integration offers a lower-carbon hydrogen pathway for Japanese and South Korean industrial importers.
- Chemical production naphtha displacement:Asian petrochemical manufacturers are trialing methane-derived syngas routes to reduce olefin production costs.
- Indigenous land-use agreements:Structured benefit-sharing frameworks with traditional owners are unlocking access to tenements previously stalled by native title complexity.
Industry Challenges
- Hydrogeological modeling expertise scarcity:Specialized groundwater impact assessment capabilities are concentrated among a handful of consultancies, extending recruitment timelines.
- Multi-year capital lockup:Drilling commitments, water monitoring infrastructure, and pipeline laterals demand sustained funding before first gas sales materialize.
- Aquifer interference certification delays:Demonstrating cumulative impact compliance under Queensland's regulatory framework requires extended baseline data collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Seam Gas Market |
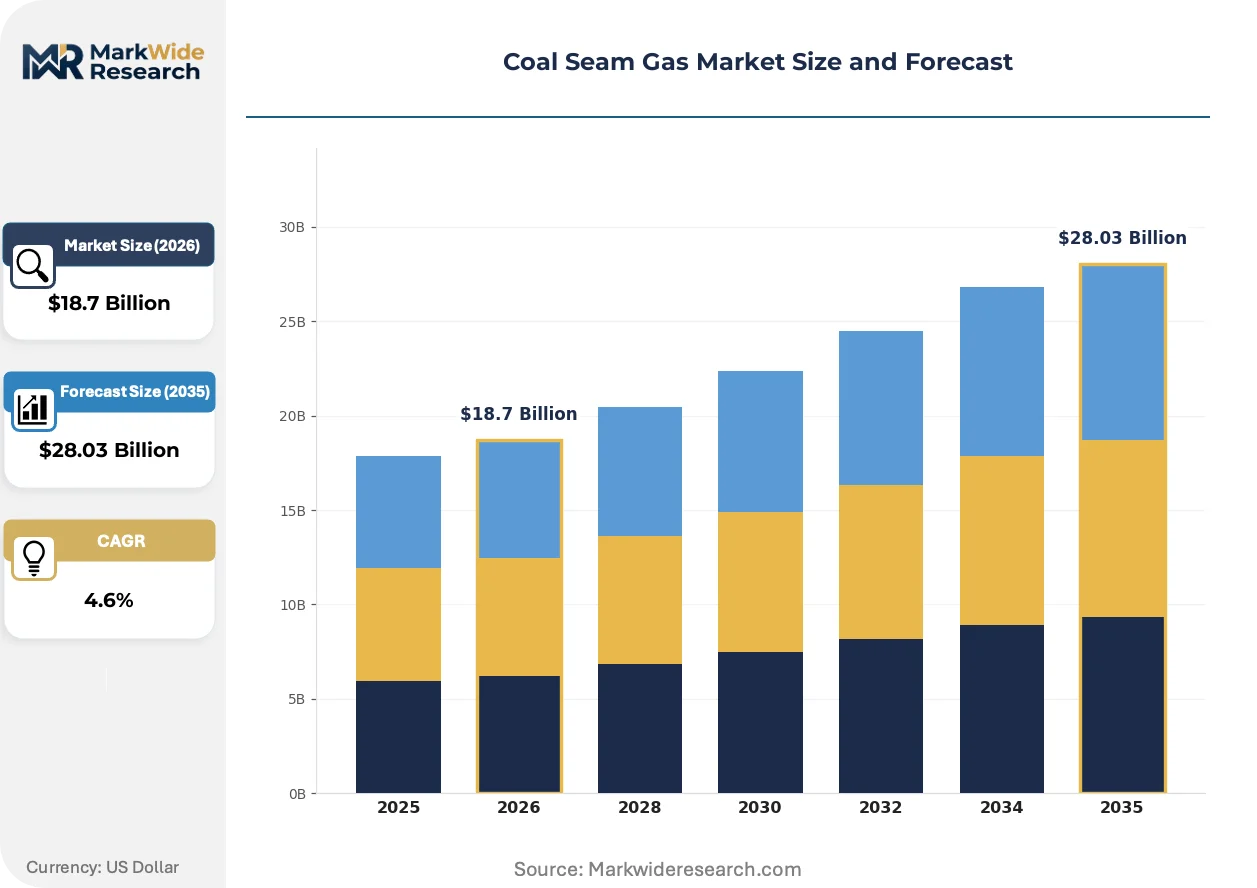
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Conventional, Unconventional, Enhanced Coal Bed Methane, Hydraulic Fracturing End User: Industrial, Power Generation, Residential, Transportation Application: Heating, Power Supply, Fuel for Vehicles, Chemical Production Technology: Upstream Technologies, Midstream Solutions, Downstream Processes, Monitoring Systems |
| Companies Covered | Origin Energy, Santos, Queensland Gas Company, Arrow Energy, Beach Energy, Peabody Energy, BHP Group, ExxonMobil, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Seam Gas Market Emerging Trajectories
Horizontal well geometries and real-time reservoir monitoring are compressing the cost curve for marginal seam development, while regulatory frameworks harden around cumulative groundwater impact accountability.
Directional drilling with geosteering capabilities is unifying previously isolated coal seam compartments into single wellbore drainage footprints. Integrated producers in the Surat Basin are deploying these systems to reduce surface disturbance density by half. The technology is unifying exploration and production workflows, collapsing the timeline between resource confirmation and commercial commissioning.
Australia's Environment Protection and Biodiversity Conservation Act amendments are mandating upfront biodiversity offset calculations for all new petroleum tenements. Project proponents must now secure offset parcels before drilling approvals, shifting environmental liability from post-impact remediation to pre-development mitigation. This regulatory tightening most affects greenfield entrants lacking legacy offset portfolios, pushing them toward joint-venture structures with established holders.
Japanese power utilities are compressing contract tenures from fifteen-year baseload agreements to five-year bridge-fuel arrangements with renewable buildout clauses. Trading houses in Tokyo are intermediating these shorter-dated structures, absorbing price risk that producers previously transferred directly. This contracting evolution is most visible in Queensland LNG export negotiations, where spot-indexed volumes are displacing traditional oil-linked term formulas.
Coal Seam Gas Market Segmentation
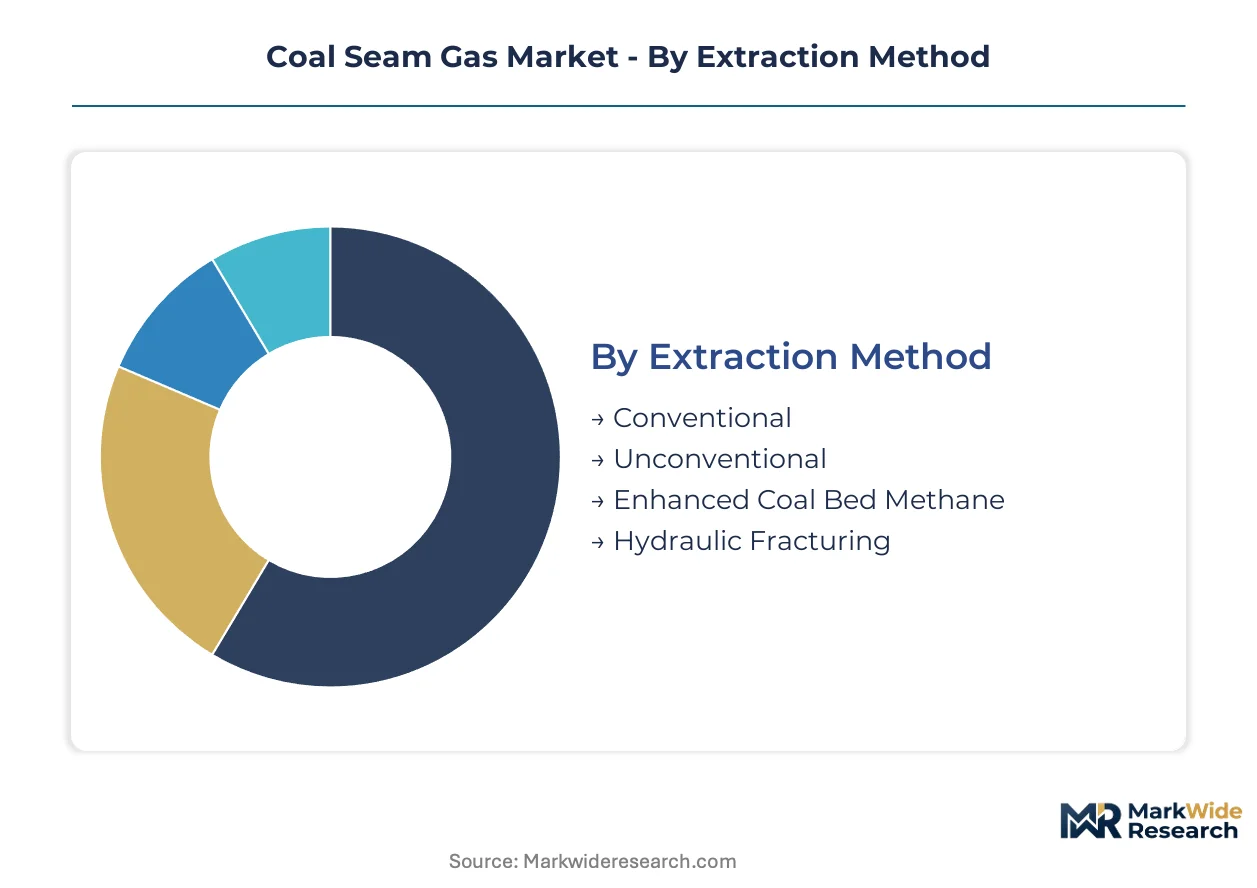
Segmentation in coal seam gas markets reveals how extraction economics, regulatory constraints, and end-use specifications fragment commercial opportunities across distinct technical and demand profiles.
Extraction Method:
Standalone surface operations dominate mature basins, while embedded multi-well pad systems are displacing single-well development in greenfield acreage.
- Conventional:Vertical wells target shallow, high-permeability seams at 200-400 metre depths with minimal dewatering requirements. Queensland's Surat Basin operators deploy these for rapid payback in established fairways where baseline groundwater data already exists.
- Unconventional:Horizontal drilling with multi-stage completions unlocks deeper, lower-permeability coal seams previously bypassed. Arrow Energy and Santos anchor portfolios here, though extended dewatering timelines stretch capital recovery.
- Enhanced Coal Bed Methane:CO₂ or nitrogen injection accelerates methane desorption rates from coal matrices. Pilot projects in Alberta and Queensland test viability for carbon utilization credits.
- Hydraulic Fracturing:Proppant-stimulated fractures create artificial permeability in tight coals where natural cleat systems are degraded. Regulatory moratoria in several Australian states constrain deployment despite proven North American results.
Conventional methods lead volumes today; unconventional extraction is gaining share fastest as producers target deeper resource bases.
End User:
Contract tenures and price indexation structures diverge sharply between baseload offtakers and interruptible demand segments.
- Power Generation:Combined-cycle gas turbines in eastern Australian national electricity markets absorb the largest contracted volumes. Origin Energy and AGL Energy negotiate 10-15 year baseload agreements with oil-linked or hybrid pricing.
- Industrial:Smelters, refineries, and manufacturing facilities require firm supply with pressure specifications above standard pipeline tariffs. Gladstone's alumina producers represent concentrated demand with limited fuel-switching flexibility.
- Residential:Reticulated distribution networks in Queensland and New South Wales serve temperature-driven heating loads with seasonal demand peaks.
- Transportation:Compressed natural gas fuelling infrastructure for heavy road freight remains sparse, though pilot corridors between Brisbane and Sydney test fleet conversion economics.
Power generation commands current volume leadership; industrial offtake is climbing the fastest as manufacturers seek alternatives to grid-exposed electricity.
Application:
Energy conversion efficiency requirements and carbon intensity accounting differentiate commercial viability across use cases.
- Heating:Direct combustion in commercial and residential boilers delivers 85-90% thermal efficiency with lower NOₓ emissions than fuel oil equivalents.
- Power Supply:Grid-synchronous generation provides voltage support and inertia services that inverter-based renewables cannot replicate.
- Fuel for Vehicles:Spark-ignition engines adapted for compressed natural gas reduce particulate emissions in urban freight corridors.
- Chemical Production:Steam methane reforming and syngas routes to ammonia and methanol compete with naphtha-based olefin production in Asian petrochemical complexes.
Power supply anchors current demand; chemical production shows steepest expansion trajectory as feedstock substitution accelerates.
Technology:
Capital allocation across the value chain reflects where producers can defend margin through proprietary capability versus purchased services.
- Upstream Technologies:Reservoir characterization, directional drilling, and dewatering systems constitute the highest R&D intensity segment. Proprietary geosteering algorithms differentiate Santos and Origin Energy in Surat Basin development.
- Midstream Solutions:Gathering networks, compression stations, and dehydration facilities concentrate around Wallumbilla and Gladstone hub infrastructure with limited third-party access.
- Downstream Processes:LNG liquefaction trains, pipeline injection treatment, and small-scale distribution systems sit with integrated majors or utility counterparties.
- Monitoring Systems:Real-time aquifer pressure telemetry and fugitive methane detection hardware face procurement acceleration under Queensland's Office of Groundwater Impact Assessment compliance mandates.
Upstream technologies dominate current investment; monitoring systems are expanding most quickly as regulatory disclosure requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's Surat and Bowen Basins anchor coal seam gas production economics through established gathering infrastructure and proven Permian-to-Triassic coal measures. Field development concentrates where pipeline lateral density and water treatment facilities already exist. Regulatory frameworks in each producing jurisdiction determine project sanctioning velocity and capital allocation priority.
Australia
Power generation utilities in New South Wales and Queensland execute long-term offtake agreements for baseload gas supply as coal plant retirements accelerate. The Environment Protection and Biodiversity Conservation Act intersects with state water licensing to impose multi-year assessment periods on new projects. Gladstone's LNG export facilities and Wallumbilla's pipeline hub concentrate midstream infrastructure investment.
China
Industrial manufacturers in Shanxi and Shaanxi provinces seek methane-derived syngas routes to reduce olefin production costs. The Ministry of Ecology and Environment enforces groundwater monitoring mandates for coalbed methane extraction in agricultural zones. Qinshui Basin operators deploy enhanced coal bed methane pilot projects testing carbon utilization credits.
United States
Power generators in the Appalachian basin absorb coal seam gas volumes for combined-cycle turbine dispatch. The EPA regulates fugitive methane emissions under Subpart W of the Greenhouse Gas Reporting Program. Powder River Basin producers in Wyoming and Colorado target deeper, lower-permeability seams through horizontal drilling with multi-stage completions.
Canada
Chemical producers in Alberta evaluate coalbed methane feedstock for hydrogen and ammonia synthesis pathways. The Alberta Energy Regulator mandates aquifer protection protocols for drilling operations in agricultural districts. Horseshoe Canyon operators in central Alberta test managed aquifer recharge systems to reduce surface water handling costs.
Indonesia
Industrial estates in East Kalimantan negotiate firm supply contracts for manufacturing heat applications. The country's national energy regulator oversees production sharing arrangements for unconventional gas development. Kutai Basin exploration targets Miocene coal measures with vertical well programs prior to horizontal appraisal.
Coal Seam Gas Market Vendor Landscape
Global majors compete with regional champions across integrated upstream-to-downstream value chain positions. The market structure concentrates around three strategic tiers: integrated majors with LNG export capacity, domestic utilities with captive upstream positions, and independent producers supplying pipeline spot markets. Competitive dynamics center on securing long-term offtake agreements and navigating multi-year environmental approval timelines. Players defend position through joint-venture partnerships for risk-sharing and through proprietary dewatering technology deployment.
Within the integrated major tier, Origin Energy and Santos exemplify full-value-chain operators, while Arrow Energy occupies a position emphasizing joint-venture structures with international partners. These three Australian entities anchor the competitive landscape through their exposure to Queensland's Surat Basin resource base and their relationships with Gladstone LNG export infrastructure.
| Leading Market Players |
|---|
| Origin Energy |
| Santos |
| Queensland Gas Company |
| Arrow Energy |
| Beach Energy |
| Peabody Energy |
| BHP Group |
| ExxonMobil |
| Shell |
| Others |
Supply Flow & Price Mechanics
Metallurgical coal and Portland cement price indices cascade through coal seam gas well economics, compressing margins for producers locked into fixed-price offtake agreements while rewarding those with flexible, spot-indexed contract structures. Input cost volatility stratifies the market into three tiers: integrated majors with captive supply chains, mid-tier independents exposed to commodity swings, and marginal operators facing well economics below breakeven thresholds.
Pricing Analysis
Input-cost pass-through mechanisms dominate contract negotiations, with steel casing and cement completion materials subject to quarterly adjustment clauses tied to commodity benchmarks. Price differentiation rests on reserve quality tier and pipeline access proximity, with Surat Basin producers commanding premiums over greenfield entrants facing infrastructure buildout costs. Pricing pressure stems from renewable storage substitution narrowing baseload contract windows. Industrial offtakers exhibit highest price sensitivity due to limited fuel-switching flexibility, while LNG export traders absorb volatility through portfolio diversification.
Supply Chain Analysis
Regional distribution centers at Wallumbilla and Gladstone anchor hub-and-spoke gathering networks, compressing logistics costs for Surat Basin producers while isolating new field entrants. Australia, China, and the United States concentrate upstream drilling capacity and dewatering technology deployment. Raw material dependencies encompass high-strength steel casing, specialized proppants, and cement clinker for well completion. Single-source vulnerability concentrates in geosteering software and directional drilling services. Distribution runs through pipeline lateral networks feeding Gladstone LNG trains and eastern Australian domestic interconnects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coal seam gas functions as a regulatory compounder, where Queensland's Office of Groundwater Impact Assessment mandates are accelerating capital deployment into monitoring infrastructure ahead of production sanctioning. This regulatory milestone compresses project timelines for compliant operators while erecting barriers for undercapitalized entrants.
For Market Incumbents: To counter renewable storage substitution eroding baseload contract tenures, Origin Energy and Santos should deepen upstream control over dewatering technology portfolios and accelerate capacity addition in Queensland's Surat Basin fairways with existing groundwater baseline data. Certification investment in carbon capture integration for blue hydrogen feedstock production offers differentiation against pure-play methane competitors. For New Entrants and Emerging Players: Launch via joint-venture structures with established offset portfolio holders to circumvent pre-development biodiversity mitigation requirements under Australia's EPBC Act amendments. Chemical production feedstock supply to Asian petrochemical manufacturers represents the most penetrable segment, with naphtha displacement trials creating first-mover windows for methane-derived syngas routes. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-year capital lockup requirements exceed independent producer funding capacity, particularly for greenfield tenements lacking legacy infrastructure. Mid-tier operators with proven Surat Basin reserves and pending aquifer interference certification represent prime acquisition targets. The signal to watch is Queensland groundwater impact assessment approval velocity as inflection indicator for project sanctioning timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Aquifer Recharge Deployment | Reduces surface water handling costs and accelerates Queensland regulatory approval timelines. |
| Horizontal Well Geosteering Investment | Unifies isolated coal seam compartments, halving surface disturbance density in Surat Basin development. |
| Carbon Capture Integration for Blue Hydrogen | Opens Japanese and South Korean industrial import markets seeking lower-carbon feedstock pathways. |
| Indigenous Land-Use Agreement Structuring | Unlocks tenements previously stalled by native title complexity through benefit-sharing frameworks. |
| Short-Term Bridge-Fuel Contracting Pivot | Aligns with Tokyo trading house intermediation of five-year renewable buildout clauses. |
Methodological Framework
Bottom-up power generation and chemical production demand modeling reconciled against top-down drilling activity and pipeline capacity tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists combined with secondary validation from EIA data, IEA reports, FERC filings, and Queensland government tenement databases. This dual approach enables cross-verification of reserve estimates against actual production volumes and contract disclosure patterns.
Input-output matrix framing connects reserve depletion curves, dewatering technology deployment rates, and infrastructure buildout timelines to volume and value projections across the analysis window. Segmentation dimensions encompass extraction method, end user archetype, application type, and technology tier, with regional regulatory framework clusters as an industry-specific overlay. CAGRs derive from fitted growth curves applied to disclosed production volumes and announced project sanctions, with coal plant retirement schedules and renewable storage cost trajectories as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated renewable substitution or prolonged Queensland groundwater assessment delays. Outputs reflect documented assumptions regarding regulatory harmonization progress and Asian LNG demand elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Proppant Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Angola Oil and Gas Upstream Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
Coal Bed Methane Market