
 France Oral Anti-Diabetic Drug Market | 2026-2036
France Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
France Oral Anti-Diabetic Drug Market Insights
The capability gap between biologics-scale manufacturers and pure-play oral formulation specialists is unwinding competitive stability across the France Oral Anti-Diabetic Drug Market. Sanofi leverages its integrated insulin-to-oral portfolio to control hospital formularies in Lyon and Marseille. Novo Nordisk anchors its position through deep GLP-1 expertise that extends into oral combination strategies. Eli Lilly and Company differentiates via manufacturing scale for extended-release metformin complexes.
France Oral Anti-Diabetic Drugs comprise small-molecule hypoglycemic agents administered perorally to modulate glucose metabolism through hepatic, pancreatic, or renal pathways, with formulations ranging from immediate-release tablets to multi-layer extended-release matrices designed for precise dissolution profiles. The primary commercial purpose centers on chronic outpatient management of type 2 diabetes mellitus within France's statutory health insurance framework. SGLT2 inhibitors command premium positioning as cardiorenal protective agents, while DPP-4 inhibitors occupy a mature, volume-driven tier where HAS generic substitution rules compress margins. Extended-release delivery modes represent the fastest-growing structural segment as patient adherence programs gain reimbursement traction.
ANSM oversees batch release testing and post-market surveillance for all oral anti-diabetic entrants, while HAS evaluates clinical benefit scores that determine reimbursement levels and hospital procurement eligibility. EMA centralized procedures govern novel SGLT2 and dual-agonist approvals, with France often serving as a reference member state for pricing negotiations. Stakeholders must monitor evolving HAS criteria for combination therapy reimbursement as real-world evidence requirements tighten for newer drug classes.
Market Dynamics
Hospital formulary consolidation around SGLT2 inhibitors is decomposing the traditional DPP-4 volume base, as Île-de-France academic centers rewrite combination therapy protocols and force regional procurement alignment.
Growth Catalysts
- ANSM pharmacovigilance frameworks:Post-market surveillance mandates for cardiorenal outcomes data accelerate adoption of evidence-backed SGLT2 protocols in tertiary centers.
- Extended-release matrix technology:Multi-layer dissolution engineering improves glycemic variability control, driving HAS reimbursement for adherence-optimized formulations.
- Île-de-France concentration:Academic medical center purchasing power concentrates demand, creating reference market effects that cascade to Lyon and Marseille hospital networks.
Market Restraints
- HAS generic substitution rules:Mandatory interchange for mature DPP-4 molecules compresses originator margins and discourages incremental innovation investment.
- API supply concentration:Metformin precursor manufacturing clusters in coastal China, exposing French formulators to shipping cost volatility and customs clearance delays.
- Fixed-dose combination limits:Regulatory complexity of triple-therapy pills exceeds current ANSM bioequivalence guidance, slowing next-generation development.
Strategic Opportunities
- Auvergne-Rhône-Alpes expansion:Lyon-based metabolic research institutes seek localized trial partnerships, opening access to protocol design influence before national rollout.
- Real-world evidence mandates:HAS expanding requirements for post-authorization effectiveness studies create demand for data-analytics service partnerships.
- Hospital-at-home channels:Regional health agencies pilot oral therapy delivery outside inpatient settings, requiring new cold-chain and adherence-monitoring capabilities.
Industry Challenges
- Biostatistics talent scarcity:Complex adaptive trial designs for combination therapies exceed capabilities of traditional clinical research organizations serving mid-tier sponsors.
- Legacy ERP integration:Hospital procurement platforms in Provence-Alpes-Côte d'Azir lack API connectivity for real-time inventory synchronization with distributor systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Oral Anti-Diabetic Drug Market |
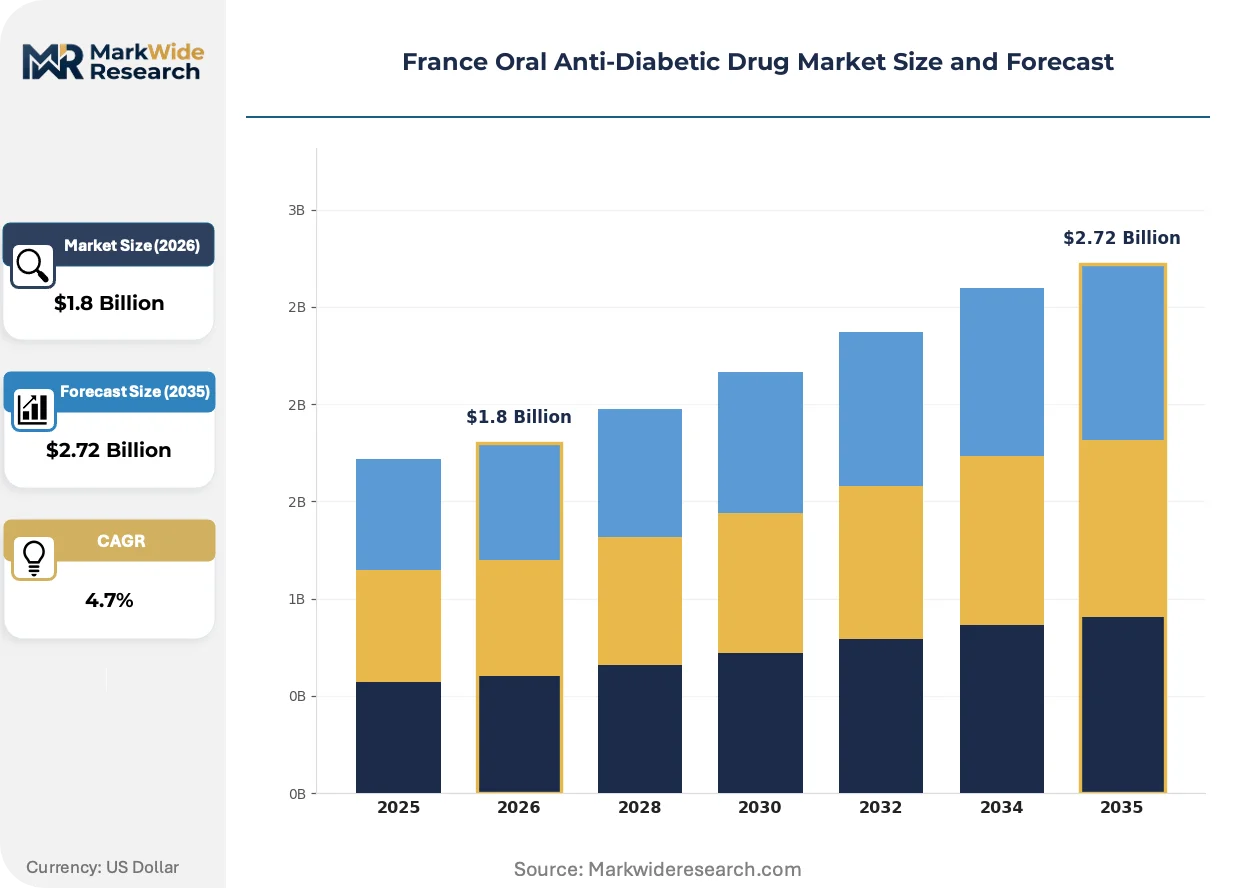
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Therapy Area: Type 2 Diabetes, Prediabetes, GDM, Obesity Delivery Mode: Oral Tablets, Oral Solutions, Extended Release, Combination Therapy End User: Healthcare Professionals, Patients, Pharmacies, Hospitals |
| Companies Covered | Eli Lilly and Company, Merck & Co., Sanofi, Janssen Pharmaceuticals, Novartis, Novo Nordisk, Boehringer Ingelheim, Astellas Pharma, AstraZeneca, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Oral Anti-Diabetic Drug Market Trends and Innovations
Formulation science and regulatory data requirements are converging to reward manufacturers who can bridge laboratory-scale dissolution engineering with large-cohort outcomes evidence generation.
Dual-agonist oral molecules targeting GLP-1 and GIP pathways are decomposing the traditional insulin-to-oral escalation ladder, enabling earlier intensive therapy initiation in newly diagnosed patients. Endocrinology departments at Paris public hospital groups are piloting these protocols ahead of formal HAS guidance. The structural consequence is compression of DPP-4 inhibitor lifecycle value as cardiorenal protection becomes the default prescribing criterion.
EMA centralized procedures for novel SGLT2 indications now require cardiovascular outcomes trial data prior to approval, extending development timelines but reducing post-market withdrawal risk. French sponsors face elevated documentation burdens for renal impairment subgroup analyses. The requirement most affects fixed-dose combination submissions, where sponsors must demonstrate component-specific benefit attribution.
Regional hospital purchasing consortiums in Hauts-de-France are consolidating oral anti-diabetic procurement under single-tender frameworks, displacing fragmented pharmacy-level ordering. Distributors must now guarantee 48-hour stock availability across multiple sites to maintain contract eligibility. The shift is most visible in Lille and Amiens, where three-hospital networks have merged formularies under unified logistics contracts.
France Oral Anti-Diabetic Drug Market Segmentation
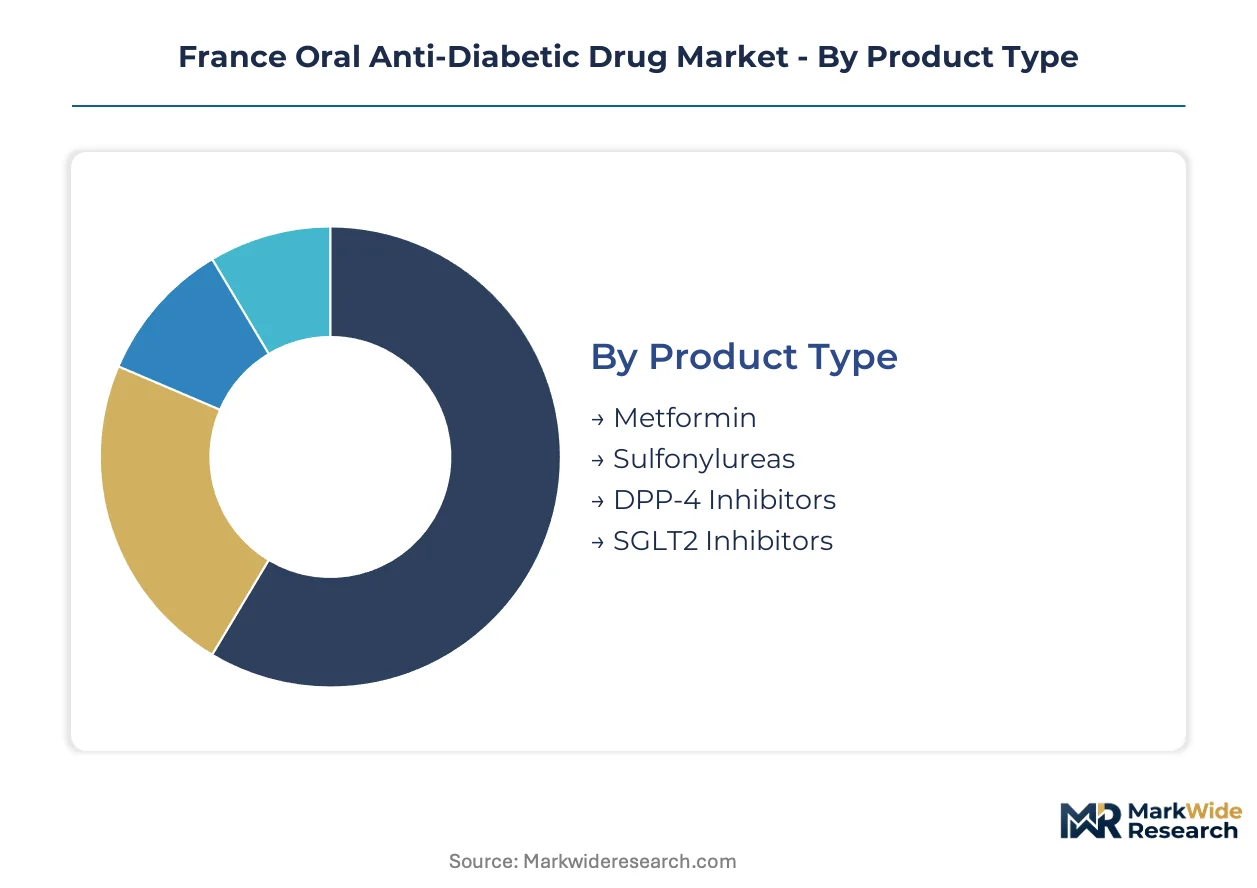
Segmentation in the France Oral Anti-Diabetic Drug Market reveals how reimbursement tiers and clinical protocols fragment demand across molecular classes and delivery formats. HAS assessment criteria and ANSM batch release requirements create divergent margin structures that reward certain combinations over others.
Product Type:
SGLT2 inhibitors face the most intense substitution pressure from emerging dual-agonist oral molecules, while mature DPP-4 compounds confront HAS-mandated generic interchange.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers deliver cardiorenal protection through renal glucose excretion. Demand concentrates in Île-de-France academic medical centers where hospital formularies prioritize cardiovascular outcomes data.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors provide glucose-dependent insulin secretion with minimal hypoglycemia risk. Lyon and Marseille procurement networks drive volume through standardized combination protocols despite margin compression from HAS generic rules.
- Metformin:Biguanide compounds remain the first-line foundation therapy across all French regions under statutory health insurance guidelines.
- Sulfonylureas:ATP-sensitive potassium channel blockers occupy a declining tier as hypoglycemia concerns shift prescribing toward SGLT2 and DPP-4 alternatives.
Metformin anchors the volume base while SGLT2 inhibitors gain share at the steepest rate.
Therapy Area:
Cost tier differentiation separates chronic disease management from preventive intervention, with reimbursement intensity varying by progression stage.
- Type 2 Diabetes:Established insulin resistance with pancreatic β-cell dysfunction constitutes the core reimbursed indication. Hospital procurement in Hauts-de-France consolidates demand under single-tender frameworks for this population.
- Obesity:Adjunctive oral therapy for weight management in diabetic patients attracts premium positioning as dual-agonist molecules demonstrate metabolic benefits. Paris public hospital groups pilot early intensive protocols ahead of formal HAS guidance.
- Prediabetes:Impaired glucose tolerance without diagnostic threshold crossing receives limited pharmacological reimbursement under current statutory frameworks.
- GDM:Gestational diabetes mellitus management relies primarily on insulin, restricting oral agent penetration to postpartum conversion protocols.
Type 2 Diabetes generates the dominant prescription volume while Obesity applications expand most quickly through off-protocol adoption.
Delivery Mode:
Patient adherence economics and manufacturing complexity create margin stratification across formulation technologies.
- Extended Release:Multi-layer matrix tablets enable precise dissolution profiles improving glycemic variability control. HAS reimbursement for adherence-optimized formulations drives Auvergne-Rhône-Alpes hospital network adoption.
- Combination Therapy:Fixed-dose dual and triple agent pills reduce pill burden but face ANSM bioequivalence guidance complexity. Regional health agencies in Provence-Alpes-Côte d'Azur pilot hospital-at-home delivery requiring new logistics capabilities.
- Oral Tablets:Immediate-release solid dosage forms maintain lowest unit cost position across all French pharmacy channels.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties in limited tertiary center niches.
Oral Tablets anchor the volume base while Extended Release formulations gain share at the steepest rate.
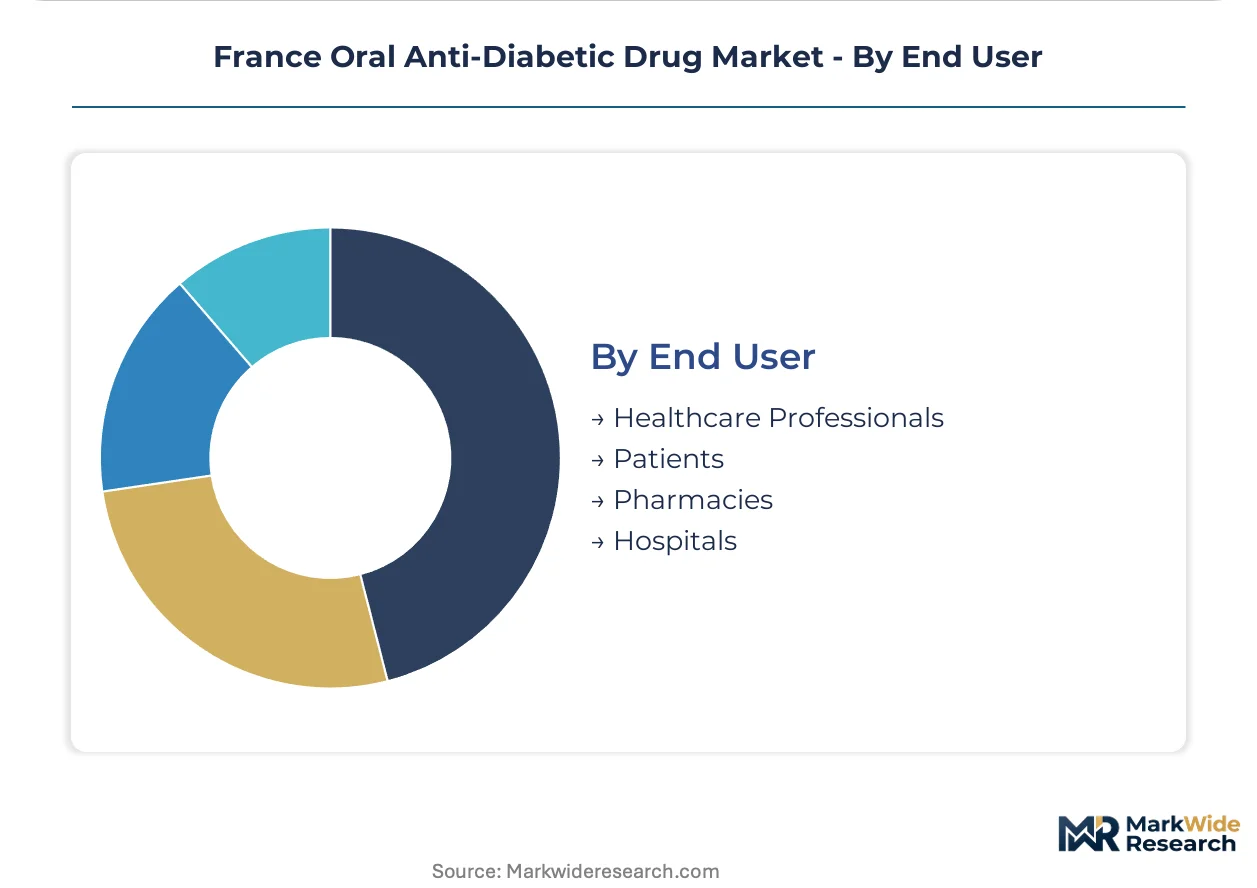
End User:
Procurement authority concentration determines pricing leverage, with hospital consortiums displacing fragmented pharmacy-level ordering.
- Hospitals:Tertiary and secondary care institutions control protocol design and formulary placement. Lille and Amiens three-hospital networks have merged procurement under unified logistics contracts with 48-hour stock availability requirements.
- Healthcare Professionals:Endocrinologists and general practitioners influence prescribing through real-world evidence generation. Lyon-based metabolic research institutes seek localized trial partnerships opening protocol design influence.
- Pharmacies:Community dispensers execute HAS generic substitution mandates for mature DPP-4 molecules under statutory health insurance frameworks.
- Patients:Direct acquisition remains minimal under France's reimbursement-based system, limited to non-reimbursed complementary products.
Hospitals anchor the volume base while Healthcare Professionals gain influence at the steepest rate through evidence-generation partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across French regions. Academic medical centers in Île-de-France prioritize clinical outcomes over acquisition costs, while consolidated hospital networks in Hauts-de-France and Provence-Alpes-Côte d'Azur leverage tender scale to compress supplier margins.
Île-de-France
Paris public hospital groups and suburban academic centers drive protocol innovation for SGLT2 inhibitors and dual-agonist combinations. ANSM pharmacovigilance requirements concentrate specialist expertise here, accelerating adoption of evidence-backed therapies. The Greater Paris metabolic research cluster generates real-world data that shapes national HAS reimbursement assessments.
Auvergne-Rhône-Alpes
Lyon-based endocrinology institutes seek localized clinical trial partnerships for extended-release formulations. The region's hospital procurement networks standardize combination therapy protocols despite margin pressure from generic substitution rules. Grenoble and Saint-Étienne satellite centers follow Lyon protocol templates, creating regional formulary alignment.
Provence-Alpes-Côte d'Azur
Marseille hospital consortiums consolidate oral anti-diabetic procurement under unified logistics contracts with 48-hour availability mandates. Regional health agencies pilot hospital-at-home delivery channels requiring cold-chain capabilities. Legacy ERP systems in Nice and Toulon lack API connectivity, creating inventory synchronization delays.
Hauts-de-France
Lille and Amiens three-hospital networks merge formularies under single-tender frameworks, displacing fragmented pharmacy-level ordering. The region's industrial heritage in chemical manufacturing supports API formulation capabilities. Procurement concentration here produces reference pricing that influences adjacent Normandy hospital networks.
Occitanie
Toulouse academic hospitals participate in EMA centralized procedure pilot programs for novel SGLT2 indications. Montpellier biotechnology clusters attract formulation science partnerships for multi-layer matrix development. The region's geriatric population concentration drives demand for adherence-optimized extended-release delivery modes.
France Oral Anti-Diabetic Drug Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the France Oral Anti-Diabetic Drug Market. Sanofi leverages its insulin-to-oral portfolio integration to control hospital formularies, while Novo Nordisk anchors positioning through GLP-1 expertise extending into oral combinations. Eli Lilly and Company differentiates via manufacturing scale for extended-release metformin complexes. The competitive terrain rewards three archetypes: portfolio-integrated pharmaceutical conglomerates, metabolic disease pure-plays, and formulation technology specialists. Dominant competitive moves include hospital formulary consolidation through real-world evidence partnerships and backward integration into active pharmaceutical ingredient supply security.
Within the portfolio-integrated tier, Sanofi, Novo Nordisk, and Eli Lilly and Company exemplify divergent strategic positions. Sanofi represents the broad metabolic portfolio archetype spanning injectable and oral modalities. Novo Nordisk occupies the peptide-to-oral translation specialist position. Eli Lilly and Company anchors the manufacturing scale-driven formulation capability segment. These three entities collectively shape procurement dynamics in Lyon, Marseille, and Paris academic hospital networks through distinct value propositions—portfolio breadth, clinical evidence depth, and supply reliability respectively.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Merck & Co. |
| Sanofi |
| Janssen Pharmaceuticals |
| Novartis |
| Novo Nordisk |
| Boehringer Ingelheim |
| Astellas Pharma |
| AstraZeneca |
| Others |
Pricing and Supply Chain Analysis
Generic DPP-4 interchange mandated by HAS reimbursement rules is displacing originator molecule procurement across French hospital networks, simultaneously compressing supplier margins and redirecting manufacturing investment toward SGLT2 inhibitor capacity in coastal China and Indian API clusters. This substitution dynamic concentrates pricing power among integrated portfolio holders while fragmenting procurement leverage across regional hospital consortiums.
Pricing Analysis
After-sales revenue from real-world evidence generation contracts and adherence-monitoring service partnerships drives lifetime value for formulation technology specialists. The market operates on a contract-based long-term offtake structure where HAS reimbursement tiers stratify pricing across premium cardiorenal-protected SGLT2 molecules, standard DPP-4 generics, and economy-tier sulfonylurea volumes. Price differentiation rests on HAS clinical benefit scores and ANSM batch release certification status. Cost compression in the DPP-4 tier is intensifying because mandatory generic substitution rules eliminate originator brand premiums. Community pharmacies exhibit highest price sensitivity due to statutory margin caps, while Île-de-France academic medical centers prioritize cardiovascular outcomes data over acquisition costs.
Supply Chain Analysis
Inbound logistics costs from Shanghai-to-Marseille container routes and Rotterdam port congestion are elevating working capital requirements for French formulators dependent on Asian API shipments. Metformin precursor manufacturing concentrates in coastal China and Gujarat, India, with SGLT2 inhibitor active pharmaceutical ingredients sourcing from South Korean and Italian specialty chemical producers. Raw material dependencies include biguanide salts, gliflozin intermediates, and DPP-4 enzyme inhibitor precursors. Single-source vulnerability pervades the metformin API tier where three Chinese manufacturers control global supply. Distribution runs through regional hospital purchasing consortiums in Hauts-de-France and Provence-Alpes-Côte d'Azur that mandate 48-hour stock availability across multiple sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards manufacturers who bridge formulation science capabilities with large-cohort outcomes evidence generation, yet biostatistics talent for complex adaptive trial designs remains scarce across traditional clinical research organizations serving mid-tier sponsors.
For Market Incumbents: Secure backward integration into SGLT2 API supply through partnerships with South Korean specialty chemical manufacturers, insulating margin structures from Shanghai port congestion volatility. Defend hospital formulary positioning in Lyon and Marseille by embedding real-world evidence generation capabilities within metabolic research institute partnerships, countering emerging dual-agonist oral molecule threats from peptide-to-oral translation specialists. For New Entrants and Emerging Players: Anchor in extended-release matrix formulation technology where HAS reimbursement for adherence-optimized products creates white-space opportunity ahead of generic erosion. Target Auvergne-Rhône-Alpes hospital network procurement standardization as the most penetrable geography, leveraging Lyon-based clinical trial partnerships to influence protocol design before national HAS rollout. Deploy data-analytics service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulation technology specialists with captive API supply and hospital evidence partnerships. Long-term viability over the projection horizon rests on regulatory data generation capabilities rather than molecule exclusivity alone. Prioritize acquisition targets possessing multi-layer dissolution engineering expertise and established ANSM batch release relationships. Monitor HAS post-authorization effectiveness study requirements as the signal to watch for inflection toward real-world evidence service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Partnership | HAS expanding post-authorization requirements creates demand for data-analytics capabilities with hospital networks. |
| API Supply Security Investment | Backward integration into South Korean and Indian specialty chemical producers reduces exposure to Chinese shipping volatility. |
| Extended-Release Manufacturing Scale-Up | Multi-layer matrix capacity expansion captures HAS reimbursement preference for adherence-optimized formulations. |
| Hospital-at-Home Logistics Development | Regional health agency pilots in Provence-Alpes-Côte d'Azur require cold-chain and adherence-monitoring infrastructure. |
| Dual-Agonist Clinical Trial Advancement | Paris public hospital group protocols ahead of formal HAS guidance establish early prescriber relationships. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation against EMA centralized procedure submissions, ANSM pharmacovigilance databases, HAS reimbursement assessment records, and hospital formulary databases. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchored segmentation estimates across molecular classes and delivery formats.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within each modeled segment spanning SGLT2 inhibitors, DPP-4 inhibitors, metformin formulations, and sulfonylureas by therapy line, dosage form, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical HAS reimbursement tier transitions and hospital procurement consolidation patterns. Forecast inputs incorporate ANSM batch release timelines and EMA centralized procedure pilot program participation rates.
Material uncertainties — regulatory shifts in HAS combination therapy criteria, API supply disruptions from Chinese port congestion, and dual-agonist oral molecule protocol adoption velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding reimbursement stability and hospital consortium procurement consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Korea Continuous Glucose Monitoring Devices Market
Diabetes Care
Diabetes Injection Pens Market
Diabetes Care
Russia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Network Point-Of-Care Glucose Testing Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Insulin Drugs and Devices Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
Vietnam Oral Anti-Diabetic Drug Market
Diabetes Care
Middle East and Africa Diabetes Care Devices Market
Diabetes Care
New Zealand Continuous Glucose Monitoring Devices Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market