
 Asia-Pacific Insulin Delivery Devices Market | 2026-2036
Asia-Pacific Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insulin Delivery Devices Market Outlook
Leasing and pay-per-use models for insulin pumps is tilting competitive dynamics toward firms with strong balance-sheet capacity. Novo Nordisk leverages its integrated insulin-pump ecosystem to sustain recurring revenue streams across multiple Asian markets. Medtronic anchors its position through deep clinical channel relationships and service infrastructure in Japan and Australia. Ypsomed competes with compact, rechargeable patch-pump designs that reduce patient training burdens.
Asia-Pacific insulin delivery devices encompass electromechanical and mechanical systems engineered to administer precise insulin doses subcutaneously, with smart pumps typically achieving dosing accuracy within 0.05-unit increments and incorporating Bluetooth-enabled glucose data integration. These devices serve the primary commercial purpose of replicating physiological insulin secretion patterns for glycemic control outside clinical settings. Insulin pens occupy the dominant revenue position due to their cost efficiency and physician familiarity, while patch pumps represent the fastest-expanding technology segment as wearable form factors gain traction among working-age diabetics. Home care settings command growing margin pools as reimbursement frameworks shift toward outpatient chronic disease management.
Japan's PMDA and Australia's TGA enforce stringent biocompatibility and electromagnetic-safety standards that shape product development timelines and market entry costs for device manufacturers. India's CDSCO and China's NMPA operate under evolving harmonization pathways that increasingly reference ISO 15197 and IEC 60601-1-10 for glucose monitoring interface compatibility. Stakeholders must monitor how each national regulator calibrates digital-health approval frameworks against real-world evidence requirements for algorithm-driven dosing systems.
Market Dynamics
Home care migration is compressing facility-based revenue pools while India's PLI scheme for medical device manufacturing reconfigures regional supply geography.
Growth Catalysts
- China NMPA streamlined approval pathways:The regulator's reference to IEC 60601-1-10 for glucose monitoring interface compatibility accelerates smart pump market entry timelines.
- Working-age diabetic populations:Patch pump adoption concentrates among employed patients seeking discretion during professional hours.
- Japan PMDA electromagnetic-safety frameworks:These standards create predictable compliance benchmarks that reduce product development uncertainty for Bluetooth-enabled devices.
Market Restraints
- Biocompatibility testing costs:Japan's PMDA and Australia's TGA requirements for prolonged skin-contact materials inflate pre-market expenditure for patch pump manufacturers.
- Rechargeable battery supply concentration:Compact patch pump designs depend on specialized lithium polymer cells sourced primarily from Northeast Asian suppliers.
- Algorithm-driven dosing liability:Unclear fault attribution between device manufacturers and insulin suppliers slows closed-loop system deployment.
Strategic Opportunities
- India CDSCO domestic manufacturing incentives:The PLI scheme offers capital subsidies that reduce landed cost disadvantages against imported pen systems.
- Subscription-based pump access:Pay-per-use models reduce upfront patient barriers while locking in recurring revenue streams.
- Bluetooth-continuous glucose monitor convergence:Integrated data ecosystems enable automated dose adjustment protocols that differentiate premium tier offerings.
Industry Challenges
- Diabetes educator workforce gaps:Complex smart pump onboarding requires certified training capacity that lags device deployment rates.
- Multi-regulator software validation:Algorithm updates for dosing systems trigger parallel CDSCO, NMPA, and PMDA review cycles that fragment development resources.
- Legacy pen user conversion friction:Established injection habits create behavioral resistance to pump adoption despite clinical efficacy advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insulin Delivery Devices Market |
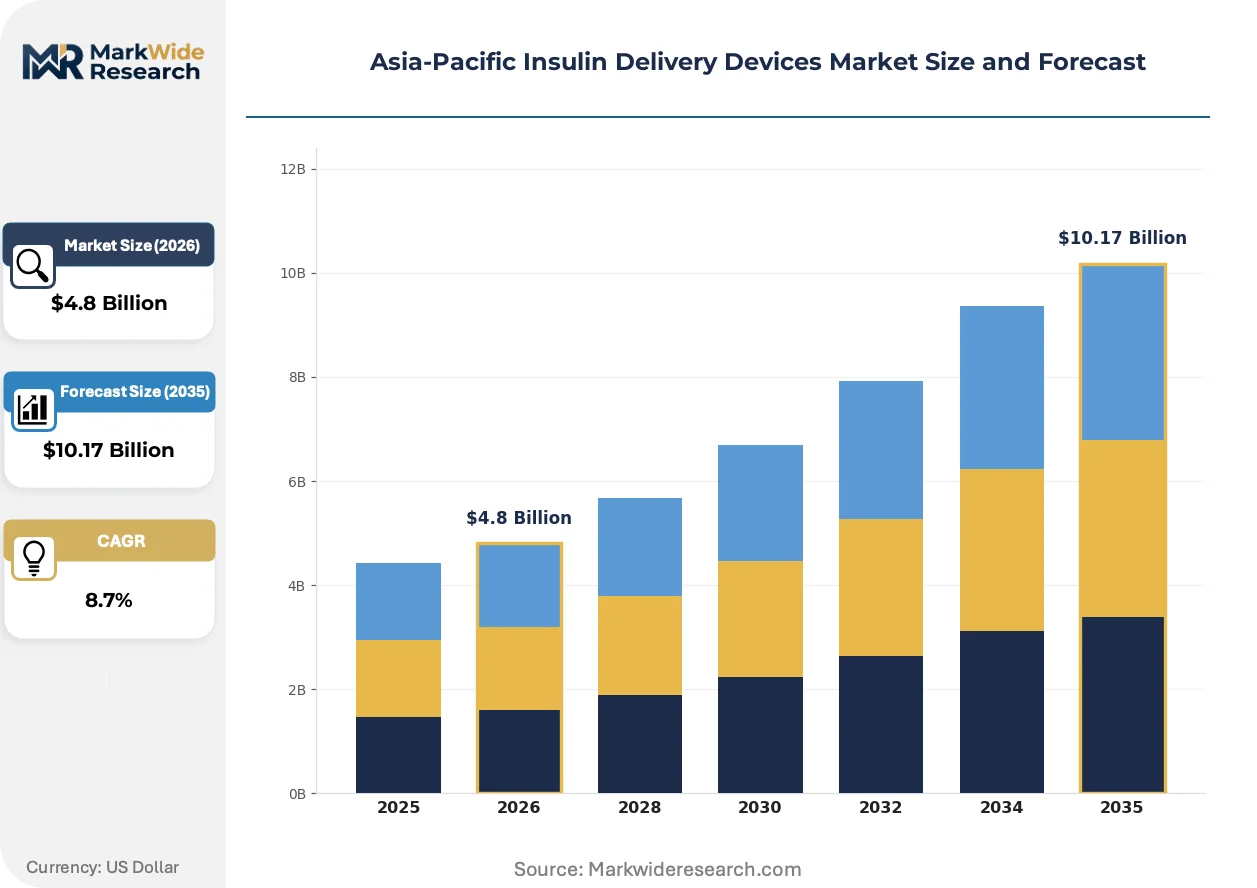
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Insulin Syringes, Jet Injectors Technology: Smart Pumps, Patch Pumps, Cartridge Pumps, Non-electronic Injectors Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes End User: Hospitals, Diabetes Clinics, Ambulatory Care Centers, Home Care Settings |
| Companies Covered | Novo Nordisk, Medtronic, Sanofi, Eli Lilly and Company, Ypsomed, Becton Dickinson, Insulet, Abbott Laboratories, Biocon, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insulin Delivery Devices Market Strategic Shifts
Digital connectivity is collapsing the distinction between delivery hardware and glucose data platforms, forcing business model reinvention across pen, pump, and patch categories.
Smart connectivity modules are virtualizing traditional device boundaries. Bluetooth-enabled pens now transmit dose logs to smartphone applications, enabling physician remote monitoring without pump infrastructure. Home care settings adopt these hybrid tools fastest where clinic visit frequency is constrained. This convergence is virtualizing the standalone device category into integrated disease management ecosystems.
Australia's TGA has tightened electromagnetic-safety documentation requirements for wearable devices with wireless transmission capabilities. Manufacturers must submit expanded clinical evidence for RF exposure during continuous glucose data streaming. Patch pump developers targeting Australian reimbursement lists face extended validation timelines that compress first-mover advantages.
Hospital procurement committees now demand unbundled after-sales service contracts separate from device capital expenditure. This purchasing pattern shift fragments vendor revenue recognition and forces service infrastructure investments ahead of volume commitments. China's tier-one municipal hospital systems lead this disaggregation, pressuring multinational suppliers to localize technical support capabilities.
Asia-Pacific Insulin Delivery Devices Market Segmentation
Insulin delivery device segmentation reveals divergent margin structures across mechanical and electromechanical platforms. Each dimension—product form, connectivity level, disease indication, and care setting—carries distinct regulatory pathways and reimbursement logic that shape vendor portfolio priorities across Asia-Pacific markets.
Product Type:
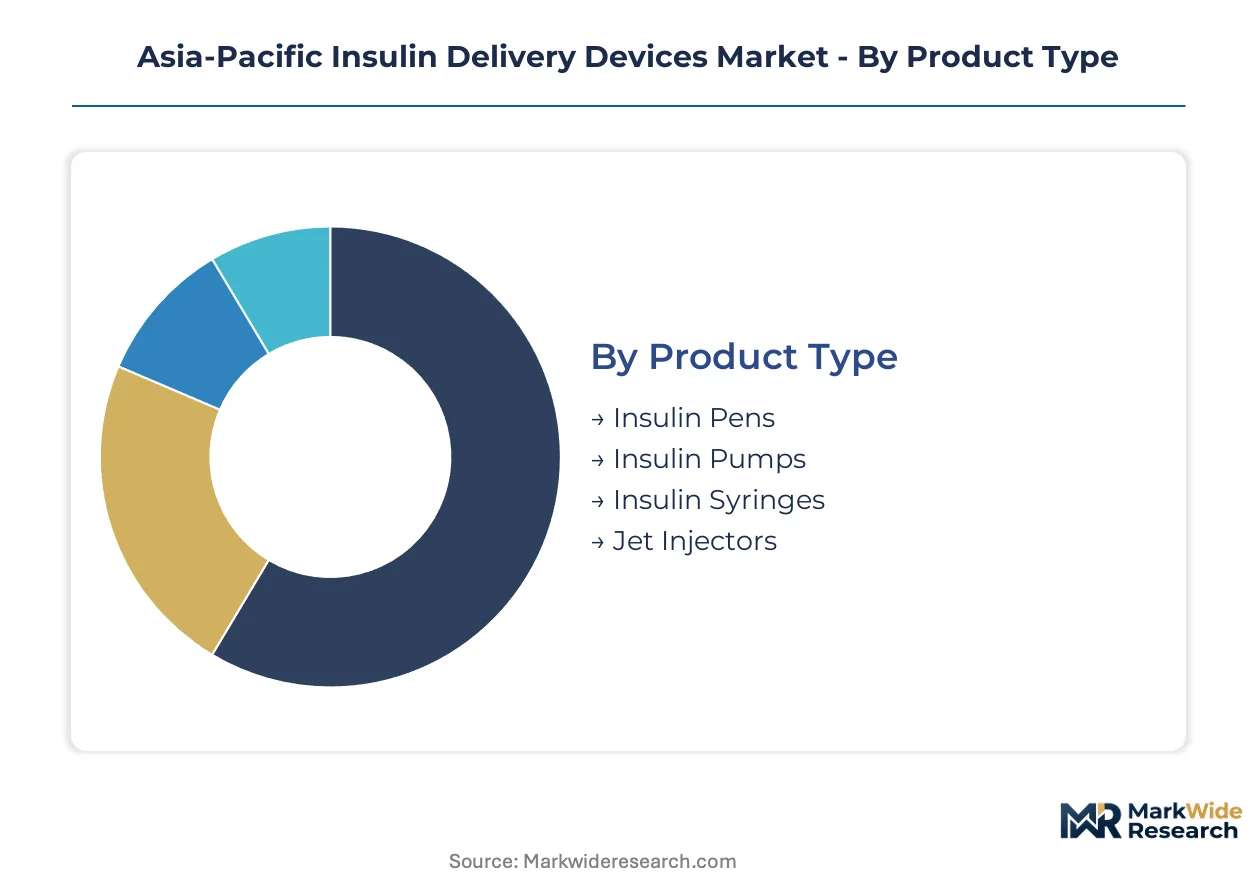
Mature mechanical formats dominate unit volumes while electromechanical systems capture expanding value pools.
- Insulin Pens:Reusable and disposable pen systems combine precision dose dials with cartridge-based insulin reservoirs. China's municipal hospital procurement networks and India's retail pharmacy channels drive bulk purchasing for these devices, though price ceilings in national reimbursement catalogs compress manufacturer margins.
- Insulin Pumps:Electromechanical infusion systems deliver subcutaneous basal and bolus dosing through programmable algorithms. Japan's PMDA electromagnetic-safety certification requirements and Australia's TGA biocompatibility standards create compliance barriers that favor established suppliers with dedicated regulatory affairs teams.
- Insulin Syringes:Conventional needle-and-barrel systems remain prevalent in cost-sensitive segments.
- Jet Injectors:Needle-free pressure delivery devices serve needle-phobic patient subsets.
Insulin pens handle the majority of throughput; insulin pumps are gaining share fastest as closed-loop integration matures.
Technology:
Connectivity tier separates premium positioning from commodity competition.
- Smart Pumps:Bluetooth-enabled devices integrate continuous glucose monitor data streams for algorithm-assisted dose adjustment. Australia's TGA tightened electromagnetic-safety documentation requirements specifically for these wireless transmission capabilities, extending validation timelines for new market entrants.
- Patch Pumps:Adhesive-mounted disposable pumps eliminate tubing and reduce patient training burdens. Working-age diabetics across China's tier-one cities and Japan's metropolitan prefectures favor these wearable form factors for professional discretion during employment hours.
- Cartridge Pumps:Traditional reservoir-based systems with external tubing sets.
- Non-electronic Injectors:Spring-powered or purely mechanical dose delivery without power sources.
Smart pumps command premium pricing tiers; patch pumps climb the fastest on patient preference shifts.
Application:
Disease severity spectrum dictates device complexity requirements and reimbursement intensity.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive insulin therapy with precise dosing flexibility. Pump adoption concentrates among this population across Japan's pediatric endocrinology centers and Australia's specialized diabetes services, where intensive management protocols justify premium device expenditure.
- Type 2 Diabetes:Progressive insulin resistance drives escalating insulin requirements. China's expanding middle-aged diabetic population generates volume demand for pen systems as oral agent failure accelerates insulin initiation in primary care settings.
- Gestational Diabetes:Temporary insulin requirements during pregnancy.
- Prediabetes:Preventive intervention before insulin dependency.
Type 2 diabetes generates the largest patient base; Type 1 diabetes shows the steepest pump penetration trajectory.
End User:
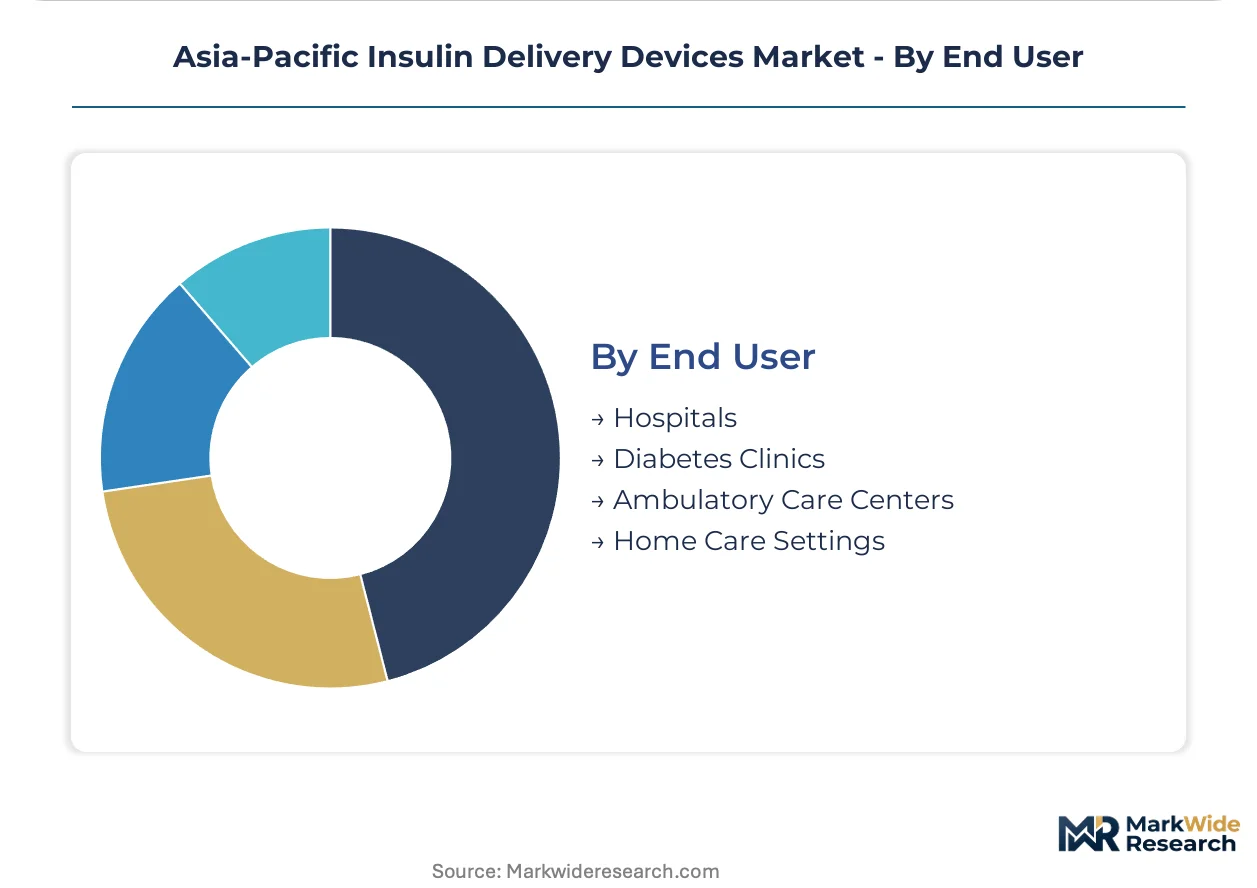
Care setting migration reconfigures procurement authority and service model requirements.
- Home Care Settings:Patient-directed administration outside clinical facilities. India's PLI scheme for domestic medical device manufacturing targets this segment with capital subsidies that reduce landed cost disadvantages for locally produced pen systems.
- Hospitals:Acute care facilities with centralized procurement committees. China's tier-one municipal hospital systems now demand unbundled after-sales service contracts separate from device capital expenditure, fragmenting vendor revenue recognition patterns.
- Diabetes Clinics:Specialized outpatient facilities with educator staffing.
- Ambulatory Care Centers:Intermediate settings between hospital and home.
Home care settings absorb the fastest volume expansion; hospitals retain concentrated negotiating leverage on price.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical device manufacturing is redrawing regional supply geography while China's NMPA streamlines approval pathways for connected devices. Japan's PMDA electromagnetic-safety frameworks and Australia's TGA biocompatibility standards create divergent compliance environments across the region.
China
China's tier-one municipal hospital systems drive volume demand for pen and pump systems through centralized procurement networks. The NMPA's reference to IEC 60601-1-10 for glucose monitoring interface compatibility accelerates smart pump market entry timelines for manufacturers. Shanghai and Beijing medical device clusters concentrate patch pump development targeting working-age diabetics seeking professional discretion.
India
India's retail pharmacy channels and expanding home care settings generate bulk purchasing for pen systems as insulin initiation accelerates in primary care. The CDSCO domestic manufacturing incentives under the PLI scheme offer capital subsidies that reduce landed cost disadvantages against imported devices. Gujarat and Maharashtra industrial corridors are scaling local production capacity for mechanical delivery systems.
Japan
Japan's pediatric endocrinology centers and specialized diabetes services concentrate pump adoption among Type 1 populations with intensive management protocols. The PMDA enforces stringent electromagnetic-safety standards that shape Bluetooth-enabled device development timelines and market entry costs. Tokyo and Osaka metropolitan prefectures favor wearable patch pump form factors for employed patient discretion.
Australia
Australia's TGA tightened electromagnetic-safety documentation requirements specifically for wireless transmission capabilities in wearable devices. Melbourne and Sydney clinical channel relationships anchor service infrastructure investments from multinational suppliers seeking reimbursement list placement. The country's diabetes educator workforce gaps create training capacity constraints that lag device deployment rates.
South Korea
South Korea's MFDS operates under evolving harmonization pathways that increasingly reference international standards for glucose monitoring interface compatibility. Seoul Capital Area medical centers demand unbundled after-sales service contracts separate from device capital expenditure. The country's rechargeable battery supply concentration supports compact patch pump manufacturing for regional export.
Asia-Pacific Insulin Delivery Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base clusters around three archetypes: integrated insulin-pump ecosystem operators, deep clinical channel incumbents, and compact wearable form factor innovators. Consolidation pressure intensifies as leasing and pay-per-use models tilt competitive dynamics toward firms with strong balance-sheet capacity. Strategic moves center on subscription-based pump access and Bluetooth-continuous glucose monitor convergence.
Within the integrated ecosystem tier, Novo Nordisk and Medtronic occupy positions that exemplify recurring revenue capture across multiple Asian markets. Ypsomed represents the compact wearable specialist archetype with rechargeable patch-pump designs. Among India-based manufacturers, Biocon sits within the domestic production tier capitalizing on PLI scheme incentives. These three anchors illustrate how regulatory compliance depth, service infrastructure scale, and form factor innovation define competitive positioning.
| Leading Market Players |
|---|
| Novo Nordisk |
| Medtronic |
| Sanofi |
| Eli Lilly and Company |
| Ypsomed |
| Becton Dickinson |
| Insulet |
| Abbott Laboratories |
| Biocon |
| Others |
Value Chain & Pricing Dynamics
Gujarat and Maharashtra industrial corridors anchor mechanical pen manufacturing capacity that feeds price-sensitive retail pharmacy channels across India and Southeast Asia. Their scaling output compresses landed costs for basic delivery systems while premium electromechanical platforms retain pricing power through proprietary algorithm ecosystems.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between commodity and premium tiers across Asia-Pacific procurement networks. Subscription-based pump access models are displacing capital expenditure structures, particularly in Japan's pediatric endocrinology centers and Australia's specialized diabetes services. Cost compression in standard pen systems intensifies as India's PLI scheme subsidizes domestic manufacturing. Hospital procurement committees exhibit lowest price sensitivity due to unbundled service contract requirements, while home care patients face highest upfront cost barriers.
Supply Chain Analysis
Tariff exposure between China and key Northeast Asian battery suppliers dominates supply chain risk calculus for patch pump manufacturers. Component sourcing concentrates in South Korea and Japan for specialized lithium polymer cells, with China handling precision molding and PCB assembly. Biocompatibility-grade silicone and medical-grade plastics draw from Japanese and German chemical suppliers. Single-source vulnerability in rechargeable battery supply creates procurement exposure. Distribution runs through hospital procurement committees in tier-one Chinese cities, retail pharmacy networks in India, and specialized diabetes clinics in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-continuous glucose monitor convergence is transforming insulin delivery from standalone hardware into platform-mediated disease management, creating winner-take-most dynamics around data ecosystem control.
For Market Incumbents: Insulate recurring revenue streams by deepening software companion development and locking hospital systems into unbundled service contracts. Acquire or partner with continuous glucose monitor specialists to close the data loop before closed-loop algorithms commoditize hardware margins. Defend against patch pump specialists by accelerating rechargeable form factor roadmaps. For New Entrants and Emerging Players: Establish a beachhead in India's home care settings by leveraging PLI scheme subsidies to undercut imported pen system pricing. Target gestational diabetes and prediabetes populations where insulin initiation protocols remain less entrenched than Type 1 intensive management. Pursue direct-to-patient subscription models that bypass hospital procurement gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease platform play because insulin delivery hardware becomes the customer acquisition vehicle for recurring data and algorithm revenue. Acquisition targets should display deep regulatory affairs capabilities across PMDA, NMPA, and CDSCO frameworks, plus established educator training networks. Watch for algorithm-driven dosing liability clarification as the signal indicating closed-loop system deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Navigating China's NMPA streamlined pathways and Japan's PMDA electromagnetic-safety requirements accelerates premium pump market access. |
| Software Companion Development | Bluetooth-enabled dose logging applications differentiate pens from commodity injection systems in physician remote monitoring workflows. |
| Hospital System Partnership | Unbundled after-sales service contracts with China's tier-one municipal hospitals fragment revenue recognition but lock in multi-year technical support commitments. |
| CE Marking Pathway | Harmonized European conformity assessment streamlines subsequent approvals through Australia's TGA and South Korea's MFDS. |
| Backward Integration into Battery Supply | Captive lithium polymer cell production mitigates Northeast Asian supplier concentration risk for compact patch pump designs. |
Study Parameters
Cross-validation between primary interviews with diabetes device executives and secondary validation through regulatory filing databases anchors the qualitative findings. The research incorporated conversations with hospital procurement managers, biomedical engineers, GPO contracts specialists, and diabetes educator program directors across China, India, Japan, and Australia. Secondary sources included NMPA approval databases, PMDA electromagnetic-safety guidance documents, CDSCO manufacturing incentive circulars, and TGA biocompatibility standards. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Calibration against historical volume trajectories and regulatory approval timelines shaped the analytical framework. Segmentation dimensions spanned product type (pen, pump, patch), connectivity tier (smart versus conventional), disease indication severity, and care setting migration patterns. CAGRs derived from fitted growth curves applied to patient population projections and device penetration assumptions. Key inputs included insulin initiation rates in primary care, reimbursement policy shifts toward outpatient management, and algorithm-driven dosing system regulatory pathways.
Stress conditions across battery supply disruptions, biocompatibility testing cost inflation, and educator workforce capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and home care reimbursement expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Diabetic Ulcers Treatment Market
Diabetes Care
Australia Continuous Glucose Monitoring Devices Market
Diabetes Care
Digital Diabetes Management Market
Diabetes Care
North America Insulin Infusion Pumps Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Digital Diabetes Market
Diabetes Care
Combination Anti-Diabetes Drugs Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
South Africa Self-Monitoring Blood Glucose Devices Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Mexico Diabetes Care Devices Market
Diabetes Care
Diabetic Lancing Devices Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market