
 France Self-Monitoring Blood Glucose Devices Market | 2026-2036
France Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Self-Monitoring Blood Glucose Devices Market Insights
Connected glucose monitoring platforms is reconfiguring how French patients and clinicians exchange metabolic data in real time. Roche Diabetes Care leverages its integrated digital ecosystem to sustain loyalty among endocrinology networks across Lyon and Marseille. Abbott Diabetes Care anchors its competitive position through FreeStyle Libre sensor technology, which dominates pharmacy reimbursement tiers. Ascensia Diabetes Care differentiates via Contour Next accuracy standards that align with HAS evaluation protocols.
Self-monitoring blood glucose devices comprise portable electrochemical or optical systems that quantify capillary glucose concentration through enzymatic reaction on disposable test strips or subcutaneous sensor filaments, primarily enabling diabetic patients to adjust insulin dosing, dietary intake, and physical activity outside clinical settings. Continuous glucose monitors capture the fastest structural expansion as French insurers broaden sensor reimbursement from Type 1 to select Type 2 cohorts. Fingerstick meters retain the largest installed base but face margin compression as pharmacy chains consolidate generic strip purchasing. Electrochemical technology leads the technology dimension due to its established accuracy profile and lower unit cost versus emerging optical alternatives.
ANSM enforces post-market surveillance and vigilance reporting for all active glucose sensors distributed in France, while CE marking under EU MDR mandates clinical evidence renewal for legacy devices previously cleared under the Medical Devices Directive. The national Haute Autorité de Santé (HAS) determines reimbursement eligibility through medical service benefit assessments that directly shape manufacturer pricing negotiations. Stakeholders must monitor whether France's stratégie nationale de lutte contre le diabète expands connected device subsidies to prediabetic populations.
Market Dynamics
Connected glucose monitoring platforms are collapsing the traditional separation between patient-generated data and clinical decision workflows, forcing reimbursement frameworks to adapt faster than institutional procurement cycles.
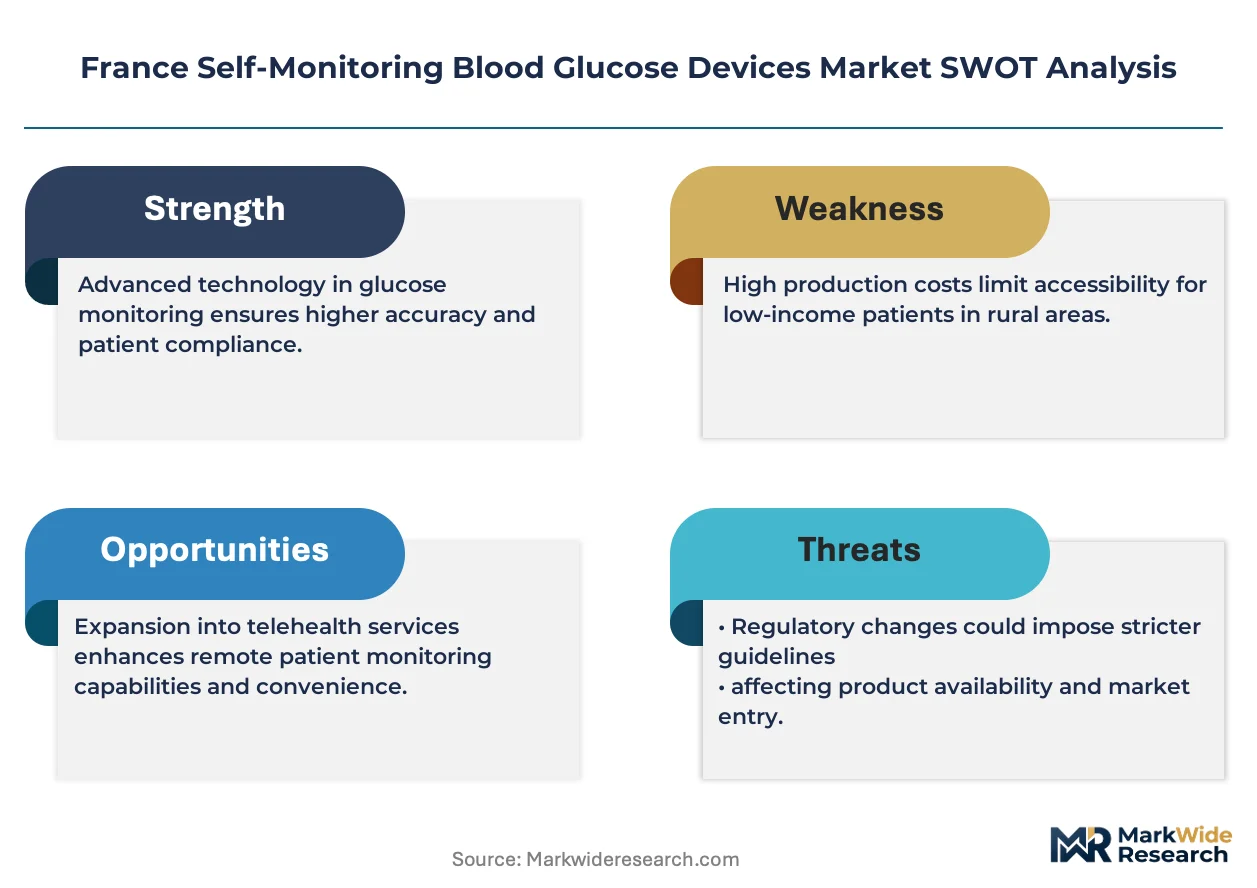
Growth Catalysts
- HAS Reimbursement Expansion:France's national health authority has broadened sensor coverage from Type 1 to select Type 2 diabetic cohorts, accelerating pharmacy dispensing volumes for continuous monitoring systems.
- Homecare Protocol Adoption:Patient self-management programs under the stratégie nationale de lutte contre le diabète are routing device procurement toward retail pharmacy channels and away from hospital-based distribution.
- Île-de-France Cluster Density:Paris-based hospital networks and pharmacy chains concentrate procurement volumes, creating demand gravity that pulls manufacturer inventory allocation toward the capital region.
Market Restraints
- EU MDR Clinical Evidence Burden:Legacy devices previously cleared under the Medical Devices Directive must renew clinical documentation, extending time-to-market for product iterations and freezing SKU rationalization decisions.
- Generic Strip Margin Compression:Pharmacy chain consolidation of test strip purchasing is squeezing unit economics for electrochemical fingerstick meter suppliers.
- Optical Sensor Cost Premium:Emerging photonic detection technologies carry manufacturing cost structures that remain above enzymatic electrochemical alternatives, limiting price-competitive positioning.
Strategic Opportunities
- Prediabetic Population Screening:France's national diabetes prevention program creates a pre-clinical addressable market for connected monitoring devices currently excluded from reimbursement tiers.
- Real-Time Data Integration:Convergence of continuous glucose monitors with insulin pump closed-loop systems is opening integrated therapy management contracts with endocrinology networks.
- Telemedicine Channel Development:Remote patient monitoring platforms are establishing direct-to-patient subscription models that bypass traditional pharmacy distribution markups.
Industry Challenges
- ANSM Vigilance Reporting Capacity:Post-market surveillance obligations for distributed active sensors require dedicated regulatory affairs staffing that mid-tier manufacturers struggle to maintain.
- Legacy Hospital IT Integration:Connected device data streams must interface with heterogeneous electronic health record systems across France's fragmented hospital network infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Self-Monitoring Blood Glucose Devices Market |
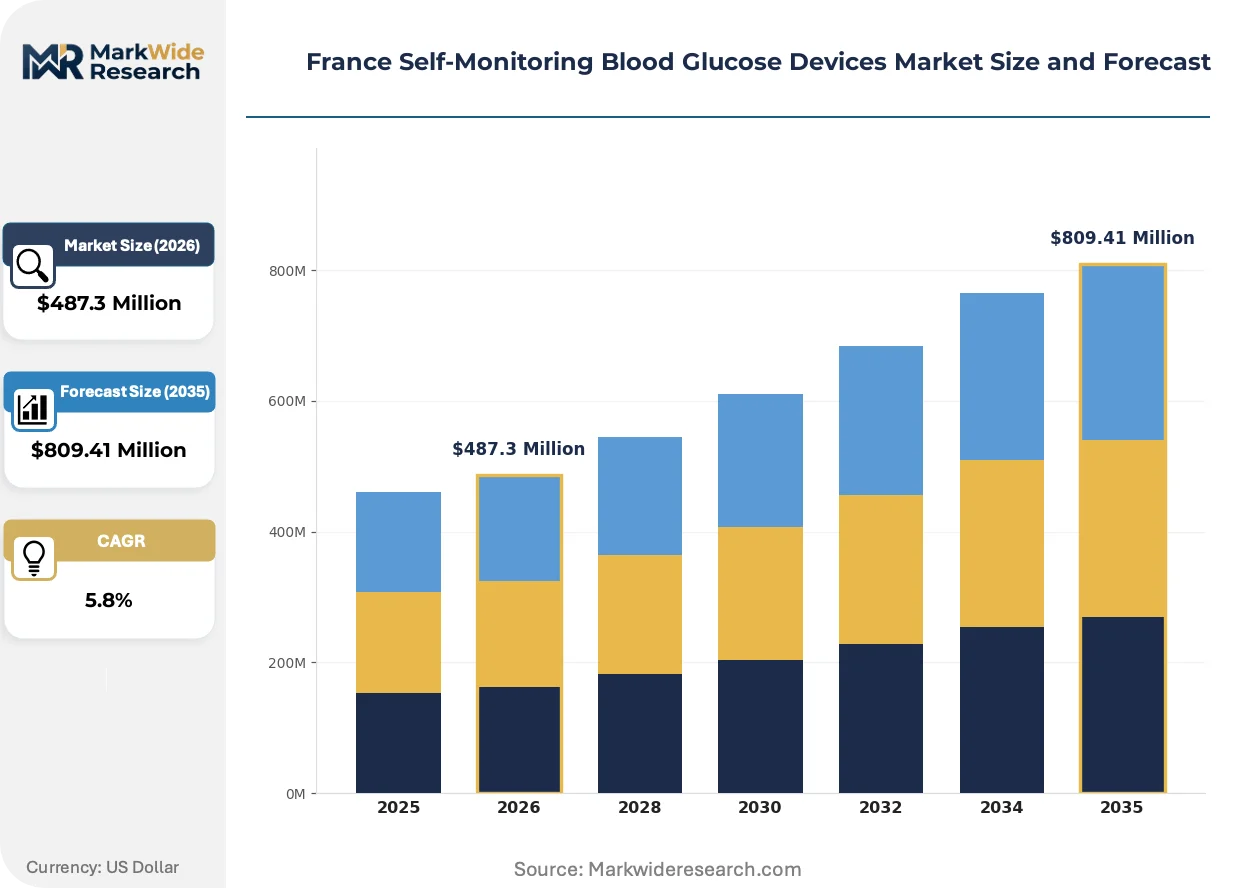
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerstick Meters, Continuous Glucose Monitors, Smart Meters, Test Strips Technology: Electrochemical, Optical, RFID, Infrared End User: Homecare, Hospitals, Clinics, Pharmacies Distribution Channel: Retail Pharmacies, Online Stores, Hospital Sales, Medical Supply Distributors |
| Companies Covered | LifeScan, Bionime Corporation, Roche Diabetes Care, Acon Laboratories, AgaMatrix Inc, Abbott Diabetes Care, Arkray, Trivida Functional Medicine, Ascensia Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Data interoperability standards and algorithmic glucose prediction are converging to transform self-monitoring from episodic measurement into continuous metabolic management.
Factory-calibrated continuous glucose sensors are collapsing the calibration burden that previously limited patient adherence and clinical trust. Endocrinology practices in Lyon and Marseille are adopting these systems at pace, replacing fingerstick protocols for insulin-dependent patients. The structural consequence is compressing revenue per patient for test strip manufacturers while expanding total addressable spend for sensor-integrated therapy platforms.
CE marking transition under EU MDR is forcing manufacturers to regenerate clinical evidence packages for legacy glucose monitoring devices. The industrial consequence is freezing product pipeline decisions as firms prioritize MDR compliance over feature development. Devices with predicate approvals under the old Medical Devices Directive face the most severe timeline pressure, with some SKUs facing market withdrawal rather than renewal investment.
Pharmacy chains are consolidating generic test strip purchasing through central procurement offices, displacing the fragmented store-level ordering that previously sustained multiple supplier relationships. This concentration is most visible in the Île-de-France region, where Paris-based retail networks negotiate volume-based contracts that exclude smaller strip manufacturers from shelf access.
France Self-Monitoring Blood Glucose Devices Market Segmentation
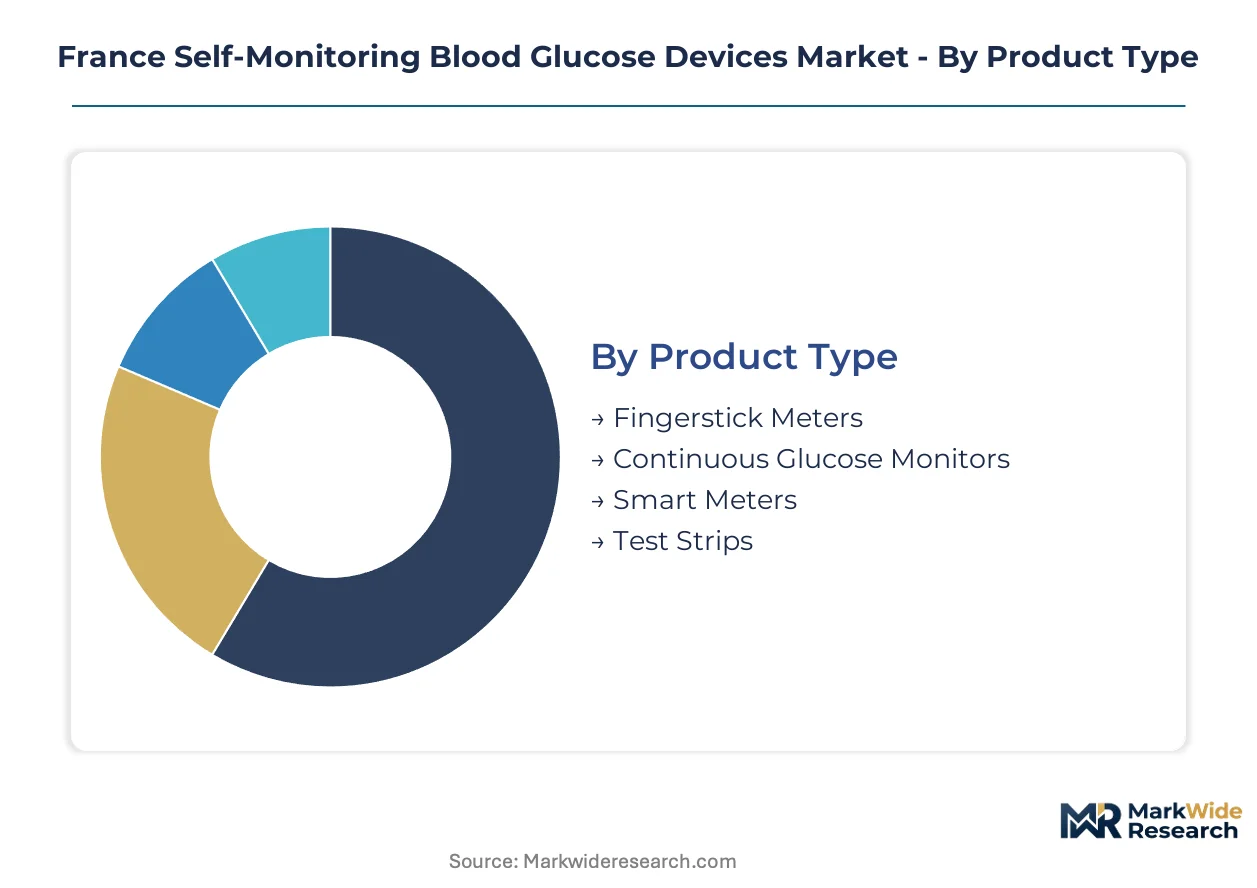
Segmentation reveals how reimbursement tiers, technology transitions, and procurement channel shifts are fragmenting demand across distinct patient populations and care settings in France. Understanding these divides clarifies where manufacturers must align product specifications with HAS evaluation protocols versus pharmacy margin expectations.
Product Type:
Mature electrochemical systems dominate installed base economics while emerging sensor platforms capture policy-enabled expansion.
- Fingerstick Meters:Portable enzymatic devices requiring disposable test strips for capillary glucose quantification. Demand concentrates in Île-de-France retail pharmacies serving Type 2 patients excluded from continuous monitoring reimbursement, though generic strip consolidation is compressing supplier margins.
- Continuous Glucose Monitors:Factory-calibrated subcutaneous sensors transmitting real-time glucose data to receivers or smartphones. HAS reimbursement expansion for select Type 2 cohorts is accelerating dispensing volumes through Lyon and Marseille endocrinology networks, displacing fingerstick protocols for insulin-dependent patients.
- Smart Meters:Connected devices with Bluetooth data transmission to mobile applications and cloud platforms.
- Test Strips:Disposable enzymatic reagents enabling glucose oxidation measurement in fingerstick meters.
Fingerstick meters retain volume leadership; continuous glucose monitors hold the steepest expansion curve.
Technology:
Cost tier differentiation separates established manufacturing methods from emerging photonic alternatives seeking clinical validation.
- Electrochemical:Enzymatic glucose oxidation producing measurable current response on disposable electrodes. Homecare procurement through France's stratégie nationale de lutte contre le diabète favors this technology for its established accuracy profile and lower per-test cost versus optical alternatives.
- Optical:Photonic detection methods including near-infrared spectroscopy and Raman scattering for non-invasive or minimally invasive glucose measurement. Manufacturing cost structures remain above electrochemical alternatives, limiting competitive positioning in price-sensitive pharmacy channels.
- RFID:Radio-frequency identification enabling automated lot tracking and calibration code transmission between strips and meters.
- Infrared:Spectroscopic methods targeting transdermal glucose measurement without blood sample extraction.
Electrochemical technology commands current procurement volumes; optical platforms face cost barriers to mainstream adoption.
End User:
Application context determines whether devices require hospital IT integration or standalone patient operation.
- Homecare:Patient-directed monitoring outside clinical supervision for insulin dosing and lifestyle adjustment. The stratégie nationale de lutte contre le diabète is routing device procurement toward retail pharmacy channels and away from hospital-based distribution, expanding this segment's addressable population.
- Hospitals:Inpatient glycemic management requiring integration with electronic health record systems. Paris-based hospital networks concentrate procurement volumes but face legacy IT infrastructure fragmentation that complicates connected device deployment.
- Clinics:Outpatient endocrinology practices managing stable diabetic populations.
- Pharmacies:Point-of-care screening and device dispensing with reimbursement processing.
Homecare settings are gaining share fastest; hospitals retain concentrated purchasing power despite integration friction.
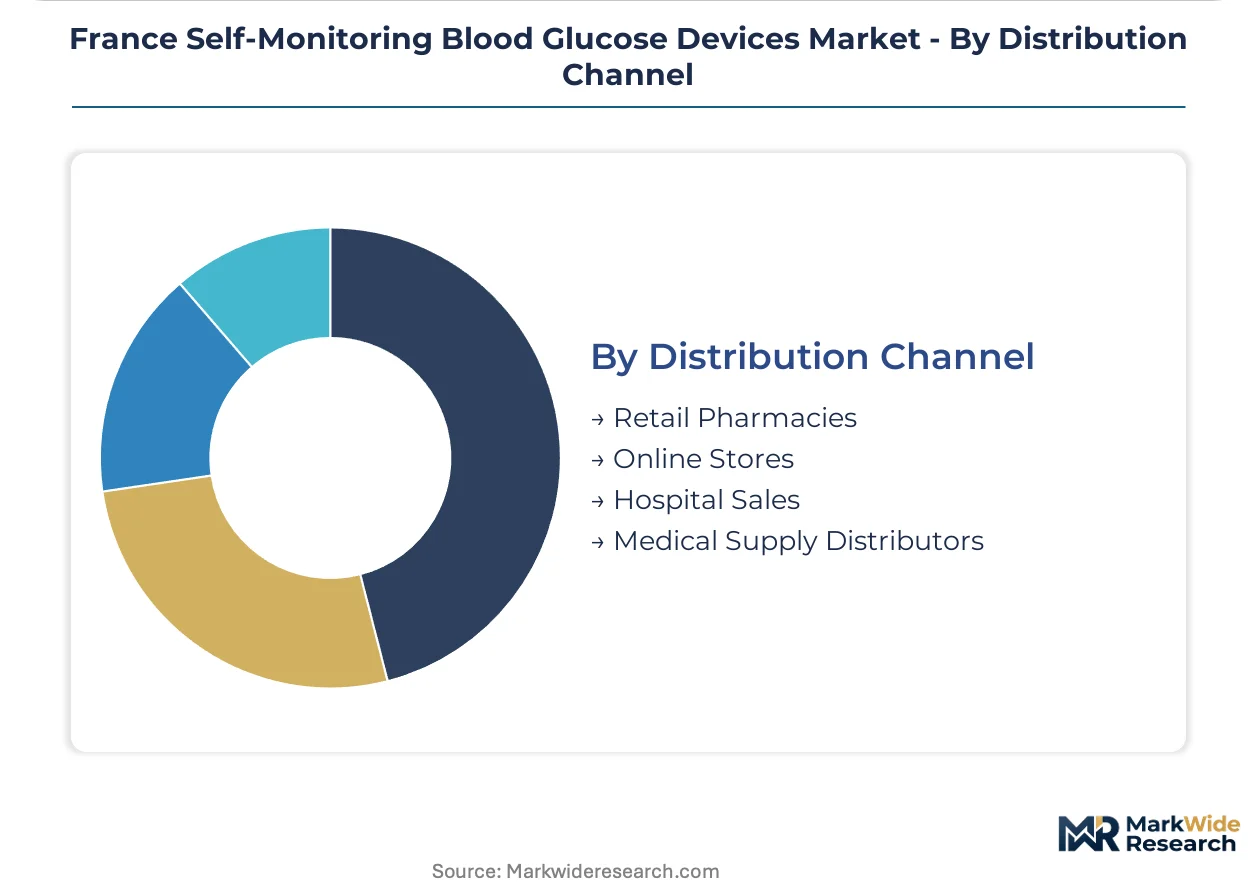
Distribution Channel:
Customer type concentration shapes whether procurement flows through centralized negotiation or fragmented store-level ordering.
- Retail Pharmacies:Brick-and-mortar dispensing with HAS reimbursement processing and patient counseling. Central procurement offices in Île-de-France retail networks are consolidating test strip purchasing through volume-based contracts that exclude smaller manufacturers from shelf access.
- Online Stores:Direct-to-patient platforms bypassing traditional pharmacy markups through subscription models. Remote patient monitoring platforms are establishing digital-first distribution that challenges incumbent channel economics.
- Hospital Sales:Institutional procurement through group purchasing organizations and hospital pharmacy committees.
- Medical Supply Distributors:Wholesale intermediaries serving clinics and smaller healthcare facilities.
Retail pharmacies retain volume leadership; online stores are climbing the fastest as telemedicine channels mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical device exporters supply sensor technology to French hospital procurement networks, while Swiss manufacturers route precision components through Lyon distribution hubs into the domestic market.
Île-de-France
Paris-based hospital networks and pharmacy chains anchor national procurement volumes for glucose monitoring devices. ANSM post-market surveillance requirements concentrate regulatory affairs staffing in this region. The capital's endocrinology practices are adopting factory-calibrated continuous glucose sensors at pace, displacing traditional fingerstick protocols for insulin-dependent patients.
Auvergne-Rhône-Alpes
Lyon's medical technology cluster hosts distribution infrastructure for German and Swiss component suppliers serving eastern France. The EU MDR clinical evidence burden affects device registration timelines for manufacturers operating through this logistics corridor. Regional hospital networks here are integrating connected glucose monitors with electronic health record systems ahead of national averages.
Provence-Alpes-Côte d'Azur
Marseille endocrinology networks are expanding continuous monitoring adoption among Type 2 diabetic cohorts newly eligible under HAS reimbursement protocols. The stratégie nationale de lutte contre le diabète routes self-management device procurement through retail pharmacy channels concentrated in this coastal region. Local clinicians are piloting real-time data integration with insulin pump closed-loop systems.
Hauts-de-France
Pharmacy chain consolidation of generic test strip purchasing is most visible in Lille-based retail networks negotiating volume-based contracts. This northern region's proximity to Belgian distribution hubs creates cross-border procurement alternatives for hospital purchasing committees. Electrochemical fingerstick meters retain installed base dominance here among Type 2 populations excluded from sensor reimbursement tiers.
Nouvelle-Aquitaine
Bordeaux-area homecare settings are expanding device adoption as patient self-management protocols gain traction under France's national diabetes program. Regional telemedicine platforms are establishing direct-to-patient subscription models that bypass traditional pharmacy distribution markups. The area's aging demographic profile sustains demand for simplified meter interfaces designed for elderly diabetic populations.
France Self-Monitoring Blood Glucose Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated therapy platforms that bundle sensors with data analytics capabilities. The competitive terrain separates legacy fingerstick meter suppliers facing margin compression from sensor-integrated platform developers capturing reimbursement-enabled expansion. Three archetypes dominate: multinational diagnostics conglomerates with digital ecosystems, mid-tier accuracy-focused specialists, and emerging telemedicine-integrated challengers. Dominant competitive moves include M&A activity targeting connected health capabilities and strategic partnerships with pharmacy chains for distribution access.
Among multinational diagnostics conglomerates, Roche Diabetes Care and Abbott Diabetes Care exemplify the integrated platform archetype, anchoring competitive positioning through digital ecosystem development and sensor technology advancement respectively. Ascensia Diabetes Care occupies a distinct accuracy-specialist tier, aligning product specifications with HAS evaluation protocols. These three companies represent the dominant supply-side configurations shaping procurement negotiations with French hospital networks and pharmacy chains.
| Leading Market Players |
|---|
| LifeScan |
| Bionime Corporation |
| Roche Diabetes Care |
| Acon Laboratories |
| AgaMatrix Inc |
| Abbott Diabetes Care |
| Arkray |
| Trivida Functional Medicine |
| Ascensia Diabetes Care |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in electrochemical test strip manufacturing across Western Europe is compressing unit economics for suppliers while forcing pricing discipline on sensor-integrated platform developers seeking pharmacy formulary placement. Factory utilization rates below optimal thresholds in German and Swiss component plants are driving inventory liquidation tactics that ripple through French procurement negotiations.
Pricing Analysis
The technology-generation pricing gap separates legacy fingerstick systems from factory-calibrated continuous monitors and emerging optical platforms. Three-tier pricing structure across premium sensor-integrated, standard connected meters, and economy generic strips dominates procurement. Price differentiation rests on HAS reimbursement tier alignment and pharmacy chain volume scale. Cost compression in test strips is intensifying because central procurement offices in Île-de-France retail networks are consolidating supplier relationships. Type 2 patients excluded from sensor reimbursement tiers exhibit highest price sensitivity; insulin-dependent cohorts accessing HAS-covered continuous monitoring show lowest elasticity.
Supply Chain Analysis
EU dual-use export controls on advanced photonic detection components limit flows of precision sensor substrates from Swiss and German manufacturers to French assembly facilities. Geographic supply concentration centers on Germany for electrochemical electrode substrates, Switzerland for precision sensor filaments, and Ireland for Bluetooth-enabled microcontroller units. Raw material dependencies include glucose oxidase enzymes, noble metal electrode coatings, and medical-grade polymer sensor housings. Single-source vulnerability in enzyme supply from Danish biotech specialists threatens production continuity. Distribution runs through centralized pharmacy procurement offices in Paris and Lyon, bypassing fragmented store-level ordering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's self-monitoring blood glucose market constitutes a defensive-moat opportunity anchored in regulatory entrenchment. HAS reimbursement protocols and ANSM vigilance requirements create switching costs that protect incumbent positions while raising barriers for unvalidated entrants.
For Market Incumbents: Pre-empt margin erosion in test strips by accelerating backward integration into enzyme production and securing exclusive pharmacy chain partnerships in Auvergne-Rhône-Alpes. Consolidation of generic strip purchasing by Île-de-France retail networks threatens supplier shelf access. Investment in CE marking renewal under EU MDR preserves market presence against regulatory forced exit. For New Entrants and Emerging Players: Prediabetic population screening in Nouvelle-Aquitaine offers addressable white space outside current reimbursement tiers. Telemedicine-integrated subscription models bypass pharmacy markup structures and capture direct patient relationships. Target Bordeaux-area homecare settings with simplified elderly-optimized interfaces as the most penetrable segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated platform developers with closed-loop insulin pump compatibility. Long-term viability across the analysis window favors manufacturers with demonstrated HAS negotiation track records and established endocrinology network relationships. Watch for ANSM guidance expansion on prediabetic monitoring subsidies as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance renewal preserves market access for legacy glucose monitoring portfolios. |
| Hospital System Partnership | Integration with Paris-based electronic health record networks secures institutional procurement preference. |
| Reimbursement Strategy | HAS medical service benefit alignment determines pharmacy formulary placement and pricing authority. |
| Software Companion Development | Mobile application ecosystems sustain patient adherence and generate real-world evidence for regulators. |
| Distribution Channel Expansion | Direct-to-patient telemedicine platforms bypass pharmacy consolidation and capture subscription revenue. |
Research Methodology
Desk research of EU MDR guidance documents, ANSM vigilance databases, and HAS medical service benefit assessments preceded structured interviews with hospital procurement managers, pharmacy chain category directors, endocrinology practice administrators, and biomedical engineering specialists. Primary fieldwork across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur validated secondary findings from hospital procurement databases, GPO contracts, and pharmacy dispensing records. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Assumptions held fixed include HAS reimbursement tier structures, EU MDR enforcement timelines, and sensor accuracy standards under ISO 15197; varied parameters encompassed prediabetic program expansion scope and pharmacy chain consolidation velocity. The analytical framework modeled product type, technology generation, end-user setting, and distribution channel across the projection horizon. CAGRs derived from patient population growth, reimbursement policy shifts, and technology substitution curves. Forecast inputs included insulin-dependent patient counts, sensor wear duration assumptions, and test strip consumption rates per patient.
Macroeconomic conditions sit as an overlay; deviation in eurozone healthcare expenditure growth or French social security deficit trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and reimbursement continuity. Material shifts in ANSM vigilance enforcement intensity or HAS evaluation protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Global Insulin Infusion Pumps Market
Diabetes Care
Global Non-Invasive Glucose Meter Market
Diabetes Care
Diabetes Care Devices and Drugs Market
Diabetes Care
Brazil Blood Glucose Monitoring Market
Diabetes Care
Global Continuous Subcutaneous Insulin Infusion Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Global Smart Insulin Pens Market
Diabetes Care
India Oral Anti-Diabetic Drug Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Global Type 2 Diabetes Treatment Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
US Continuous Glucose Monitoring Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Asia Pacific Blood Glucose Monitoring Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Europe Insulin Infusion Pumps Market