
 Tamiflu (Oseltamivir Phosphate) Market | 2026-2036
Tamiflu (Oseltamivir Phosphate) Market Size, Share, and Industry Trends Forecast 2026-2036
Tamiflu (Oseltamivir Phosphate) Market Analytics
Indian generic API manufacturers is recalibrating global supply allocations as post-pandemic inventory normalization compresses spot pricing. F. Hoffmann-La Roche Ltd. anchors branded originator positioning through sustained intellectual property enforcement in regulated markets. LUPIN Limited leverages vertically integrated fermentation capacity to compete on oseltamivir phosphate intermediate cost structures. Hetero Group dominates bulk API exports to government procurement channels across Southeast Asia and Latin America.
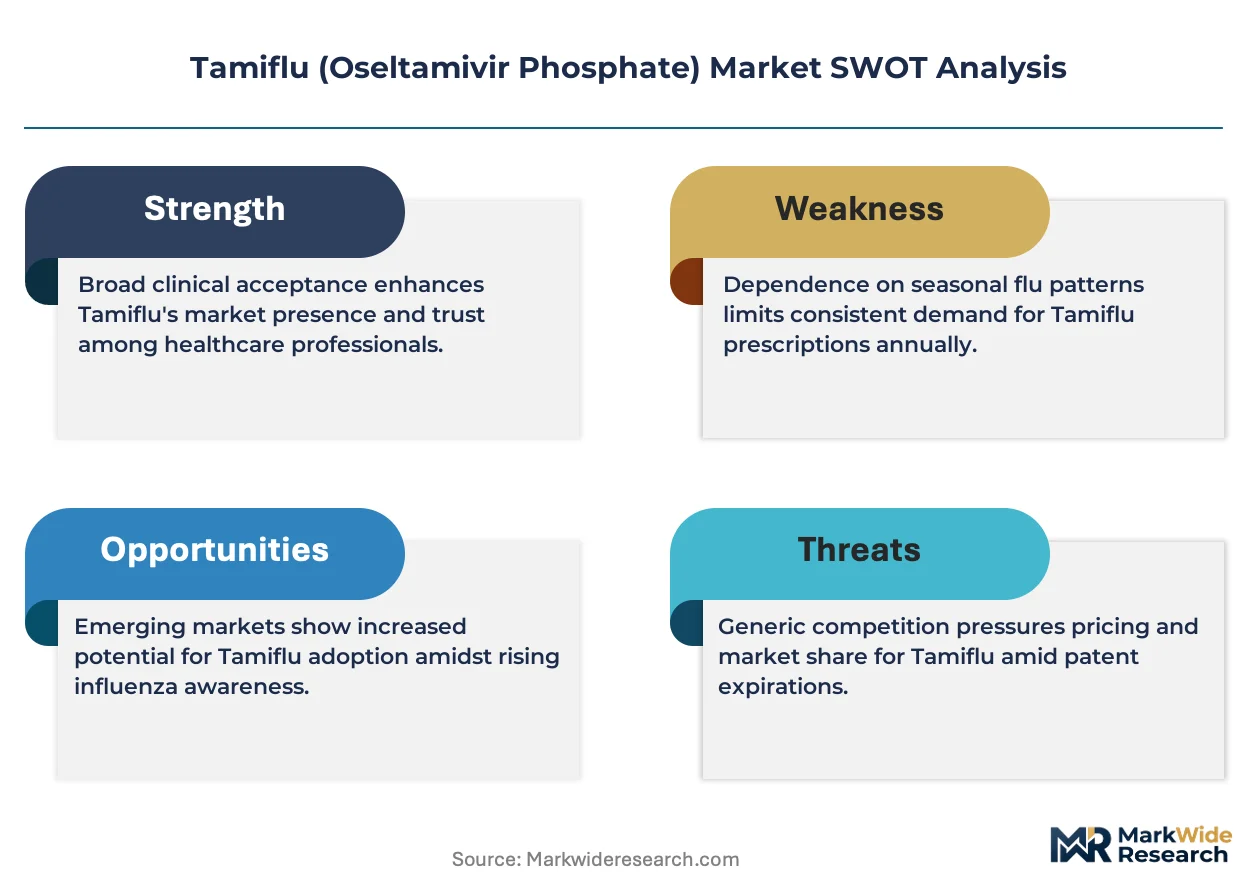
Tamiflu (oseltamivir phosphate) is a neuraminidase inhibitor prodrug, administered as the phosphate salt with oral bioavailability exceeding 75 percent, functioning to block viral release from infected host cells and reduce influenza symptom duration. The compound serves primarily as a first-line pharmaceutical intervention against influenza A and B infections in both therapeutic and prophylactic protocols. Capsule formulations occupy the largest revenue share due to adult outpatient convenience and pharmacy dispensing efficiency, while oral suspension demand accelerates fastest within pediatric applications where weight-based dosing requirements predominate. Hospital setting procurement represents a concentrated margin pool driven by institutional formulary contracts and pandemic stockpiling obligations.
FDA bioequivalence standards and WHO prequalification requirements govern generic oseltamivir market access, with India's CDSCO enforcing parallel GMP inspections on export-oriented facilities. The EMA's centralized marketing authorization pathway constrains rapid European generic entry, preserving pricing premiums for qualified suppliers. Stakeholders must monitor national pandemic preparedness fund allocations and seasonal influenza surveillance thresholds to align manufacturing capacity with unpredictable demand surges.
Market Dynamics
Post-pandemic inventory normalization is compressing spot pricing for oseltamivir phosphate API, forcing manufacturers to recalibrate fermentation capacity toward government stockpiling contracts rather than commercial spot markets. This structural pressure is reshaping competitive positioning between vertically integrated Indian suppliers and originator-dependent European formulators.
Growth Catalysts
- CDC Stockpiling Protocols:United States federal pandemic preparedness mandates sustain procurement volumes through strategic national reserve replenishment cycles, insulating domestic demand from seasonal fluctuation.
- Pediatric Formulation Gaps:Weight-based oral suspension requirements in children under one year create persistent demand for liquid dosage forms where capsule alternatives face bioavailability constraints.
- EMA Centralized Marketing Authorization:The European pathway preserves pricing premiums for qualified generic suppliers who achieve bioequivalence certification, rewarding compliance investment with sustained margin pools.
Market Restraints
- Fermentation Input Volatility:Shikimic acid supply concentration in Chinese star anise extraction creates cost structure vulnerability during agricultural harvest disruption.
- API Export Concentration:Indian CDSCO-regulated facilities dominate bulk phosphate intermediate production, concentrating supply risk within a single geographic regulatory jurisdiction.
- Neuraminidase Resistance Mutation:Circulating influenza A H1N1 variants with H275Y substitution reduce clinical efficacy, threatening protocol confidence against alternative antiviral classes.
Strategic Opportunities
- Southeast Asia Government Procurement:Vietnam, Indonesia, and Philippines national health systems are expanding influenza antiviral inclusion in essential medicines lists with limited domestic manufacturing capacity.
- WHO Prequalification Pathway:The UN procurement mechanism opens institutional access for CDSCO-inspected facilities meeting international GMP standards, bypassing fragmented national registration requirements.
- Combination Antiviral Development:Fixed-dose pairing of oseltamivir with baloxavir marboxil is absorbing clinical trial investment from NIH and EMA innovation frameworks targeting resistant strain coverage.
Industry Challenges
- Specialized Fermentation Expertise Scarcity:API synthesis requires microbial cultivation capabilities distinct from standard chemical synthesis, constraining capacity expansion to qualified bioprocessing facilities.
- Bioequivalence Study Timeline Compression:FDA 505(j) abbreviated new drug application requirements demand pharmacokinetic bridging studies that extend generic market entry by 18-24 months beyond API availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tamiflu (Oseltamivir Phosphate) Market |
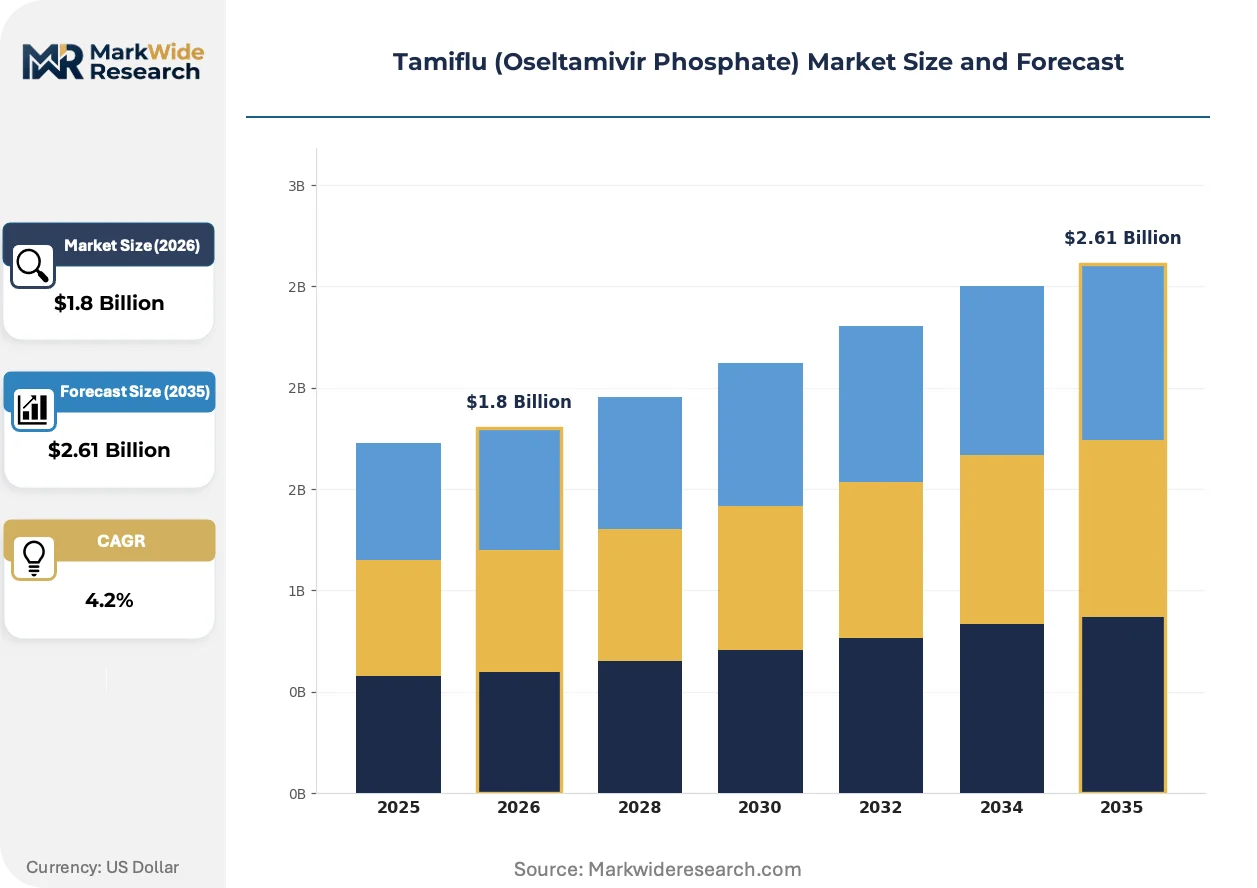
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Suspension, Injectable, Tablet Application: Influenza Treatment, Prophylaxis, Pediatric Use, Hospital Setting End User: Pharmacies, Hospitals, Clinics, Home Care Delivery Mode: Oral, Intravenous, Subcutaneous, Nasal |
| Companies Covered | LUPIN Limited, Zydus Cadila, F. Hoffmann-La Roche Ltd., Alembic Pharmaceuticals Limited, Sun Pharmaceutical Industries Ltd., NATCO Pharma Limited, Amneal Pharmaceuticals LLC, Hetero Group, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tamiflu (Oseltamivir Phosphate) Market Evolving Landscape
Continuous manufacturing technologies and regulatory science advances are compressing development timelines while pandemic preparedness frameworks institutionalize demand unpredictability as a permanent structural feature.
Continuous flow chemistry for oseltamivir phosphate synthesis is absorbing capital allocation from batch reactor infrastructure at CDSCO-inspected facilities in Hyderabad and Ahmedabad. Contract development organizations serving European formulators are adopting modular skid-mounted systems to reduce solvent waste and accelerate technology transfer. This process intensification is absorbing quality-by-design principles that compress validation timelines for WHO prequalification submissions.
EMA's revised guideline on influenza antiviral bioequivalence now permits pharmacodynamic endpoints in healthy volunteer studies, reducing reliance on clinical endpoint trials that previously extended generic approval timelines. The industrial consequence is accelerated European generic entry for Indian API suppliers meeting the new statistical criteria. Hospital procurement offices in Germany and France are responding by consolidating annual tenders around prequalified suppliers with demonstrated surge capacity.
Hospital formulary committees are consolidating influenza antiviral purchasing through prime vendor agreements that bundle neuraminidase inhibitors with respiratory syncytial virus prophylaxis portfolios. This channel consolidation is displacing independent pharmacy purchasing in the United States acute care segment, concentrating volume with distributors demonstrating pandemic surge logistics capabilities. The behavioral shift is most visible in CDC-funded hospital preparedness program jurisdictions where stockpiling compliance audits now evaluate vendor redundancy rather than sole-source relationships.
Tamiflu (Oseltamivir Phosphate) Market Segmentation
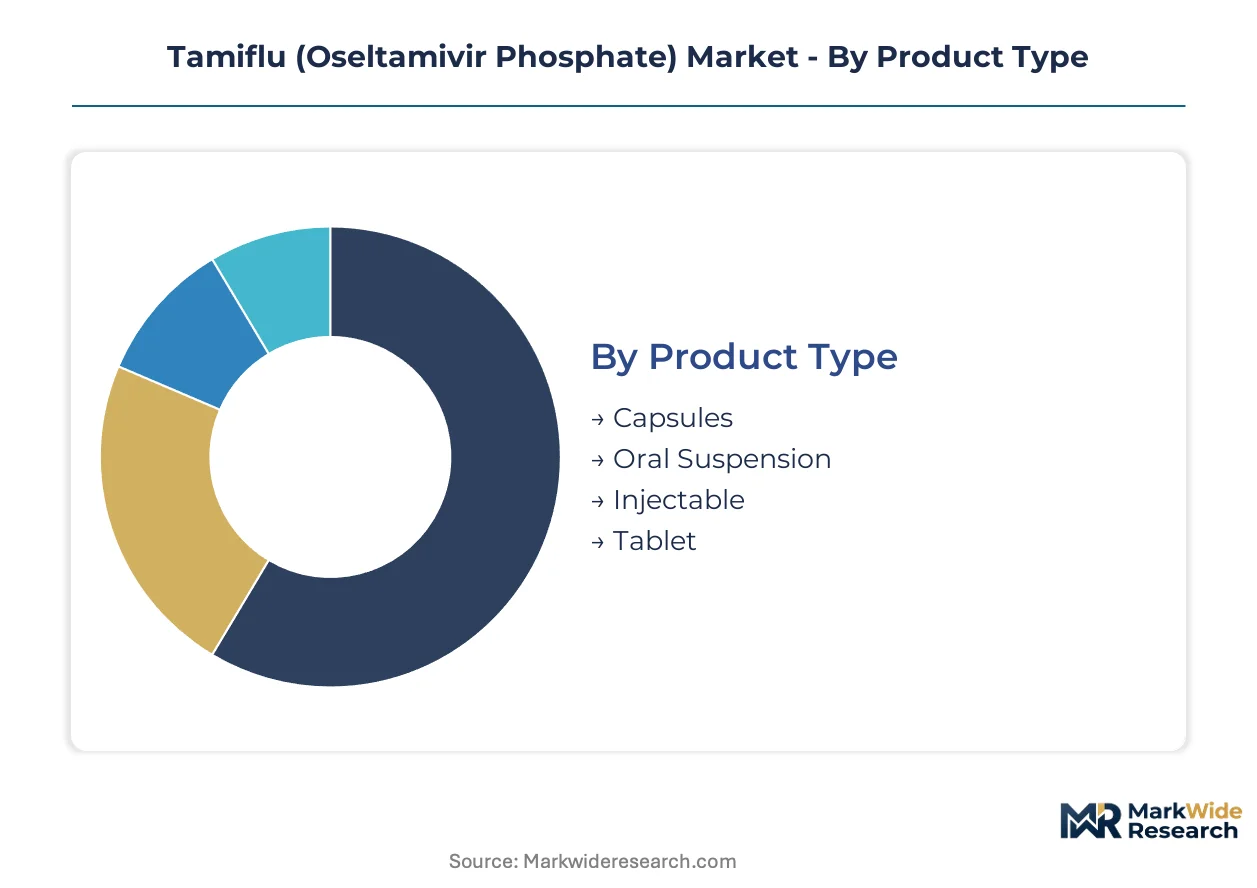
Formulation chemistry and patient population characteristics create distinct manufacturing and distribution requirements across oseltamivir phosphate product categories. Segmentation reveals how procurement channels, dosing protocols, and administration settings fragment demand into addressable commercial pockets.
Product Type:
The customization-to-standardization spectrum runs from weight-calibrated pediatric suspensions to mass-manufactured adult capsules, with injectable formats demanding specialized sterile infrastructure.
- Capsules:Hard gelatin shells containing 30mg, 45mg, or 75mg oseltamivir phosphate deliver precise unit dosing for adult outpatient protocols. United States retail pharmacy chains favor this format for inventory efficiency and patient adherence convenience, driving volume concentration in CDC stockpiling contracts.
- Oral Suspension:Reconstitutable powder formulations enable weight-based mg/kg dosing critical for patients under one year. Pediatric vaccination gaps in United States immunization schedules sustain demand for liquid alternatives where capsule swallowing capacity is undeveloped.
- Injectable:Intravenous solutions serve hospitalized patients with severe influenza unable to tolerate oral intake. Manufacturing requires aseptic fill-finish capabilities distinct from standard solid dosage infrastructure.
- Tablet:Compressed dosage forms offer alternative oral delivery where capsule shell excipients trigger intolerance. European formulators occasionally specify this format for institutional tender compliance.
Leading the category by volume: Capsules. Growing fastest: Oral Suspension.
Application:
Clinical intent shapes dosing duration, procurement authorization levels, and regulatory documentation requirements across therapeutic versus preventive use cases.
- Influenza Treatment:Five-day therapeutic courses initiated within 48 hours of symptom onset reduce viral shedding duration. Hospital emergency departments in United States pandemic preparedness jurisdictions concentrate demand through syndromic surveillance-triggered protocols.
- Prophylaxis:Extended-duration regimens protect unvaccinated household contacts and institutional outbreak containment scenarios. Long-term care facilities in Germany and France specify this application for seasonal staff protection mandates.
- Pediatric Use:Modified dosing schedules and formulation requirements address pharmacokinetic differences in immature hepatic enzyme systems. Weight-band dosing tables complicate pharmacy dispensing workflows versus adult fixed-dose protocols.
- Hospital Setting:Critical care applications demand intravenous alternatives and rapid therapeutic substitution protocols. Institutional formularies in United States acute care networks bundle neuraminidase inhibitors with respiratory antiviral portfolios.
Volume concentrates in Influenza Treatment. Steepest expansion trajectory: Hospital Setting procurement.
End User:
Channel structure fragments between decentralized retail access and consolidated institutional purchasing with divergent margin and logistics requirements.
- Pharmacies:Community and retail dispensaries handle outpatient prescriptions with seasonal demand surges straining inventory forecasting. United States independent pharmacies compete with chain networks on CDC-funded emergency dispensing authorization.
- Hospitals:Acute care institutions command concentrated purchasing power through prime vendor agreements and pandemic stockpiling compliance audits. Formulary committees evaluate vendor surge capacity alongside unit pricing.
- Clinics:Outpatient medical offices serve intermediate acuity patients with rapid diagnostic testing capabilities. Urgent care networks in United States metropolitan areas drive same-day prescribing volumes.
- Home Care:Post-acute and long-term residential settings administer extended prophylaxis regimens for vulnerable populations. Skilled nursing facilities in Japan specify this channel for institutional outbreak containment protocols.
Hospitals dominate procurement value. Home Care is climbing the fastest on aging population demographics.
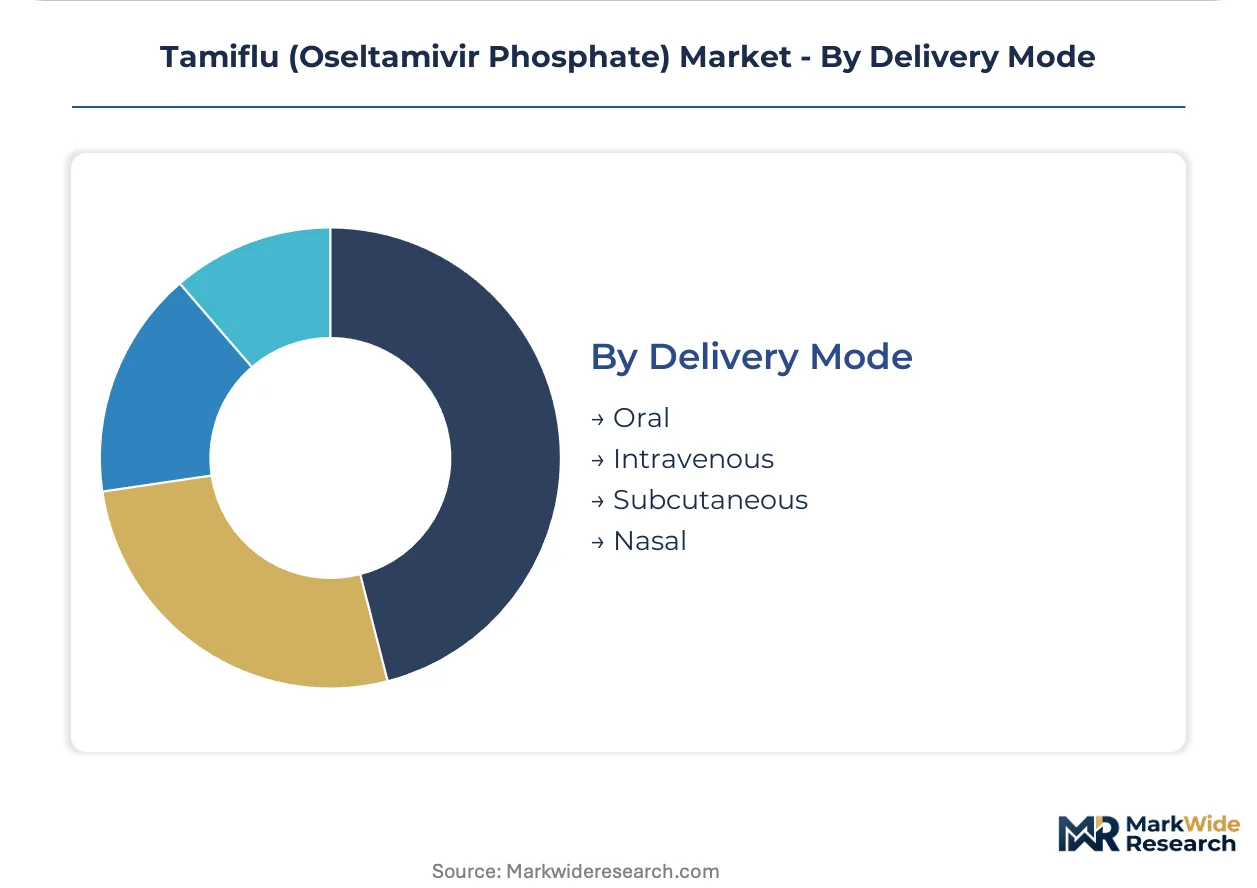
Delivery Mode:
Administrative route selection reflects patient consciousness status, gastrointestinal tolerance, and therapeutic urgency within clinical workflows.
- Oral:Capsule and liquid ingestion routes leverage established gastrointestinal absorption with bioavailability exceeding 75 percent. Outpatient convenience drives preference where swallowing capacity and intestinal function remain intact.
- Intravenous:Direct vascular administration bypasses compromised absorption in critical illness states. Manufacturing requires sterile injectable capacity with endotoxin control specifications.
- Subcutaneous:Tissue depot injection offers alternative parenteral access where vascular cannulation is impractical. Limited current application in neuraminidase inhibitor protocols.
- Nasal:Mucosal absorption pathways remain investigational for oseltamivir phosphate due to molecular weight constraints. Preclinical formulation development continues at CDSCO-inspected contract research organizations.
Oral delivery commands absolute volume share. Intravenous is gaining share fastest on hospital formulary consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Star anise cultivation in southern China anchors shikimic acid supply chains that feed oseltamivir phosphate synthesis worldwide. Indian fermentation clusters process this feedstock into API intermediates for formulation across regulated markets. Government stockpiling programs in North America and Europe absorb contracted volumes ahead of seasonal demand surges.
United States
CDC strategic national stockpile replenishment cycles sustain procurement volumes independent of seasonal influenza severity. FDA emergency use authorization frameworks obligate manufacturers to maintain surge manufacturing readiness. New Jersey and Massachusetts pharmaceutical corridors host formulation facilities serving hospital prime vendor contracts.
India
CDSCO-inspected fermentation facilities in Hyderabad and Ahmedabad dominate bulk oseltamivir phosphate intermediate production for export markets. Government procurement channels across Southeast Asia and Latin America source API from Indian suppliers meeting WHO prequalification standards. Telangana's bioprocessing cluster absorbs capital allocation toward continuous flow chemistry infrastructure.
Germany
EMA centralized marketing authorization requirements preserve pricing premiums for qualified generic suppliers achieving bioequivalence certification. Hospital formulary committees in Bavaria and North Rhine-Westphalia consolidate influenza antiviral purchasing through prime vendor agreements. Berlin-based regulatory consultancies guide Indian API suppliers through European generic entry pathways.
Japan
PMDA seasonal influenza surveillance thresholds trigger national stockpiling replenishment from domestic and imported sources. Long-term care facilities administer extended prophylaxis regimens for institutional outbreak containment. Osaka pharmaceutical manufacturing zones formulate pediatric oral suspensions for regional distribution.
Brazil
ANVISA national essential medicines list inclusion expands influenza antiviral access through public health system procurement. São Paulo state hospital networks concentrate demand for therapeutic and prophylactic protocols. Local distributors bridge supply from Indian API exporters to government tender channels.
Tamiflu (Oseltamivir Phosphate) Market Competitive Landscape
Global majors compete with regional champions across API supply and finished dosage formulation. The market structures around originator brand defense in regulated markets and generic volume capture in emerging economies. Three archetypes dominate: vertically integrated Indian API-to-formulation suppliers, European originator-dependent formulators, and multisource generic distributors. Capacity expansion and WHO prequalification pursuit constitute the dominant competitive moves.
Among Indian-origin suppliers, LUPIN Limited and Hetero Group exemplify vertically integrated fermentation-to-formulation positioning. F. Hoffmann-La Roche Ltd. occupies the originator archetype in branded markets. These three anchors illustrate how patent status and manufacturing geography stratify competitive access across regulatory jurisdictions.
| Leading Market Players |
|---|
| LUPIN Limited |
| Zydus Cadila |
| F. Hoffmann-La Roche Ltd. |
| Alembic Pharmaceuticals Limited |
| Sun Pharmaceutical Industries Ltd. |
| NATCO Pharma Limited |
| Amneal Pharmaceuticals LLC |
| Hetero Group |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Network & Pricing Analysis
CDC stockpiling protocols in the United States are compressing commercial spot margins and forcing API manufacturers toward long-term government contracts with fixed-price mechanisms. This procurement preference shift concentrates pricing power with vertically integrated Indian suppliers capable of absorbing fermentation cost volatility.
Pricing Analysis
Warranty and surge-readiness bundling now separates qualified suppliers from commodity API traders in government tender evaluations. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, CDSCO inspection history, and demonstrated pandemic surge capacity. Price differentiation hinges on bioequivalence certification tier and after-sales regulatory support. Cost compression in the standard tier is intensifying because post-pandemic inventory normalization has flooded spot markets with excess API. Hospital procurement offices demonstrate lowest price sensitivity due to formulary consolidation, while independent retail pharmacies face acute margin pressure.
Supply Chain Analysis
Direct-to-government channels handle strategic national reserve replenishment, while prime vendor agreements serve hospital network procurement. Geographic supply concentration centers on India, China, and the United States, with Hyderabad and Ahmedabad fermentation clusters processing Chinese star anise-derived shikimic acid into API intermediates. Raw material dependencies rest on shikimic acid extraction, specialized microbial cultivation media, and sterile fill-finish excipients. Single-source vulnerability in Chinese agricultural feedstock creates structural exposure during harvest disruption. Distribution runs through WHO prequalified supplier networks and EMA-authorized generic pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tamiflu market operates as a cost-of-compliance story where FDA bioequivalence standards and WHO prequalification requirements erect formidable barriers against undercapitalized entrants, entrenching advantages for inspection-ready manufacturers.
For Market Incumbents: Deploy backward integration into shikimic acid supply as the primary defensive lever. Secure captive supply of Chinese star anise extraction capacity or alternative fermentation feedstocks to neutralize agricultural price volatility. Expand CDSCO-inspected fermentation capacity in Telangana to capture Southeast Asian government procurement growth. Neuraminidase resistance mutations threaten protocol confidence and demand sustained R&D investment in combination antiviral development. For New Entrants and Emerging Players: Contract development organizations serving European formulators represent the most accessible channel partner type for technology transfer revenue. Target WHO prequalification pathway facilitation as a service offering rather than finished dosage competition. Vietnam, Indonesia, and Philippines national health systems present underpenetrated procurement channels with limited domestic manufacturing. Pursue modular continuous flow chemistry equipment supply to CDSCO-inspected facilities as a capital-light entry angle. For Investors and Strategic Acquirers: The window for entry favors vertically integrated API-to-formulation suppliers with existing CDSCO inspection records and demonstrated WHO prequalification success. Long-term viability rests on pandemic preparedness institutionalization as permanent government policy rather than cyclical emergency response. Monitor national stockpiling fund allocation announcements as the critical inflection signal for capacity utilization swings.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | UN procurement mechanism access bypasses fragmented national registration requirements for Indian API suppliers. |
| Continuous Flow Chemistry Adoption | Hyderabad and Ahmedabad facilities reduce solvent waste and accelerate EMA technology transfer timelines. |
| Shikimic Acid Supply Securement | Chinese star anise extraction concentration creates vulnerability requiring backward integration or alternative feedstock development. |
| Combination Antiviral Clinical Investment | NIH and EMA innovation frameworks target H275Y resistant strain coverage through fixed-dose pairing with baloxavir marboxil. |
| Prime Vendor Agreement Consolidation | Hospital formulary committees bundle neuraminidase inhibitors with respiratory antiviral portfolios in CDC-funded jurisdictions. |
Research Methodology
FDA filings, EMA centralized marketing authorization submissions, and ClinicalTrials.gov records formed the secondary backbone of this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors supplied forward-looking demand calibration. Bottom-up and top-down triangulation cross-validated API production volumes against government stockpiling contract disclosures and seasonal prescription patterns.
Bottom-up modeling anchored volume projections in fermentation capacity utilization rates and CDSCO-inspected facility expansion announcements across the analysis window. Segmentation dimensions included dosage form, patient population, administration route, and regional regulatory cluster. CAGR derivation synthesized historical procurement cycle patterns with pandemic preparedness fund allocation trajectories. Forecast inputs incorporated influenza surveillance threshold triggers and bioequivalence study pipeline visibility.
Several conditions sit outside the modeled scope, including emergence of neuraminidase inhibitor resistance exceeding current H275Y substitution prevalence and abrupt shifts in CDC strategic national stockpile composition toward alternative antiviral classes. Forecasts reflect base-case assumptions about sustained government pandemic preparedness institutionalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Insulin Secretagogues Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Global Incretin-Based Drugs Market