
 US Generic Injectables Market | 2026-2036
US Generic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
US Generic Injectables Market Intelligence
Hospital group purchasing organization channels is fragmenting as integrated delivery networks build direct sourcing relationships with manufacturers. Hikma Pharmaceuticals leverages its US-based sterile manufacturing footprint to sustain contract wins with major health systems. Fresenius Kabi anchors hospital shelf space through its parenteral nutrition and anesthesia portfolios. Pfizer Inc. competes on volume scale, while Sandoz AG differentiates through biosimilar-to-generic injectable cross-selling.
Generic injectables are sterile, bioequivalent pharmaceutical products administered parenterally, typically formulated as solutions, suspensions, or lyophilized powders requiring reconstitution with specified diluents and manufactured under aseptic processing conditions compliant with current good manufacturing practice. Their primary purpose is to deliver cost-effective therapeutic equivalents of branded parenteral drugs across acute and chronic care settings. Pre-filled syringes command expanding share as safety-engineered devices reduce needlestick exposure and dosing errors in hospital workflows. Oncology therapy area applications lead volume demand, while infectious disease injectables face margin compression from multi-source competition. Intravenous delivery mode dominates value capture due to complex formulation requirements and higher barrier-to-entry manufacturing.
FDA Current Good Manufacturing Practice enforcement, USP Chapter 797 sterile compounding standards, and Drug Supply Chain Security Act traceability mandates collectively elevate compliance costs and consolidate manufacturing among capital-intensive operators. These frameworks restrict market access for smaller compounders while rewarding facilities with validated aseptic fill-finish lines and robust quality management systems. Stakeholders must monitor FDA inspectional observation trends and USP revision cycles to anticipate which product categories will face supply constraints or accelerated generic entry opportunities.
Market Dynamics
Hospital procurement consolidation through integrated delivery networks is compressing supplier margins while elevating quality assurance requirements. Direct sourcing relationships now bypass traditional group purchasing organization intermediaries, reshaping competitive positioning for sterile injectable manufacturers.
Growth Catalysts
- USP Chapter 797 sterile compounding standards:Stringent aseptic processing requirements are consolidating manufacturing among capital-intensive operators with validated fill-finish infrastructure.
- Oncology therapy area expansion:Rising chemotherapy administration volumes in hospital outpatient settings are accelerating demand for cytotoxic generic injectables with complex handling protocols.
- Pre-filled syringe device innovation:Safety-engineered delivery systems are displacing traditional vial-and-syringe workflows in Texas and Florida health systems.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing dependence on Indian and Chinese manufacturers creates vulnerability to geopolitical trade friction.
- FDA inspectional observation escalation:Warning letter issuance to sterile manufacturing facilities is constraining domestic production capacity expansion timelines.
- Lyophilization equipment scarcity:Limited global supply of production-scale freeze-dryers is extending facility commissioning cycles for complex biologic-equivalent injectables.
Strategic Opportunities
- 503B compounding outsourcing:Hospital-adjacent sterile compounding facilities in California and New York are capturing acute shortage-driven demand.
- Biosimilar-to-generic cross-selling:Oncology and immunology portfolios enable bundled contracting with integrated delivery networks seeking formulary simplification.
- Continuous manufacturing adoption:Real-time release testing integration with process analytical technology is compressing batch release timelines for high-volume parenterals.
Industry Challenges
- Aseptic processing technician scarcity:Validated cleanroom operator certification pipelines are failing to match facility expansion rates in high-cost manufacturing regions.
- Legacy enterprise resource planning integration:Drug Supply Chain Security Act serialization mandates are forcing costly system overhauls at mid-scale sterile manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Generic Injectables Market |
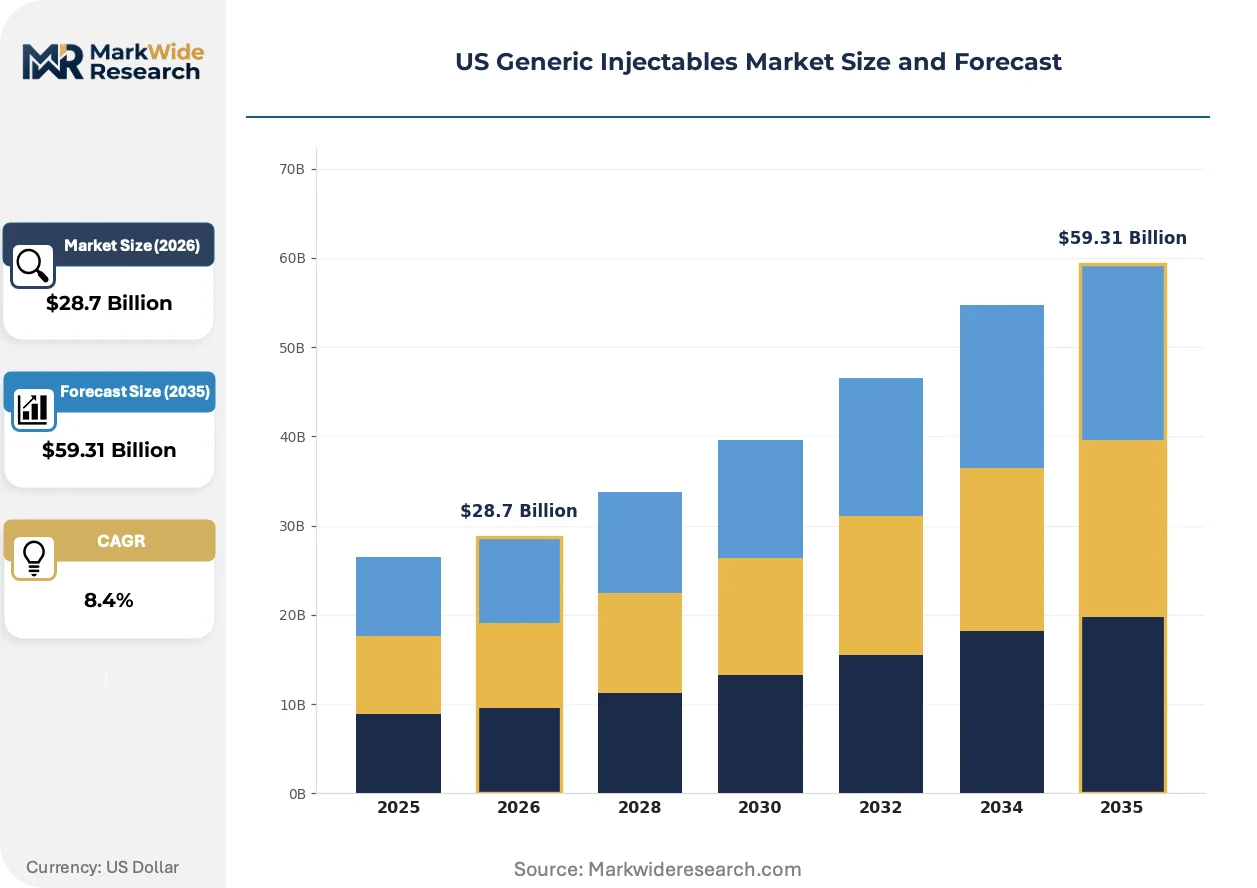
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Pre-filled Syringes, Cartridges Therapy Area: Oncology, Infectious Diseases, Cardiovascular, Pain Management Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intra-articular End User: Hospitals, Clinics, Homecare, Specialty Pharmacies |
| Companies Covered | Sandoz AG, Jubilant Pharma Limited, Hikma Pharmaceuticals, PCI Pharma Services, Dr. Reddy's Laboratories Ltd., Pfizer Inc., Baxter International, Gland Pharma Limited (USA), Fresenius Kabi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Generic Injectables Market Strategic Shifts & Innovations
Digital integration across sterile manufacturing workflows is compressing quality assurance cycles while elevating real-time process control capabilities. Automation investments are reshaping competitive differentiation among parenteral suppliers.
Process analytical technology deployment is digitizing aseptic fill-finish operations through in-line particle monitoring and automated environmental sampling. Major health systems in Texas and California are now requiring suppliers to demonstrate continuous process verification data packages. This capability compression is favoring manufacturers with integrated manufacturing execution systems.
FDA quality metrics reporting requirements under the Pharmaceutical Quality Management System framework are elevating documentation burdens for sterile injectable facilities. The agency's enhanced surveillance inspection program is prioritizing sites with higher complexity parenteral portfolios. Oncology and parenteral nutrition manufacturers are responding by embedding quality by design principles into development protocols.
Integrated delivery network direct sourcing is displacing traditional group purchasing organization channel intermediaries in hospital sterile injectable procurement. Major health systems in Florida and Illinois are negotiating multi-year sole-source agreements with manufacturers holding US-based aseptic capacity. This channel consolidation is most visible in the parenteral nutrition and anesthesia therapeutic categories where supply security outweighs price sensitivity.
US Generic Injectables Market Segmentation
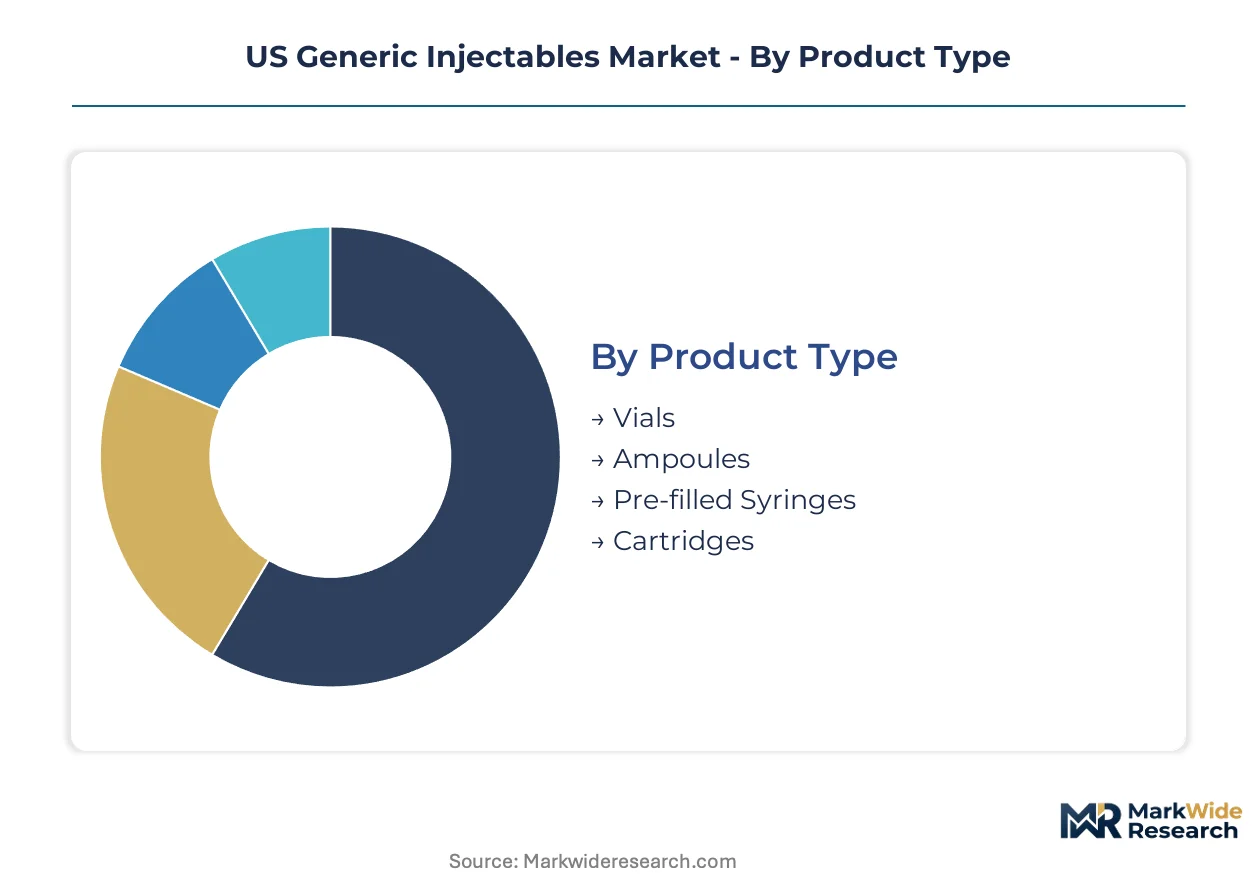
Segmentation in the US generic injectables market reveals how formulation complexity, therapy specificity, and care setting economics create distinct competitive arenas. Each dimension shapes manufacturing investment priorities and contracting strategies differently.
Product Type:
Mature glass primary containers dominate hospital procurement volumes, while emerging polymer and safety-engineered formats are capturing preference shifts in outpatient settings.
- Vials:Borosilicate glass or polymer containers sealed with elastomeric stoppers, requiring aseptic withdrawal via needle and syringe. Demand concentrates in high-volume antibiotic and analgesic administration across Texas and California integrated delivery networks, where unit cost minimization outweighs handling efficiency concerns.
- Pre-filled Syringes:Sterile drug product in ready-to-use glass or plastic syringes with integrated needles or Luer connections, manufactured under ISO 11040 standards. Florida health systems are accelerating adoption for chemotherapy and anticoagulant protocols, driven by Joint Commission medication safety mandates and nursing workflow compression targets.
- Ampoules:Single-dose glass containers with scored necks for snap-open access, prevalent in emergency and anesthetic applications requiring immediate availability.
- Cartridges:Cylindrical containers designed for pen injector and pump systems, gaining traction in diabetes and hormone therapy home administration.
Vials retain volume leadership; pre-filled syringes hold the steepest expansion curve.
Therapy Area:
Margin profiles diverge sharply across therapeutic categories, with cytotoxic portfolios commanding premium positioning and anti-infective segments facing commoditization pressure.
- Oncology:Cytotoxic and supportive care injectables requiring hazardous drug handling infrastructure, including closed-system transfer devices and negative-pressure compounding environments. Hospital outpatient departments in California and New York are expanding infusion center capacity, creating demand concentration for platinum agents, taxanes, and supportive care biosimilars with complex cold-chain requirements.
- Infectious Diseases:Antibiotic, antifungal, and antiviral parenterals spanning narrow-spectrum to broad-coverage spectra. Multi-source generic competition has compressed margins on piperacillin-tazobactam and vancomycin formulations, though carbapenem and liposomal amphotericin portfolios retain pricing power due to manufacturing complexity barriers.
- Cardiovascular:Anticoagulants, antiarrhythmics, and vasoactive agents administered in acute coronary and stroke protocols.
- Pain Management:Opioid and non-opioid analgesics for perioperative and chronic pain, subject to DEA controlled-substance scheduling and diversion control requirements.
Oncology commands the highest value per unit dose; infectious disease represents the most contested volume battleground.
Delivery Mode:
Route selection determines formulation sophistication, with vascular administration requiring the most stringent particulate and endotoxin controls.
- Intravenous:Direct vascular administration via bolus or infusion, demanding isotonicity, particulate-free clarity, and pyrogen compliance per USP <788> and <85> standards. Hospital intensive care and oncology infusion units in Illinois and Florida are standardizing on premixed bag formats for high-alert medications, reducing compounding error exposure while elevating supplier qualification requirements for large-volume parenteral manufacturing.
- Intramuscular:Depot injection into skeletal muscle for sustained absorption, common in vaccine and long-acting antipsychotic delivery.
- Subcutaneous:Administration into adipose tissue for gradual absorption, prevalent in biologic and insulin delivery where patient self-administration training determines adherence outcomes.
- Intra-articular:Direct joint space injection for localized anti-inflammatory effect, requiring particulate control and viscosity modulation for synovial fluid compatibility.
Intravenous routes absorb the majority of sterile manufacturing capacity investment; subcutaneous formats are gaining fastest in homecare migration scenarios.
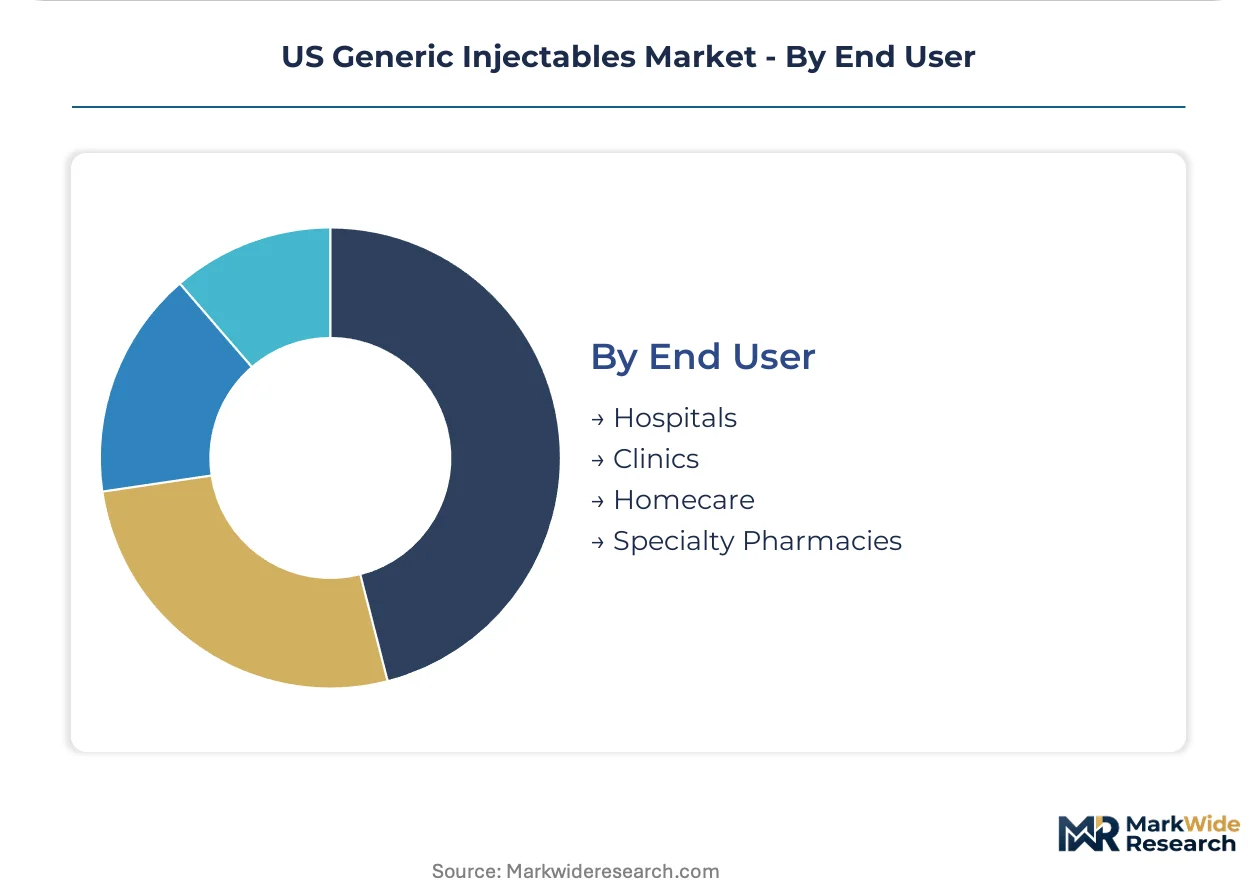
End User:
Procurement authority is consolidating toward entities controlling total cost of care, reshaping channel economics for sterile injectable suppliers.
- Hospitals:Acute care facilities with 340B pricing eligibility and group purchasing organization or direct sourcing contracts. Integrated delivery networks in Texas, California, and Florida are consolidating formulary decisions across 15-50 hospital systems, leveraging volume aggregation to extract price concessions while demanding US-based manufacturing and redundant supply commitments for critical care medications.
- Clinics:Ambulatory surgical and specialty infusion centers with intermediate procurement scale.
- Homecare:Home infusion and skilled nursing services managing chronic parenteral therapy outside institutional settings.
- Specialty Pharmacies:Limited-distribution channels for high-cost biologic and orphan drug injectables with REMS requirements and patient support program integration.
Hospitals anchor procurement volume concentration; homecare channels are expanding most quickly as payors push site-of-care optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors Pacific pharmaceutical distribution corridors serving California's integrated delivery networks. Interstate pharmaceutical logistics corridors connect Texas Gulf Coast manufacturing clusters to Midwest hospital systems. FDA-regulated cold-chain infrastructure concentrates along these coastal and interior distribution axes.
California
Hospital outpatient oncology expansion in Los Angeles and San Francisco Bay Area metro corridors drives cytotoxic injectable demand concentration. USP Chapter 797 sterile compounding enforcement through the California State Board of Pharmacy elevates 503B outsourcing facility qualifications. San Diego's biotech manufacturing corridor hosts contract fill-finish operations serving West Coast IDN networks with validated aseptic capacity.
Texas
Texas Medical Center procurement scale in Houston anchors parenteral nutrition and anesthesia injectable volume concentration. FDA inspectional oversight through the Dallas District Office shapes manufacturing compliance timelines for regional sterile facilities. The Austin-San Antonio corridor attracts continuous manufacturing technology pilots targeting real-time release testing integration.
Florida
Joint Commission medication safety mandates accelerate pre-filled syringe adoption across Miami and Tampa Bay health systems. State-level controlled substance diversion controls through the Florida Department of Health intersect with DEA scheduling requirements for pain management injectables. Orlando's hospital supply chain consolidation hubs coordinate direct sourcing relationships bypassing traditional GPO intermediaries.
Illinois
Chicago-area integrated delivery network formulary consolidation drives multi-year sole-source contracting for critical care injectables. Illinois Environmental Protection Agency hazardous pharmaceutical waste regulations shape cytotoxic drug handling infrastructure investments. The Rockford sterile manufacturing corridor supplies premixed bag formats to Midwest intensive care units standardizing high-alert medication workflows.
New York
New York City metropolitan hospital systems expand 503B compounding outsourcing partnerships for shortage-driven acute demand. USP Chapter 797 revision cycles through the New York State Board of Pharmacy compounding committee reshape sterile processing compliance requirements. Buffalo-Niagara pharmaceutical logistics clusters serve as distribution nodes for Northeast Corridor IDN networks requiring redundant supply commitments.
US Generic Injectables Market Key Industry Players
On the supply side, the industry is consolidating around capital-intensive operators with validated aseptic fill-finish infrastructure and US-based manufacturing footprints. Three archetypes dominate: sterile manufacturing specialists with dedicated parenteral portfolios, diversified pharmaceutical conglomerates leveraging volume scale, and contract development and manufacturing organizations capturing hospital-adjacent outsourcing demand. Competitive positioning depends on backward integration into API sourcing and continuous manufacturing technology licensing.
Among US and European-based operators, Pfizer Inc., Hikma Pharmaceuticals, and Fresenius Kabi exemplify distinct strategic positions within this structure. Pfizer Inc. occupies a scale-driven archetype anchored by volume manufacturing infrastructure. Hikma Pharmaceuticals represents the sterile specialist model with concentrated parenteral expertise. Fresenius Kabi sits within the hospital-system integrated tier, leveraging parenteral nutrition and anesthesia portfolio breadth to sustain formulary positioning.
| Leading Market Players |
|---|
| Sandoz AG |
| Jubilant Pharma Limited |
| Hikma Pharmaceuticals |
| PCI Pharma Services |
| Dr. Reddy's Laboratories Ltd. |
| Pfizer Inc. |
| Baxter International |
| Gland Pharma Limited (USA) |
| Fresenius Kabi |
| Others |
Cost & Logistics Intelligence
Underutilization of US-based aseptic fill-finish capacity in Illinois and Texas is forcing sterile manufacturers to absorb fixed costs across smaller batch runs, compressing margins while elevating price premiums for validated domestic production. This utilization gap simultaneously pressures contract manufacturers to accept longer payment terms from consolidated hospital buyers and rewards operators with backward-integrated API sourcing.
Pricing Analysis
Volume-discount tiering structures separate sole-source critical care contracts from multi-source commodity tenders across integrated delivery network procurement. Three-tier pricing stratifies across FDA-inspected domestic facilities, qualified foreign establishments, and contingent suppliers with warning letter exposure. Cost compression in anti-infective vials is intensifying because carbapenem and liposomal portfolios face Indian and Chinese API import competition. Oncology cytotoxic pre-filled syringes demonstrate the lowest buyer price sensitivity due to hazardous handling infrastructure requirements and Joint Commission safety mandates.
Supply Chain Analysis
Contract manufacturing concentration rests on PCI Pharma Services, Baxter International, and Gland Pharma Limited (USA) for sterile fill-finish capacity serving hospital networks. Active pharmaceutical ingredient sourcing draws from India, China, and domestic fermentation facilities for parenteral nutrition components. Single-source vulnerability concentrates in lyophilization equipment and borosilicate glass primary containers from European suppliers. Distribution runs through cold-chain logistics corridors connecting Texas Gulf Coast manufacturing clusters to California and Florida integrated delivery networks with redundant supply commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation through integrated delivery networks has shifted bargaining power toward buyers controlling 15-50 hospital systems, fragmenting traditional group purchasing organization intermediaries and demanding sole-source security commitments from sterile manufacturers.
For Market Incumbents: Harden quality management systems against FDA enhanced surveillance inspection priorities targeting oncology and parenteral nutrition portfolios. Deepen backward integration into API sourcing for cytotoxic and controlled-substance injectables to mitigate Indian and Chinese supply disruption exposure. Expand validated aseptic capacity in Texas and California corridors where IDN direct sourcing relationships bypass GPO intermediaries.
For New Entrants and Emerging Players: Establish a beachhead in 503B compounding outsourcing for shortage-driven acute demand in California and New York hospital-adjacent facilities. Target premixed bag formats for high-alert intravenous medications in Illinois and Florida intensive care units where standardization mandates create procurement windows. Pursue continuous manufacturing technology licensing to compress batch release timelines and differentiate against legacy batch operators.
For Investors and Strategic Acquirers: Long-term, this sits as a supply-security premium play because hospital formulary consolidation prioritizes redundant US-based manufacturing over unit cost minimization. Acquisition targets should display validated aseptic fill-finish lines with FDA establishment inspection reports free of OAI classifications. Watch FDA warning letter issuance rates to sterile facilities as the inflection signal for supply-constrained therapeutic categories.
| Strategic Initiative | Industry Significance |
|---|---|
| USP Chapter 797 Compliance Investment | California State Board of Pharmacy enforcement elevates 503B facility qualification barriers. |
| Continuous Manufacturing Technology Licensing | Process analytical technology integration compresses batch release timelines for high-volume parenterals. |
| Integrated Delivery Network Direct Sourcing Partnership | Florida and Texas health systems negotiate multi-year sole-source agreements bypassing GPO channels. |
| Pre-filled Syringe Device Portfolio Expansion | Joint Commission medication safety mandates accelerate chemotherapy and anticoagulant adoption. |
| API Backward Integration | Captive supply of cytotoxic and controlled-substance raw materials mitigates geopolitical trade friction exposure. |
Research Approach
A spread of perspectives from hospital procurement directors, sterile manufacturing quality executives, 503B compounding facility operators, and FDA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interview insights were validated against FDA inspectional observation databases, USP revision cycle documentation, integrated delivery network formulary consolidation announcements, and Drug Supply Chain Security Act implementation guidance. Secondary sources included hospital group purchasing organization contract awards, state pharmacy board compounding regulations, and sterile manufacturing facility establishment inspection reports. Bottom-up demand modeling across therapy areas and delivery modes was triangulated with top-down market sizing from capital expenditure disclosures and capacity expansion announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, therapy area, delivery mode, and end-user procurement authority. Compound annual growth rates were derived from elasticity-adjusted volume projections and price trajectory assumptions for commoditized versus complex formulation categories. Forecast inputs incorporated USP Chapter 797 revision implementation timelines, FDA inspectional capacity allocation patterns, and integrated delivery network geographic expansion trajectories.
Stress conditions across API import disruption scenarios, FDA warning letter issuance rates, and lyophilization equipment delivery delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory enforcement continuity and hospital consolidation momentum. Quarterly review of FDA Form 483 observation trends and IDN merger announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Terbinafine Tablet Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Influenza Vaccine Market