
 East Africa Generic Drug Market | 2026-2036
East Africa Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Generic Drug Market Intelligence
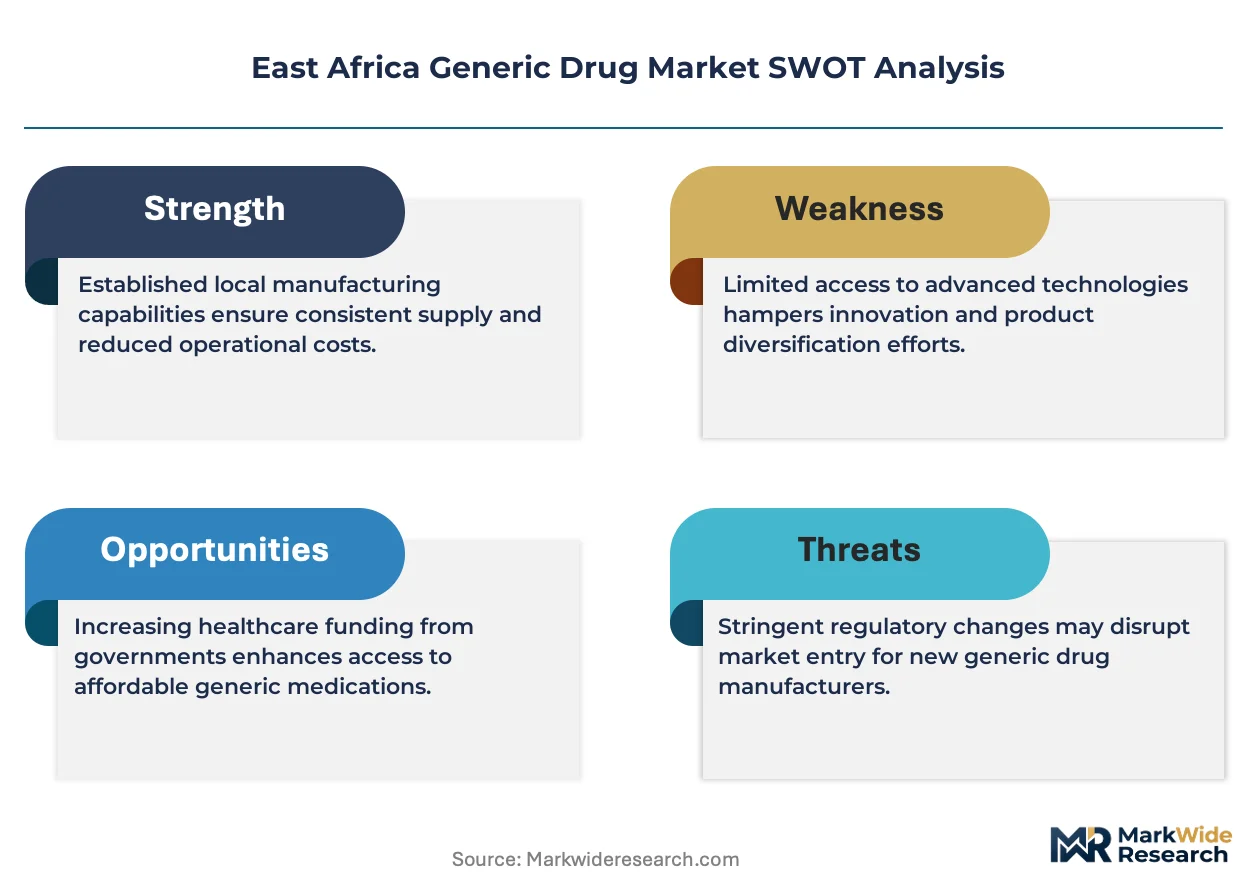
East African Community harmonized medicines regulations is restructuring cost-of-entry calculus for manufacturers seeking multi-country registration. Cipla Limited leverages its long-standing East African manufacturing footprint to sustain volume leadership across antiretroviral and antibiotic portfolios. Sun Pharmaceutical Industries Limited anchors its regional position through specialized injectable production that meets stringent quality benchmarks. Aspen Pharmacare competes aggressively on oral solid dosage forms where price sensitivity shapes tender outcomes.
East Africa generic drugs are chemically equivalent copies of originator pharmaceuticals, manufactured after patent expiry to identical active pharmaceutical ingredient standards, primarily serving cost-constrained public health systems and private pharmacy networks. Tablet formulations dominate volume throughput due to stability advantages in tropical distribution environments, while injectable segments command premium positioning where cold-chain reliability differentiates suppliers. Antiretroviral therapy areas retain structural importance given HIV program scale, though antihypertensive demand is accelerating as non-communicable disease protocols expand across national insurance schemes.
Kenya's Pharmacy and Poisons Board, Tanzania's Medicines and Medical Devices Authority, and Uganda's National Drug Authority collectively enforce bioequivalence standards that determine market access eligibility. These regulators shape competitive dynamics by accelerating approvals for prequalified manufacturers while restricting informal import channels. Stakeholders must monitor regulatory convergence timelines and prequalification status changes to anticipate shifts in tender eligibility and distribution rights.
Market Dynamics
East African Community harmonized medicines regulations are compressing registration timelines and redrawing competitive boundaries for generic manufacturers seeking multi-country market access. This regulatory convergence is the dominant structural force reshaping how suppliers configure their regional portfolios and tender strategies.
Growth Catalysts
- EAC Medicines Registration Harmonization:The East African Community's centralized marketing authorization pathway eliminates redundant national filings, cutting time-to-market for prequalified manufacturers by half.
- Public Hospital Procurement Expansion:Kenya's Managed Equipment Services program and Tanzania's Medical Stores Department are consolidating generic antibiotic and antiretroviral volumes under framework contracts.
- Fixed-Dose Combination Formulation Demand:HIV triple-therapy protocols are pulling specialized manufacturing capacity toward Dar es Salaam and Nairobi pharmaceutical clusters.
Market Restraints
- Active Pharmaceutical Ingredient Import Dependence:Kenya, Tanzania, and Uganda source over ninety percent of APIs from Indian and Chinese suppliers, exposing margins to currency volatility and shipping disruptions.
- Bioequivalence Testing Capacity Bottlenecks:Only three EAC-accredited clinical pharmacology units can execute comparative dissolution studies, creating approval backlogs for new generic entrants.
- Originator Patent Extension Tactics:Secondary patents on crystalline forms and formulation salts delay generic entry for oncology and diabetes therapies beyond primary patent expiry.
Strategic Opportunities
- Rwanda and Burundi Market Development:These smaller EAC members lack domestic manufacturing and rely on Kenyan and Tanzanian distributors, creating first-mover advantages for regional logistics integrators.
- Non-Communicable Disease Protocol Expansion:National health insurance schemes in Uganda and Kenya are adding antihypertensive and statin coverage, opening volume channels previously dominated by communicable disease funding.
- Cold-Chain Injectable Specialization:Vaccine and biologic adjuvant manufacturing requirements are creating premium positioning for suppliers with validated cold-chain infrastructure from port to clinic.
Industry Challenges
- Pharmaceutical Quality Control Talent Scarcity:Kenya's Pharmacy and Poisons Board and Tanzania's Medicines and Medical Devices Authority both report insufficient analytical chemists to staff manufacturing site inspections at required frequency.
- WHO Prequalification Timeline Compression:Manufacturers face eighteen-month backlogs for priority medicine listing, delaying tender eligibility for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Generic Drug Market |
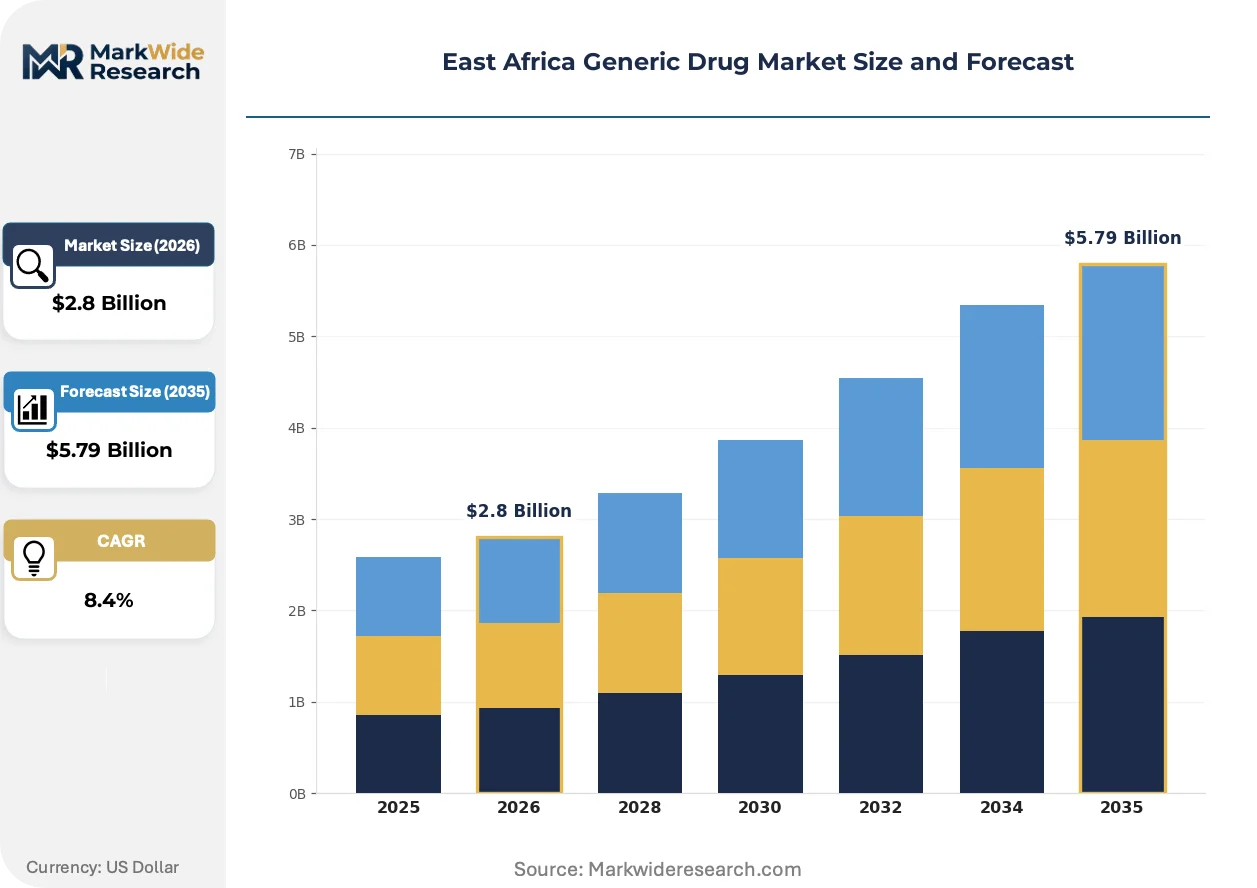
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectables, Suspensions Therapy Area: Antibiotics, Antiretrovirals, Analgesics, Antihypertensives Delivery Mode: Oral, Parenteral, Topical, Transdermal Formulation Type: Solid, Liquid, Semi-Solid, Others |
| Companies Covered | Cipla Limited, Aspen Pharmacare, Sun Pharmaceutical Industries Limited, Shalina Healthcare, Ajanta Pharma Limited, Emzor Pharmaceutical Industries Ltd, Fidson Healthcare Plc, Dawa Life Sciences, Varichem Pharmaceuticals, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing technologies and regulatory data harmonization are converging to reshape how generic drug producers compete across East African markets. These shifts favor capital-intensive manufacturers with integrated quality systems over traditional batch-dependent operations.
Continuous direct compression systems are overtaking conventional wet granulation for high-volume tablet production in Nairobi's pharmaceutical cluster. Cipla's regional manufacturing facility has adopted this technology for antiretroviral lines, cutting batch release times from weeks to days. The shift is compressing working capital requirements and enabling just-in-time tender responses that batch manufacturers cannot match.
Kenya's Pharmacy and Poisons Board has adopted ICH Q12 lifecycle management guidelines, allowing post-approval change management without prior regulatory review for established products. This industrial consequence reduces variation reporting burdens for manufacturers with mature quality systems. Multinational generic suppliers with centralized regulatory affairs functions are responding fastest, while local manufacturers lag in implementation capacity.
National health insurance schemes are consolidating purchasing through centralized electronic procurement platforms that disintermediate traditional distributor networks. Kenya's SHA platform and Tanzania's MSD e-procurement system now handle majority generic volumes, compressing margins for wholesalers while rewarding manufacturers with direct tender relationships. This behavior shift is most visible in Nairobi and Dar es Salaam, where former distribution intermediaries are pivoting to last-mile logistics services.
East Africa Generic Drug Market Segmentation
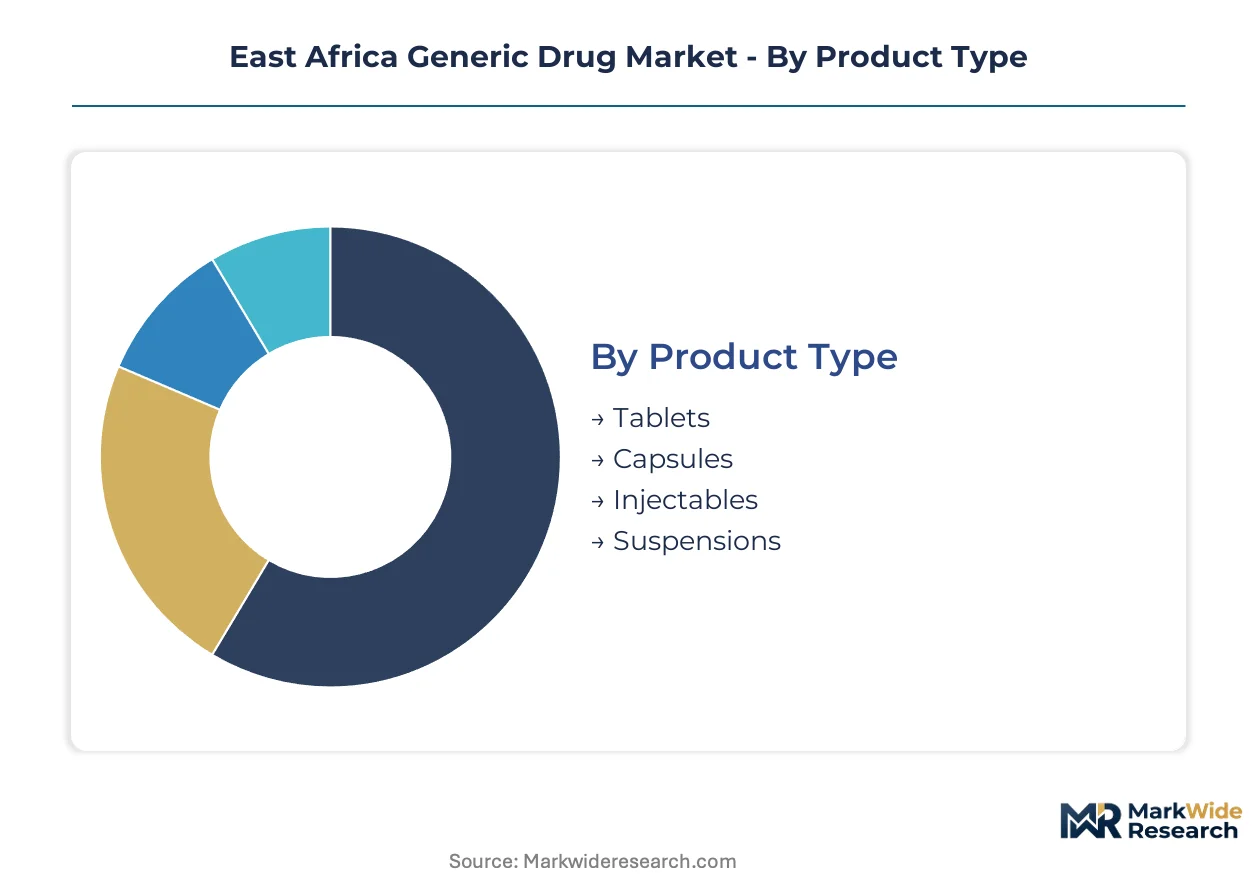
East Africa's generic drug market fragments across formulation technologies, therapeutic applications, and delivery modalities that determine manufacturing investment priorities and distribution infrastructure requirements. Understanding these segment boundaries reveals where procurement volumes concentrate and where regulatory complexity creates competitive moats.
Product Type:
Tablet compression technology and sterile fill-finish capabilities define the manufacturing capability axis across Nairobi and Dar es Salaam production facilities.
- Tablets:Direct compression and wet granulation formulations dominate antiretroviral and antibiotic procurement volumes. Kenya's Pharmacy and Poisons Board prioritizes bioequivalence data for immediate-release solid orals, accelerating approvals for manufacturers with continuous manufacturing lines.
- Injectables:Sterile vials and prefilled syringes require validated aseptic processing and cold-chain integrity from port to clinic. Tanzania's Medical Stores Department tenders favor suppliers with WHO-prequalified sterile manufacturing, creating qualification barriers that filter out smaller regional players.
- Capsules:Hard gelatin shells accommodate hygroscopic APIs unsuited to tablet compression, serving specialized antibiotic and antifungal portfolios.
- Suspensions:Pediatric and geriatric liquid formulations address swallowing difficulties, with stability testing under tropical humidity conditions determining shelf-life claims.
Tablets lead on scale; injectables lead on momentum.
Therapy Area:
Procurement concentration patterns across national health insurance schemes and vertical disease programs shape demand allocation.
- Antiretrovirals:Triple-therapy fixed-dose combinations anchor Kenya's SHA procurement platform and Tanzania's MSD framework contracts. PEPFAR and Global Fund financing channels concentrate volumes through prequalified manufacturer lists.
- Antibiotics:Amoxicillin and azithromycin generics face tender price compression where Indian imports undercut regional manufacturing on cost.
- Analgesics:Paracetamol and ibuprofen over-the-counter volumes flow through private pharmacy networks in Nairobi and Kampala.
- Antihypertensives:Amlodipine and losartan demand climbs as Uganda's national health insurance expands non-communicable disease coverage.
Antiretrovirals capture procurement volume concentration; antihypertensives capture the steepest expansion trajectory.
Delivery Mode:
Patient compliance requirements and healthcare worker training levels determine route selection across public hospital and primary care settings.
- Oral:Self-administered solid and liquid formulations minimize clinic visit burdens for chronic disease management in rural Tanzania and Uganda.
- Parenteral:Intravenous and intramuscular routes dominate inpatient antibiotic therapy and vaccine adjuvant delivery where bioavailability requirements exclude enteral options.
- Topical:Creams and ointments serve dermatology and localized infection protocols with minimal systemic absorption concerns.
- Transdermal:Patch formulations remain limited by import costs and storage requirements, with niche application in pain management protocols.
Oral administration dominates prescription volumes; parenteral routes command premium positioning.
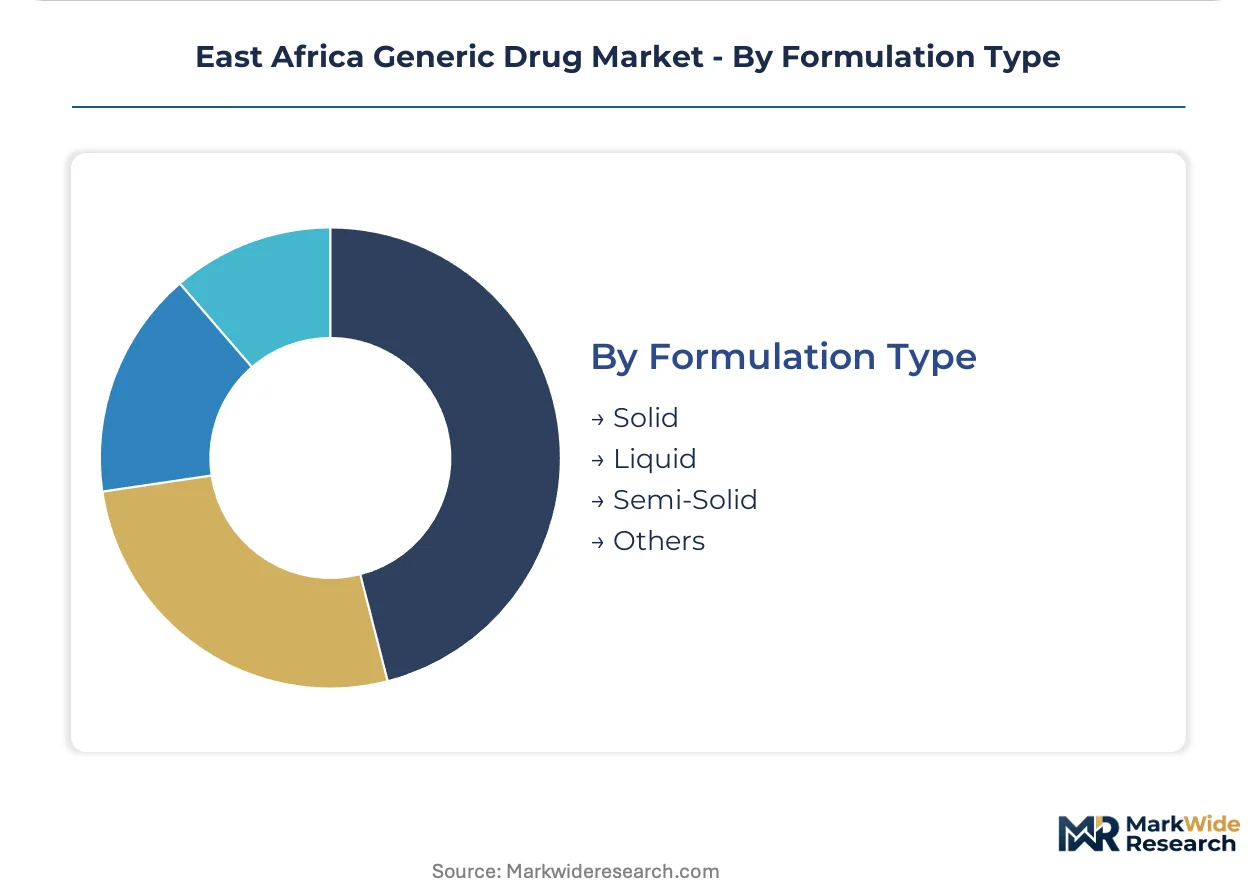
Formulation Type:
Physical state classification aligns with manufacturing equipment specialization and stability testing protocols enforced by EAC national regulators.
- Solid:Tablets, capsules, and powders leverage Nairobi's concentration of compression and encapsulation capacity, with humidity-controlled packaging essential for tropical distribution.
- Liquid:Solutions and suspensions require preservative validation and container-closure integrity testing that extends registration timelines.
- Semi-Solid:Ointments and gels demand specialized mixing equipment and rheological testing less common in regional manufacturing facilities.
- Others:Inhalers, suppositories, and novel drug delivery systems occupy minimal procurement share given complexity and import dependence.
Solid formulations anchor manufacturing investment; liquid formulations are gaining share fastest in pediatric segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Africa's pharmaceutical workforce concentrates in Nairobi and Dar es Salaam, where analytical chemists and regulatory affairs specialists anchor manufacturing and distribution operations across the region's generic drug supply chain.
Kenya
Kenya's Social Health Authority platform and expanding national health insurance coverage drive procurement volumes for antiretroviral and antibiotic generics. The Pharmacy and Poisons Board enforces bioequivalence standards that determine tender eligibility for domestic and imported products. Nairobi's pharmaceutical cluster hosts continuous manufacturing lines for fixed-dose combination tablets serving regional export markets.
Tanzania
Tanzania's Medical Stores Department consolidates public sector generic purchasing through framework contracts that favor WHO-prequalified suppliers. The Medicines and Medical Devices Authority coordinates with EAC harmonization protocols to streamline cross-border registration. Dar es Salaam's distribution hub manages cold-chain logistics for injectable antibiotics and vaccine adjuvants destined for domestic and neighboring markets.
Uganda
Uganda's National Drug Authority regulates import and local production of generics through prequalification requirements aligned with EAC standards. The national health insurance scheme's expansion into non-communicable disease coverage accelerates demand for antihypertensive and statin formulations. Kampala's private pharmacy networks distribute over-the-counter analgesics and prescription chronic disease medications.
Rwanda
Rwanda lacks domestic pharmaceutical manufacturing and depends on Kenyan and Tanzanian distributors for generic drug supply. The country's national health insurance program achieves near-universal coverage, creating predictable procurement volumes for essential medicines. Kigali's centralized procurement system negotiates regional framework agreements that leverage EAC harmonized regulations.
Burundi
Burundi's pharmaceutical market remains underdeveloped with minimal local manufacturing capacity and reliance on informal import channels. The country's national medicines regulatory authority participates in EAC harmonization processes to strengthen quality control at ports of entry. Bujumbura's distribution infrastructure serves as a transit point for generics entering eastern Democratic Republic of Congo.
East Africa Generic Drug Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across East Africa's generic drug procurement channels. Indian multinational manufacturers anchor volume leadership through regional manufacturing footprints and WHO prequalification status. The market structure fragments across three strategic archetypes: integrated multinational manufacturers with EAC production facilities, regional distributors with tender relationships, and emerging local formulators serving domestic markets. Competitive moves concentrate on securing direct procurement platform access and expanding sterile manufacturing capacity for injectable portfolios.
Among Indian-based pharmaceutical manufacturers, Cipla Limited and Sun Pharmaceutical Industries Limited exemplify the multinational archetype with established East African operations. Aspen Pharmacare represents the Africa-anchored diversified player competing across oral solid dosage forms. These three companies occupy positions that reflect divergent strategic bets: Cipla on antiretroviral manufacturing scale, Sun on specialized injectable quality benchmarks, and Aspen on price-competitive tender participation.
| Leading Market Players |
|---|
| Cipla Limited |
| Aspen Pharmacare |
| Sun Pharmaceutical Industries Limited |
| Shalina Healthcare |
| Ajanta Pharma Limited |
| Emzor Pharmaceutical Industries Ltd |
| Fidson Healthcare Plc |
| Dawa Life Sciences |
| Varichem Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Active pharmaceutical ingredient import costs from Indian and Chinese suppliers cascade through three distinct pricing tiers across East African procurement channels. Kenya's Social Health Authority platform and Tanzania's Medical Stores Department framework contracts compress margins for manufacturers lacking backward integration into API production.
Pricing Analysis
Bundled tender pricing for WHO-prequalified products separates from unbundled spot purchasing for non-prequalified generics across Nairobi and Dar es Salaam distribution channels. Price differentiation hinges on bioequivalence certification status and cold-chain validation documentation, with originator patent extension tactics on crystalline forms squeezing margins for oncology entrants. Cost compression in the antibiotics segment intensifies as Indian imports undercut regional manufacturing on amoxicillin and azithromycin tenders. Public hospital procurement managers exhibit acute price sensitivity on oral solid dosages, while private pharmacy networks absorb modest premiums for cold-chain injectables.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese API suppliers, where over ninety percent of active pharmaceutical ingredients for Kenya, Tanzania, and Uganda originate. Raw material dependencies span amoxicillin trihydrate, tenofovir disoproxil fumarate, and lamivudine intermediates that feed Nairobi's continuous manufacturing lines. Tariff exposure on imported excipients and packaging materials compounds working capital pressure for regional formulators lacking captive supply. Distribution runs through Dar es Salaam's port-to-clinic cold-chain infrastructure and Nairobi's pharmaceutical cluster for last-mile delivery to Kampala and Kigali.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's generic drug market functions as a regulatory compounder, where EAC harmonized medicines registration accelerates multi-country market access and concentrates procurement volumes through prequalified manufacturer lists.
For Market Incumbents: Extend sterile manufacturing capacity in Dar es Salaam to capture vaccine adjuvant and injectable antibiotic tenders requiring validated cold-chain integrity. Deepen backward integration into API sourcing through long-term supply agreements with Indian suppliers, insulating margins from currency volatility that threatens price-competitive positioning against Sun Pharmaceutical's specialized injectable lines.
For New Entrants and Emerging Players: The price-point gap between WHO-prequalified premium tiers and informal import economy channels creates white-space opportunity in Rwanda and Burundi, where domestic manufacturing absence forces reliance on Kenyan and Tanzanian distributors. Target antihypertensive and statin segments as Uganda's national health insurance expands non-communicable disease coverage. Secure EAC centralized marketing authorization pathway access ahead of national regulator filings to compress time-to-market against established players.
For Investors and Strategic Acquirers: Consolidation pressure builds where bioequivalence testing capacity bottlenecks restrict new generic entrants to three EAC-accredited clinical pharmacology units in Nairobi and Dar es Salaam. Long-term viability favors manufacturers with continuous direct compression technology and established tender relationships on Kenya's SHA platform. Monitor WHO prequalification timeline compression as the inflection signal determining tender eligibility windows for portfolio expansion candidates.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Unlocks tender eligibility on Kenya's SHA platform and Tanzania's MSD framework contracts. |
| Continuous Manufacturing Adoption | Cipla's Nairobi facility demonstrates batch release compression from weeks to days for antiretroviral lines. |
| Cold-Chain Infrastructure Expansion | Dar es Salaam's port-to-clinic validation enables premium positioning for sterile fill-finish portfolios. |
| EAC Harmonized Registration Filing | Eliminates redundant national filings and halves time-to-market across Kenya, Tanzania, and Uganda. |
| Non-Communicable Disease Portfolio Shift | Aligns with Uganda's national health insurance expansion into antihypertensive and statin coverage. |
Research Approach
Bottom-up therapy area modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors at Kenya's Pharmacy and Poisons Board, procurement managers at Tanzania's Medical Stores Department, formulary specialists at Uganda's National Drug Authority, and distribution executives at Nairobi pharmaceutical clusters informed demand segmentation. Secondary validation drew from EAC medicines registration harmonization protocols, WHO prequalification listings, national health insurance scheme expansion documents, and pharmaceutical import customs records across the five member states.
Historical tender volume analysis across the projection horizon established baseline growth trajectories for antiretroviral, antibiotic, and antihypertensive segments. The forecast framework disaggregates by formulation type, therapy area, delivery mode, and regulatory cluster to capture procurement concentration patterns. CAGRs derive from regression against public health expenditure trends, EAC regulatory convergence timelines, and PEPFAR financing channel allocations. Modeled inputs include bioequivalence approval backlogs, continuous manufacturing adoption rates, and cold-chain infrastructure expansion milestones.
The model assumes a particular technology adoption path; alternative pathways for continuous direct compression versus conventional wet granulation would alter the outlook for Nairobi manufacturing competitiveness. Forecasts reflect assumptions regarding EAC regulatory harmonization implementation pace, WHO prequalification timeline evolution, and national health insurance coverage expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
North America Vaccines Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market