
 Major Home Appliances Market | 2026-2036
Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Major Home Appliances Market Foresight
The Major Home Appliances market is pivoting on a widening split between premium connected suites and commodity replacement units. Midea leverages its integrated compressor and motor manufacturing to dominate cost-efficient refrigeration for emerging markets. Electrolux sustains its European brand equity through specialized built-in kitchen portfolios that command higher margins in Western European renovation cycles.
Major home appliances encompass electrically powered durable goods designed for residential food preservation, fabric care, and meal preparation, typically operating on 110-240V alternating current with rated lifespans of 10-15 years and energy consumption profiles measured under standardized test protocols. Refrigerators and washing machines anchor volume demand across replacement cycles, while smart appliances and energy-efficient variants capture expanding margin pools as utility rebate programs and building codes tighten operational cost thresholds. Conventional technology segments still occupy the majority of installed base value but face displacement where grid-connected diagnostics and variable-speed compressors reshape consumer expectations.
The US Department of Energy and the European Commission's Ecodesign framework jointly constrain minimum efficiency standards for refrigeration and laundry equipment, forcing manufacturers to redesign insulation systems and motor architectures to maintain market access. China's GB standards and India's Bureau of Energy Efficiency labeling program add parallel compliance layers that shape export sourcing decisions and local production investments. Stakeholders must monitor how fragmented national efficiency timelines and divergent smart-grid interoperability requirements reshape product platform economics and regional manufacturing allocation.
Market Dynamics
The Major Home Appliances market is bifurcating between connected premium ecosystems and cost-optimized replacement units, with EU Ecodesign Directive mandates and US DOE efficiency standards compressing legacy platform economics while variable-speed compressor adoption accelerates across refrigeration portfolios.
Growth Catalysts
- EU Ecodesign Directive:Tightening minimum efficiency thresholds for refrigeration and laundry equipment force technology upgrades that expand addressable market for inverter-driven systems.
- Urban household formation:Accelerating electrification programs in India and Brazil extend appliance access to first-time buyers entering formal housing markets.
- Variable-speed compressors:These motor architectures reduce energy consumption profiles enough to qualify for utility rebate programs in Japan and the United States.
Market Restraints
- Copper and steel input volatility:Raw material price swings compress margin buffers for manufacturers dependent on commodity-intensive insulation and motor housing production.
- Compressor supply concentration:Integrated motor-compressor manufacturing clusters in China create sourcing vulnerability for brands without captive production.
- Refrigerant transition friction:F-Gas Regulation phase-down timelines in Europe force costly retooling of sealed system architectures before alternative chemistries achieve scale.
Strategic Opportunities
- India Bureau of Energy Efficiency labeling expansion:Star-rating program extensions create tiered demand pull for higher-efficiency variants in urban replacement cycles.
- Grid-connected diagnostics convergence:Smart-meter interoperability standards in Germany and Japan enable predictive maintenance revenue streams beyond hardware sales.
- Direct-to-installer channels:Bypassing traditional retail through contractor-integrated platforms captures renovation-cycle demand in US and Australian housing markets.
Industry Challenges
- Sealed system technician scarcity:Refrigerant handling certification requirements outpace vocational training pipeline expansion in North American service networks.
- Multi-standard compliance timelines:Divergent national efficiency test protocols force parallel product platform development for GB standards, BEE labeling, and DOE certification.
- Legacy smart-home protocol fragmentation:Integration complexity with existing home automation ecosystems delays connected appliance adoption among renovation buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Major Home Appliances Market |
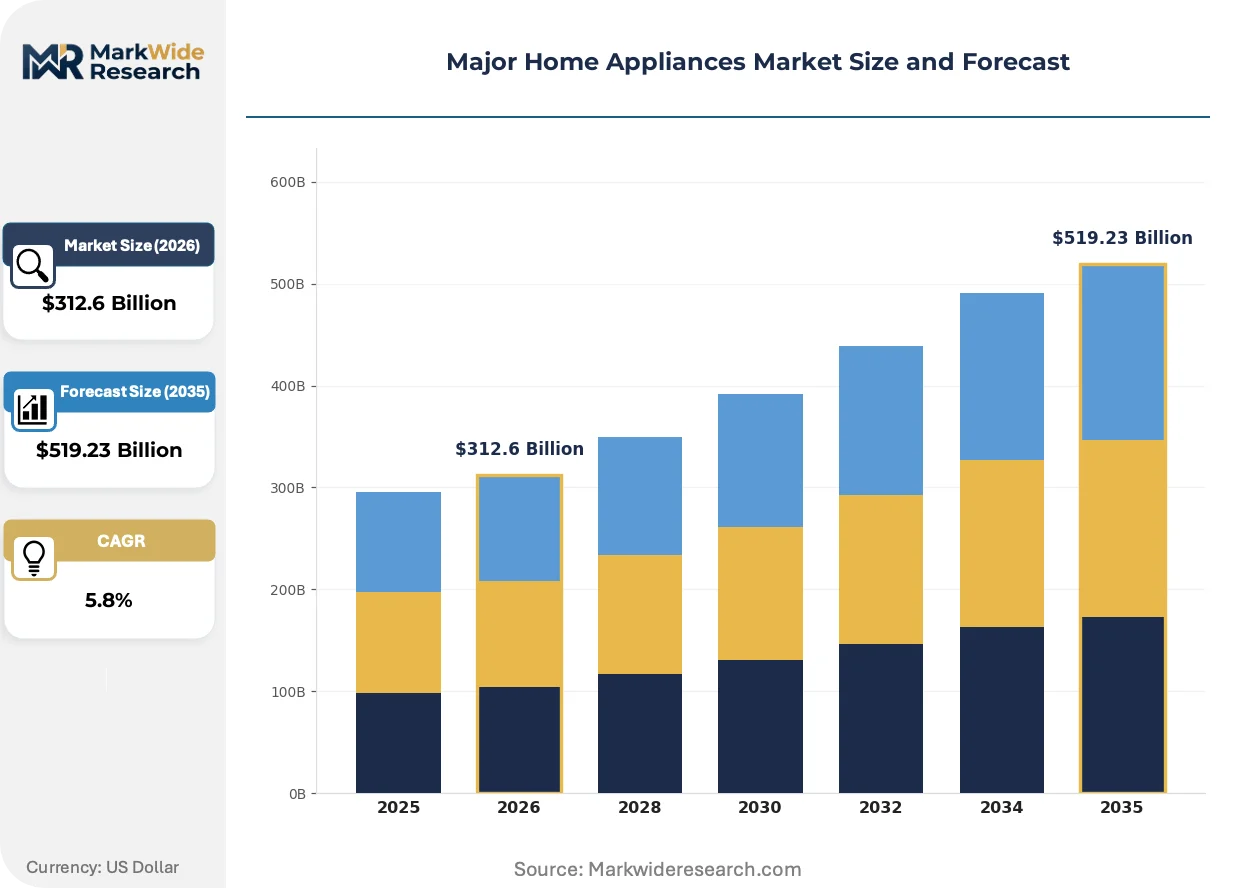
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Dishwashers, Ovens Technology: Smart Appliances, Energy-Efficient, Conventional, Eco-Friendly End User: Households, Rental Properties, Hospitality, Commercial Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Midea, Electrolux, Haier Smart Home, GE Appliances, Samsung Electronics, LG Electronics, BSH Home Appliances, Bosch, Whirlpool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Major Home Appliances Market Shifts & Advancements
Three forces are restructuring appliance value creation: AI-driven predictive maintenance compressing service cost structures, refrigerant chemistry transitions mandated by environmental frameworks, and procurement model shifts among institutional buyers favoring lifecycle contracts over capital expenditure.
Machine vision quality control is automating defect detection in compressor winding and insulation foam injection processes. Tier-one manufacturers in South Korea and Germany deploy these systems at line speeds exceeding manual inspection capacity. This technology is automating workforce reduction in final assembly while raising first-pass yield rates for inverter motor production.
The F-Gas Regulation mandates stepped reductions in hydrofluorocarbon refrigerant volumes through 2030, forcing redesign of heat exchanger architectures and expansion valve calibrations. European manufacturers face compressed R&D timelines to qualify hydrocarbon and hydrofluoroolefin alternatives under CE marking pressure. Sealed system suppliers in Italy and Poland are consolidating testing capacity to spread certification costs across brand portfolios.
Institutional buyers in US multifamily housing and European hospitality are unbundling after-sales service from equipment procurement, signing separate multi-year maintenance contracts with regional service aggregators. This purchasing behavior shift displaces traditional dealer-integrated warranty models. The pattern concentrates in California and Florida rental markets where operator consolidation creates sufficient scale for direct vendor negotiation.
Major Home Appliances Market Segmentation
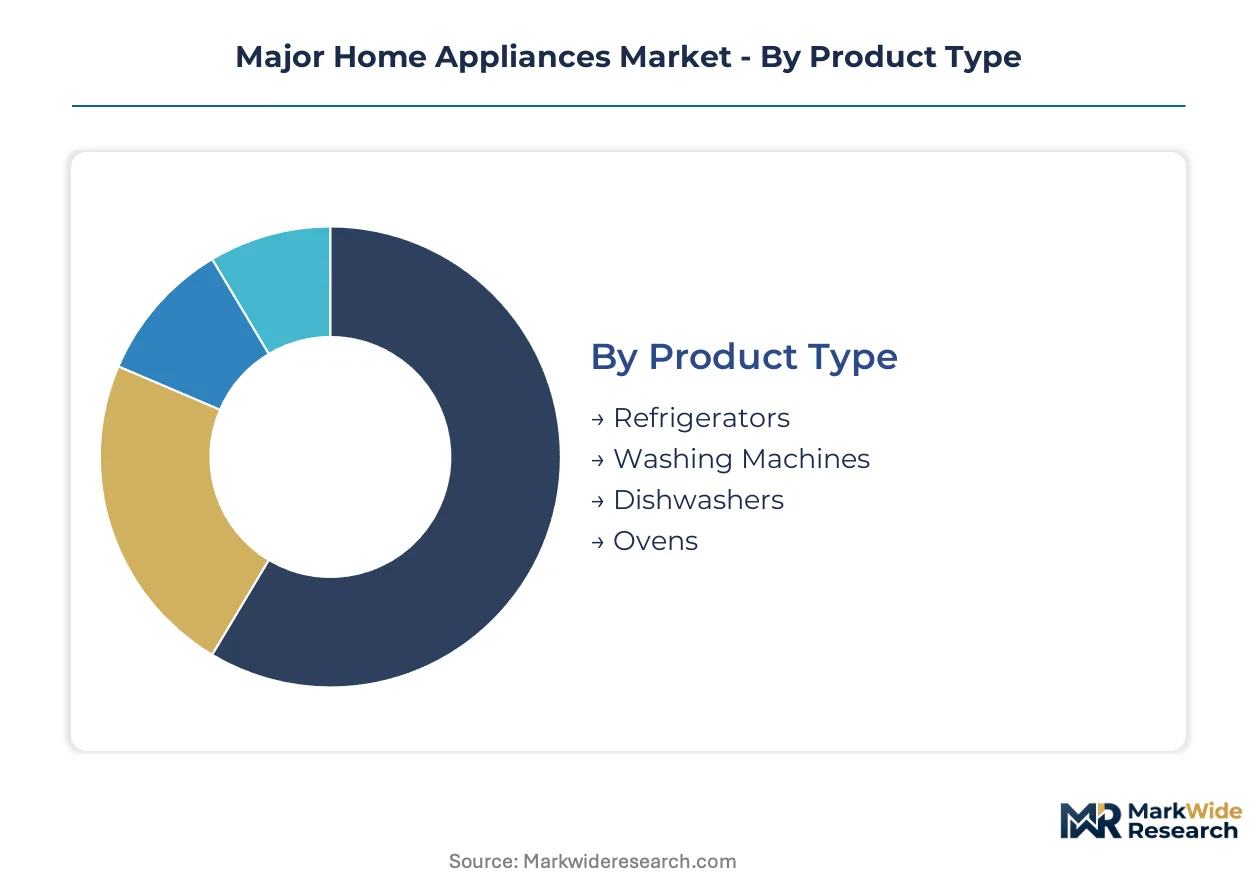
Major home appliances segment along four intersecting axes that determine pricing power, channel strategy, and compliance burden. Product type dictates sealed system complexity and technician certification requirements. Technology tier separates rebate-eligible platforms from legacy replacement stock.
Product Type:
Refrigeration and fabric care equipment anchor volume procurement, with thermal engineering specifications driving regional manufacturing allocation.
- Refrigerators:Sealed system architectures with variable-speed compressor integration dominate efficiency tiering. Urban household formation in India and Brazil pulls first-time buyer demand for frost-free units.
- Washing Machines:Motor architecture differentiates front-load inverter drives from conventional top-load agitators. EU Ecodesign Directive thresholds force platform redesigns for drum insulation and water heating elements.
- Dishwashers:Built-in configurations command renovation-cycle premiums in Western European markets. Water consumption metrics determine eligibility for utility rebate programs in Germany and Japan.
- Ovens:Convection and pyrolytic cleaning features segment price tiers. Multifamily housing operators in US coastal markets favor standard electric ranges for replacement cycles.
Refrigerators lead on scale; washing machines lead on momentum.
Technology:
Connectivity and efficiency certification stratify margin pools, with inverter motor platforms capturing utility incentive flows.
- Smart Appliances:Grid-connected diagnostics enable predictive maintenance revenue streams. German smart-meter interoperability standards and Japan's METI efficiency labeling create dual certification pathways.
- Energy-Efficient:Inverter-driven compressors and heat pump dryers qualify for BEE star ratings in India and DOE rebate programs in the United States. Variable-speed motor adoption accelerates across refrigeration portfolios.
- Conventional:Fixed-speed compressor platforms serve price-sensitive replacement demand. Commodity input volatility compresses margin buffers for manufacturers without captive motor production.
- Eco-Friendly:Hydrocarbon refrigerant architectures address F-Gas Regulation phase-down timelines. European sealed system suppliers consolidate testing capacity to spread certification costs.
Energy-Efficient variants lead on scale; Smart Appliances lead on momentum.
End User:
Procurement authority and lifecycle cost horizons separate institutional buyers from residential purchasers.
- Households:Individual replacement cycles dominate volume, with renovation timing driving premium suite adoption. Extended warranty preferences vary by housing tenure patterns.
- Rental Properties:US multifamily operators consolidate purchasing scale for direct vendor negotiation. California and Florida markets unbundle equipment procurement from maintenance contracts.
- Hospitality:European hotel chains accelerate refresh cycles to meet sustainability reporting requirements under CSRD. Lifecycle cost modeling favors higher-efficiency platforms despite capital cost premiums.
- Commercial:Food service and institutional laundry operations demand industrial-grade durability ratings. Technician certification requirements constrain service network expansion.
Households lead on scale; Rental Properties lead on momentum.
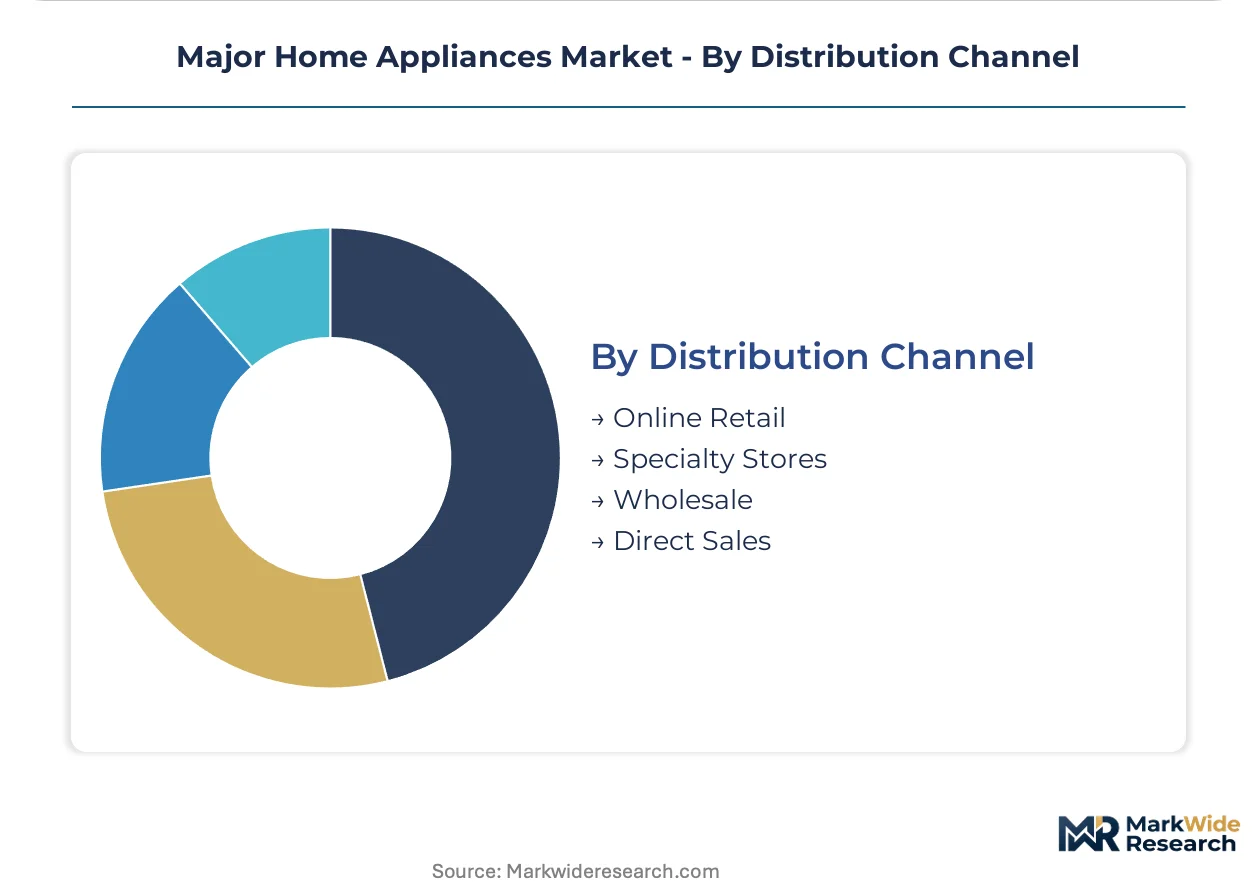
Distribution Channel:
Channel configuration determines margin capture and installation service integration.
- Online Retail:Platform logistics networks enable next-day delivery for standard-size refrigeration. Return handling complexity limits category penetration for built-in kitchen portfolios.
- Specialty Stores:In-store consultation drives premium suite attachment rates. Kitchen renovation project coordination requires designer-certified sales staff.
- Wholesale:Contractor-integrated procurement captures new construction and multifamily replacement demand. Inventory financing terms determine competitive positioning among regional distributors.
- Direct Sales:Manufacturer-owned channels bypass retail margin extraction in concentrated urban markets. Installation service bundling addresses technician scarcity constraints.
Specialty Stores lead on scale; Direct Sales lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed base of refrigeration equipment while India generates faster household formation velocity; both markets contrast with mature replacement cycles dominating the United States and Germany.
United States
Multifamily housing operators in California and Florida consolidate purchasing scale for direct vendor negotiation. The Department of Energy tightens minimum efficiency standards for refrigeration and laundry equipment, forcing motor architecture redesigns. Appliance manufacturing clusters in the Midwest and Southeast maintain captive compressor production for domestic supply security.
Germany
Renovation-cycle demand for built-in kitchen portfolios sustains premium pricing in Western European markets. The F-Gas Regulation mandates stepped hydrofluorocarbon phase-downs through 2030, compressing sealed system R&D timelines. Industrial concentrations in North Rhine-Westphalia and Bavaria host consolidated testing capacity for hydrocarbon refrigerant certification.
China
Urban household electrification programs extend appliance access to first-time buyers in tier-two and tier-three cities. GB standards impose parallel compliance layers that shape export sourcing decisions and local production investments. Manufacturing gravity concentrates in the Yangtze River Delta and Pearl River Delta, where integrated motor-compressor clusters serve emerging market demand.
India
Accelerating urban household formation pulls frost-free refrigeration demand from buyers entering formal housing markets. The Bureau of Energy Efficiency star-rating program extensions create tiered demand pull for higher-efficiency variants. Production investments concentrate in Maharashtra and Gujarat, where domestic assembly scales to meet replacement-cycle growth.
Brazil
Electrification program extensions broaden appliance access across urban peripheries and secondary cities. National energy efficiency labeling requirements align with regional Mercosur standards, shaping import sourcing patterns. Manufacturing clusters in São Paulo and Minas Gerais anchor Latin American supply for cost-optimized refrigeration platforms.
Major Home Appliances Market Competitive Landscape
Top-tier vendors anchor premium connected ecosystems, while mid-tier fabricators compete on cost-optimized replacement platforms and regional brand equity. The vendor base stratifies across three archetypes: integrated compressor manufacturers with captive motor production, European heritage brands with built-in kitchen specialization, and diversified electronics conglomerates with smart-home ecosystem leverage. Consolidation pressure concentrates in sealed system supply, where backward integration into compressor manufacturing determines margin sustainability. Technology licensing and regional distribution partnerships represent the dominant competitive moves for market access expansion.
Within the integrated manufacturing tier, Midea and Haier Smart Home exemplify scale-driven positioning through captive compressor and motor production. Electrolux occupies a position representing European heritage brand equity and built-in kitchen portfolio specialization. Among diversified electronics conglomerates, Samsung Electronics and LG Electronics sit within the smart-home ecosystem leverage archetype, with connectivity integration shaping competitive differentiation.
| Leading Market Players |
|---|
| Midea |
| Electrolux |
| Haier Smart Home |
| GE Appliances |
| Samsung Electronics |
| LG Electronics |
| BSH Home Appliances |
| Bosch |
| Whirlpool |
| Others |
Supply & Pricing Matrix
A widening performance gap between inverter-driven efficiency tiers and fixed-speed commodity platforms splits both pricing power and sourcing architectures across the Major Home Appliances market. EU Ecodesign Directive compliance costs and utility rebate eligibility in Japan and the United States concentrate margin capture among manufacturers with captive compressor production, while commodity replacement demand in emerging markets feeds cost-optimized platforms from integrated motor clusters in China.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for conventional refrigeration platforms through integrated motor-compressor manufacturing scale. Three-tier pricing structure across premium connected suites, efficiency-certified mid-tier, and economy replacement units differentiates on BEE star ratings and smart-grid interoperability. Price compression runs through fixed-speed commodity tiers as steel and copper input volatility erodes margin buffers. Rental property operators in California and Florida exhibit lowest price sensitivity due to lifecycle cost modeling, while first-time buyers in India and Brazil drive volume at economy price points.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Brazil anchor hub-and-spoke patterns for finished appliance logistics, with inventory positioning tied to renovation cycle seasonality. Manufacturing gravity concentrates in China, South Korea, and Poland, where sealed system assembly draws from copper winding, steel housing, and refrigerant chemistry inputs. Single-source vulnerability persists in variable-speed compressor motors sourced from integrated clusters in China's Pearl River Delta. Distribution runs through contractor-integrated wholesale channels for multifamily replacement demand and specialty retail for built-in kitchen portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Major Home Appliances market rests on two structural levers: captive compressor production absorbing commodity volatility, and premium connected suites capturing utility incentive flows through smart-meter interoperability.
For Market Incumbents: To counter sealed system technician scarcity constraining service network expansion in North America, incumbents should deepen backward integration into compressor manufacturing to secure margin buffers against steel and copper volatility, while accelerating predictive maintenance platform development to capture recurring revenue beyond hardware sales through grid-connected diagnostics convergence in Germany and Japan. For New Entrants and Emerging Players: The price-point gap between premium built-in kitchen portfolios and cost-optimized replacement units creates white-space opportunity in India's Bureau of Energy Efficiency star-rating tier expansion and Brazil's electrification program extensions. Direct-to-installer channel development bypasses retail margin extraction and captures renovation-cycle demand in US and Australian housing markets without legacy dealer network obligations. For Investors and Strategic Acquirers: Consolidation pressure builds where refrigerant transition timelines under Europe's F-Gas Regulation compress R&D capacity for smaller sealed system suppliers. Long-term viability favors integrated manufacturers with captive motor production and multi-standard compliance capabilities. The signal to monitor is hydrocarbon refrigerant certification throughput at Italian and Polish testing facilities as alternative chemistry scale indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Captive motor production insulates margin buffers against commodity volatility and supply concentration risk. |
| Smart-Grid Interoperability Certification | METI labeling in Japan and German smart-meter standards unlock utility rebate revenue streams. |
| Hydrocarbon Refrigerant Platform Transition | F-Gas Regulation compliance secures European market access through 2030 phase-down timelines. |
| Direct-to-Installer Channel Development | Contractor-integrated procurement captures US multifamily and Australian renovation-cycle demand. |
| Predictive Maintenance Service Bundling | Grid-connected diagnostics enable recurring revenue beyond hardware in institutional buyer segments. |
Research Methodology
Direct dialogue with appliance manufacturing executives, sealed system R&D directors, multifamily housing procurement managers, and regional distribution channel heads grounded qualitative assessment in operational realities. Secondary validation drew from US Department of Energy certification databases, European Commission Ecodesign implementing measures, India's Bureau of Energy Efficiency labeling records, and customs trade data for compressor motor imports. Bottom-up demand modeling across replacement cycles and first-time buyer formation triangulated against top-down macroeconomic indicators.
Market size and growth trajectory outputs reflect segment-level modeling across product type, technology tier, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs derive from fitted trend analysis incorporating urban household formation rates, electrification program extension timelines, and efficiency standard implementation schedules. Industry-specific forecast inputs include variable-speed compressor adoption curves and refrigerant chemistry transition cost profiles.
Caveats apply where divergent national efficiency test protocols or accelerated F-Gas Regulation phase-down timelines could materially shift the outlook for sealed system platform economics. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
South Africa Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Built-In Hobs Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Europe Small Home Appliances Market
Home Appliances
Kuwait Major Home Appliances Market
Home Appliances
Home Laundry Appliances Market
Home Appliances
United States Household Refrigerators Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
North America Major Home Appliances Market