
 United Arab Emirates Data Center Cooling Market | 2026-2036
United Arab Emirates Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Data Center Cooling Market Insights
Capital-intensity divergence between hyperscale-ready cooling infrastructure and legacy air-cooled deployments is bifurcating the vendor landscape. Schneider Electric SE leverages its integrated power and cooling architecture to anchor large-scale projects across Dubai South. Vertiv Group Corp competes through thermal management specialization for high-density GPU clusters. Stulz GmbH sustains its position with precision air conditioning systems purpose-built for the Gulf's extreme ambient conditions.
Data center cooling encompasses engineered thermal management systems that maintain IT equipment within operational temperature thresholds, typically between eighteen and twenty-seven degrees Celsius, using chilled water loops, direct expansion refrigerant cycles, or dielectric fluid immersion baths to dissipate heat generated by servers and storage arrays. Liquid cooling solutions are capturing disproportionate investment as AI training workloads push rack densities beyond thirty kilowatts per rack in Abu Dhabi and Dubai facilities. Among end users, hyperscale data centers and cloud service providers command the dominant share of capital deployment, while colocation providers retrofit existing white space with hybrid air-liquid architectures to extend asset lifecycles.
MOHAP and the Emirates Authority for Standardization and Metrology enforce energy efficiency benchmarks that mandate minimum performance thresholds for cooling equipment deployed in federal data centers. The UAE's net-zero commitments for Dubai and Abu Dhabi are accelerating specifications for low-global-warming-potential refrigerants and free cooling economizer hours. Stakeholders must monitor how liquid cooling infrastructure investments align with evolving district cooling integration requirements and carbon disclosure frameworks.
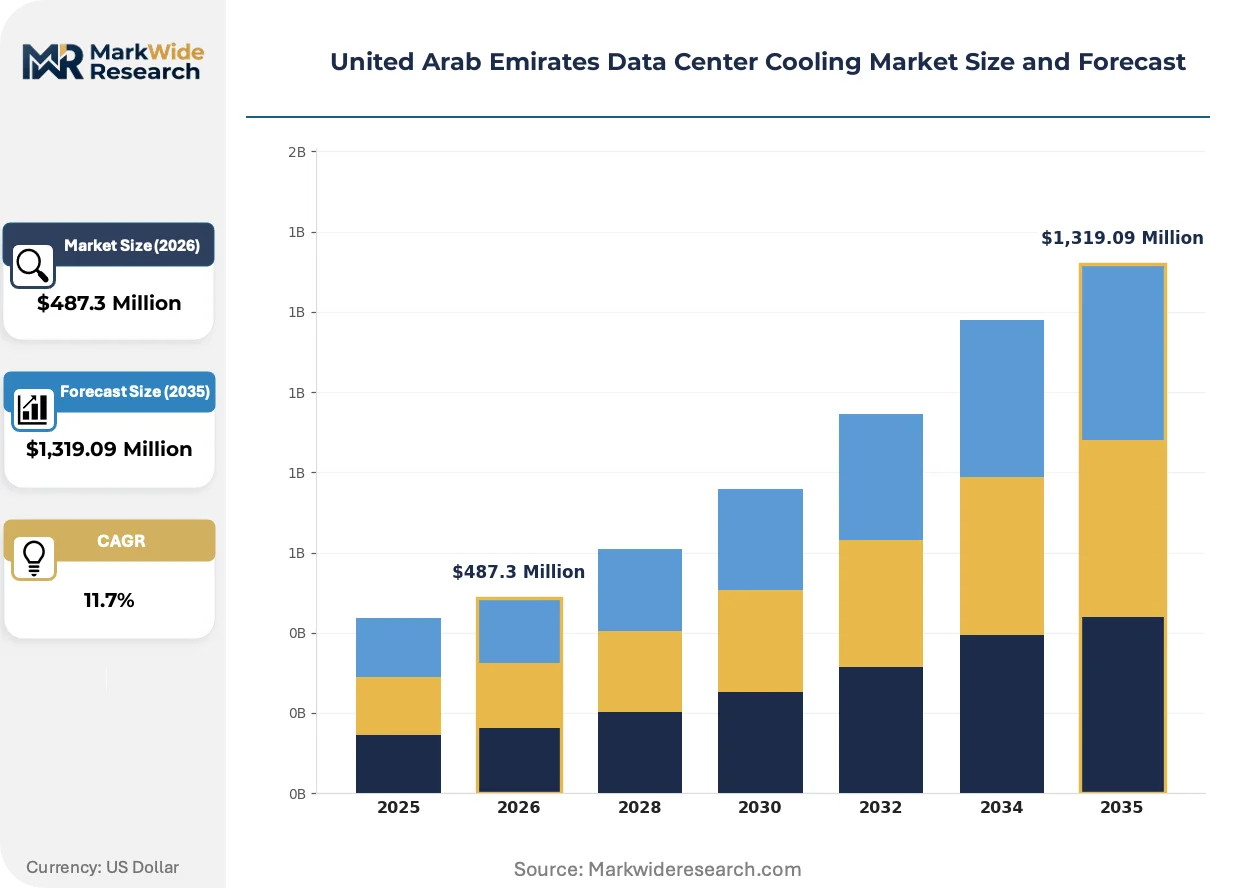
Market Dynamics
Liquid cooling infrastructure investments are compressing deployment timelines for AI-ready facilities across Dubai and Abu Dhabi, forcing incumbent air-cooled vendors to reposition or exit high-density segments entirely.
Growth Catalysts
- MOHAP Efficiency Mandates:Federal data centers must meet escalating performance thresholds for cooling equipment, accelerating replacement cycles in Dubai Internet City and Masdar City facilities.
- GPU Cluster Density Surge:AI training workloads in Abu Dhabi are pushing rack densities beyond thirty kilowatts, creating immediate demand for dielectric fluid immersion and direct-to-chip cooling architectures.
- District Cooling Integration:Emirates District Cooling integration requirements are unlocking capital-efficient thermal pathways for hyperscale campuses seeking carbon disclosure alignment.
Market Restraints
- Refrigerant Supply Concentration:Low-global-warming-potential refrigerant supply chains concentrate among European and East Asian chemical producers, exposing UAE projects to import volatility and extended lead times.
- Legacy Asset Stranding:Existing air-cooled white space in Dubai's older colocation facilities faces accelerated obsolescence as liquid-cooled AI pods command premium tenancy rates.
- Technical Skill Scarcity:Dielectric fluid handling and immersion bath maintenance expertise remains concentrated among a narrow technician pool, constraining deployment velocity for liquid-cooled installations.
Strategic Opportunities
- Masdar City Sustainable Computing Zone:Net-zero commitments and free cooling economizer hour specifications are creating a testbed for integrated solar-thermal and liquid cooling hybrid architectures.
- Free Zone Regulatory Tailwinds:Dubai South and Abu Dhabi Global Market free zone incentives are attracting cloud service providers seeking rapid permitting for high-density cooling infrastructure.
- Retrofit Hybrid Air-Liquid Systems:Colocation providers are extending asset lifecycles through phased liquid cooling integration, preserving existing white space while accommodating GPU-intensive tenants.
Industry Challenges
- Certification Timeline Compression:Emirates Authority for Standardization and Metrology equipment approval processes are struggling to match the pace of liquid cooling technology iteration, delaying commercialization.
- Integration Complexity with Legacy Power Distribution:Existing uninterruptible power supply and busbar configurations in Dubai Internet City facilities require substantial reengineering to support liquid cooling pump redundancy and leak detection systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Data Center Cooling Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Liquid Cooling, Air Cooling, Evaporative Cooling, Immersion Cooling End User: Colocation Providers, Enterprises, Hyperscale Data Centers, Cloud Service Providers Installation Type: New Construction, Retrofitting, Modular System, Upgraded Facilities Cooling Technology: Chilled Water Systems, Direct Expansion, Free Cooling, Fans |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Stulz GmbH, Asetek A/S, Mitsubishi Electric Corporation, Johnson Controls International plc, Daikin Industries Ltd, Emerson Electric Co, Rittal GmbH and Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Data Center Cooling Market Trends and Innovations
Direct-to-chip and immersion cooling technologies are fragmenting the vendor landscape as established precision air conditioning specialists compete with industrial fluid systems entrants for AI workload contracts.
Dielectric fluid immersion baths are fragmenting the high-density cooling market. These systems submerge server assemblies in thermally conductive, electrically insulating liquids, eliminating air-handling infrastructure entirely. Hyperscale operators in Abu Dhabi are piloting single-phase immersion for training clusters exceeding forty kilowatts per rack. The technology is fragmenting procurement patterns by decoupling thermal performance from traditional HVAC vendor relationships.
MOHAP and the Emirates Authority for Standardization and Metrology are tightening energy efficiency benchmarks for federal facility cooling equipment. These mandates establish minimum coefficient-of-performance thresholds that legacy direct-expansion systems cannot satisfy. Colocation providers in Dubai are responding by accelerating hybrid retrofit timelines to maintain tenancy eligibility for government-contracted workloads.
Cloud service providers are consolidating procurement authority for thermal infrastructure at the hyperscale engineering level rather than delegating to facility operators. This centralization is compressing vendor engagement cycles and privileging integrated power-cooling architectures over component specialists. The shift is most visible in Dubai South, where Schneider Electric and Vertiv compete for anchor tenant specifications through design-build partnerships rather than equipment-only tenders.
United Arab Emirates Data Center Cooling Market Segmentation
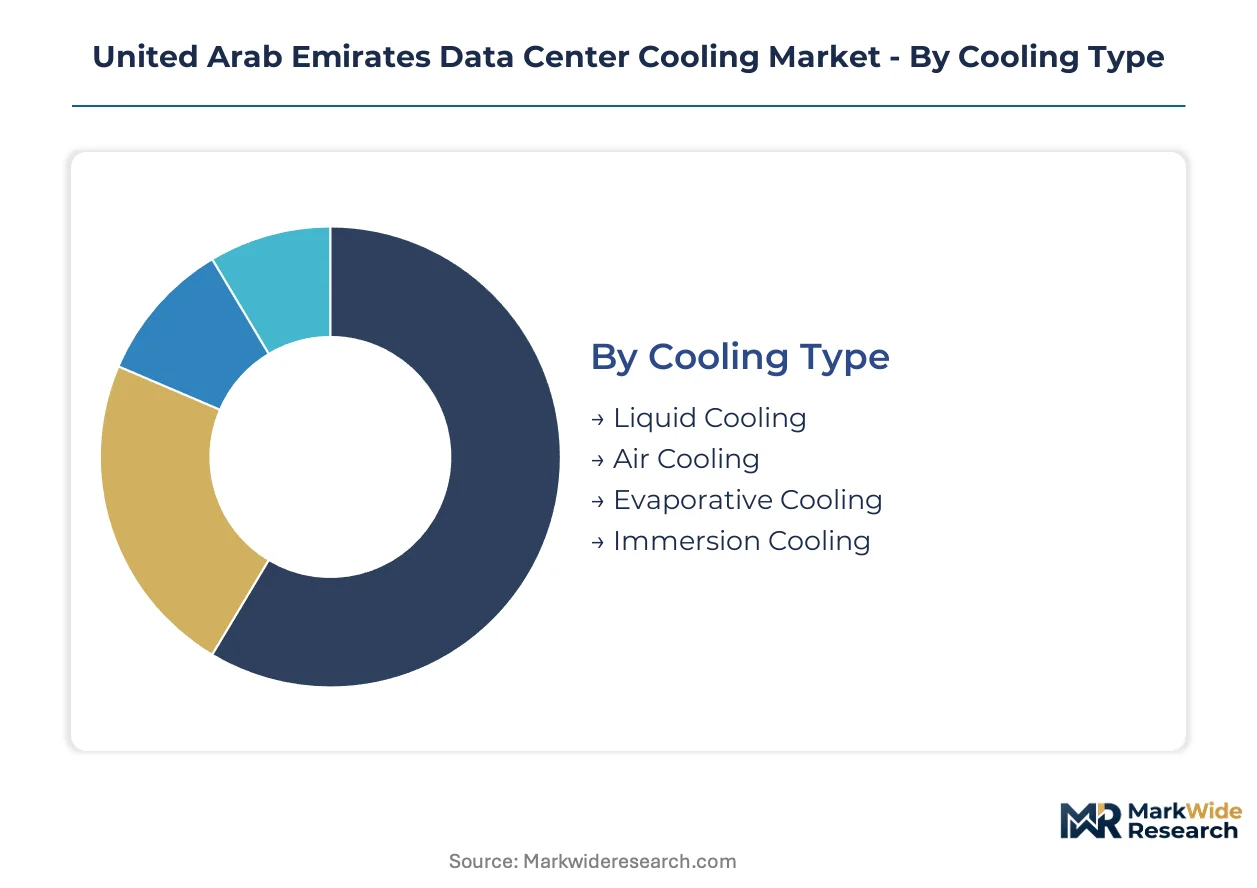
Segmentation in the UAE data center cooling market reveals how procurement authority concentrates and where technology transitions create margin migration. Cooling type and end user classifications expose the divergence between legacy infrastructure maintenance and AI-ready liquid cooling deployment.
Cooling Type:
Premium margins pool in liquid cooling solutions as hyperscale operators pay substantial premiums for thermal systems capable of sustaining GPU-intensive workloads.
- Liquid Cooling:Direct-to-chip and cold plate architectures circulate dielectric fluids through server assemblies to dissipate heat from processors exceeding 500 watts. Abu Dhabi hyperscale facilities are mandating liquid cooling specifications for training clusters surpassing thirty kilowatts per rack, driven by MOHAP efficiency thresholds that legacy systems cannot satisfy.
- Immersion Cooling:Complete server submersion in thermally conductive, electrically insulating fluids eliminates air-handling infrastructure and enables rack densities beyond forty kilowatts. Dubai South cloud campuses are piloting single-phase immersion for AI workloads, constrained by technician scarcity for dielectric fluid handling and leak detection protocols.
- Air Cooling:Precision air conditioning units and computer room air handlers remain prevalent in legacy colocation facilities across Dubai Internet City, though facing accelerated obsolescence as liquid-cooled pods command premium tenancy rates.
- Evaporative Cooling:Adiabatic cooling systems leverage the Gulf's low humidity periods to reduce mechanical refrigeration loads, finding application in Masdar City's sustainable computing zone where free cooling economizer hours align with net-zero commitments.
The dominant share belongs to air cooling, while liquid cooling is closing the gap fastest.
End User:
Volume concentration tracks capital deployment authority, with hyperscale operators consolidating thermal infrastructure procurement at the engineering level rather than delegating to facility managers.
- Hyperscale Data Centers:Operators with single-tenant campuses exceeding ten megawatts deploy integrated power-cooling architectures through design-build partnerships, specifying direct-to-chip liquid cooling for AI training infrastructure in Dubai South and Abu Dhabi.
- Cloud Service Providers:Multi-tenant platform operators prioritize rapid permitting in free zones and modular liquid cooling integration to accommodate variable GPU cluster densities, with procurement cycles compressing as thermal decisions centralize at headquarters engineering teams.
- Colocation Providers:Multi-tenant facility operators in Dubai Internet City face stranded asset risk from legacy air-cooled white space, responding with hybrid retrofit timelines to preserve tenancy eligibility for government-contracted workloads under MOHAP mandates.
- Enterprises:Private data center operators in federal and financial services sectors prioritize compliance with Emirates Authority for Standardization and Metrology equipment approvals, driving replacement cycles for direct expansion systems that fail minimum coefficient-of-performance thresholds.
Hyperscale data centers command the dominant share, while cloud service providers are expanding most quickly.
Installation Type:
Project velocity and margin structure diverge sharply between greenfield campuses with integrated thermal design and constrained retrofit environments with legacy power distribution limitations.
- New Construction:Greenfield hyperscale campuses in Dubai South and Masdar City incorporate liquid cooling infrastructure from foundation design, enabling district cooling integration and solar-thermal hybrid architectures that align with carbon disclosure frameworks.
- Retrofitting:Existing facilities in Dubai Internet City require substantial reengineering of uninterruptible power supply and busbar configurations to support liquid cooling pump redundancy, compressing project timelines and elevating integration risk.
- Modular System:Factory-integrated cooling modules with pre-tested pump redundancy and leak detection systems accelerate deployment for cloud service providers seeking rapid capacity expansion in Abu Dhabi Global Market free zones.
- Upgraded Facilities:Phased liquid cooling integration in colocation environments extends asset lifecycles while accommodating GPU-intensive tenants, preserving existing white space through hybrid air-liquid architectures.
New construction claims the dominant share, while retrofitting faces the steepest capacity constraints.
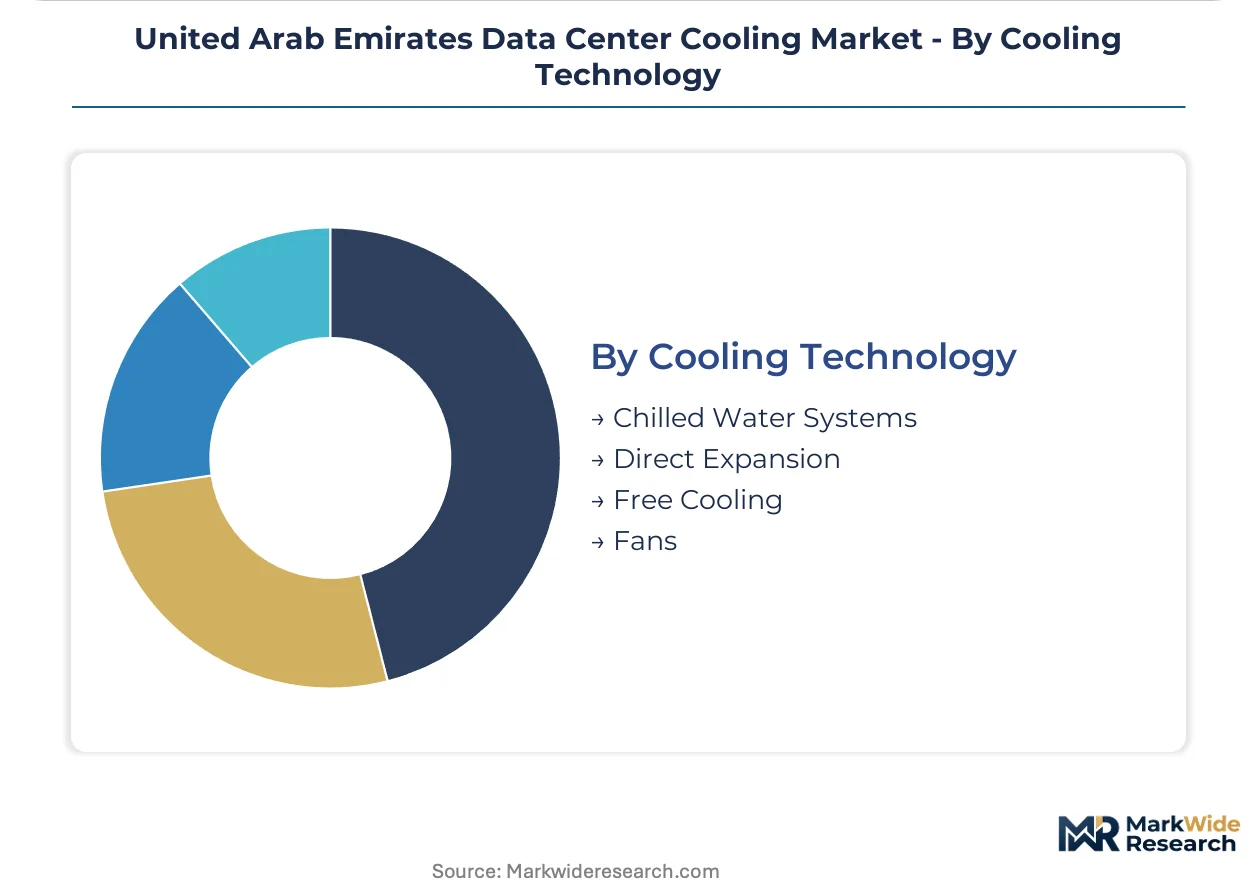
Cooling Technology:
Technology selection reflects the tension between district cooling integration opportunities and refrigerant supply chain vulnerabilities exposed by low-global-warming-potential chemical import concentration.
- Chilled Water Systems:Centralized chilled water loops distribute cooling capacity across hyperscale halls, with Dubai facilities increasingly integrating Emirates District Cooling infrastructure to reduce on-site refrigeration plant capital and operating costs.
- Direct Expansion:Self-contained refrigerant-based systems face replacement pressure from MOHAP efficiency mandates, with legacy installations in older colocation facilities unable to satisfy escalating coefficient-of-performance thresholds.
- Free Cooling:Economizer systems exploit ambient temperature differentials during winter months to bypass mechanical refrigeration, with Masdar City specifications mandating minimum free cooling hour targets for sustainable computing zone eligibility.
- Fans:Air movement infrastructure persists as a component in hybrid architectures and legacy facilities, though declining as a standalone cooling approach for densities exceeding fifteen kilowatts per rack.
Chilled water systems hold the dominant share, while free cooling is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE data center cooling market exhibits pronounced sub-regional concentration, with capital deployment gravitating toward emirates offering free zone incentives and district cooling integration. Import dependency for low-global-warming-potential refrigerants and dielectric fluids shapes procurement timelines across all emirates.
Dubai
Dubai Internet City and Dubai South anchor hyperscale expansion, with cloud service providers consolidating thermal infrastructure procurement at headquarters engineering levels. MOHAP efficiency mandates for federal facilities accelerate replacement cycles in older colocation assets. Masdar City's sustainable computing zone pilots solar-thermal hybrid architectures with free cooling economizer specifications.
Abu Dhabi
Abu Dhabi Global Market free zone incentives compress permitting timelines for GPU-intensive AI training clusters exceeding thirty kilowatts per rack. The Emirates Authority for Standardization and Metrology enforces equipment approval processes that strain to match liquid cooling iteration velocity. Yas Island and Khalifa Port industrial zones concentrate hyperscale campus development with district cooling integration requirements.
Sharjah
Sharjah Research Technology and Innovation Park attracts modular cooling deployments through cost-competitive land and power arrangements. The emirate's national pharmaceutical regulator alignment with federal MOHAP standards ensures equipment interoperability across UAE facilities. Industrial zones near Sharjah International Airport host retrofit-oriented colocation providers extending legacy air-cooled asset lifecycles.
Northern Emirates
Ras Al Khaimah and Fujairah leverage lower operational costs to capture disaster recovery and backup facility demand from Dubai and Abu Dhabi operators. Federal net-zero commitments apply uniformly, driving refrigerant specification convergence across all seven emirates. Subsea cable landing stations in Fujairah create edge computing node demand for compact liquid cooling modules.
United Arab Emirates Data Center Cooling Market Competitive Landscape
Concentration sits with integrated power-cooling architecture specialists and thermal management pure-plays competing for hyperscale engineering specifications. The vendor landscape bifurcates between legacy precision air conditioning incumbents and industrial fluid systems entrants targeting AI workload densities. Two strategic archetypes dominate: design-build integrators anchoring greenfield campuses and retrofit specialists preserving existing white space through hybrid architectures. Competitive moves center on district cooling partnership structures and modular factory-integrated system pre-certification to compress deployment timelines.
Within the integrated architecture tier, Schneider Electric SE exemplifies the design-build partnership model across Dubai South anchor tenant specifications. Vertiv Group Corp occupies a position among thermal management specialists targeting high-density GPU cluster requirements. Stulz GmbH represents the precision air conditioning archetype purpose-engineered for extreme Gulf ambient conditions, sustaining relevance in legacy facility maintenance segments while repositioning toward hybrid liquid-air retrofit offerings.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Stulz GmbH |
| Asetek A/S |
| Mitsubishi Electric Corporation |
| Johnson Controls International plc |
| Daikin Industries Ltd |
| Emerson Electric Co |
| Rittal GmbH and Co. KG |
| Others |
Pricing and Supply Chain Analysis
Hyperscale capacity utilization above eighty percent across Dubai South and Abu Dhabi Global Market concentrates procurement leverage among cloud service providers and AI training operators, compressing margin pools for component specialists while elevating integrated architecture premiums. This scale concentration simultaneously tightens dielectric fluid and low-global-warming-potential refrigerant supply chains around European and East Asian chemical producers, establishing import-dependent price floors that resist localization efforts.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures for liquid cooling infrastructure, with three-tier pricing stratification across premium direct-to-chip systems, standard cold plate architectures, and economy-grade retrofit hybrid modules. Price differentiation hinges on Emirates Authority for Standardization and Metrology pre-certification status and district cooling integration capability, with certified systems commanding substantial premiums. Pricing pressure intensifies in legacy air-cooled segments as MOHAP efficiency mandates accelerate replacement cycles, while hyperscale operators exhibit lowest price sensitivity due to tenancy rate premiums for AI-ready thermal infrastructure.
Supply Chain Analysis
Strategic stockpiling of dielectric fluids and specialized refrigerants dominates inventory strategy given European and East Asian chemical producer concentration and extended maritime lead times through Jebel Ali. Manufacturing draws from Germany, Japan, and South Korea for precision pumps and heat exchangers, while fluorinated fluid production rests on Belgian and American specialty chemical capacity. Single-source vulnerability concentrates in immersion cooling dielectric formulations, with distribution running through Dubai-based system integrators holding Emirates District Cooling partnership credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where MOHAP efficiency mandates and Emirates Authority for Standardization and Metrology certification timelines create structural barriers that favor incumbents with approved equipment portfolios and established government contracting relationships.
For Market Incumbents: Secure anchor tenant specifications in Dubai South and Masdar City through design-build partnerships that bundle power distribution with liquid cooling infrastructure, insulating against industrial fluid systems entrants targeting GPU cluster density segments. Deepen backward integration into dielectric fluid handling technician certification programs to constrain deployment velocity for competitors lacking training infrastructure. For New Entrants and Emerging Players: Retrofit service gaps in Dubai Internet City's legacy colocation facilities offer penetrable entry points, where hybrid air-liquid integration expertise addresses stranded asset risk among operators facing MOHAP compliance deadlines. Target modular factory-integrated cooling systems for Abu Dhabi Global Market free zone rapid deployment requirements, leveraging pre-tested pump redundancy configurations to compress permitting timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among thermal management pure-plays with district cooling partnership structures and long-term service contracts tied to hyperscale campus expansion. Acquisition focus should center on firms holding Emirates Authority for Standardization and Metrology pre-certification for direct-to-chip and immersion technologies, with inflection signal concentrated in GPU cluster density specifications crossing forty kilowatts per rack.| Strategic Initiative | Industry Significance |
|---|---|
| District Cooling Partnership | Emirates District Cooling integration unlocks capital-efficient thermal pathways for hyperscale campuses seeking carbon disclosure alignment. |
| Technician Certification Program | Dielectric fluid handling expertise scarcity constrains deployment velocity, making captive training capacity a competitive differentiator. |
| Pre-Certification Investment | Emirates Authority for Standardization and Metrology approval timelines lag technology iteration, favoring early regulatory engagement. |
| Hybrid Retrofit Capability | Phased liquid cooling integration extends legacy asset lifecycles while preserving tenancy eligibility under MOHAP mandates. |
| Free Zone Rapid Deployment | Modular factory-integrated systems compress permitting timelines for cloud service providers in Dubai South and Abu Dhabi Global Market. |
Research Methodology
The analysis maps liquid cooling infrastructure, air-cooled legacy maintenance, and hybrid retrofit segments, each validated through hyperscale engineering directors, colocation facility operators, Emirates District Cooling procurement leads, and thermal systems integration specialists. Primary interview findings triangulate against SEC filings from listed infrastructure providers, hyperscaler capital expenditure disclosures, MOHAP regulatory bulletins, and Emirates Authority for Standardization and Metrology equipment approval databases. Bottom-up installation tracking across Dubai Internet City, Dubai South, Masdar City, and Abu Dhabi Global Market converges with top-down emirate-level capacity modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning cooling type, end user archetype, installation format, and technology architecture. CAGRs derive from installation pipeline analysis, tenancy rate projections for AI-ready versus legacy thermal infrastructure, and replacement cycle acceleration under federal efficiency mandates. Forecast inputs incorporate GPU cluster density specifications, district cooling integration adoption curves, and refrigerant supply chain lead time assumptions.
Underlying assumptions cover MOHAP mandate enforcement consistency, hyperscale capital commitment continuity, and dielectric fluid supply chain stability, with deviation risk concentrated in Emirates Authority for Standardization and Metrology certification timeline compression and low-global-warming-potential refrigerant import volatility. Revision becomes warranted when GPU cluster density specifications exceed modeled thermal dissipation thresholds or district cooling integration requirements shift materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market