
 AI Datacenter Liquid Cooling Market | 2026-2036
AI Datacenter Liquid Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
AI Datacenter Liquid Cooling Market Insights
Multi-source procurement for coolant distribution units and heat exchangers is broadening as hyperscale operators diversify supply risk across specialist vendors. Vertiv leverages its integrated power and thermal portfolio to anchor large-scale deployments across North American cloud campuses. Schneider Electric sustains competitive positioning through prefabricated modular cooling architectures that compress deployment timelines. CoolIT Systems specializes in direct-to-chip cold plate assemblies for GPU-intensive servers, occupying a narrow but technically defensible tier.
AI datacenter liquid cooling encompasses closed-loop thermal management systems that transfer heat from high-density computing hardware via dielectric fluids or water-glycol mixtures, operating at supply temperatures between 40°C and 60°C to capture waste heat for reuse or rejection. The primary purpose is sustaining reliable performance of AI accelerators whose thermal design power now exceeds 700 watts per processor. Immersion cooling commands attention for extreme-density racks exceeding 100 kilowatts, while direct-to-chip approaches dominate mainstream hyperscale adoption due to retrofit compatibility. Rear door heat exchangers serve enterprise colocation facilities where infrastructure overhaul options remain constrained by lease structures and capital cycles.
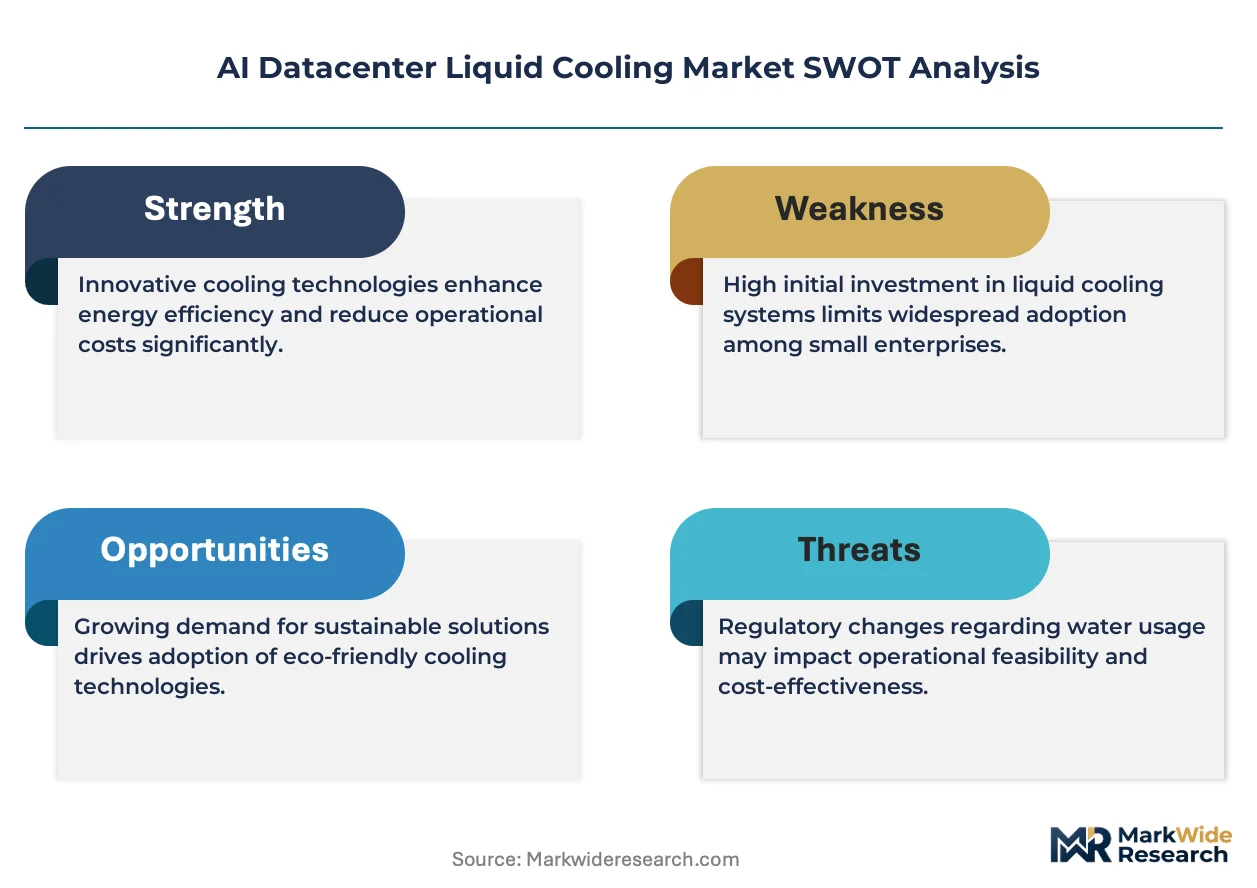
The US Department of Energy imposes efficiency benchmarks that effectively mandate liquid cooling for federal AI procurement, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in legacy chiller systems. China's MIIT enforces data center power usage effectiveness ceilings that favor liquid-based heat rejection in eastern provinces where grid capacity tightens. Stakeholders must weigh coolant chemistry choices against evolving fire safety codes and material compatibility standards as rack densities continue climbing.
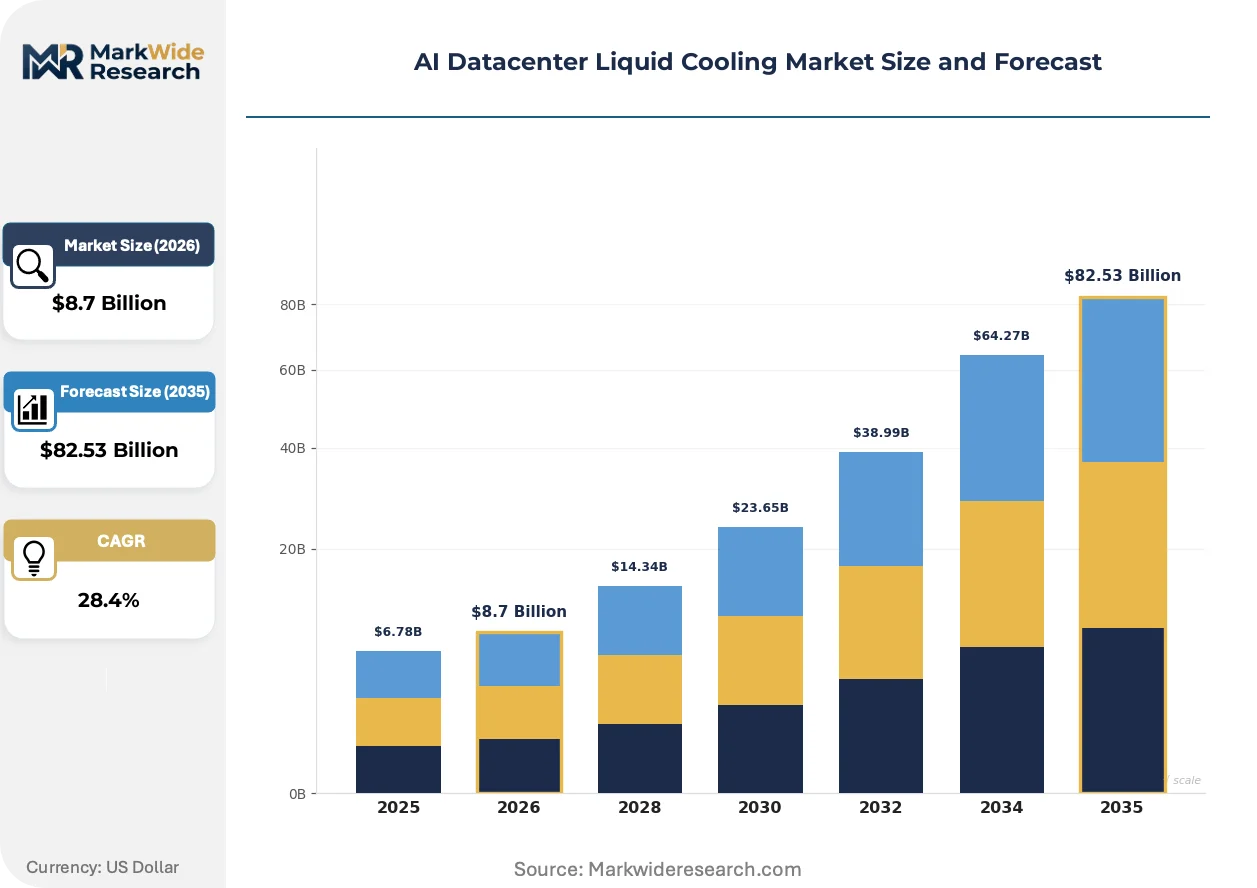
Market Dynamics
GPU thermal design power thresholds now exceed 700 watts per processor, forcing hyperscale operators to abandon air-cooled architectures and commit capital to liquid infrastructure before rack densities render legacy facilities obsolete.
Growth Catalysts
- EU F-Gas Regulation:Hydrofluorocarbon phase-down mandates are accelerating chiller replacements with liquid-based heat rejection systems across European cloud campuses.
- AI training clusters:Hyperscale operators deploying 100+ kilowatt racks require direct-to-chip and immersion cooling to sustain accelerator performance without thermal throttling.
- Dielectric fluid chemistry:Advances in synthetic coolants with improved material compatibility are expanding retrofit options for existing server footprints.
Market Restraints
- Specialized component supply:Precision cold plate manufacturing concentrates among Asian metalwork suppliers, creating single-source vulnerability for North American integrators.
- Facility retrofit costs:Enterprise colocation operators face lease structure barriers that prevent infrastructure overhaul despite technical necessity.
- Fire safety code friction:Evolving standards for dielectric fluid deployment in occupied spaces delay permitting timelines in multiple jurisdictions.
Strategic Opportunities
- Waste heat recovery:District heating integration in Germany and Nordic markets creates secondary revenue streams from 40-60°C coolant discharge temperatures.
- Prefabricated modular architectures:Factory-integrated cooling and power skids compress deployment timelines for rapid AI cluster scaling.
- China MIIT efficiency ceilings:Eastern provincial power usage effectiveness mandates favor liquid cooling adoption for new data center approvals.
Industry Challenges
- Thermal-fluid engineering talent:Shortage of specialists capable of optimizing coolant flow rates and pressure drop across heterogeneous GPU configurations.
- Material certification timelines:Protracted validation cycles for O-ring and gasket compatibility with novel dielectric chemistries delay product releases.
- Legacy facility integration:Hybrid air-liquid environments create control complexity and monitoring fragmentation during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Datacenter Liquid Cooling Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Immersion Cooling, Direct-to-Chip Cooling, Rear Door Heat Exchanger, Cooling Plate, Hybrid Cooling Data Center Type: Hyperscale, Enterprise, Edge, Colocation, Modular End User Industry: Cloud Service Providers, Telecommunications, Financial Services, Media & Entertainment, Research Institutions Deployment Model: On-Premises, Managed Services, Hybrid Cloud, Private Cloud, Public Cloud |
| Companies Covered | Vertiv, Schneider Electric, Rittal, CoolIT Systems, Submer, LiquidStack, Iceotope, Green Revolution Cooling, Modine Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Datacenter Liquid Cooling Market Trends and Innovations
Thermal management architectures are converging around standardized fluid distribution designs that reduce engineering redundancy across hyperscale deployments while enabling faster replication.
Single-phase immersion cooling is consolidating around standardized tank geometries and fluid chemistries that simplify supply chains and reduce qualification overhead. Hyperscale operators in the United States and Germany are adopting these platforms for extreme-density training clusters exceeding 100 kilowatts per rack. The technology is consolidating vendor relationships by rewarding integrated system suppliers over component specialists.
China's MIIT has tightened data center power usage effectiveness enforcement in eastern provinces where grid capacity constraints intensify. The regulation now effectively mandates liquid-based heat rejection for new facility approvals above 6,000 rack positions. Operators in Shanghai and Beijing are responding with direct-to-chip retrofits and dedicated liquid cooling builds for AI training infrastructure.
Hyperscale procurement patterns now favor multi-year thermal service agreements that bundle hardware, fluid management, and heat rejection infrastructure under single-vendor accountability. This displaces the traditional model of discrete capital purchases for chillers, CRAH units, and containment. The shift is most visible among cloud operators in the United States negotiating campus-scale deployments.
AI Datacenter Liquid Cooling Market Segmentation
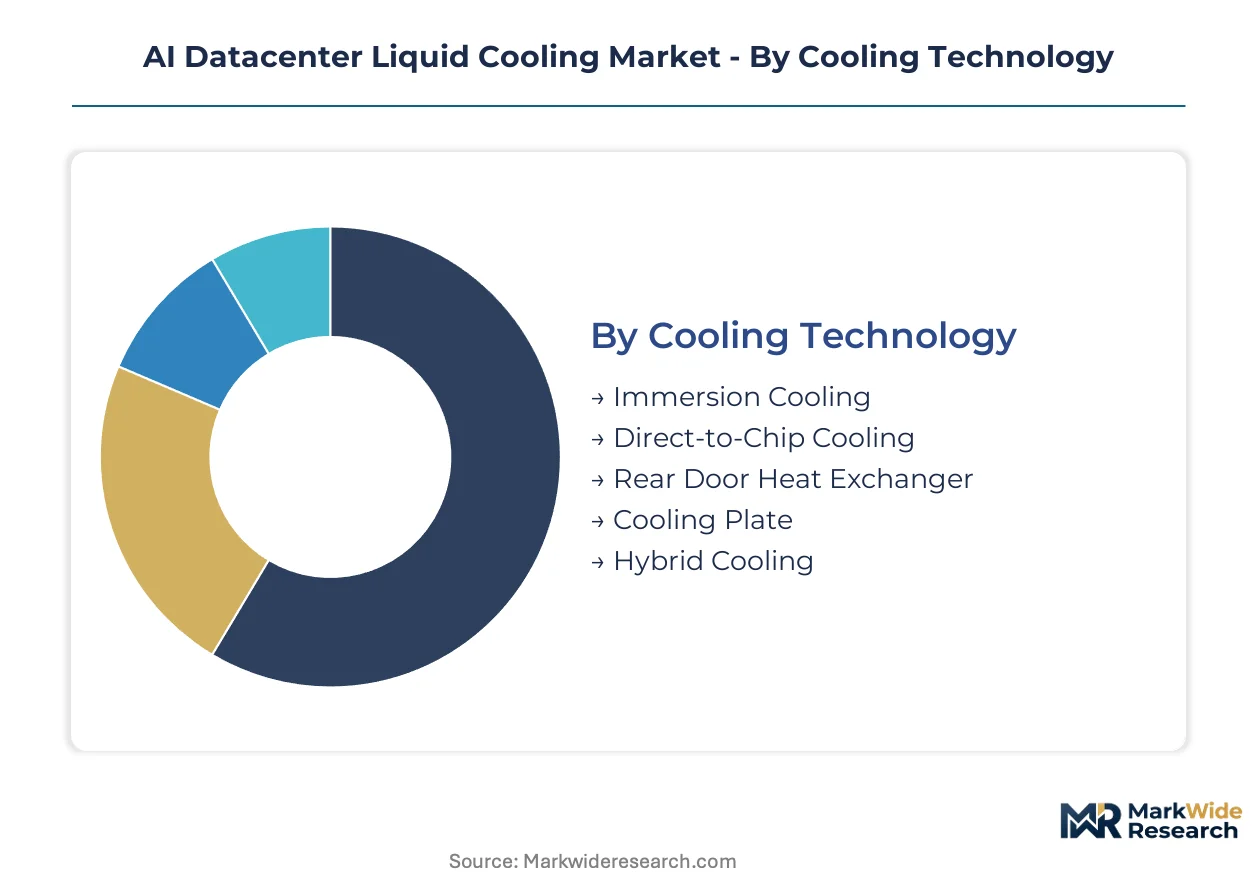
Segmentation in liquid cooling reflects divergent thermal engineering requirements across GPU densities, facility ownership models, and regulatory environments. Technology choices determine capital intensity and retrofit feasibility. End-user profiles shape procurement timelines and service bundling preferences.
Cooling Technology:
Customization intensity varies sharply across this category, from standardized cold plate assemblies to bespoke immersion tank architectures engineered for specific rack geometries.
- Immersion Cooling:Submerges entire server nodes in dielectric fluid, eliminating thermal interface resistance for racks exceeding 100 kilowatts. Hyperscale operators in Germany and the United States deploy this for AI training clusters where density mandates justify facility-level redesign.
- Direct-to-Chip Cooling:Delivers coolant through microchannel cold plates mounted directly on GPU and CPU packages, capturing heat at the source with minimal flow rates. Cloud campuses across China favor this approach for its retrofit compatibility with existing server footprints.
- Rear Door Heat Exchanger:Passive cooling coils replace standard rack rear doors, rejecting heat to facility water loops without server modification. Enterprise colocation facilities constrained by lease structures adopt this for incremental thermal capacity.
- Cooling Plate:Flat heat spreaders conduct heat from components to liquid loops through thermal interface materials, offering intermediate performance for mid-density compute nodes.
- Hybrid Cooling:Combines liquid and air handling for transitional deployments, managing mixed rack environments during infrastructure refresh cycles.
Leading the category by volume: Direct-to-Chip Cooling. Expanding most quickly: Immersion Cooling.
Data Center Type:
Capital deployment scale determines procurement patterns, from multi-billion-dollar campus builds to constrained edge installations.
- Hyperscale:Purpose-built facilities exceeding 50 megawatts with dedicated liquid cooling infrastructure from ground-up design. Operators in the United States and China dominate procurement volumes for AI training infrastructure.
- Enterprise:Corporate-owned facilities with mixed workloads and longer capital cycles, often requiring phased liquid cooling retrofits.
- Edge:Distributed compute nodes with severe space and power constraints, limiting liquid cooling to compact direct-to-chip implementations.
- Colocation:Multi-tenant facilities where lease structures complicate infrastructure overhaul despite tenant demand for high-density racks.
- Modular:Factory-integrated power and cooling skids enabling rapid deployment, favored by cloud operators compressing construction timelines.
Hyperscale commands procurement volume. Modular deployments are climbing the fastest.
End User Industry:
Workload characteristics and regulatory exposure create divergent thermal performance requirements and compliance burdens.
- Cloud Service Providers:Operate the largest AI training clusters, driving standardization of liquid cooling architectures across multiple geographies.
- Telecommunications:Deploy edge inference infrastructure with strict latency requirements, favoring compact liquid cooling for 5G core and RAN virtualization.
- Financial Services:Low-latency trading infrastructure in London, New York, and Singapore drives demand for precision thermal management of FPGA and GPU accelerators.
- Media & Entertainment:Rendering farms and real-time streaming workloads concentrate in Los Angeles and Seoul facilities with high GPU density requirements.
- Research Institutions:National laboratories and university clusters operate specialized HPC environments with custom cooling specifications for scientific computing.
Cloud Service Providers dominate procurement. Research Institutions show steepest expansion trajectory.
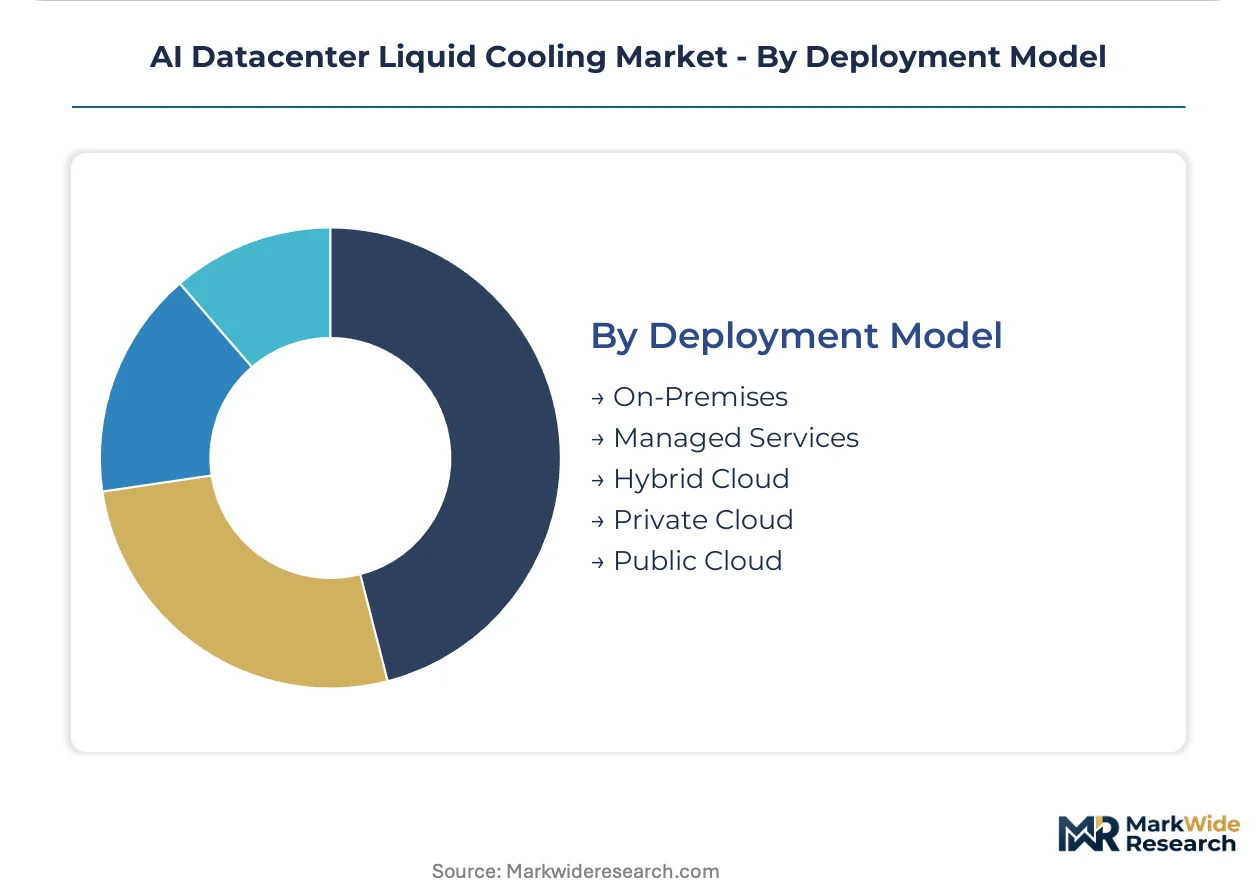
Deployment Model:
Ownership and operational responsibility allocation determines who bears thermal infrastructure capital risk and fluid management complexity.
- On-Premises:Organizations own and operate liquid cooling infrastructure directly, common among defense contractors and national research facilities with security requirements.
- Managed Services:Third-party operators assume thermal infrastructure maintenance and fluid chemistry management, reducing operational burden for enterprise AI deployments.
- Hybrid Cloud:Split workloads across owned and leased infrastructure, creating thermal design challenges for data portability and consistent performance.
- Private Cloud:Dedicated liquid cooling resources for single-tenant environments, prevalent in financial services and healthcare AI development.
- Public Cloud:Shared liquid cooling infrastructure with abstracted thermal management, the default model for mainstream AI training and inference.
Public Cloud leads by deployment volume. Managed Services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum smelting corridors in northern China anchor the liquid cooling supply chain, with dielectric fluid synthesis clustering near Shanghai's chemical industrial zones.
United States
Hyperscale cloud operators in Northern Virginia and Phoenix are deploying direct-to-chip systems for GPU clusters exceeding 700 watts per processor. The Department of Energy efficiency benchmarks mandate liquid cooling for federal AI procurement contracts. Microsoft and Amazon Web Services are expanding liquid-cooled campuses in Loudoun County, Virginia, to support training infrastructure for large language models.
China
Domestic AI chip foundries in Shanghai and Beijing are driving demand for immersion cooling as rack densities surpass 100 kilowatts. The MIIT enforces power usage effectiveness ceilings in eastern provinces that effectively require liquid-based heat rejection for new approvals above 6,000 rack positions. ByteDance and Alibaba Cloud are building dedicated liquid cooling facilities in the Yangtze River Delta to circumvent grid capacity constraints.
Germany
Industrial AI deployments in Bavaria and Baden-Württemberg are concentrating thermal infrastructure investment around automotive and manufacturing workloads. The EU F-Gas Regulation accelerates hydrofluorocarbon phase-downs that force chiller replacements with liquid heat rejection systems. Frankfurt's banking district hosts Europe's densest concentration of waste heat recovery installations, feeding district heating networks from 40-60°C coolant discharge.
Japan
Semiconductor packaging facilities in Kyushu and high-performance computing centers in Kanto require precision thermal management for GPU-intensive simulation workloads. METI efficiency standards for data center infrastructure favor liquid cooling adoption in Tokyo's power-constrained eastern wards. Fujitsu and NEC are retrofitting existing air-cooled facilities in Osaka with hybrid liquid architectures during infrastructure refresh cycles.
Singapore
Tropical ambient temperatures and severe land constraints are forcing rapid liquid cooling deployment for financial services and cloud infrastructure. The Infocomm Media Development Authority imposes sustainability standards that effectively prohibit air-cooled builds for new data center approvals above 5 megawatts. Equinix and Google Cloud are constructing immersion-cooled facilities in Jurong to maximize compute density per square meter.
AI Datacenter Liquid Cooling Market Competitive Landscape
Multi-year thermal service agreements dominate the current landscape as hyperscale operators disperse discrete capital purchases. The vendor base stratifies across integrated infrastructure conglomerates, specialist cold plate fabricators, and immersion system pure-plays. Three archetypes occupy distinct positions: power-thermal integrators anchoring campus-scale deployments, component specialists defending narrow technical tiers, and fluid chemistry innovators capturing retrofit opportunities. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as operators seek geographic redundancy and supply security.
Within the integrated infrastructure tier, Vertiv and Schneider Electric exemplify scale-driven positioning through prefabricated modular architectures that compress deployment timelines. CoolIT Systems occupies a defensible specialist position focused on direct-to-chip cold plate assemblies. These three entities collectively represent the competitive spectrum from broad power-thermal portfolios to narrow technical specialization.
| Leading Market Players |
|---|
| Vertiv |
| Schneider Electric |
| Rittal |
| CoolIT Systems |
| Submer |
| LiquidStack |
| Iceotope |
| Green Revolution Cooling |
| Modine Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive cold plate manufacturing anchors Vertiv's supply position and pricing power against Asian metalwork competitors. This upstream control over precision machining capacity insulates the company from single-source vulnerabilities while supporting multi-year thermal service agreement premiums that bundle hardware, fluid chemistry, and heat rejection infrastructure.
Pricing Analysis
Warranty and fluid management bundling separates premium thermal service agreements from unbundled capital purchases of discrete chillers and CRAH units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and customization intensity, with hyperscale cloud operators showing lowest price sensitivity due to thermal throttling risks. Cost compression in standard-tier cold plate assemblies is intensifying because Chinese MIIT efficiency enforcement is expanding addressable demand faster than specialist fabrication capacity. Enterprise colocation facilities demonstrate highest price sensitivity as lease structures prevent infrastructure overhaul despite technical necessity.
Supply Chain Analysis
Precision machining workforce availability in northern China, South Korea, and Taiwan concentrates cold plate and heat exchanger fabrication for North American integrators. Copper and aluminum smelting corridors in Hebei province feed dielectric fluid synthesis clustering near Shanghai's chemical industrial zones, creating geographic interdependency. Single-source vulnerability in O-ring and gasket compatibility certification delays product releases when novel synthetic coolants require extended validation cycles. Distribution runs through hyperscale procurement teams negotiating campus-scale deployments directly with integrated infrastructure conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold plate fabrication capacity constraints prop pricing power for incumbent specialists, as GPU thermal design power thresholds exceeding 700 watts per processor expand demand faster than precision machining expansion.
For Market Incumbents: To counter emerging immersion cooling pure-plays, Vertiv and Schneider Electric should deepen captive supply of precision cold plate assemblies through facility expansion in South Korea and Taiwan. Certification investment in fire safety code compliance for dielectric fluid deployment accelerates permitting timelines in occupied spaces where competitors face delays. For New Entrants and Emerging Players: Direct-to-chip retrofit channels for enterprise facilities constrained by lease structures offer the most penetrable white-space target, as hybrid cooling demand for transitional deployments remains underserved by integrated infrastructure conglomerates. A go-to-market angle emphasizing rapid deployment timelines through prefabricated modular architectures addresses cloud operators compressing construction schedules. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by power-thermal integrators seeking geographic redundancy and fluid chemistry capabilities. Long-term viability hinges on sustained hyperscale capex commitment to AI training infrastructure and district heating integration economics in Germany and Nordic markets. The signal to watch is MIIT enforcement intensity in eastern Chinese provinces, where power usage effectiveness ceiling tightening accelerates liquid cooling mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold Plate Manufacturing | Captive precision machining capacity insulates Vertiv from Asian supplier concentration risks. |
| Prefabricated Modular Architecture Deployment | Factory-integrated cooling skids compress timelines for Microsoft and Amazon Web Services campus builds. |
| Dielectric Fluid Chemistry Certification | Extended O-ring compatibility validation delays Submer and LiquidStack product releases against incumbents. |
| District Heating Network Integration | Waste heat recovery installations in Frankfurt create secondary revenue streams from 40-60°C coolant discharge. |
| Multi-Year Thermal Service Agreement Expansion | Bundled hardware and fluid management accountability displaces discrete capital purchase models across cloud operators. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC 10-K filings, and EU F-Gas Regulation implementation guidance, complemented by interviews with data center facility engineers, thermal infrastructure procurement leads, dielectric fluid R&D directors, and cloud operator sustainability officers. Secondary validation drew from customs and trade data tracking copper and aluminum flow into precision metalwork, MIIT enforcement bulletins, and Department of Energy efficiency benchmark documentation. Bottom-up installation forecasts triangulated against top-down hyperscale infrastructure investment projections.
Segmented outputs across cooling technology, data center type, end user industry, and deployment model dimensions fed into analytical framework spanning the projection horizon. CAGRs derived from installation volume trajectories weighted by GPU thermal design power thresholds and regulatory enforcement intensity in named geographies. Forecast inputs incorporated hyperscale rack density commitments, dielectric fluid chemistry advancement timelines, and fire safety code evolution in multiple jurisdictions.
The model holds under sustained hyperscale AI training infrastructure investment and MIIT efficiency ceiling enforcement; deviation in GPU thermal design power trajectory or F-Gas Regulation phase-down pace would shift adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Belgium Data Center Cooling Market