
 Automotive Communication Technology Market | 2026-2036
Automotive Communication Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Communication Technology Market Analysis
Software licensing revenue is reconfiguring margin pools away from discrete hardware sales toward recurring platform monetization. Qualcomm leverages its Snapdragon Digital Chassis to anchor cellular V2X modem dominance across premium vehicle programs. NXP Semiconductors sustains its position through dedicated short range communications chipsets purpose-built for low-latency safety messaging. Continental AG competes by integrating roadside unit hardware with its broader ADAS sensor portfolio.
Automotive communication technology encompasses the protocols, hardware interfaces, and network architectures enabling real-time data exchange between vehicles, infrastructure, and cloud platforms, typically operating across sub-6 GHz and millimeter-wave spectrum bands with latency requirements under 10 milliseconds for safety-critical functions. Its primary purpose is to enable cooperative intelligent transport systems that reduce collision incidence while optimizing traffic flow and energy consumption. Cellular V2X infrastructure commands the largest near-term investment as telecommunications operators partner with Tier-1 suppliers to deploy roadside units along priority corridors. The onboard unit segment differentiates through processing power tiers that separate premium autonomous driving platforms from standard safety configurations. Fleet operators represent the fastest-growing end user category as logistics providers mandate vehicle-to-infrastructure connectivity for predictive routing and regulatory compliance documentation.
The European Telecommunications Standards Institute and the US Federal Communications Commission jointly shape spectrum allocation and interoperability mandates that determine which communication protocols achieve commercial viability in their respective markets. The EU Cyber Resilience Act and US NHTSA guidance on V2X security certification create compliance thresholds that filter market access for component suppliers lacking embedded cybersecurity architectures. China's MIIT issues GB standards that localize protocol implementations for domestic intelligent transport deployments. Stakeholders must monitor divergence between regional certification regimes when designing modular communication platforms intended for multi-territory vehicle programs.
Market Dynamics
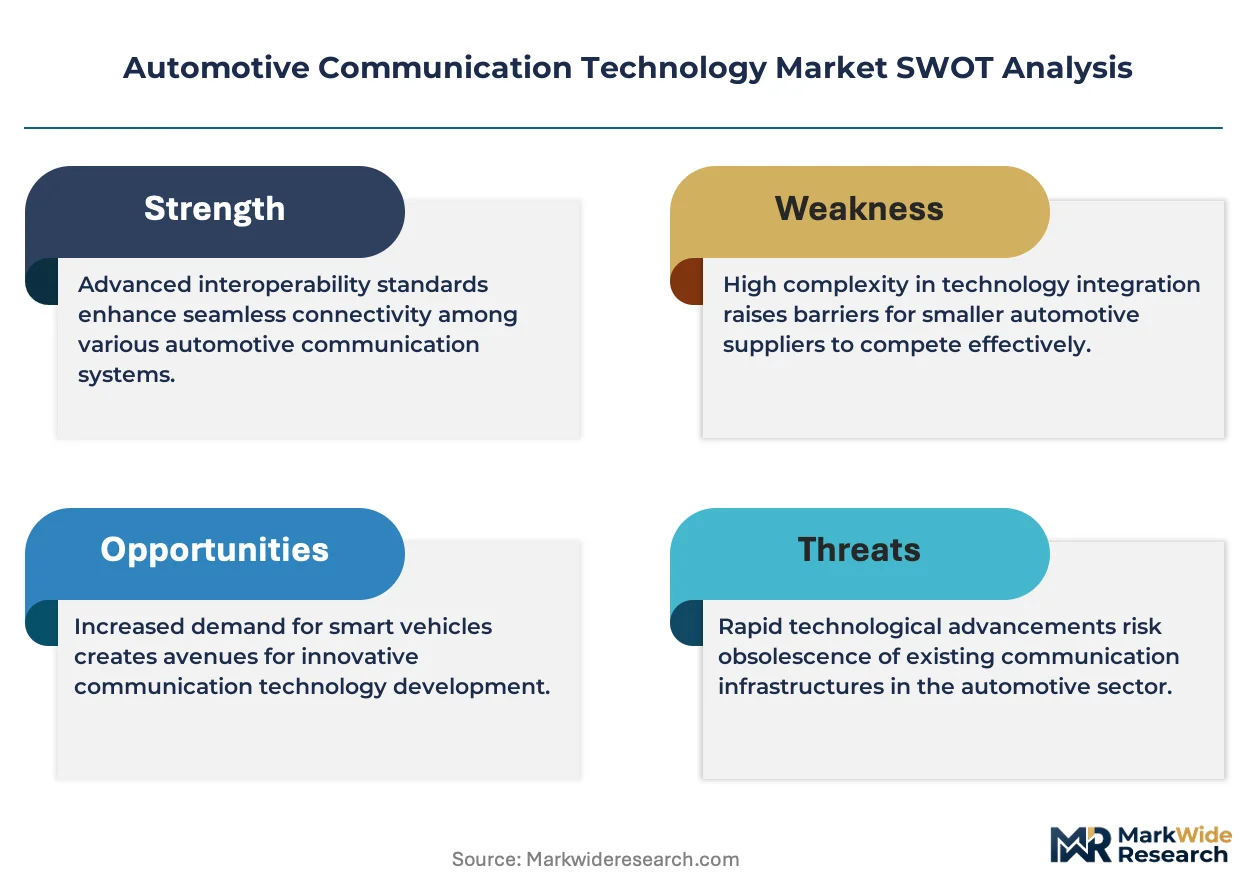
The EU Cyber Resilience Act mandates over-the-air update capabilities across all new vehicle platforms, forcing hardware refresh cycles that compress supplier development timelines and reconfigure margin pools toward recurring software licensing.
Growth Catalysts
- Cellular V2X spectrum allocation:The US Federal Communications Commission's 5.9 GHz band reconfiguration accelerates roadside unit deployment along interstate corridors. Telecommunications operators partner with infrastructure providers to enable vehicle-to-everything messaging.
- Fleet management digitization:Logistics providers mandate real-time connectivity for predictive routing and regulatory compliance documentation. Commercial vehicle operators represent the fastest-growing end user category for onboard communication units.
- Germany's automotive corridor concentration:OEM engineering centers around Stuttgart and Munich drive concentrated demand for low-latency safety messaging chipsets. Tier-1 suppliers locate R&D facilities proximate to these development hubs.
Market Restraints
- Millimeter-wave component cost structure:Gallium nitride substrate prices and specialized packaging requirements inflate bill-of-materials costs for high-bandwidth modules. Cost premiums limit penetration in economy vehicle segments.
- Regional certification fragmentation:Divergent security architectures required by the EU Cyber Resilience Act, US NHTSA guidance, and China's GB standards force redundant engineering cycles. Modular platform design adds non-recurring engineering overhead.
- DSRC protocol substitution threat:Dedicated short-range communications infrastructure faces displacement as cellular V2X achieves comparable latency performance. Prior roadside investments risk stranded asset exposure.
Strategic Opportunities
- India's intelligent transport deployment:The country's national highway expansion program creates greenfield roadside unit installation demand. Domestic automotive production growth supports localized onboard unit manufacturing partnerships.
- Edge-cloud convergence:Integration of roadside unit processing with distributed cloud architectures enables new traffic management service revenue streams. Municipal infrastructure operators seek data monetization partnerships.
- EU Green Deal mobility incentives:Carbon reduction mandates accelerate electric vehicle fleet connectivity requirements for charging optimization and grid integration. Communication modules become mandatory for energy management compliance.
Industry Challenges
- Embedded cybersecurity engineering talent scarcity:Automotive communication architecture design requires specialized expertise in hardware security modules and cryptographic key management. Universities produce insufficient graduates with cross-domain automotive and security competencies.
- Multi-standard interoperability certification timelines:Simultaneous validation against ETSI, IEEE, and 3GPP specifications extends product qualification cycles. Testing laboratory capacity constraints create queue bottlenecks for new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Communication Technology Market |
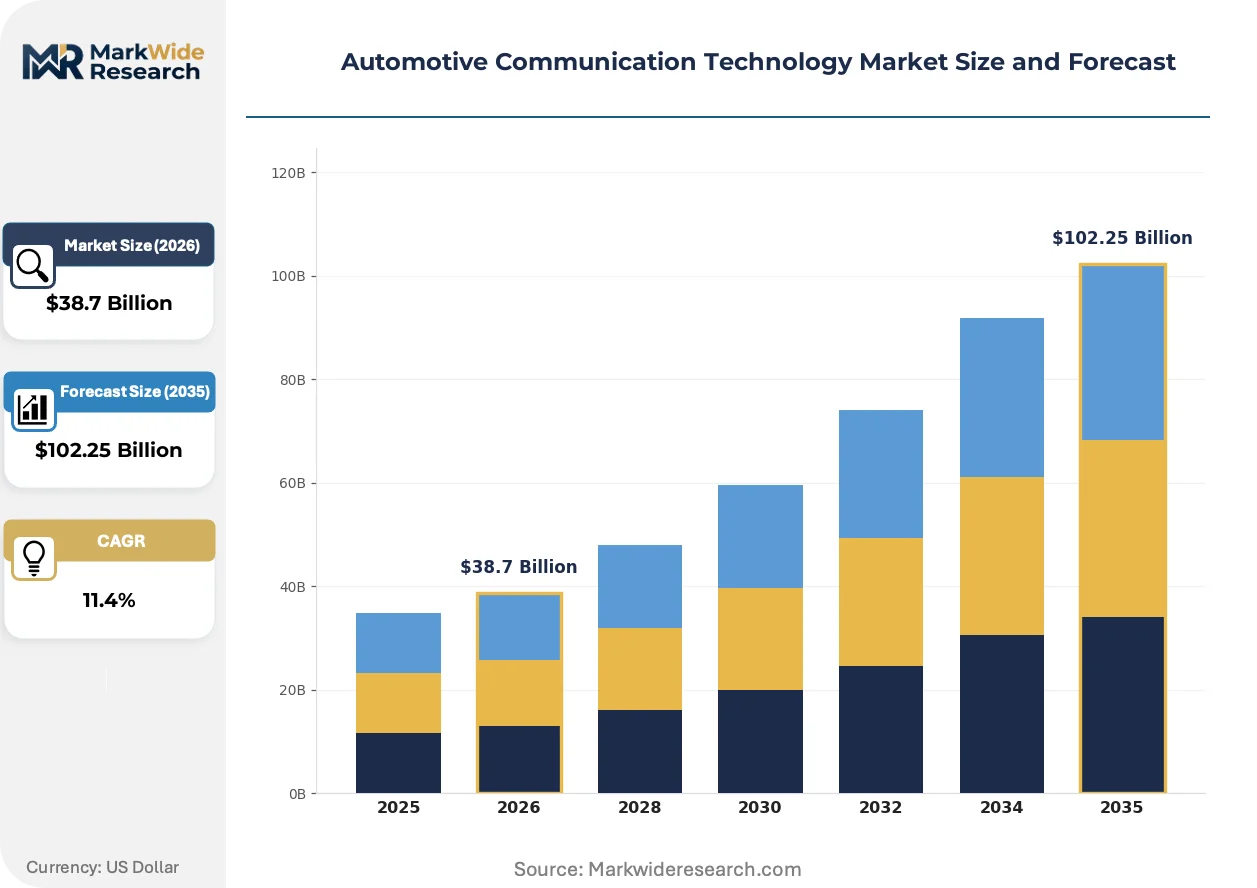
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vehicle-to-Vehicle, Vehicle-to-Infrastructure, Cellular V2X, Dedicated Short Range Communications Component: Onboard Units, Roadside Units, Antennas, Sensors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Safety Systems, Traffic Management, Infotainment, Autonomous Driving |
| Companies Covered | Qualcomm, KPIT Technologies, Continental AG, NNG, Airbiquity, Cerence, NXP Semiconductors, Bosch, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Communication Technology Market Emerging Trajectories
Software-defined vehicle architectures are collapsing traditional domain boundaries, enabling communication systems to assume central roles in safety, infotainment, and powertrain coordination through unified network backbones.
5G New Radio sidelink technology is digitizing direct vehicle-to-vehicle communication by enabling peer-to-peer messaging without network infrastructure dependency. Premium autonomous driving programs adopt this capability for cooperative perception in urban environments. The technology compresses reliance on cellular network coverage for safety-critical functions.
The EU Cyber Resilience Act mandates embedded security architectures with hardware-based root-of-trust for all connected vehicle components. Component suppliers must demonstrate vulnerability management processes and secure update mechanisms to achieve type approval. The onboard unit segment faces the steepest compliance burden as these devices bridge external networks with vehicle internal buses.
Commercial fleet operators now specify connectivity performance metrics in procurement contracts rather than accepting standard OEM configurations. Logistics providers demand guaranteed latency thresholds and uptime commitments backed by service-level agreements. This pattern is most visible in Germany's long-haul trucking sector where predictive maintenance contracts require continuous data stream reliability.
Automotive Communication Technology Market Segmentation
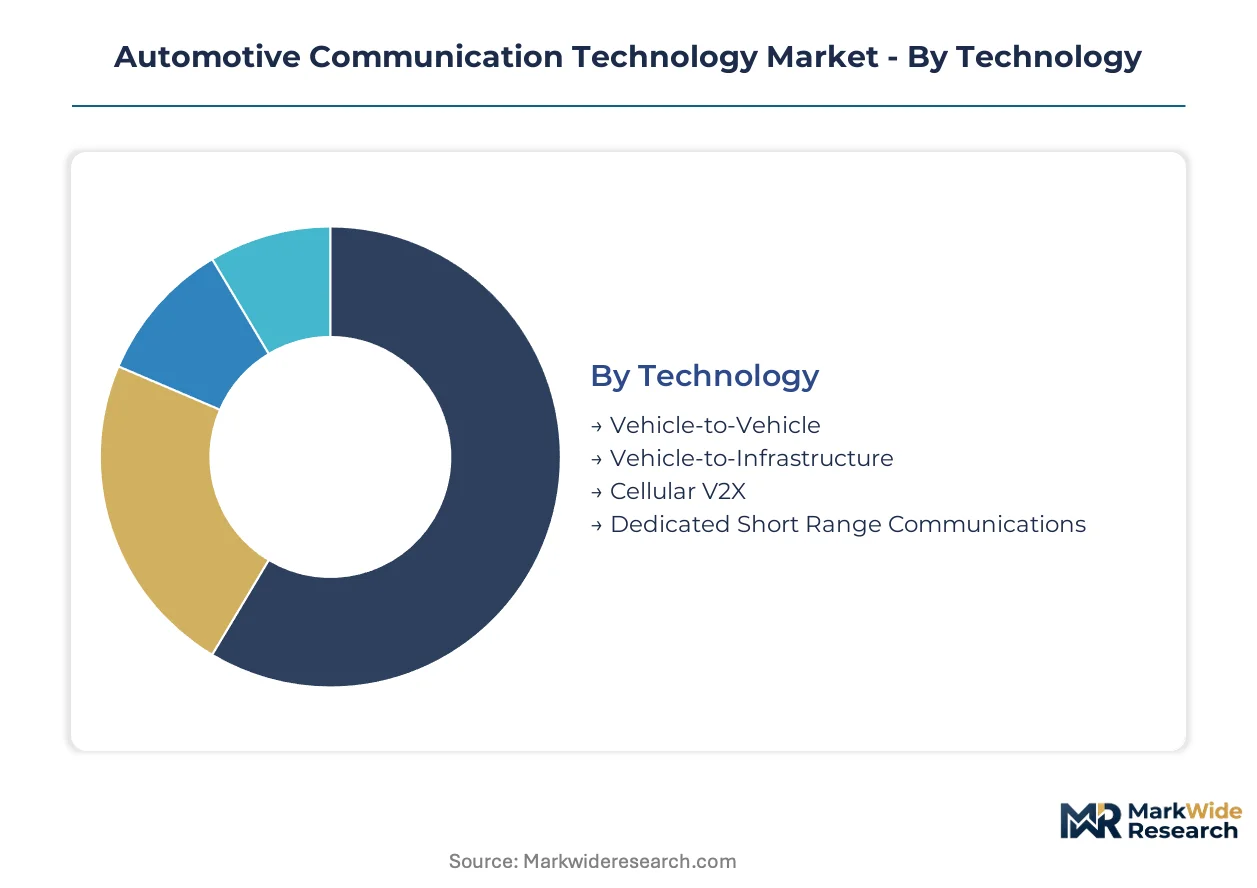
Segmentation in automotive communication technology reveals divergent hardware refresh cycles and margin structures across protocol types and component categories. Fleet procurement patterns now override traditional OEM specification hierarchies, reshaping volume distribution across end-user channels.
Technology:
Cellular V2X protocols refresh every 3-4 years as 3GPP releases advance, while DSRC hardware cycles extend toward 7-8 years due to stranded infrastructure investments.
- Cellular V2X:5G New Radio sidelink enables direct vehicle-to-vehicle messaging without network dependency. German premium OEMs concentrate procurement for urban autonomous programs, driven by EU Cyber Resilience Act update mandates. Qualcomm Snapdragon modems dominate this segment's silicon supply.
- Vehicle-to-Vehicle:Direct peer-to-peer protocols operate in 5.9 GHz spectrum with sub-10 millisecond latency for cooperative perception. Stuttgart engineering centers specify these for safety-critical platooning applications, constrained by FCC spectrum reconfiguration timelines.
- Vehicle-to-Infrastructure:Roadside coordination protocols integrate traffic signal phase and timing data. US interstate corridor deployments concentrate demand along I-75 and I-95 priority routes.
- Dedicated Short Range Communications:IEEE 802.11p-based systems face displacement risk as cellular alternatives achieve comparable performance. Prior municipal investments in Japan and US create legacy maintenance obligations.
Cellular V2X anchors the volume base while Vehicle-to-Vehicle gains share at the steepest rate.
Component:
Cost tier separation distinguishes premium autonomous platforms from standard safety configurations, with processing power and antenna array complexity driving bill-of-materials divergence.
- Onboard Units:Integrated computing platforms bridge external networks to vehicle internal buses with hardware security modules. Fleet operators in Germany's long-haul trucking sector now specify latency SLAs in procurement contracts, displacing OEM standard configurations.
- Roadside Units:Edge-processing infrastructure enables traffic management services without cloud dependency. India's national highway expansion program generates greenfield installation demand alongside domestic manufacturing partnerships.
- Antennas:Multi-band arrays covering sub-6 GHz and millimeter-wave spectrum enable simultaneous V2X and 5G connectivity. Gallium nitride substrate costs limit economy vehicle penetration.
- Sensors:Environmental perception modules feed data into communication stacks for cooperative awareness. Integration with ADAS portfolios drives Tier-1 supplier consolidation strategies.
Onboard Units generate the highest absolute revenue while Roadside Units expand most quickly through municipal infrastructure partnerships.
End User:
Procurement authority is shifting from OEM engineering centers toward fleet operators and Tier-1 suppliers as connectivity becomes a service-layer purchase rather than hardware specification.
- Fleet Operators:Commercial logistics providers mandate predictive routing and regulatory compliance documentation through guaranteed connectivity tiers. This channel now specifies performance metrics independently of OEM platforms.
- Tier-1 Suppliers:Continental AG and similar integrators bundle communication modules with ADAS sensor portfolios, capturing margin through system-level packaging rather than discrete component sales.
- OEMs:Vehicle manufacturers retain specification authority for premium autonomous programs but cede procurement control in commercial vehicle segments.
- Aftermarket Providers:Retrofit installation channels serve legacy fleet vehicles lacking factory connectivity, concentrated in North American owner-operator trucking segments.
OEMs retain the installed base while Fleet Operators command the steepest expansion trajectory in procurement volume.
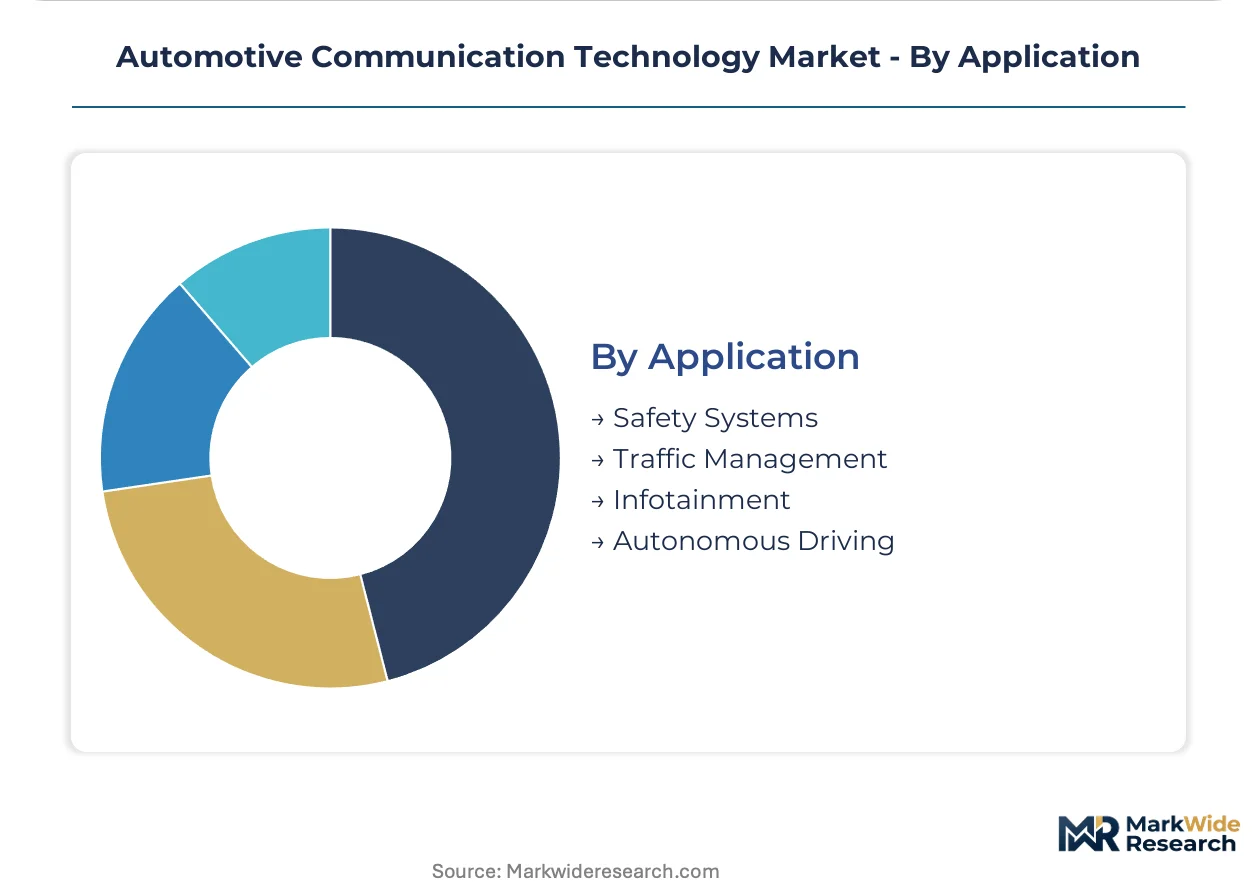
Application:
Maturity stages separate safety-critical functions with hardened certification requirements from infotainment applications where consumer electronics refresh cycles apply.
- Safety Systems:Collision avoidance and cooperative awareness functions demand sub-10 millisecond latency with functional safety certification. EU type approval processes under Cyber Resilience Act extend qualification timelines.
- Autonomous Driving:Cooperative perception in urban environments requires vehicle-to-vehicle sidelink capability. Munich and Stuttgart development hubs concentrate R&D procurement for SAE Level 4 programs.
- Traffic Management:Municipal infrastructure operators seek data monetization partnerships through edge-cloud convergence architectures.
- Infotainment:Passenger-facing connectivity applications operate with relaxed latency requirements, enabling consumer-grade silicon substitution.
Safety Systems anchor the volume base while Autonomous Driving climbs the fastest through premium platform penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication clusters in Germany, the United States, China, Japan, and South Korea concentrate the supply base for cellular V2X modems and dedicated short-range communications chipsets. Engineering talent pools and automotive OEM proximity determine where Tier-1 suppliers locate R&D facilities.
United States
The FCC's 5.9 GHz band reconfiguration accelerates roadside unit deployment along I-75 and I-95 interstate corridors. NHTSA guidance on V2X security certification creates compliance thresholds that filter market access for component suppliers. Detroit and Austin engineering centers concentrate autonomous driving program procurement for premium vehicle platforms.
Germany
OEM engineering centers around Stuttgart and Munich drive concentrated demand for low-latency safety messaging chipsets. The EU Cyber Resilience Act mandates over-the-air update capabilities that compress supplier development timelines. Continental AG and Bosch locate R&D facilities proximate to these development hubs to capture specification authority.
China
MIIT issues GB standards that localize protocol implementations for domestic intelligent transport deployments. National highway expansion programs generate greenfield roadside unit installation demand. Shanghai and Beijing technology corridors concentrate cellular V2X modem manufacturing partnerships with domestic telecommunications operators.
Japan
METI coordinates spectrum allocation for vehicle-to-infrastructure coordination alongside automated driving roadmaps. Prior municipal investments in DSRC infrastructure create legacy maintenance obligations that constrain cellular V2X migration speed. Nagoya and Tokyo metropolitan areas concentrate Tier-1 supplier engineering centers serving domestic OEM programs.
South Korea
MFDS and related agencies align automotive cybersecurity certification with international export requirements. Domestic OEMs specify 5G New Radio sidelink capability for urban autonomous programs. Seoul and Busan technology clusters anchor semiconductor packaging facilities for millimeter-wave communication modules.
Automotive Communication Technology Market Vendor Landscape
Semiconductor specialists and automotive Tier-1 integrators split the market between silicon supply and system-level packaging. The vendor base concentrates around three strategic archetypes: cellular modem designers with consumer electronics heritage, dedicated automotive chipmakers with functional safety certification, and diversified suppliers bundling communication modules with sensor portfolios. Consolidation pressure intensifies as software-defined vehicle architectures collapse traditional domain boundaries. Geographic expansion through localized manufacturing partnerships represents the dominant competitive move alongside strategic technology licensing for multi-standard interoperability.
Within the semiconductor archetype, Qualcomm and NXP Semiconductors occupy anchor positions representing divergent strategic origins. Qualcomm leverages consumer cellular heritage into automotive modem dominance, while NXP exemplifies dedicated automotive silicon specialization with short-range communications focus. Continental AG sits within the diversified Tier-1 integrator tier, bundling roadside unit hardware with broader ADAS sensor portfolios to capture system-level margin rather than discrete component revenue.
| Leading Market Players |
|---|
| Qualcomm |
| KPIT Technologies |
| Continental AG |
| NNG |
| Airbiquity |
| Cerence |
| NXP Semiconductors |
| Bosch |
| Harman International |
| Others |
Supply Flow & Price Mechanics
Stuttgart's concentrated Tier-1 engineering ecosystem anchors silicon procurement for low-latency safety messaging chipsets, translating geographic supply density into pricing leverage for premium autonomous platforms while compressing margins in standard safety configurations.
Pricing Analysis
The EU Cyber Resilience Act dictates the pricing tier structure across automotive communication modules, separating premium platforms with hardware security module integration from economy configurations lacking embedded root-of-trust architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from fleet operators. Price erosion runs through the economy vehicle segment as gallium nitride substrate costs limit component suppliers' margin flexibility. Commercial logistics providers exhibit lowest price sensitivity due to mandated connectivity SLAs, while aftermarket retrofit channels face highest sensitivity from owner-operator trucking segments.
Supply Chain Analysis
TSMC and Samsung Foundry anchor contract-manufacturing concentration for cellular V2X modem silicon, with domestic packaging partners in South Korea and Taiwan completing module assembly. The supply chain draws from gallium nitride substrate producers in Japan and specialized antenna array fabricators in Germany for millimeter-wave components. Single-source vulnerability concentrates in 5G New Radio baseband processor supply where Qualcomm's automotive-qualified modems dominate Tier-1 qualification pipelines. Distribution runs through OEM platform engineering centers in Munich and Stuttgart for original equipment fitment, alongside direct fleet procurement channels for commercial vehicle retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive communication technology incumbents face sustained substitution pressure from software-defined radio architectures that collapse discrete hardware boundaries, requiring defensive repositioning around embedded cybersecurity certification and silicon supply security.
For Market Incumbents: Harden platform stickiness through captive supply of hardware security modules and cryptographic key management IP, defending against modular software-radio substitutes that displace dedicated chipset procurement. Deepen backward integration into gallium nitride substrate sourcing to offset cost compression in economy-tier antenna arrays. Prioritize EU Cyber Resilience Act pre-certification pipelines to capture specification authority before compliance deadlines filter market access.
For New Entrants and Emerging Players: Build out edge-cloud convergence service layers for municipal infrastructure operators in India's national highway expansion corridors, where greenfield roadside unit deployment lacks incumbent maintenance obligations. Target fleet operator procurement channels in Germany's long-haul trucking sector with guaranteed latency SLAs that displace OEM standard configurations. Pursue system-level packaging partnerships with Tier-1 integrators rather than discrete component qualification routes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor specialists with functional safety certification heritage over consumer-electronics modem designers exposed to automotive qualification timeline compression. Long-term viability rests on embedded cybersecurity engineering depth and multi-standard interoperability patent portfolios. Monitor cellular V2X spectrum allocation decisions by the FCC and ETSI as inflection indicators for roadside unit deployment velocity and stranded DSRC asset exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Qualcomm's Snapdragon Digital Chassis collapses discrete domain boundaries into unified network backbones. |
| Geographic Manufacturing Footprint | Continental AG locates R&D proximate to Stuttgart and Munich engineering centers to capture specification authority. |
| Platform Standardization | NXP Semiconductors' dedicated short-range communications chipsets achieve IEEE 802.11p interoperability across regional certification regimes. |
| Charging Infrastructure Partnership | EU Green Deal carbon mandates make communication modules mandatory for electric vehicle grid integration compliance. |
| Battery Supply Agreement | Fleet operators specify connectivity performance metrics independently of OEM platforms for predictive routing documentation. |
Methodological Framework
The analysis maps cellular V2X modem tiers, DSRC legacy infrastructure maintenance obligations, and edge-cloud convergence service layers, each validated through Tier-1 supplier procurement directors, OEM platform engineers, fleet operator connectivity specification leads, and municipal infrastructure planning officers. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, FCC spectrum allocation filings, and ETSI interoperability certification records. Bottom-up component shipment analysis and top-down fleet procurement survey data reconcile volume estimates across the projection horizon.
Assumption sets held regulatory certification timelines and spectrum allocation decisions fixed while varying fleet operator penetration rates and gallium nitride substrate cost trajectories. The analytical framework segments by technology protocol, component category, end-user procurement authority, and application maturity stage. CAGRs derive from installed base replacement cycles for DSRC infrastructure and greenfield deployment velocity for cellular V2X roadside units. Modeled inputs include 3GPP release adoption curves and EU Cyber Resilience Act compliance cost pass-through coefficients.
Stress conditions across FCC 5.9 GHz reconfiguration timelines, MIIT GB standard localization requirements, and embedded cybersecurity engineering talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that regional certification fragmentation or single-source silicon supply disruptions could revise trajectory. Quarterly review of roadside unit deployment permits, fleet operator connectivity SLA specifications, and 3GPP standardization committee outputs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Control Cable Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Automotive AR Head-Up Display Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
India Automotive Lighting Market
Automotive Electronics & Wiring
Off-Road Machine High-Durability Wiring Harness Systems Market
Automotive Electronics & Wiring
Australia Automotive Camera Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Automotive Wireless Module Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Automotive Glow Plug Market