
 Automotive Auxiliary Lamps Market | 2026-2036
Automotive Auxiliary Lamps Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Auxiliary Lamps Market Intelligence
The European Union's Green Deal, with its focus on vehicle energy efficiency, is realigning the design priorities for auxiliary lighting systems. HELLA GmbH & Co. KGaA leverages its specialization in advanced LED and laser technologies to meet these new efficiency standards. Valeo S.A. competes on system integration, offering complete lighting modules for passenger and commercial vehicles. Robert Bosch GmbH anchors its market position through its extensive distribution network in the automotive aftermarket across Europe and North America.
Automotive auxiliary lamps are supplemental lighting devices installed on vehicles to enhance visibility beyond standard headlights. These systems, including fog lamps and driving lamps, are engineered to project specific beam patterns, such as a wide, low-set beam to cut through fog. LED technology now dominates new installations, displacing older halogen and xenon systems due to superior longevity and efficiency. Demand for off-road lamps represents the fastest-growing product type, driven by recreational and professional use in markets like the United States and Australia.
Regulations such as the US Federal Motor Vehicle Safety Standards (FMVSS) and Europe's UN/ECE regulations dictate permissible brightness, color, and mounting locations for auxiliary lights. In China, GB standards for automotive lighting ensure compliance for both domestic and imported vehicles, shaping market access for all suppliers. Component suppliers must now decide whether to focus on high-volume standard LED units or invest in specialized, higher-margin laser and OLED lighting technologies for premium segments.
Market Dynamics
The central structural force shaping the automotive auxiliary lamps market is the technological substitution of legacy halogen and xenon systems with solid-state LED lighting, a shift that redefines product lifecycles, energy efficiency, and design possibilities.
Growth Catalysts
- Regulatory Mandates:Frameworks like the European Union's Green Deal incentivize vehicle energy efficiency, directly promoting the adoption of low-power LED auxiliary lamps over less efficient halogen alternatives to meet overall vehicle emissions targets.
- Off-Road Vehicle Demand:The expanding recreational and professional use of off-road vehicles, particularly in the United States and Australia, drives substantial demand for high-performance, durable driving lamps and light bars for enhanced visibility in rugged environments.
- LED Cost-Performance Ratio:Continuous improvements in the luminous efficacy and manufacturing cost of high-power LED chips are making advanced lighting performance accessible in mainstream vehicle segments, moving beyond an exclusive focus on the premium market.
Market Restraints
- Higher Initial Cost:The upfront cost for advanced LED, laser, or OLED auxiliary lighting systems remains significantly higher than for traditional halogen units, limiting adoption in the price-sensitive economy vehicle sector and some aftermarket replacement segments.
- Regulatory Fragmentation:Divergent standards, including FMVSS in the United States, UN/ECE regulations in Europe, and GB standards in China, create compliance complexity and increase development costs for suppliers aiming for a global product portfolio.
- Thermal Management Complexity:High-output LED systems generate significant heat that must be effectively dissipated to maintain performance and longevity, posing a persistent engineering constraint that adds cost and complexity to lamp design and integration.
Strategic Opportunities
- Smart and Adaptive Lighting:Development of adaptive auxiliary lighting systems, which adjust beam patterns in real-time based on weather, speed, and steering angle, presents a high-margin opportunity within the premium and electric vehicle segments.
- Commercial Vehicle Retrofits:The large, aging global fleet of commercial trucks using halogen lamps offers a substantial opportunity for aftermarket suppliers to provide LED retrofit kits that offer improved durability, safety, and lower long-term operating costs.
- E-commerce Channel Growth:The rise of specialized e-commerce platforms and direct-to-consumer brands for automotive parts creates a new channel to reach enthusiasts in the off-road and light truck customization markets, bypassing traditional distribution layers.
Industry Challenges
- System Integration Complexity:Integrating advanced auxiliary lamps with modern vehicle electronics, including ADAS sensors and complex body control modules, requires deep software and network communication expertise, creating a barrier for component-focused suppliers.
- Counterfeit Products:The proliferation of non-compliant and low-quality counterfeit LED lamps in online marketplaces erodes brand value for legitimate manufacturers, poses safety risks, and creates downward price pressure in the aftermarket.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Auxiliary Lamps Market |
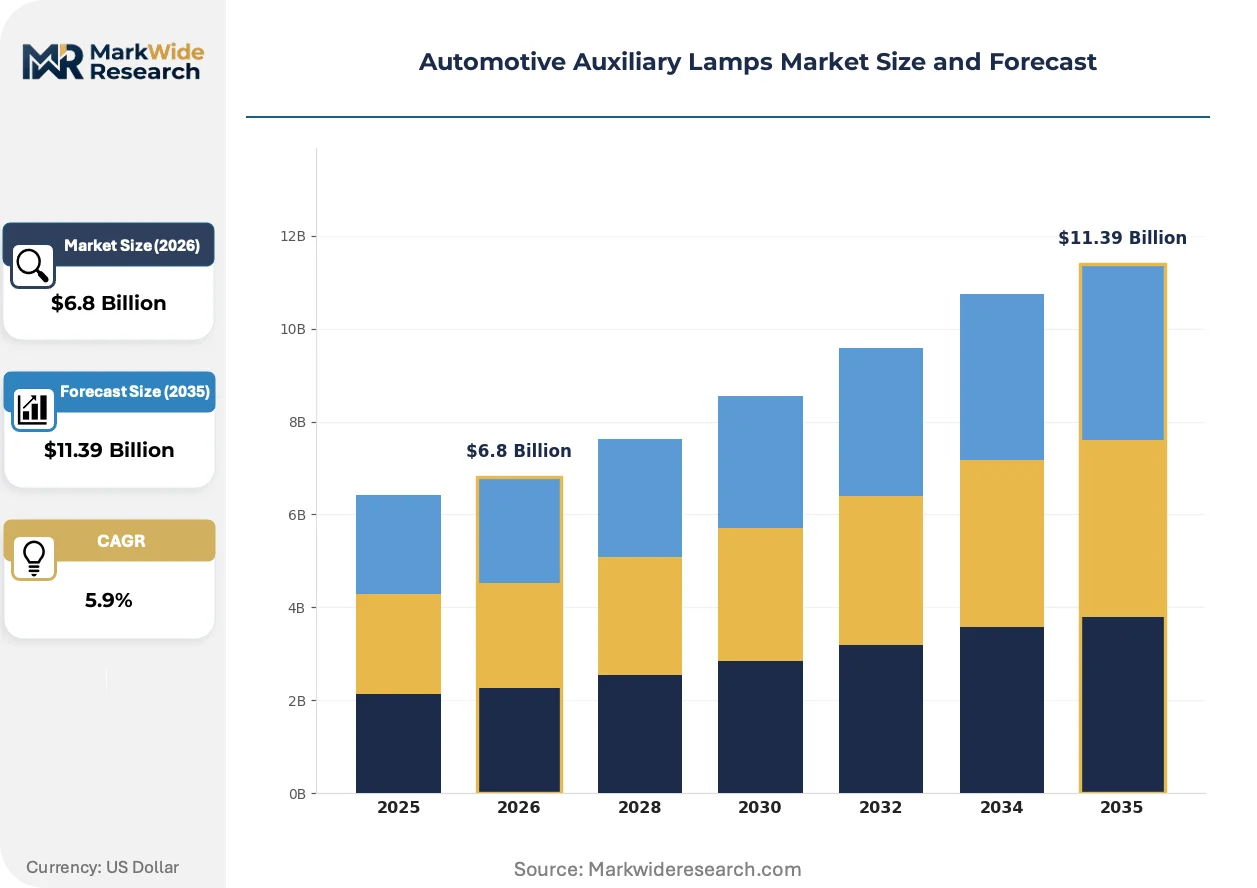
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fog Lamps, Driving Lamps, Cornering Lamps, Daytime Running Lamps, Off-Road Lamps Technology: Halogen, LED, Xenon, Laser, OLED Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Off-Road Vehicles, Agricultural Machinery End User: Vehicle Assemblers, Tier-1 Suppliers, Dealerships, Aftermarket Providers, Fleet Operators |
| Companies Covered | Continental AG, HELLA GmbH & Co. KGaA, Valeo S.A., Koito Manufacturing Co. Ltd, Stanley Electric Co. Ltd, Robert Bosch GmbH, Denso Corporation, Hyundai Mobis, Magneti Marelli S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Auxiliary Lamps Market Strategic Shifts & Innovations
Intelligent lighting systems are transforming auxiliary lamps from static components into dynamic, responsive systems. The market is pivoting towards lamps that integrate with vehicle sensors to actively enhance driver perception and safety in varied conditions.
Advanced adaptive driving beam (ADB) technology utilizes a matrix of individually controllable LEDs to shape the light pattern in real time. Adoption of ADB is accelerating in premium passenger cars from European and Asian automakers. This functionality is expanding into the auxiliary lamp category, enabling smart fog lamps that can alter their beam width and driving lamps that selectively block light to avoid dazzling oncoming drivers.
European and US regulations are converging to allow more sophisticated lighting technologies. The US NHTSA's recent update to FMVSS 108, for instance, now permits the sale of vehicles with adaptive driving beam systems. This change eliminates a major barrier for automakers wanting to offer unified global lighting platforms. The primary impact is on the premium vehicle segment, where these advanced systems are a key feature differentiator.
Aftermarket demand patterns are shifting toward aesthetic personalization, especially for light trucks and SUVs. Consumers are increasingly selecting auxiliary lamps based on housing design, unique form factors like light bars, and even selectable color temperatures or accent lighting. This trend favors agile, direct-to-consumer brands that can quickly respond to new styles, challenging the dominance of traditional parts distributors. This behavior is most visible in the North American aftermarket customization community.
Automotive Auxiliary Lamps Market Segmentation
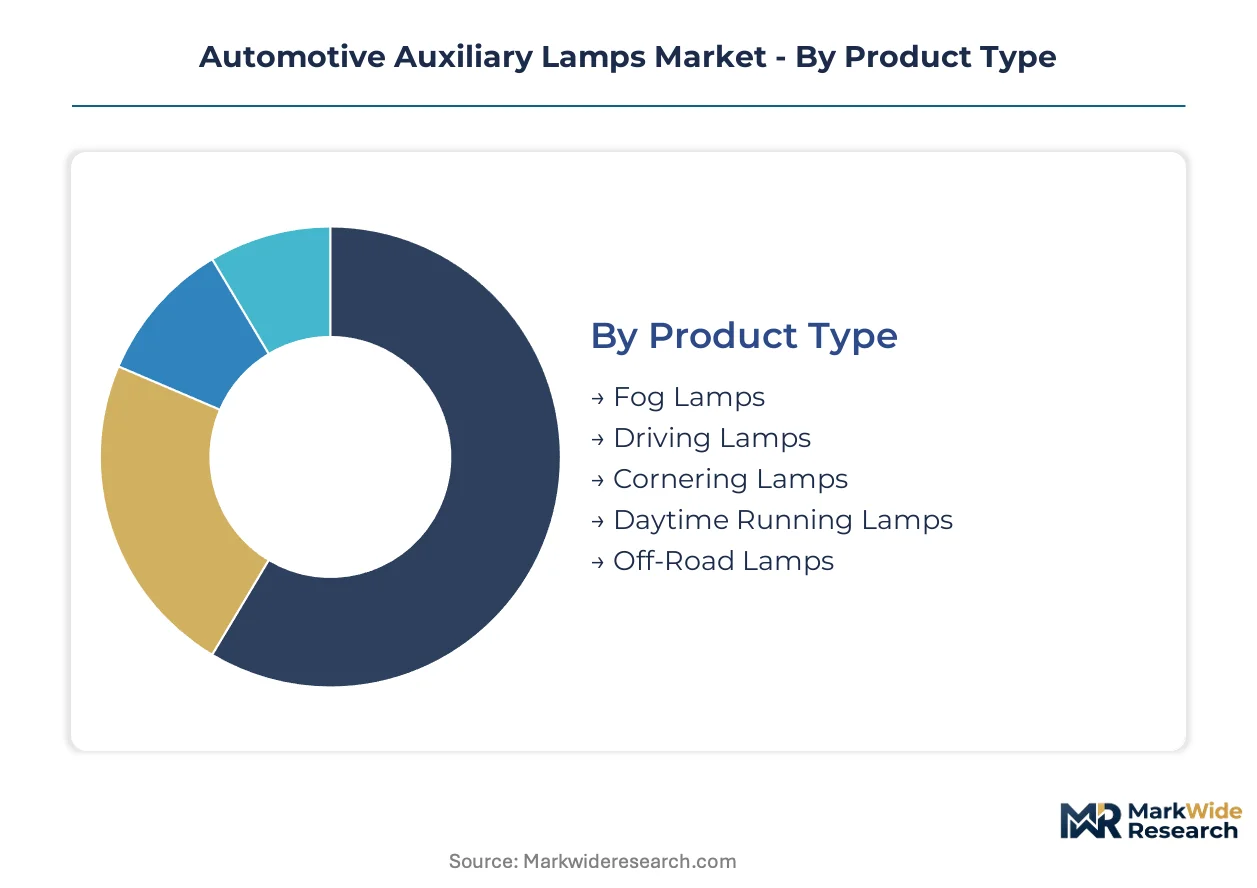
The Automotive Auxiliary Lamps market segments based on distinct product types, underlying technologies, vehicle applications, and diverse end-user requirements. Understanding these divisions reveals where specific demand originates and how technological advancements are reshaping market dynamics. This segmentation provides clarity on the varying needs across the automotive ecosystem for supplemental lighting solutions.
Product Type:
Buyers prioritize specific beam patterns and durability when selecting auxiliary lamps for diverse operational needs.
- Off-Road Lamps:These robust lighting units are designed for extreme conditions, offering high-intensity, wide-angle illumination for enhanced visibility in rugged terrain. Demand from recreational and professional use in markets like the United States and Australia drives this segment.
- Driving Lamps:Engineered to provide powerful, long-range illumination beyond standard high beams, driving lamps improve visibility on highways and rural roads. Commercial truck fleets and long-haul transport operators often equip these for extended night driving.
- Fog Lamps:These lamps project a wide, low-set beam specifically designed to cut through fog, rain, or snow without reflecting glare back to the driver. Many passenger vehicles include fog lamps as standard or optional equipment for safety.
- Daytime Running Lamps:Designed to make vehicles more visible to other road users during daylight hours, these lamps operate automatically when the engine is running. Regulatory mandates in Europe and North America have spurred their widespread adoption.
- Cornering Lamps:These specialized lamps illuminate the side of the road in the direction the vehicle is turning, enhancing visibility during maneuvers at intersections or on winding roads. Premium passenger vehicles frequently incorporate cornering lamps for advanced safety.
Volume sits with Fog Lamps; growth tilts toward Off-Road Lamps.
Technology:
The choice of lighting technology often reflects a balance between initial investment and long-term operational efficiency.
- LED:Light-Emitting Diode technology offers superior energy efficiency, extended lifespan, and compact design flexibility, making it the dominant choice for new installations. This technology is replacing older systems due to its performance benefits and declining manufacturing costs.
- Halogen:These traditional lamps utilize a tungsten filament within a halogen gas-filled bulb, offering a low initial cost and simple replacement. The aftermarket segment, particularly for older vehicles, still relies on halogen units for cost-effective solutions.
- Xenon:High-Intensity Discharge (HID) lamps, commonly known as Xenon, produce a brighter, whiter light than halogen, improving nighttime visibility. These lamps found a niche in mid-range and luxury vehicles before the widespread adoption of LED technology.
- Laser:Representing the cutting edge of automotive lighting, laser technology offers extremely powerful and precise light beams, enabling ultra-long-range illumination. This technology is currently reserved for ultra-premium vehicle segments due to its high cost and complexity.
- OLED:Organic Light-Emitting Diode technology provides uniform, flexible light panels, allowing for innovative design aesthetics and unique lighting signatures. OLED is emerging in premium vehicle segments for accent lighting and rear lamp designs.
Market penetration is highest with LED technology; innovation concentrates in Laser and OLED.
Application:
Different vehicle applications dictate distinct requirements for auxiliary lighting systems, influencing design and performance specifications.
- Commercial Trucks:These heavy-duty vehicles require robust and powerful auxiliary lamps for enhanced visibility during long-haul operations and in challenging weather conditions. China's large commercial truck manufacturing base is a significant demand center for these systems.
- Off-Road Vehicles:Designed for demanding environments, auxiliary lamps for off-road vehicles must withstand harsh impacts, water, and vibration while providing intense illumination. The US aftermarket for light trucks and SUVs significantly drives this application segment.
- Passenger Vehicles:This segment encompasses a broad range of cars and SUVs, where auxiliary lamps contribute to both safety and aesthetic appeal. The integration of advanced LED systems is becoming standard across various passenger vehicle categories.
- Agricultural Machinery:Tractors, harvesters, and other farm equipment utilize auxiliary lamps for visibility during early morning, late evening, or nighttime operations in fields. Durability and wide-area illumination are critical for these applications.
- Two-Wheelers:Motorcycles and scooters use auxiliary lamps to improve rider visibility to other road users and enhance illumination on dark roads. Compact design and low power consumption are important considerations for two-wheeler applications.
Passenger Vehicles represent the largest installed base; Off-Road Vehicles are expanding most quickly.
End User:
End-user segments exhibit varied purchasing behaviors and distribution channel preferences for automotive auxiliary lamps.
- Vehicle Assemblers:Original Equipment Manufacturers (OEMs) integrate auxiliary lamps directly into new vehicles during the production process, demanding high volumes and strict compliance with global regulations. HELLA GmbH & Co. KGaA and Valeo S.A. are key suppliers to this segment.
- Aftermarket Providers:This segment includes retailers and distributors supplying auxiliary lamps for replacement, upgrade, or customization after a vehicle is sold. E-commerce platforms and specialized automotive stores serve this growing market, particularly in North America.
- Tier-1 Suppliers:These companies design and manufacture complete lighting modules and systems, supplying them directly to vehicle assemblers for integration. Robert Bosch GmbH provides comprehensive lighting solutions to various OEMs.
- Dealerships:Authorized vehicle dealerships offer auxiliary lamp installations and replacements as part of their service and accessories offerings. They cater to vehicle owners seeking manufacturer-approved components and installation services.
- Fleet Operators:Companies managing large fleets of commercial vehicles or rental cars procure auxiliary lamps for maintenance, upgrades, and to ensure operational safety. Durability and long-term cost-effectiveness are primary concerns for fleet operators.
Procurement volume is highest from Vehicle Assemblers; specialized demand originates from Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta region, a major automotive manufacturing hub, significantly influences the global auxiliary lamps market through its vast production capacity. This region concentrates vehicle assembler demand and aftermarket supply chains. Concurrently, the United States drives innovation in aftermarket customization and off-road vehicle lighting.
United States
Demand for high-performance auxiliary lamps in the United States stems from the expanding off-road vehicle market and light truck customization. US Federal Motor Vehicle Safety Standards (FMVSS) dictate performance and installation requirements for these lighting systems. The aftermarket customization community, particularly in states like California and Texas, drives significant sales of specialized light bars and driving lamps.
China
China's extensive commercial truck manufacturing base fuels substantial demand for robust auxiliary lighting systems. The country's GB standards for automotive lighting ensure product compliance for both domestic and international suppliers. Major automotive production clusters, including the Yangtze River Delta and Pearl River Delta regions, serve as key centers for OEM procurement and local manufacturing.
Germany
Germany's automotive industry, focused on premium and energy-efficient vehicles, drives demand for advanced LED and laser auxiliary lighting. The European Union's Green Deal and UN/ECE regulations influence design priorities for vehicle energy efficiency. Automotive research and development centers in Stuttgart and Munich lead advancements in smart and adaptive lighting technologies.
Australia
The Australian market exhibits strong demand for durable off-road lamps due to the country's rugged terrain and recreational vehicle culture. Australian Design Rules (ADRs) govern the technical specifications and installation of vehicle lighting. Mining operations in Western Australia and Queensland also contribute to the need for high-intensity, reliable auxiliary lights.
Japan
Japan's mature automotive industry requires high-quality auxiliary lamps for both new vehicle installations and aftermarket replacements. The country's Road Transport Vehicle Act (RTVAct) and JIS standards ensure strict compliance for lighting components. Major automotive manufacturing prefectures like Aichi are central to the development and integration of advanced lighting systems.
Automotive Auxiliary Lamps Market Key Industry Players
The competitive structure tilts toward a tiered market, where large, integrated suppliers dominate the OEM segment, while specialized companies cater to the aftermarket. This market features a mix of established automotive electronics giants and agile niche players. Strategic archetypes include comprehensive system integrators, technology-focused innovators, and cost-effective volume producers. Dominant competitive moves involve portfolio diversification into advanced lighting technologies and geographic expansion into high-growth vehicle markets.
Integrated module suppliers, such as Germany-based HELLA GmbH & Co. KGaA and France-based Valeo S.A., occupy a position supplying complete lighting systems to vehicle assemblers. Robert Bosch GmbH, a Germany-headquartered automotive electronics specialist, exemplifies a broad market presence through its extensive distribution network in the aftermarket. These companies anchor the market with their engineering capabilities and global reach, setting benchmarks for quality and technological integration within the auxiliary lamps sector.
| Leading Market Players |
|---|
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Valeo S.A. |
| Koito Manufacturing Co. Ltd |
| Stanley Electric Co. Ltd |
| Robert Bosch GmbH |
| Denso Corporation |
| Hyundai Mobis |
| Magneti Marelli S.p.A. |
| Others |
Cost & Logistics Intelligence
China's skilled manufacturing workforce, concentrated in automotive hubs, creates labor-cost differentials that influence pricing spreads across auxiliary lamp tiers. This dynamic shapes how suppliers position their products, balancing cost-effectiveness for mass-market segments with premium offerings.
Pricing Analysis
Enhanced visibility and safety anchor the value-based pricing for automotive auxiliary lamps. The market largely operates on a tiered pricing structure across premium, standard, and economy levels, reflecting technology and performance. Quality grade, such as LED versus halogen, and brand premium are significant price differentiation drivers. Pricing pressure stems from the proliferation of counterfeit products in the aftermarket, driving legitimate manufacturers to emphasize durability. The economy vehicle sector and some aftermarket replacement segments exhibit the highest price sensitivity.
Supply Chain Analysis
Dual-sourcing requirements often mandate multi-supplier qualification for critical components, influencing the automotive auxiliary lamps supply chain. Geographic supply concentration for LED chips primarily stems from China, with optical components also sourced from Japan and Germany. Raw material dependencies include specialized semiconductors for LEDs, optical-grade plastics for lenses, and thermal management alloys. Regulatory fragmentation, with divergent standards like FMVSS and UN/ECE, presents a structural supply chain risk, increasing compliance costs. OEM direct supply and aftermarket e-commerce platforms represent the dominant distribution models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive auxiliary lamps market is a supply-constrained story, with specialized LED and laser component manufacturing capacity bottlenecks propping pricing for advanced systems.
For Market Incumbents: Deepen investments in advanced LED and laser R&D to maintain technological leadership against agile niche players. Strengthen OEM integration partnerships to secure long-term contracts for adaptive lighting systems. Focus on intellectual property protection to counter the threat posed by counterfeit products in the aftermarket. Expand global manufacturing footprints to mitigate regional supply chain risks and optimize production costs.
For New Entrants and Emerging Players: Specialized e-commerce platforms offer a direct channel to reach enthusiasts in the North American aftermarket customization community. Target the rapidly expanding off-road vehicle segment with innovative light bar designs and user-friendly retrofit kits. Penetrate the commercial vehicle retrofit market by offering LED solutions that promise lower long-term operating costs and improved durability. Focus on rapid product iteration and aesthetic personalization to capture market share.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-focused innovators given the accelerating adoption of smart and adaptive lighting systems. Focus on firms with strong intellectual property in real-time beam shaping technologies or robust direct-to-consumer distribution channels. Long-term viability is driven by safety mandates, energy efficiency, and vehicle personalization trends globally. The signal to watch is the increasing integration of adaptive driving beam systems into mainstream vehicle segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Laser and OLED R&D | Develop next-generation lighting solutions, differentiating offerings for premium vehicle segments. |
| Expand Aftermarket Retrofit Kits | Capture demand from the large installed base of commercial trucks seeking LED upgrades. |
| Strengthen E-commerce Channel Capabilities | Directly reach customization enthusiasts in the North American light truck market. |
| Develop Adaptive Lighting Software | Integrate auxiliary lamps with ADAS sensors for enhanced safety and driver perception. |
| Obtain Global Regulatory Certifications | Ensure market access and compliance across diverse regions like Europe, US, and China. |
Research Approach
Multi-period observation of technology adoption rates and regulatory compliance trends anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with OEM procurement managers, Tier-1 R&D leads, aftermarket distributors, and off-road vehicle modifiers. Secondary validation drew from UN/ECE regulations, US FMVSS standards, China's GB standards, and global automotive production databases. This approach enabled comprehensive bottom-up and top-down triangulation.
Segment-weighting across product type (off-road, fog lamps), technology (LED, Laser), application (commercial trucks, passenger vehicles), end-user (OEMs, aftermarket), and regional regulatory mandates informed the quantitative modeling over the projection horizon. CAGRs were derived from historical data and projected adoption curves for advanced lighting technologies. Industry-specific forecast inputs included vehicle electrification rates, off-road vehicle sales volumes, and anticipated regulatory updates.
Caveats apply where rapid technological obsolescence or unforeseen regulatory shifts could materially shift the outlook for auxiliary lamps. Forecasts reflect assumptions regarding market dynamics and innovation trajectories. Deviation in vehicle electrification rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Steering Roll Connector Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Human Interface System Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Automotive Cockpit Soc Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
On Board Connectivity Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Voice Recognition System Market
Automotive Electronics & Wiring
Mexico Automotive Camera Market
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Remote Car Starter Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Digital Tachograph System Market