
 Global Food Fiber Market | 2026-2036
Global Food Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Fiber Market Analysis
Functional beverage formulators is rotating share away from conventional bakery buyers as the fastest-growing demand archetype in food fiber procurement. Cargill, Incorporated leverages its North American grain processing infrastructure to anchor supply contracts for soluble fiber isolates. Tate & Lyle competes through specialty starch and fiber hybrid formulations targeted at reduced-sugar applications. BENEO GmbH differentiates via chicory root-derived inulin expertise cultivated across European manufacturing sites.
Food fiber encompasses non-digestible carbohydrate polymers—typically ranging from 3 to 20 degrees of polymerization—that resist hydrolysis by human digestive enzymes and confer physiological benefits including fecal bulking and fermentable substrate provision to colonic microbiota. Soluble fiber commands premium positioning in functional beverage and nutraceutical channels where viscosity modification and prebiotic claims justify higher formulation costs, while insoluble fiber maintains volume dominance in bakery and whole-grain applications where structural integrity and cost efficiency predominate. Functional fiber isolates represent the fastest-expanding margin pool as ingredient suppliers invest in clinical substantiation for specific health outcome claims.
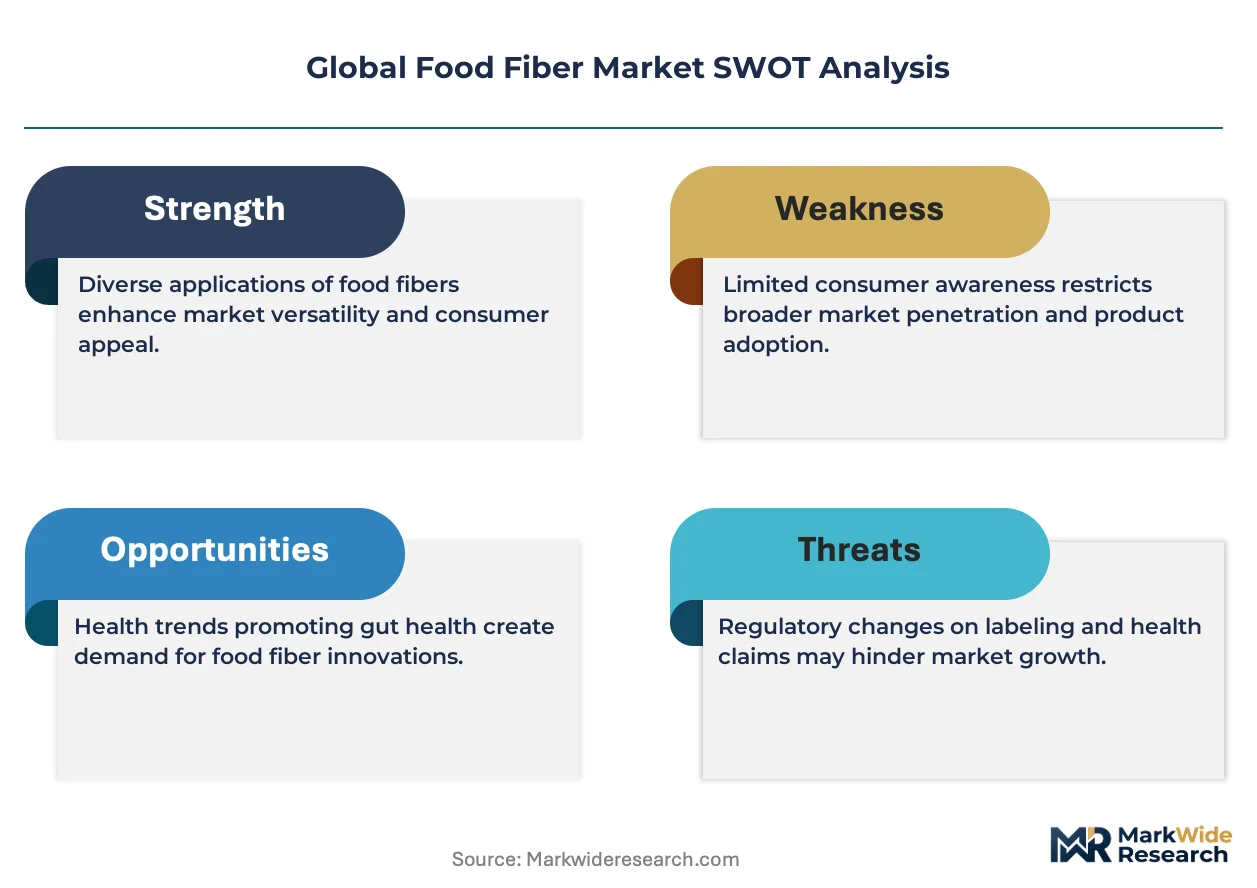
The FDA's updated nutrition facts panel and dietary fiber definition criteria reshape which isolated fibers qualify for label declarations in US-formulated products, while EFSA's health claim authorization process governs permissible prebiotic and digestive health communications across European markets. China's SAMR and national food safety standards increasingly scrutinize imported fiber concentrates for contaminant thresholds and origin documentation. Stakeholders must monitor evolving regulator positions on novel fiber sources—including upcycled agricultural byproducts—and preemptively secure clinical validation packages before petitioning for approved-use status in major jurisdictions.
Market Dynamics
Clean-label reformulation mandates across major food jurisdictions are forcing ingredient suppliers to revalidate fiber sourcing documentation and substantiate health claims through clinical trials, compressing product development timelines and raising qualification barriers for new market entrants.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration-dependent bakery chains accelerate shelf-stable fiber-fortified product development to reduce cold-chain dependency, expanding demand for heat-stable soluble fiber isolates.
- Functional beverage formulators:Prebiotic positioning in ready-to-drink wellness products drives procurement of clinically validated inulin and resistant starch variants at premium formulation rates.
- Germany:Clean-label bakery innovation clusters in Munich and Hamburg concentrate soluble fiber procurement from specialized European suppliers with integrated chicory root processing capabilities.
Market Restraints
- Chicory root supply concentration:Northern European agricultural zones dominate inulin raw material production, exposing formulators to weather-driven harvest volatility and single-origin dependency risks.
- FDA dietary fiber definition:Isolated and synthetic fibers face uncertain qualification status for nutrition label declarations, forcing costly petition processes for novel fiber sources.
- Whole-food substitution:Consumer preference for intact grain and vegetable fiber sources limits penetration of refined fiber isolates in certain premium positioning strategies.
Strategic Opportunities
- Upcycled agricultural byproducts:Citrus peel, oat hull, and apple pomace fiber extraction technologies unlock valorization pathways for food processing waste streams with circular economy credentials.
- China SAMR pathway:Pre-emptive clinical validation packages for imported fiber concentrates position suppliers ahead of tightening national food safety standard enforcement on origin documentation.
- Reduced-sugar hybrid formulations:Specialty starch and fiber combinations enable texture restoration in sugar-reduced bakery applications, capturing reformulation budgets from health-conscious manufacturers.
Industry Challenges
- Clinical substantiation timelines:EFSA health claim authorization processes demand multi-year human intervention studies, delaying market entry for novel prebiotic positioning strategies.
- Cross-jurisdictional compliance:Divergent FDA, EFSA, and SAMR fiber definition criteria force suppliers to maintain parallel specification sheets and analytical method libraries.
- Microbiome personalization complexity:Variable individual fermentability responses complicate universal prebiotic marketing claims and require sophisticated consumer segmentation approaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Fiber Market |
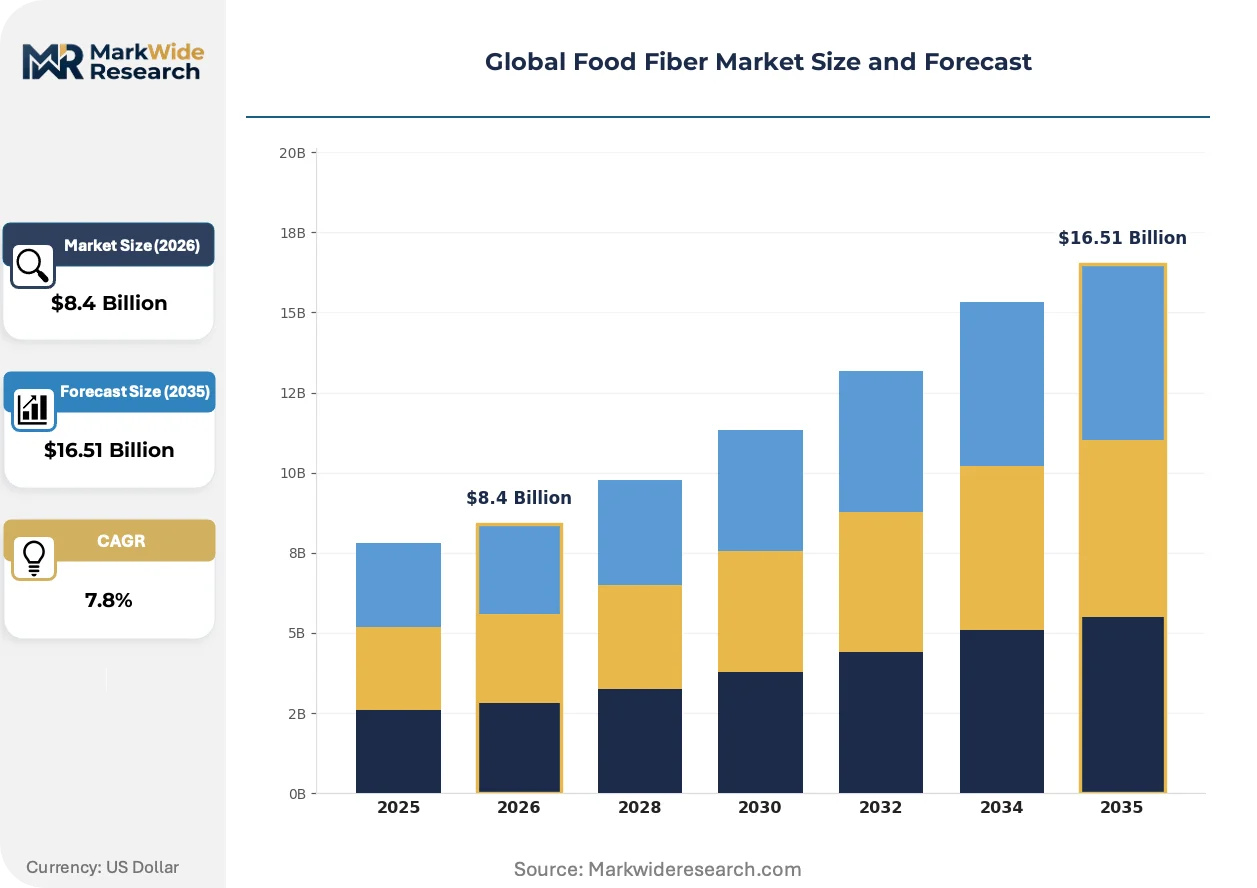
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insoluble Fiber, Soluble Fiber, Functional Fiber, Whole Food Fiber Application: Food & Beverage, Dietary Supplements, Nutraceuticals, Bakery Products Form: Powder, Granules, Tablets, Capsules Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Ingredion Incorporated, Tate & Lyle, Roquette Frères, BENEO GmbH, DuPont, Lonza, Nexira, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Fiber Market Emerging Trajectories
Precision fermentation and enzymatic modification techniques are reshaping how fiber isolates achieve specific viscosity profiles and fermentability rates, enabling tailored solutions for targeted physiological outcomes rather than generic bulking functions.
Enzymatically modified resistant starches are displacing conventional chemically processed variants in premium bakery applications. European clean-label manufacturers adopt these ingredients at accelerated rates to meet retailer sustainability scorecards. The shift is compressing margins for legacy acid-thinned starch suppliers while rewarding biotechnology-enabled fiber producers with contract premiums.
EFSA's evolving health claim authorization framework is tightening evidentiary standards for prebiotic and digestive wellness communications. Supplement and functional food manufacturers must now submit strain-specific microbiome studies rather than generic fermentability data. German and French formulators face the steepest compliance ramps given their reliance on gut-health positioning in mature markets.
Direct procurement relationships between fiber isolate suppliers and mid-sized functional beverage brands are fragmenting traditional distributor channels. These brands bypass ingredient trading houses to secure exclusive supply agreements and co-development partnerships. The pattern concentrates in North American and Western European metropolitan innovation clusters where startup beverage incubators cluster near university food science departments.
Global Food Fiber Market Segmentation
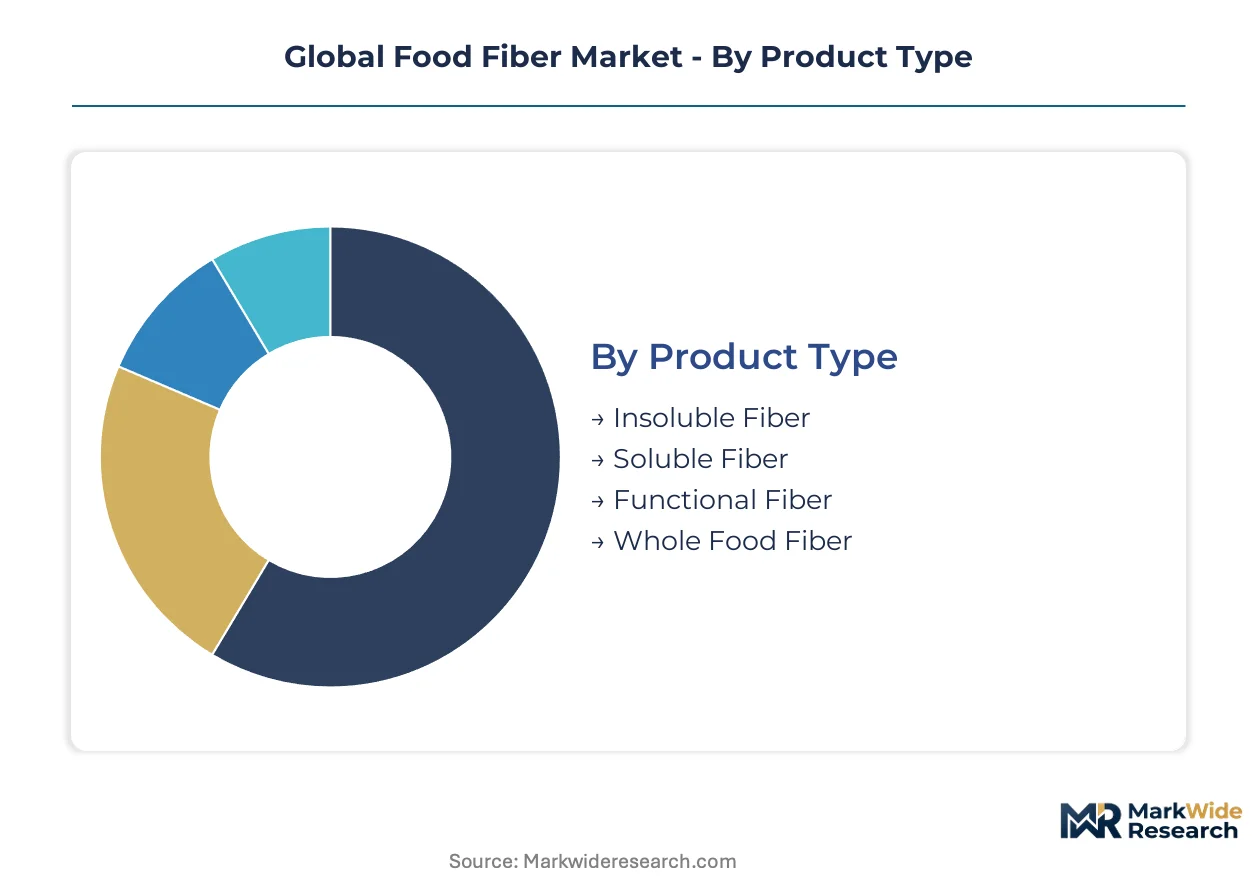
Segmentation in food fiber procurement determines which suppliers capture margin pools. Channel access, formulation requirements, and regulatory qualification status create divergent competitive dynamics across each dimension.
Product Type:
Channel-mix patterns diverge sharply: soluble fiber isolates flow predominantly through nutraceutical and functional beverage ingredient channels, while insoluble variants dominate bulk bakery supply chains.
- Soluble Fiber:Non-digestible carbohydrate polymers that dissolve in water to form viscous gels, typically inulin, pectin, or beta-glucan structures. Demand concentrates in German clean-label bakery clusters and North American functional beverage formulators where prebiotic positioning commands formulation premiums. EFSA health claim authorization requirements constrain marketing communications.
- Insoluble Fiber:Cellulose, hemicellulose, and lignin matrices that resist water absorption while providing fecal bulking and structural integrity. Whole-grain bakery applications in the US and EU absorb volume, though FDA dietary fiber definition uncertainties complicate label declarations for refined isolates.
- Functional Fiber:Isolated or synthetic non-digestible carbohydrates with demonstrated physiological benefits beyond basic bulking. Clinical substantiation investments separate qualified suppliers from commodity producers.
- Whole Food Fiber:Intact fiber matrices retained within minimally processed grains, fruits, and vegetables. Clean-label positioning in European retail channels limits penetration of refined isolates.
By volume, insoluble fiber leads. By growth pace, functional fiber is ahead.
Application:
Cost-tier stratification separates premium nutraceutical positioning from commodity bakery supply, with dietary supplements occupying the highest formulation spend per kilogram.
- Food & Beverage:The broadest application canvas spanning bakery fortification, beverage viscosity modification, and dairy texturization. Reformulation mandates across US, EU, and Chinese jurisdictions drive procurement of heat-stable and acid-tolerant variants.
- Dietary Supplements:Capsule and tablet formats demanding high-purity isolates with batch-level contaminant documentation. China's SAMR intensifies scrutiny of imported concentrates for heavy metal thresholds and origin traceability.
- Nutraceuticals:Positioning at the intersection of food and pharmaceutical regulatory frameworks. EFSA's evolving evidentiary standards for prebiotic claims compress development timelines.
- Bakery Products:Structural applications where fiber incorporation must balance water-binding capacity with crumb integrity. EU F-Gas Regulation accelerates shelf-stable fiber-fortified product development.
Food and beverage commands absolute tonnage. Dietary supplements generate the steepest value-per-unit expansion.
Form:
Volume concentration favors powder formats in industrial ingredient channels, while consumer-facing tablets and capsules capture retail margin premiums.
- Powder:The dominant industrial format enabling homogeneous dispersion in dry mixes and liquid suspensions. Bulk procurement by bakery and beverage manufacturers concentrates in North American and European processing hubs.
- Granules:Intermediate particle sizes optimized for specific rehydration rates and mouthfeel profiles. Functional beverage formulators specify granule dimensions for controlled dissolution in ready-to-drink applications.
- Tablets:Compressed formats requiring excipient compatibility and disintegration time specifications. Dietary supplement brands specify tablet hardness for packaging durability.
- Capsules:Gelatin or hydroxypropyl methylcellulose shells containing measured fiber doses. Clean-label positioning drives migration toward plant-based capsule materials.
Powder leads in procurement volume. Capsules are climbing the fastest on value growth metrics.
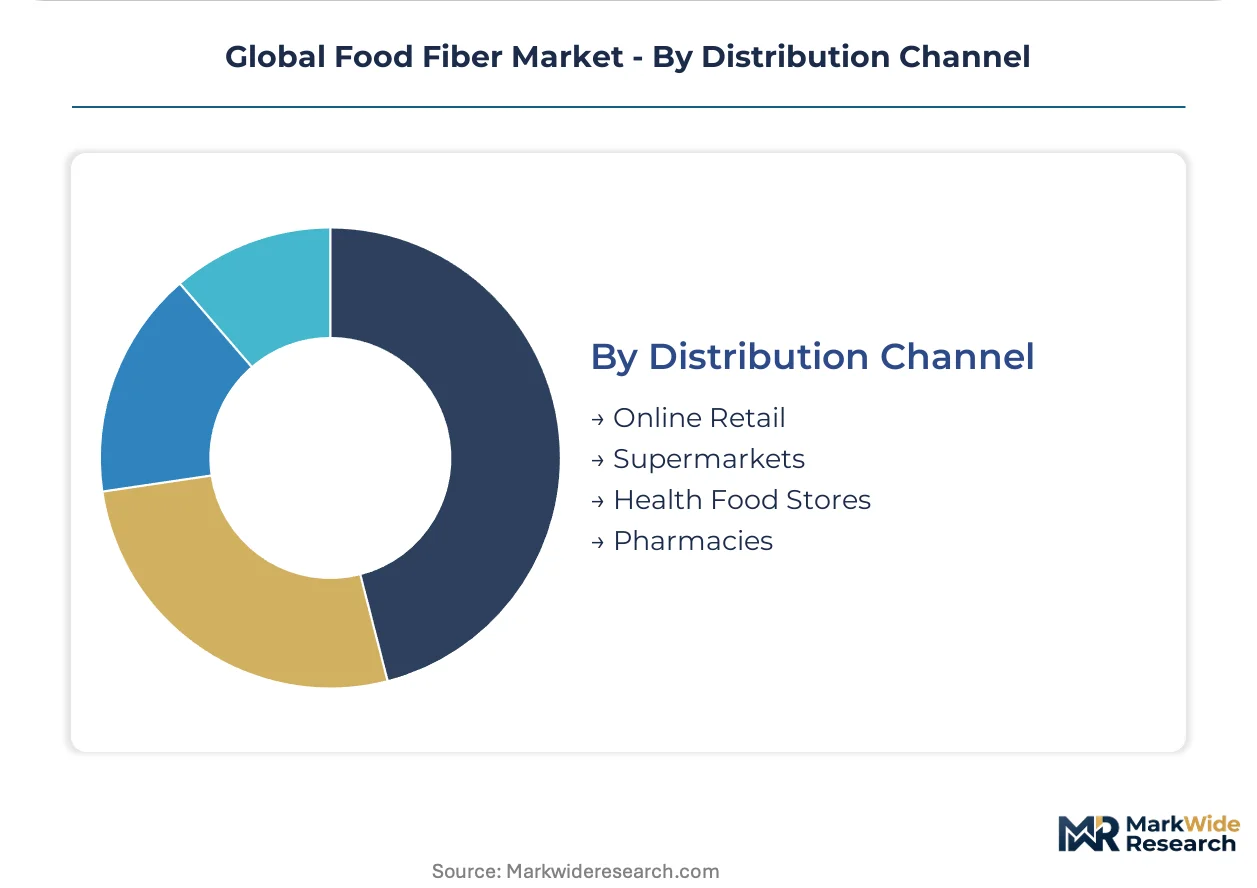
Distribution Channel:
Customer-type fragmentation separates institutional ingredient procurement from direct-to-consumer retail, with online platforms eroding traditional health food store positioning.
- Online Retail:Direct-to-consumer platforms enabling specialty fiber isolate access for small-scale formulators and wellness-focused households. Amazon and specialized nutraceutical marketplaces concentrate traffic.
- Supermarkets:Mass-market retail requiring packaged consumer goods with established brand recognition and shelf-stable formats. Private-label fiber-fortified products expand shelf space allocation.
- Health Food Stores:Specialty retail emphasizing organic certification, non-GMO verification, and transparent sourcing narratives. Staff recommendation influence sustains premium pricing.
- Pharmacies:Healthcare-adjacent positioning with pharmacist endorsement and insurance reimbursement potential in select jurisdictions. Regulatory classification boundaries limit expansion.
Supermarkets dominate absolute volume throughput. Online retail is gaining share fastest among emerging procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian and Dutch chicory root processors export inulin isolates to German bakery manufacturers and North American functional beverage brands, establishing the primary trade-flow corridor for soluble fiber procurement.
United States
FDA dietary fiber definition revisions and nutrition facts panel updates drive reformulation activity among packaged food manufacturers. The agency's petition process for novel fiber sources creates regulatory uncertainty for suppliers seeking label qualification. Chicago and Minneapolis-St. Paul processing hubs concentrate grain-derived fiber extraction capacity serving domestic bakery chains.
Germany
Clean-label bakery innovation in Munich and Hamburg accelerates soluble fiber procurement from specialized European suppliers. The EU F-Gas Regulation pushes refrigerated bakery chains toward shelf-stable fiber-fortified product development. Northern European chicory root supply zones feed integrated inulin processing operations serving domestic formulators.
China
SAMR intensifies scrutiny of imported fiber concentrates for contaminant thresholds and origin documentation requirements. National food safety standards tightening enforcement positions pre-validated suppliers ahead of compliance ramps. Yangtze River Delta food science clusters near Shanghai drive domestic resistant starch and oat fiber processing expansion.
France
EFSA health claim authorization processes govern permissible prebiotic and digestive wellness communications for supplement manufacturers. ANSM oversight of borderline food-drug products creates additional classification complexity for gut-health positioning. Paris and Lyon formulation clusters specialize in clinically substantiated fiber blends for nutraceutical applications.
Brazil
ANVISA regulatory pathways for novel food ingredients including upcycled agricultural fiber sources remain under development. Citrus peel and apple pomace valorization from domestic fruit processing waste streams attracts circular economy investment. São Paulo state food technology institutes pilot enzymatic fiber modification for export-grade isolates.
Global Food Fiber Market Vendor Landscape
Player mix skews toward integrated agribusiness conglomerates with captive raw material sourcing and specialized biotechnology firms with clinical validation capabilities. The vendor base separates into three functional tiers: grain processors leveraging North American infrastructure, European chicory root specialists with integrated cultivation networks, and hybrid ingredient formulators combining starch and fiber technologies. Consolidation pressure concentrates among mid-scale regional suppliers lacking multi-jurisdictional regulatory dossiers. Dominant competitive moves include backward integration into agricultural raw material control and exclusive supply partnerships with functional beverage startups bypassing traditional distribution channels.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland Company represent scale-driven positions anchored by North American grain processing infrastructure. Tate & Lyle and BENEO GmbH exemplify the European specialization vector, with the latter occupying a distinctive position rooted in chicory root-derived expertise. These four entities collectively illustrate the competitive spectrum from commodity-scale supply to premium isolate positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ingredion Incorporated |
| Tate & Lyle |
| Roquette Frères |
| BENEO GmbH |
| DuPont |
| Lonza |
| Nexira |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for chicory root-derived inulin concentrate procurement power in the hands of Belgian and Dutch processors, translating into formulation premiums passed to German bakery manufacturers and North American functional beverage brands. This lead-time band compresses margin flexibility for downstream buyers while rewarding integrated suppliers with captive agricultural sourcing.
Pricing Analysis
Enzymatically-modified resistant starches command formulation premiums over acid-thinned legacy variants, while precision-fermentation isolates sit at the top tier awaiting scale economics. Three-tier pricing structure across premium, standard, and economy levels separates clinically-validated functional fibers with EFSA dossiers from commodity-grade insoluble variants. Pricing pressure stems from whole-food substitution preferences in European clean-label channels. Dietary supplement manufacturers exhibit lowest price sensitivity given capsule-format value concentration, while bulk bakery procurement teams negotiate aggressively on tonnage contracts.
Supply Chain Analysis
Strategic stockpiling of chicory root inventories dominates Northern European processor behavior, contrasting with just-in-time procurement patterns among North American beverage formulators. Supply concentrates in Belgium, the Netherlands, and Germany for inulin extraction, while resistant starch processing anchors in the US and China. Raw material flows depend on chicory root cultivation, grain milling byproducts, and citrus peel waste streams. Single-source vulnerability from Belgian-Dutch chicory concentration exposes formulators to weather-driven harvest volatility. Distribution runs through specialized ingredient trading houses, though direct procurement relationships are fragmenting traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food fiber market is cycling through a regulatory-driven recovery phase as EFSA and FDA definition clarity resets qualification barriers. Reformulation mandates across major jurisdictions create replacement demand that favors validated suppliers.
For Market Incumbents: Consolidate backward integration into chicory root cultivation networks to secure supply continuity against weather volatility. Acquire clinical validation capabilities ahead of EFSA's tightening evidentiary standards for prebiotic claims. Cargill and Tate & Lyle demonstrate how North American grain infrastructure and European specialty processing expertise create defensive moats against commodity erosion.
For New Entrants and Emerging Players: Anchor in upcycled agricultural byproduct extraction—citrus peel, oat hull, and apple pomace fiber technologies—where circular economy credentials unlock premium positioning. Brazil and China present the most penetrable geographies given ANVISA pathway development and SAMR enforcement ramp. Pursue co-development partnerships with mid-sized functional beverage brands bypassing traditional distributor channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated agribusiness conglomerates seeking to divest non-core specialty ingredient divisions. Five-to-ten-year viability hinges on multi-jurisdictional regulatory dossier depth rather than commodity scale. Watch for EFSA health claim authorization rejections as inflection indicators that compress valuations for clinically unsubstantiated positioning strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Sourcing | Captive chicory root supply insulates Belgian-Dutch processors from harvest volatility. |
| Clinical Validation Investment | EFSA dossier completion separates premium isolate suppliers from commodity producers. |
| Direct Procurement Partnerships | Beverage startup alliances fragment traditional ingredient trading house channels. |
| Upcycled Byproduct Extraction | Citrus peel and oat hull valorization unlocks circular economy contract premiums. |
| Multi-Jurisdictional Regulatory Dossiers | Parallel FDA-EFSA-SAMR qualification expands addressable market for validated fibers. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with ingredient procurement managers, food formulators, and regulatory affairs directors at fiber suppliers and downstream manufacturers; and secondary validation through FDA petition filings, EFSA health claim registers, SAMR food safety standard updates, and trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing across soluble, insoluble, functional, and whole-food fiber categories.
Across the analysis window, projections incorporated segmentation by product type, application channel, and geographic regulatory cluster. CAGRs derived from elasticity-adjusted demand curves reflecting reformulation mandate intensity and clean-label penetration rates. Forecast inputs included EFSA authorization timelines, FDA petition approval velocities, and SAMR enforcement escalation patterns.
Material uncertainties—regulatory definition revisions, harvest volatility in Northern European chicory zones, and whole-food substitution acceleration—sit outside the modeled envelope. Forecasts reflect assumptions about clinical substantiation investment continuity and jurisdiction-specific claim permissibility. Revision becomes warranted when EFSA rejects prebiotic health claim petitions at rates exceeding historical baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Automotive Smart Lighting Market
Others
Connected TV Market
Others
Industrial Tablet PC Market
Others
United States Printed Signage Market
Others
Traditional PC Market
Others
North America Smart Homes Market
Others
Aerospace Engineering Services Outsourcing Market
Others
Refractometer Market
Others
Smart Home Solutions Market
Others
Europe Postal Services Market
Others
Gesture Recognition for Smart TV Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Cloud Advertising Market
Others
Industrial Personal Computer Market
Others
Advanced Combat Helmet Market
Others
Latin America Video Conferencing Hardware Market