
 Europe Smart Homes Market | 2026-2036
Europe Smart Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Homes Market Foresight
Premium ENERGY STAR-equivalent certification tiers is reorganizing competitive dynamics across the Europe smart homes sector. Legrand SA leverages its wiring device heritage to dominate integrated control panels for high-efficiency retrofits. Robert Bosch GmbH anchors its position through in-house sensor manufacturing and HVAC-to-smart-home connectivity. Signify N.V. differentiates via proprietary mesh protocols that reduce installation complexity for electrical contractors.
Europe smart homes encompass residential and light-commercial buildings where networked sensors, actuators, and controllers automate environmental, security, and energy functions through interoperable communication protocols. Systems typically integrate temperature setpoints below 0.5°C variance, occupancy detection within 30-second response windows, and encrypted local processing to meet GDPR data-localization requirements. Smart Security and Smart Thermostats command the deepest margin pools due to recurring monitoring subscriptions and utility rebate eligibility. Wi-Fi and Zigbee split connectivity architecture based on installation scale, with Zigbee preferred in multi-device German renovations and Wi-Fi dominant in French single-family retrofits where router density suffices.
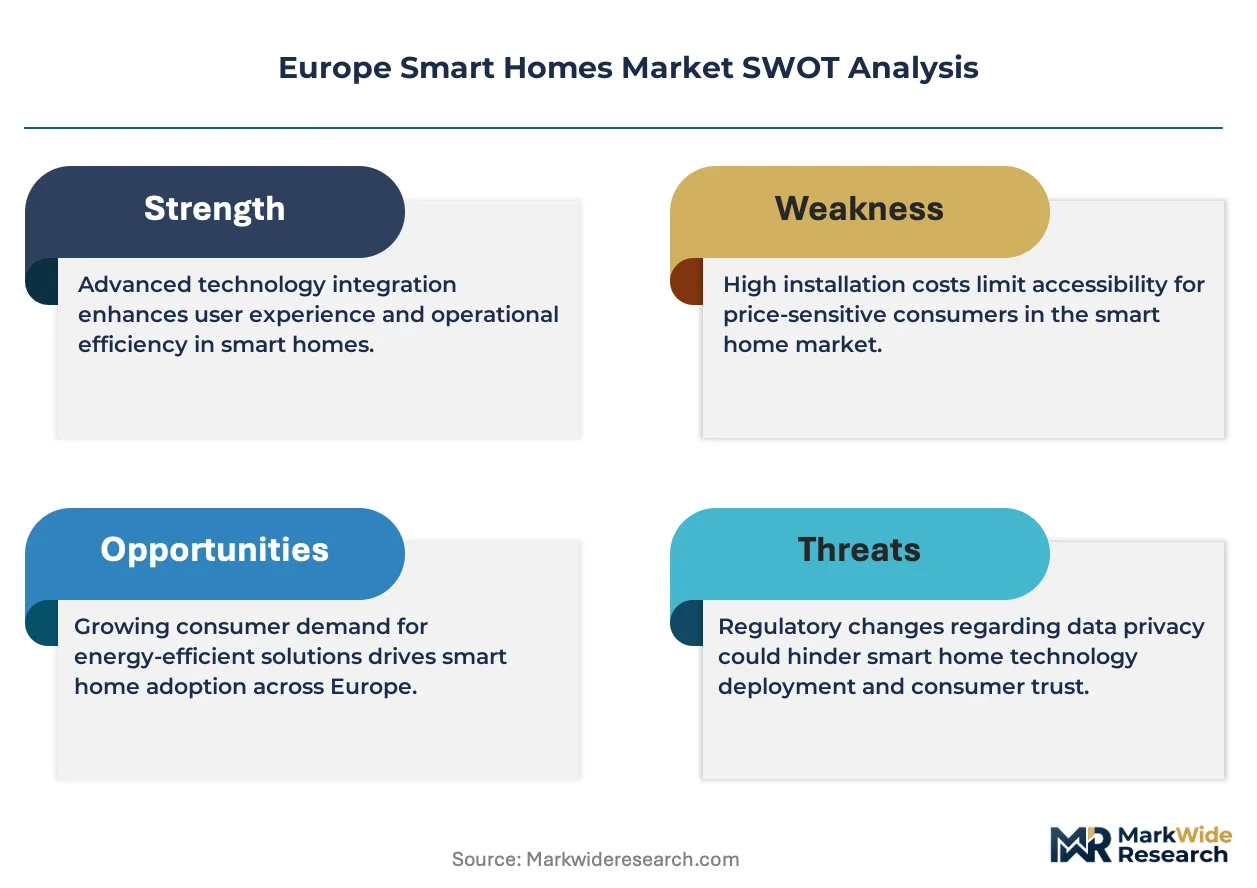
CE marking under the Radio Equipment Directive and Ecodesign for Sustainable Products Regulation mandate interoperable cybersecurity baselines and standby power thresholds below 2.00W for connected devices sold across EU member states. ECHA substance restrictions further limit heavy metals in printed circuit assemblies, pushing suppliers toward halogen-free substrate alternatives. Stakeholders must monitor whether the EU AI Act's risk-classification framework will reclassify predictive energy algorithms as high-risk systems requiring third-party conformity assessment.
Market Dynamics
The EU Green Deal's tightening Ecodesign for Sustainable Products Regulation is forcing a wholesale redesign of device architectures across European smart homes, compressing standby power thresholds and mandating interoperable cybersecurity baselines that favor suppliers with in-house compliance capabilities.
Growth Catalysts
- Residential energy management systems:Homeowners in Germany and France are retrofitting HVAC-to-smart-home connectivity to capture utility rebate eligibility and reduce heating costs through sub-0.5°C temperature variance control.
- GDPR data-localization requirements:Encrypted local processing mandates are accelerating demand for edge-computing controllers that keep occupancy detection and security data within household premises rather than cloud servers.
- Zigbee mesh protocol preference:Electrical contractors across multi-device German renovations favor proprietary mesh installations that reduce wiring complexity and enable 30-second occupancy response windows.
Market Restraints
- CE marking compliance costs:Radio Equipment Directive testing and third-party conformity assessment for cybersecurity baselines add fixed cost burdens that disproportionately squeeze smaller device manufacturers.
- ECHA substance restrictions:Heavy metal limits in printed circuit assemblies are pushing suppliers toward halogen-free substrate alternatives with constrained supply chains and higher material costs.
- Wi-Fi congestion in dense housing:French multi-unit buildings suffer router density saturation that degrades smart thermostat reliability and drives customer service costs for installers.
Strategic Opportunities
- United Kingdom retrofit acceleration:Post-Brexit building efficiency standards are creating concentrated demand for integrated control panels in aging housing stock that lacks modern wiring infrastructure.
- Predictive energy algorithm deployment:The EU AI Act's pending risk-classification framework may create first-mover advantages for vendors who pre-certify machine-learning models as non-high-risk systems.
- Recurring monitoring subscriptions:Smart security systems with encrypted local processing can bundle professional monitoring services that generate annuity revenue streams insulated from hardware margin compression.
Industry Challenges
- Interoperability fragmentation:Competing communication protocols between Wi-Fi and Zigbee ecosystems force installers to maintain dual inventory and training capabilities, raising operational overhead.
- Cybersecurity certification timelines:Third-party assessment bottlenecks for CE marking under evolving Radio Equipment Directive amendments delay product launches and compress selling seasons.
- Electrical contractor skill gaps:Mesh protocol configuration and encrypted local processing setup require training investments that many traditional wiring specialists have not absorbed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Homes Market |
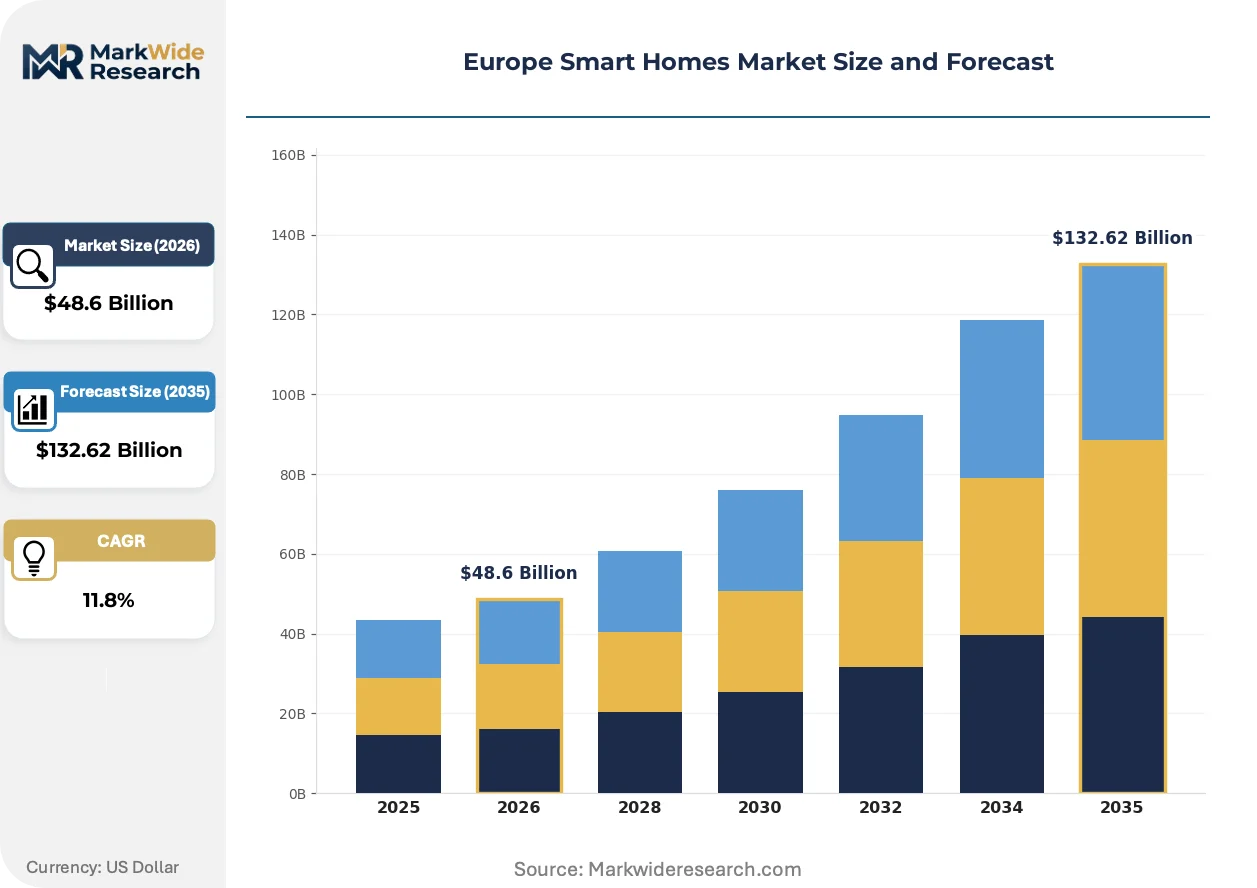
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $132.62 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Smart Security, Smart Thermostats, Smart Appliances Technology: IoT, Zigbee, Z-Wave, Wi-Fi End User: Homeowners, Renters, Property Managers, Builders Application: Energy Management, Security Monitoring, Home Automation, Health Monitoring |
| Companies Covered | Legrand SA, Honeywell International Inc., Signify N.V., ASSA ABLOY, Siemens, Robert Bosch GmbH, Johnson Controls Inc., Amazon.com Inc., Schneider Electric SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Homes Market Shifts & Advancements
Proprietary mesh protocols and edge-computing architectures are reorganizing how European smart home systems communicate, process data, and secure household information against evolving regulatory requirements.
Matter-over-Thread implementations are displacing legacy Wi-Fi dependency in multi-device installations. German renovation contractors are adopting Thread border routers for whole-home automation projects. This convergence is compressing installation timelines and reducing service call frequency for connectivity troubleshooting.
The EU AI Act's risk-classification framework is reshaping predictive energy algorithm deployment strategies. Vendors must pre-assess whether machine-learning models trigger high-risk system designation requiring third-party conformity assessment. French smart thermostat manufacturers are restructuring software architectures to maintain edge-based processing below regulatory thresholds.
Builder-direct procurement of pre-integrated smart home packages is altering traditional electrical distribution channels. United Kingdom housing developers are specifying certified control panel bundles that bypass wholesaler markup. This disintermediation concentrates volume with wiring device heritage suppliers who can deliver CE-marked, Ecodesign-compliant systems at scale.
Europe Smart Homes Market Segmentation
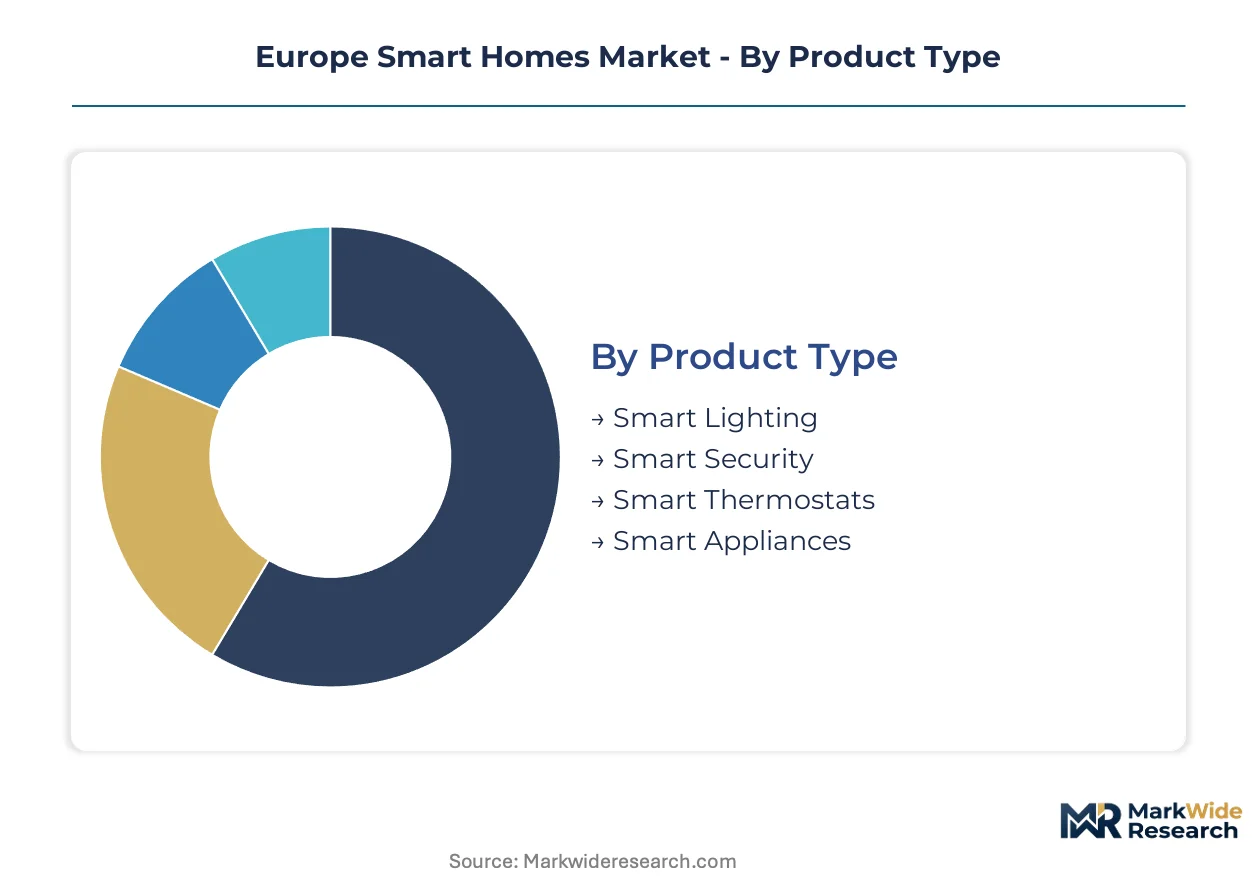
Segmentation in the Europe smart homes sector reveals how regulatory frameworks reshape product development priorities and channel economics. CE marking requirements and Ecodesign mandates create divergent compliance burdens across product categories, forcing vendors to concentrate R&D investment where certification pathways are clearest.
Product Type:
Ecodesign standby power thresholds and GDPR data-localization requirements differentiate margin structures across hardware categories, with cybersecurity certification costs acting as a selective barrier to entry.
- Smart Lighting:Systems integrate occupancy-responsive dimming and circadian rhythm programming through mesh-enabled luminaires. German electrical contractors specify these for multi-device renovations where Signify's proprietary protocols reduce installation complexity. Ecodesign mandates on standby power below 2.00W favor suppliers with in-house driver manufacturing.
- Smart Security:Encrypted local processing architectures keep video and occupancy data within household premises to satisfy GDPR requirements. Recurring monitoring subscriptions generate annuity revenue insulated from hardware margin compression. United Kingdom retrofit demand concentrates here as aging housing stock lacks modern wiring infrastructure.
- Smart Thermostats:Sub-0.5°C temperature variance control captures utility rebate eligibility in France and Germany. Wi-Fi congestion in dense French multi-unit housing degrades reliability and elevates customer service costs.
- Smart Appliances:Connected white goods face ECHA substance restrictions on heavy metals in printed circuit assemblies. Halogen-free substrate alternatives carry constrained supply chains and elevated material costs.
Smart Security handles the majority of throughput; Smart Lighting is expanding most quickly on share as mesh protocol adoption accelerates across German renovation markets.
Technology:
Installation scale and router density determine connectivity architecture selection, with contractor training investments and inventory complexity driving protocol concentration decisions.
- IoT:Broad platform architectures enable cross-device orchestration through cloud-to-edge pipelines. GDPR data-localization requirements accelerate demand for controllers that process automation logic locally rather than routing through external servers.
- Zigbee:Mesh network topology eliminates wiring complexity in whole-home German renovations. 30-second occupancy response windows satisfy efficiency rebate specifications in jurisdictions with strict performance verification.
- Z-Wave:Sub-GHz spectrum penetration excels in multi-story United Kingdom housing with dense construction materials. Smaller ecosystem scale limits peripheral device availability versus Zigbee alternatives.
- Wi-Fi:Dominant in French single-family retrofits where existing router density suffices without additional border hardware. Congestion in multi-unit buildings degrades thermostat reliability and elevates service call frequency.
Zigbee carries the deepest installer preference in volume terms; Matter-over-Thread implementations are climbing the fastest as Thread border routers displace legacy Wi-Fi dependency.
End User:
Procurement authority and rebate capture eligibility segment demand across residential market participants, with builder-direct specifications altering traditional electrical distribution economics.
- Homeowners:Retrofit investment concentrates in Germany and France where utility rebate programs reward documented energy savings. Sub-0.5°C temperature control precision qualifies installations for incentive payments.
- Renters:Portable device preference and landlord permission constraints limit hardwired system adoption. Battery-powered security and plug-in lighting dominate this constrained decision environment.
- Property Managers:Multi-unit portfolio standardization drives demand for centralized monitoring platforms. GDPR compliance across tenant data streams requires encrypted local processing architectures.
- Builders:United Kingdom housing developers specify pre-integrated control panel bundles that bypass wholesaler markup. CE-marked, Ecodesign-compliant systems delivered at scale concentrate volume with wiring device heritage suppliers.
Homeowners represent the largest addressable base; Builders are gaining share fastest as post-Brexit efficiency standards accelerate new construction specification.
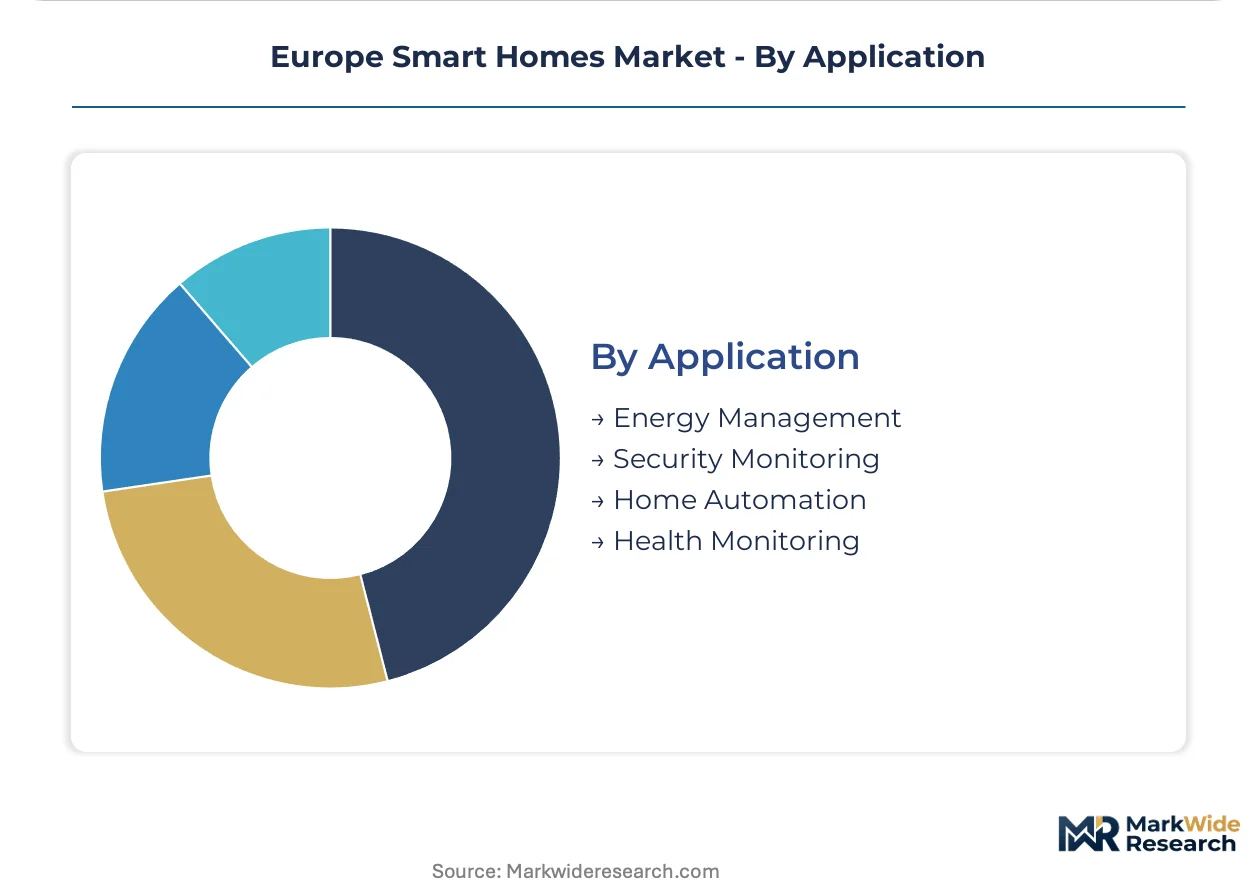
Application:
Performance verification requirements and recurring revenue potential differentiate application economics, with utility program design shaping regional demand concentration.
- Energy Management:HVAC-to-smart-home connectivity captures rebate eligibility through documented consumption reduction. EU Green Deal tightening of Ecodesign regulation forces wholesale device architecture redesigns.
- Security Monitoring:Professional service bundling generates annuity streams insulated from hardware margin compression. GDPR data-localization mandates accelerate encrypted local processing adoption.
- Home Automation:Whole-system orchestration through Matter-over-Thread implementations compresses installation timelines. German renovation contractors adopt Thread border routers for multi-device projects.
- Health Monitoring:Predictive algorithm deployment faces pending EU AI Act risk-classification scrutiny. Edge-based processing architectures aim to maintain classification below high-risk thresholds requiring third-party conformity assessment.
Energy Management commands the deepest margin pool; Health Monitoring shows the steepest expansion trajectory as aging demographics and algorithm sophistication converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supplier concentration clusters around wiring device heritage manufacturers in Western Europe, with compliance capabilities determining market access under tightening Ecodesign mandates. Germany, France, and the United Kingdom absorb the majority of retrofit investment as utility rebate programs and post-Brexit efficiency standards reshape demand geography.
Germany
Homeowners retrofit HVAC-to-smart-home connectivity to capture utility rebates requiring sub-0.5°C temperature variance documentation. The EU Green Deal's Ecodesign for Sustainable Products Regulation forces standby power thresholds below 2.00W across connected devices. Bavarian electrical contractors dominate multi-device renovation markets, specifying Zigbee mesh protocols that reduce installation complexity.
France
Single-family retrofits rely on existing Wi-Fi router density, though multi-unit buildings suffer congestion degrading thermostat reliability. GDPR data-localization requirements accelerate demand for encrypted local processing architectures that keep occupancy data within household premises. The Île-de-France region concentrates smart thermostat manufacturing as vendors restructure software to stay below EU AI Act high-risk thresholds.
United Kingdom
Post-Brexit building efficiency standards create concentrated demand for integrated control panels in aging housing stock lacking modern wiring infrastructure. The country's national building regulator enforces efficiency verification protocols that favor pre-certified system bundles. London-area housing developers specify builder-direct procurement channels that bypass traditional electrical wholesalers.
Netherlands
Randstad urban corridors drive property manager demand for centralized monitoring platforms across multi-unit portfolios. CE marking under the Radio Equipment Directive mandates interoperable cybersecurity baselines that favor suppliers with in-house compliance testing. Eindhoven's electronics cluster anchors edge-computing controller development for GDPR-compliant local processing.
Italy
Lombardy and northern industrial regions concentrate smart lighting adoption through mesh-enabled luminaires with occupancy-responsive dimming. ECHA substance restrictions on heavy metals in printed circuit assemblies push suppliers toward halogen-free substrate alternatives. Milan-area electrical distributors stock dual-protocol inventory to serve both Wi-Fi and Zigbee installation preferences.
Europe Smart Homes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe smart homes sector, creating a tiered structure where compliance capabilities and installation scale determine competitive position. The market consolidates around wiring device heritage suppliers with in-house manufacturing of controllers and sensors. Three archetypes dominate: integrated system bundlers, protocol specialists, and platform-agnostic component suppliers. M&A activity concentrates on cybersecurity certification capabilities and mesh protocol intellectual property, while capacity expansion targets Ecodesign-compliant production lines for sub-2.00W standby power devices.
Among French and Dutch electrical equipment specialists, Legrand SA and Signify N.V. exemplify the wiring device heritage archetype that dominates integrated control panel specification. Robert Bosch GmbH represents the industrial conglomerate model with captive sensor manufacturing and HVAC connectivity integration. These three companies anchor competitive positioning around CE marking compliance speed and electrical contractor channel relationships rather than consumer brand recognition.
| Leading Market Players |
|---|
| Legrand SA |
| Honeywell International Inc. |
| Signify N.V. |
| ASSA ABLOY |
| Siemens |
| Robert Bosch GmbH |
| Johnson Controls Inc. |
| Amazon.com Inc. |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
CE marking under the Radio Equipment Directive gates both supplier qualification and price differentiation simultaneously, forcing vendors to absorb third-party conformity assessment costs that stratify hardware tiers across the European smart homes sector.
Pricing Analysis
The EU Green Deal's Ecodesign for Sustainable Products Regulation dictates the pricing tier structure across European smart home devices. Three-tier pricing structure across premium, standard, and economy levels separates vendors with in-house cybersecurity certification from those outsourcing compliance testing. Cost compression in economy-tier controllers is intensifying because ECHA substance restrictions on heavy metals elevate halogen-free substrate expenses. Property managers deploying multi-unit portfolios exhibit the highest price sensitivity, while German electrical contractors specifying mesh protocol systems for whole-home renovations demonstrate the lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes constrain printed circuit assembly inbound flows to Eindhoven and Shenzhen manufacturing clusters. Supply concentrates in China for controller chipsets, Germany for wiring device heritage components, and the Netherlands for edge-computing hardware. Halogen-free substrate alternatives, Zigbee mesh protocol modules, and encrypted local processing chipsets constitute critical input dependencies. Single-source vulnerability in semiconductor controller supply creates structural risk for vendors lacking captive sensor manufacturing. Distribution runs through electrical wholesaler networks in France and Italy, with builder-direct procurement channels gaining share in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution threats from Matter-over-Thread protocol ecosystems that displace legacy Wi-Fi and Zigbee installations across German renovation markets.
For Market Incumbents: Consolidate cybersecurity certification capabilities through acquisition of specialized testing laboratories to compress CE marking timelines under Radio Equipment Directive amendments. Build backward integration into halogen-free substrate manufacturing to offset ECHA-driven material cost escalation. Channel control through exclusive electrical contractor training programs on mesh protocol configuration defends against platform-agnostic component suppliers.
For New Entrants and Emerging Players: Differentiate on GDPR-compliant encrypted local processing architectures that keep occupancy data within household premises rather than cloud servers. White-space targets concentrate in United Kingdom retrofit markets where aging housing stock lacks modern wiring infrastructure. The most penetrable segment is builder-direct procurement channels for pre-integrated control panel bundles. Go-to-market execution should anchor on London-area housing developer relationships bypassing traditional electrical wholesalers.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core smart home divisions lacking CE marking compliance speed. Long-term viability hinges on vendors capturing recurring monitoring subscription revenue insulated from hardware margin compression across the next decade. Acquisition candidates with proprietary mesh protocol intellectual property and in-house sensor manufacturing anchor defensive positioning. The signal to watch is EU AI Act final risk-classification thresholds for predictive energy algorithms.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acquisition | Compresses Radio Equipment Directive third-party assessment timelines for faster product launches. |
| Halogen-Free Substrate Backward Integration | Offsets ECHA heavy metal restriction costs in printed circuit assemblies. |
| Mesh Protocol IP Licensing | Generates royalty streams from German electrical contractor specification preferences. |
| Builder-Direct Channel Development | Bypasses wholesaler markup in United Kingdom post-Brexit efficiency standard markets. |
| Encrypted Local Processing R&D | Maintains GDPR compliance while reducing cloud infrastructure dependency. |
Research Methodology
Initial hypotheses were tested against primary input from electrical contractor channel managers, smart home platform engineers, regulatory affairs specialists at wiring device manufacturers, and procurement leads at United Kingdom housing developers and refined through secondary validation. Primary fieldwork combined structured interviews with Bavarian renovation contractors and Île-de-France thermostat manufacturers. Secondary sources encompassed CE marking documentation under the Radio Equipment Directive, ECHA substance restriction filings, EU Green Deal policy releases, and utility rebate program specifications across Germany and France. Bottom-up installation volume estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, technology protocol, end-user procurement authority, and application use case anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included Ecodesign standby power threshold compliance trajectories, Zigbee mesh protocol adoption curves in German renovation markets, and GDPR data-localization requirement implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity or accelerated Matter-over-Thread ecosystem maturation would require recalibration. Forecasts reflect documented assumptions regarding CE marking timeline stability and halogen-free substrate supply chain scaling. Regulatory amendment velocity, cybersecurity certification bottleneck severity, and electrical contractor training absorption rates constitute primary revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Edible Insects for Animal Feed Market
Others
Solar Animal Repellent Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Level Measuring Instrument Market
Others
North America Medical Simulation Market
Others
Grna Market
Others
Germany Smart Home Market
Others
North America Wiring Duct Market
Others
CAR T Cell Therapy Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Coalescing Filter Market
Others
Process Spectroscopy Market
Others
United States Cigarette Market
Others
Mine Rescue Vehicle Market
Others
Hybrid System Market
Others
Reef Aquarium Market