
 Asia-Pacific Battery E-Commerce Market | 2026-2036
Asia-Pacific Battery E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Battery E-Commerce Market Insights
Lithium iron phosphate is hardening cost structures across the Asia-Pacific Battery E-Commerce landscape as manufacturers pivot from cobalt-dependent chemistries. BYD Co Ltd leverages its captive cell production to undercut marketplace pricing on bulk orders. Samsung SDI Co Ltd anchors premium segments through stringent cycle-life specifications that appeal to data center buyers. Alibaba controls the dominant B2C gateway, though specialized industrial buyers increasingly navigate direct-sales portals hosted by manufacturers.
Asia-Pacific Battery E-Commerce denotes the digital commercial exchange of electrochemical energy storage devices, encompassing cylindrical 18650 and prismatic pouch formats with nominal voltages from 1.2V to 3.7V, primarily serving automotive, consumer electronics, and stationary power backup applications. Online retail channels for lithium-ion products command the deepest margin pools due to high unit values and buyer willingness to pay for verified authenticity, while subscription services for enterprise UPS fleets represent the fastest-growing sales channel as facilities managers seek predictable replacement cycles. Lead acid transactions still dominate volume through marketplace listings targeting price-sensitive automotive aftermarket segments across South Asia.
China's SAMR enforces GB standards compliance for lithium-ion products sold through domestic e-commerce platforms, effectively blocking uncertified cross-border listings. India's BIS mandates and DGFT import classification rules shape which battery chemistries enter digital marketplaces, creating compliance costs that favor established sellers with testing infrastructure. South Korea's KC certification, administered by the national standards body, adds another layer for marketplace vendors targeting that market. Stakeholders must monitor how evolving hazardous goods shipping rules from Korea's Ministry of Trade, Energy and Industry and parallel frameworks across ASEAN jurisdictions reshape fulfillment network design and last-mile delivery economics for energy-dense products.
Market Dynamics
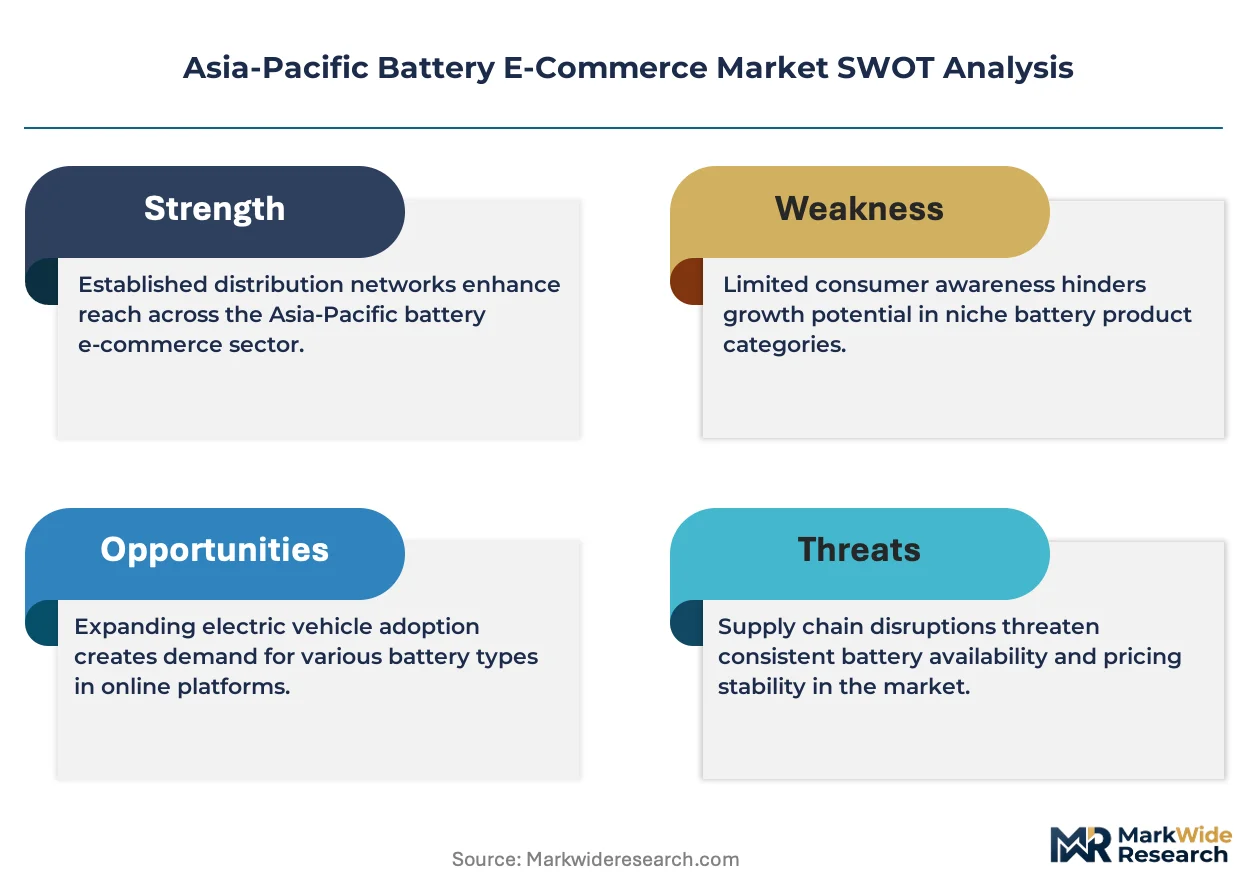
Lithium iron phosphate chemistry is absorbing procurement volume across Asia-Pacific Battery E-Commerce as cobalt price volatility and ESG scrutiny redirect buyer preferences toward lower-cost, thermally stable cell formats.
Growth Catalysts
- India's BIS certification tightening:Stricter import standards for lithium-ion products filter seller eligibility on domestic platforms, reducing counterfeit listings and elevating trust metrics for compliant vendors.
- Electric vehicle fleet procurement digitization:Southeast Asian commercial operators accelerate online cell sourcing to compress procurement cycles and secure inventory ahead of supply crunches.
- Same-day delivery infrastructure maturation:China's tier-one cities now support industrial power storage fulfillment within hours, conditioning B2B buyers to expect velocity previously reserved for consumer electronics.
Market Restraints
- Raw material concentration risk:Cathode precursor processing clusters in Chinese provinces create single-source dependency for marketplace sellers sourcing NMC and LFP cells.
- Cross-border hazardous goods friction:Korea's Ministry of Trade, Energy and Industry shipping rules impose documentation burdens that inflate last-mile costs for energy-dense products entering from ASEAN origins.
- Lead acid residual volume lock-in:Price-sensitive automotive aftermarket segments across South Asia continue transacting through marketplace listings, delaying lithium-ion penetration in cost-constrained applications.
Strategic Opportunities
- Enterprise UPS subscription services:Facilities managers in Australian data centers seek predictable replacement cycles, opening recurring revenue channels outside transactional marketplace models.
- Vietnam's manufacturing zone electrification:Industrial park operators require bulk stationary storage procurement, creating demand for direct-manufacturer portals bypassing Alibaba's B2C gateway.
- South Korea's KC certification alignment:Marketplace vendors achieving national standards body approval gain preferential platform placement and reduced customs friction for cross-border listings.
Industry Challenges
- Cell authentication skill scarcity:E-commerce platform quality control teams lack electrochemical expertise to verify cycle-life claims against seller specifications, exposing buyers to premature degradation risk.
- Legacy warehouse hazardous goods reconfiguration:Fulfillment centers across Indonesia and Thailand require capital-intensive fire suppression and thermal containment retrofits to handle lithium-ion inventory density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Battery E-Commerce Market |
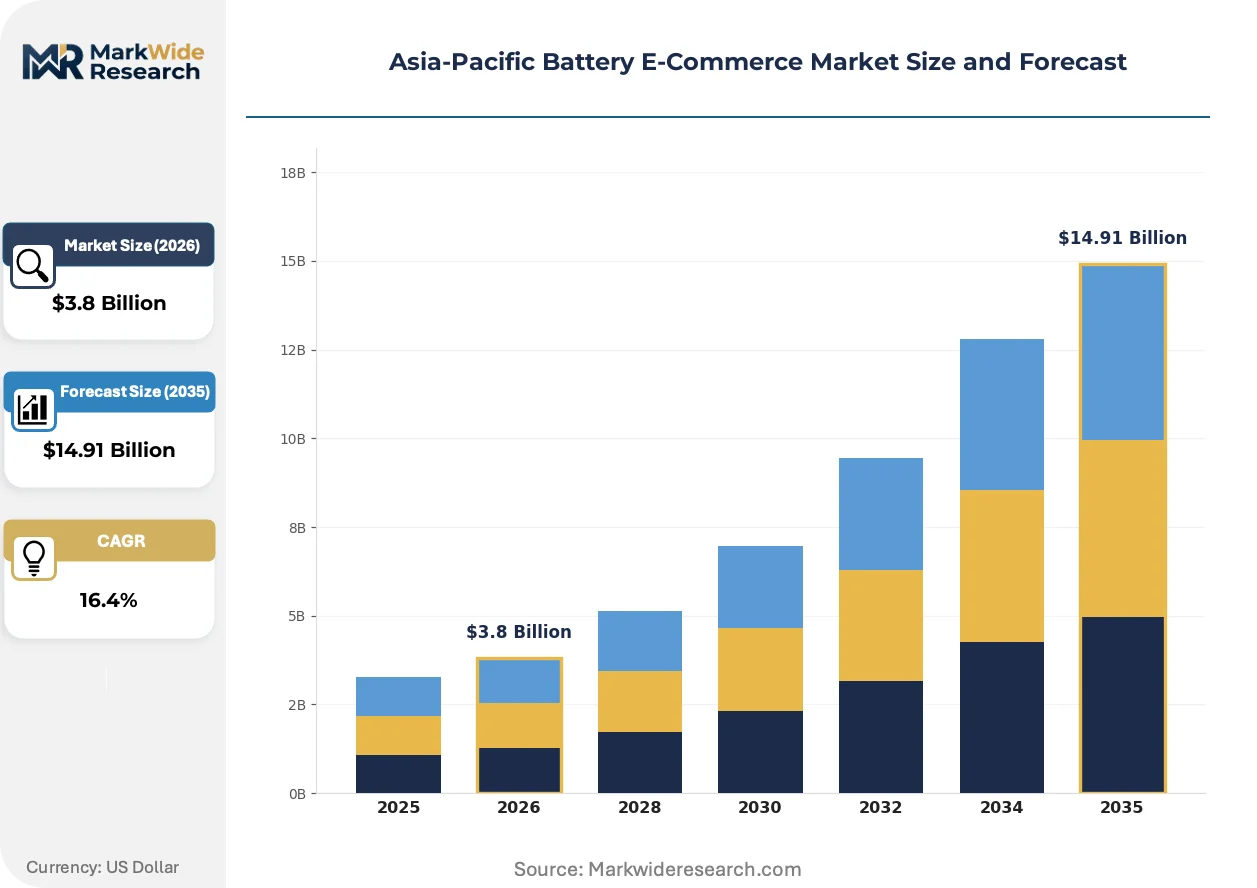
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead Acid, Alkaline Sales Channel: Online Retail, Direct Sales, Marketplace, Subscription Services Customer Type: Consumers, Small Businesses, Enterprises, OEMs Delivery Mode: Standard Shipping, Express Delivery, Store Pickup, Drop Shipping |
| Companies Covered | Exide Industries Ltd, Luminous Power Technologies Pvt Ltd, Panasonic Corporation, TATA AutoComp GY Batteries Pvt Ltd, Okaya Power Pvt Ltd, LG Chem Ltd, Samsung SDI Co Ltd, BYD Co Ltd, Alibaba, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Battery E-Commerce Market Trends and Innovations
Digital commerce infrastructure for electrochemical storage is bifurcating between mass-market platforms and specialized direct-manufacturer portals, with authentication technology and regulatory compliance emerging as the primary axes of differentiation.
Solid-state electrolyte research is absorbing venture funding and pilot production capacity as manufacturers seek energy density gains beyond liquid lithium-ion theoretical limits. Data center operators with space-constrained facilities pilot early samples despite premium pricing, betting on volumetric efficiency to offset cell cost. This transition is absorbing engineering resources that previously flowed into incremental liquid electrolyte improvements, compressing the competitive window for conventional format optimization.
China's SAMR enforcement of GB standards compliance for domestic platform listings erects a technical barrier that uncertified cross-border sellers cannot easily circumvent. The regulation redirects marketplace traffic toward domestic manufacturers with in-house testing infrastructure, fragmenting what had been a more open competitive field. Lithium-ion products lacking GB certification face algorithmic deprioritization on major platforms, forcing international sellers to establish local testing partnerships or abandon the channel.
Fleet managers across Southeast Asian logistics operators now specify authenticated cell provenance as a contractual requirement, displacing price-only evaluation frameworks. Direct-sales portals hosted by BYD and Samsung SDI capture this preference shift, offering batch-level traceability that marketplace aggregators struggle to replicate. Vietnam and Thailand exhibit the strongest migration toward manufacturer-direct relationships, where procurement teams prioritize cycle-life verification over the convenience of multi-brand comparison shopping.
Asia-Pacific Battery E-Commerce Market Segmentation
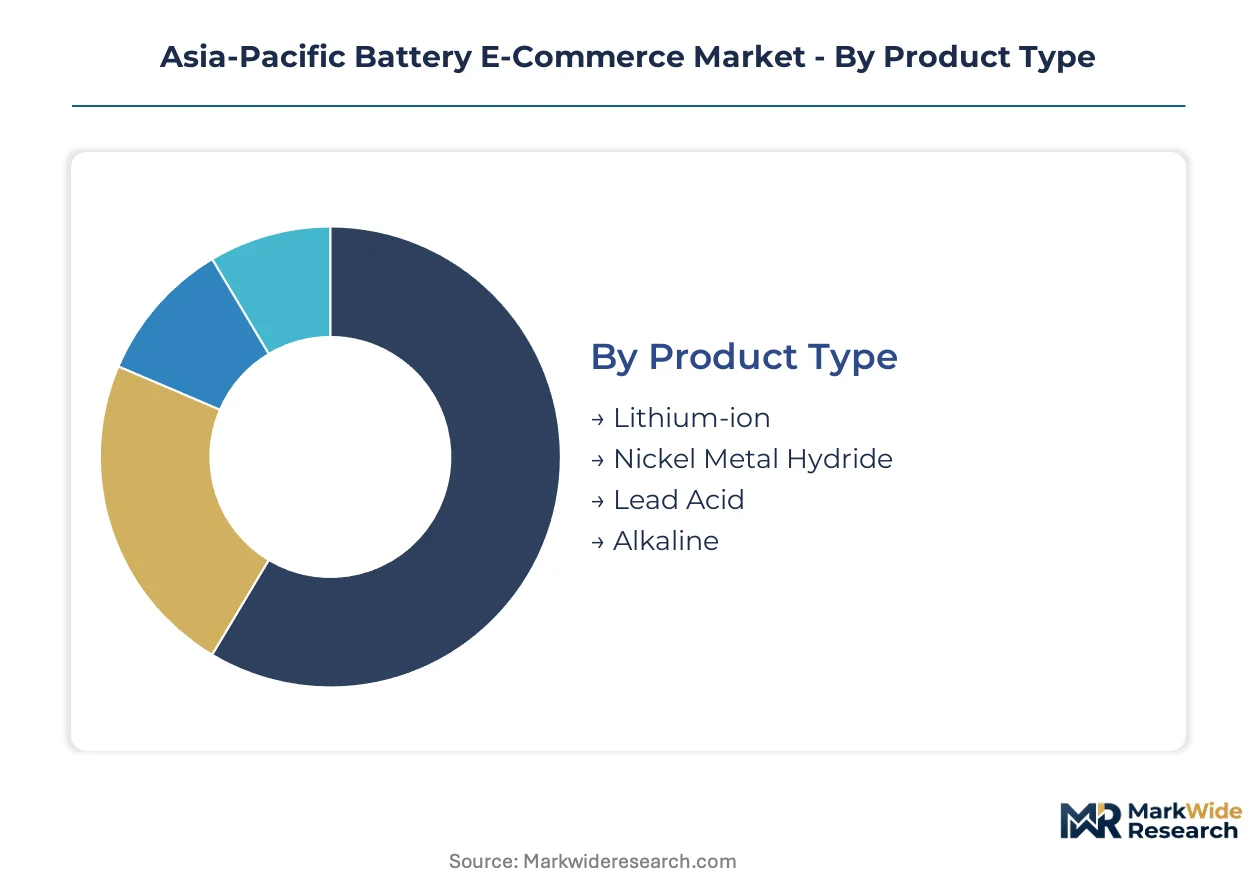
Battery e-commerce segmentation in Asia-Pacific reflects divergent fulfillment economics and authentication requirements across chemistries and buyer types. Procurement patterns split between high-velocity consumer transactions and contract-heavy enterprise sourcing with divergent margin structures.
Product Type:
Capital intensity varies sharply across electrochemical formats, with lithium-ion demanding the heaviest investment in thermal containment infrastructure and certification testing.
- Lithium-ion:Dominates procurement value through cylindrical 18650 and prismatic pouch formats with nominal voltages from 1.2V to 3.7V. Demand concentrates in China's tier-one cities where same-day delivery networks for industrial power storage have matured, though raw material concentration in cathode precursor processing clusters creates single-source dependency risks.
- Lead Acid:Retains volume leadership through marketplace listings targeting price-sensitive automotive aftermarket segments across South Asia. India's BIS certification mandates filter seller eligibility on digital platforms, elevating trust metrics for compliant vendors while delaying lithium-ion penetration in cost-constrained applications.
- Nickel Metal Hydride:Serves legacy hybrid vehicle battery replacement cycles and industrial backup systems with moderate energy density requirements. Procurement flows through direct-sales portals where batch-level traceability appeals to fleet operators.
- Alkaline:Commands shallow margins in consumer electronics accessory channels with minimal regulatory friction. Transactions aggregate on mass-market platforms with limited authentication infrastructure.
Most installed capacity flows through Lithium-ion. Expansion is steepest in Lead Acid as South Asian aftermarket demand persists.
Sales Channel:
Channel selection maps to buyer sophistication, with enterprise procurement gravitating toward relationship-based models that bypass aggregator fees.
- Online Retail:Captures consumer electronics and automotive aftermarket transactions through Alibaba's B2C gateway. China's SAMR enforces GB standards compliance, blocking uncertified cross-border listings and redirecting traffic toward domestic manufacturers with in-house testing infrastructure.
- Direct Sales:BYD Co Ltd and Samsung SDI Co Ltd host proprietary portals offering batch-level traceability that marketplace aggregators struggle to replicate. Vietnam and Thailand exhibit the strongest migration toward manufacturer-direct relationships where procurement teams prioritize cycle-life verification.
- Marketplace:Aggregates multi-brand comparison shopping for small businesses with limited technical staff. Platform quality control teams lack electrochemical expertise to verify cycle-life claims, exposing buyers to premature degradation risk.
- Subscription Services:Facilities managers in Australian data centers seek predictable replacement cycles for enterprise UPS fleets, opening recurring revenue channels outside transactional marketplace models.
Transaction volume concentrates in Online Retail. Value capture is expanding most quickly in Subscription Services as facilities managers outsource replacement cycle management.
Customer Type:
Customer segmentation reflects divergent authentication requirements and contract structures, with OEMs demanding the most stringent provenance documentation.
- Enterprises:Data center operators specify authenticated cell provenance as contractual requirements, displacing price-only evaluation frameworks. Solid-state electrolyte pilots absorb premium pricing despite early-stage production constraints.
- OEMs:Electric vehicle fleet operators across Southeast Asia accelerate online cell sourcing to compress procurement cycles and secure inventory ahead of supply crunches. Direct-sales portals capture this preference shift with verified batch documentation.
- Small Businesses:Industrial park operators in Vietnam's manufacturing zones require bulk stationary storage procurement, creating demand for direct-manufacturer portals bypassing Alibaba's B2C gateway.
- Consumers:Price-sensitive buyers in South Asian automotive aftermarket segments transact through marketplace listings with minimal technical verification, sustaining lead acid residual volume.
Revenue concentration sits with Enterprises. Customer acquisition is climbing the fastest among OEMs as fleet electrification accelerates procurement digitization.
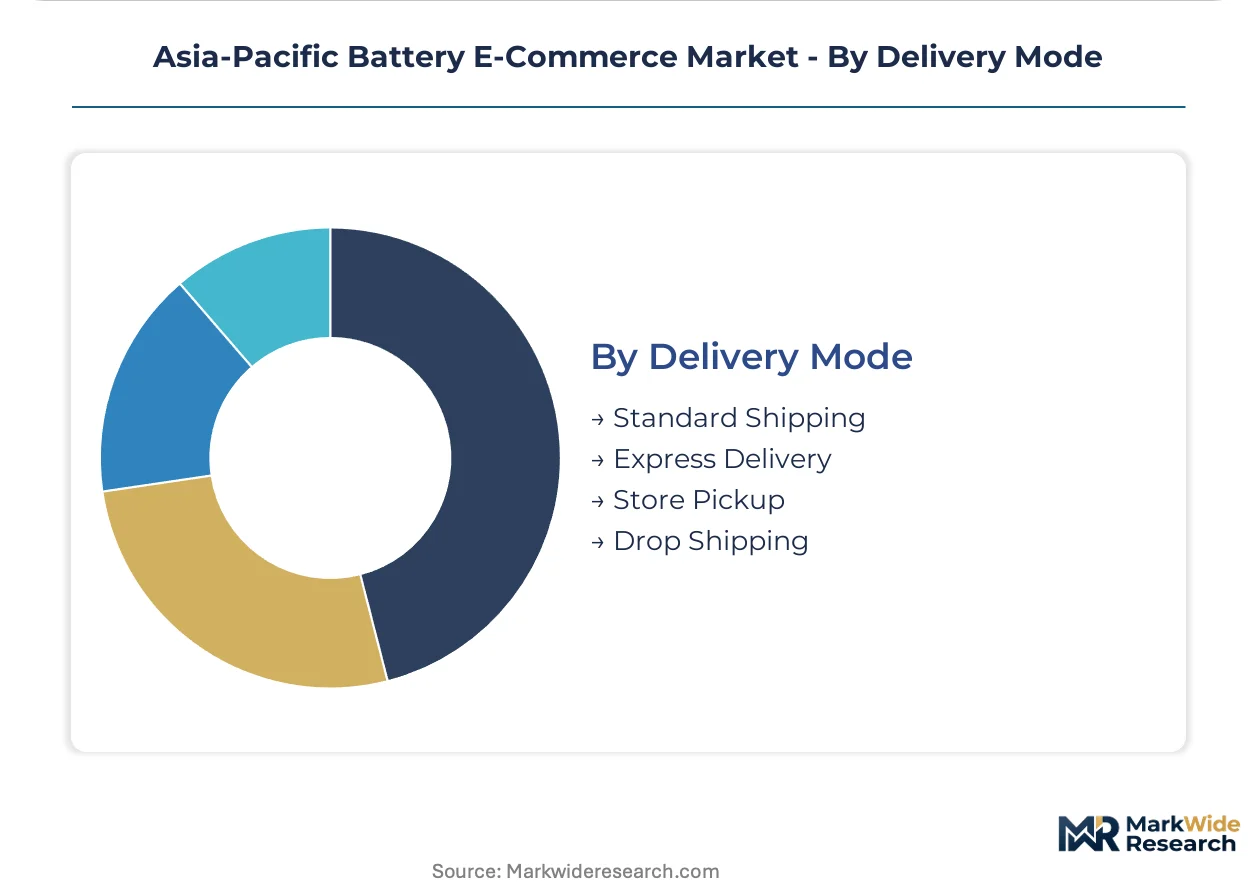
Delivery Mode:
Fulfillment economics bifurcate between hazardous goods infrastructure investments and lean last-mile networks.
- Express Delivery:China's tier-one cities support industrial power storage fulfillment within hours, conditioning B2B buyers to expect velocity previously reserved for consumer electronics. Korea's Ministry of Trade, Energy and Industry shipping rules impose documentation burdens that inflate last-mile costs for energy-dense products entering from ASEAN origins.
- Standard Shipping:Dominates lead acid transactions across South Asia where price sensitivity outweighs velocity requirements. Fulfillment centers across Indonesia and Thailand require capital-intensive fire suppression retrofits to handle lithium-ion inventory density.
- Store Pickup:Serves authenticated battery exchanges where buyers verify physical specifications before accepting custody. Limited penetration outside China's urban core.
- Drop Shipping:Cross-border sellers leverage ASEAN manufacturing proximity to bypass domestic warehousing investments, though DGFT import classification rules in India reshape eligibility for this model.
Shipment volume runs through Standard Shipping. Infrastructure investment is gaining share fastest in Express Delivery as same-day expectations permeate B2B procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta battery manufacturing clusters anchor procurement digitization across the Asia-Pacific region, with tier-one cities conditioning industrial buyers to expect same-day fulfillment velocity. Cross-border hazardous goods regulations fragment fulfillment economics between Northeast Asian certification regimes and ASEAN's evolving standards frameworks.
China
Shanghai and Shenzhen industrial zones drive lithium-ion procurement volume through mature same-day delivery networks for power storage applications. SAMR enforcement of GB standards compliance blocks uncertified cross-border listings on domestic e-commerce platforms. Guangdong province cathode precursor processing clusters create single-source dependency for marketplace sellers sourcing NMC and LFP cells.
India
BIS certification mandates tighten import standards for lithium-ion products, filtering seller eligibility on domestic digital platforms. DGFT import classification rules reshape cross-border listing eligibility and create compliance costs favoring established sellers with testing infrastructure. Maharashtra and Gujarat industrial corridors concentrate demand from automotive aftermarket segments transitioning procurement online.
South Korea
KC certification administered by the national standards body adds regulatory layers for marketplace vendors targeting domestic buyers. Ministry of Trade, Energy and Industry hazardous goods shipping rules impose documentation burdens inflating last-mile costs for energy-dense products entering from ASEAN origins. Seoul Capital Area data center operators specify authenticated cell provenance as contractual requirements.
Vietnam
Industrial park operators in manufacturing zones require bulk stationary storage procurement, creating demand for direct-manufacturer portals bypassing mass-market aggregators. Northern provinces exhibit strongest migration toward manufacturer-direct relationships where procurement teams prioritize cycle-life verification. Fulfillment centers require capital-intensive fire suppression retrofits to handle lithium-ion inventory density safely.
Australia
Facilities managers in Sydney and Melbourne data centers seek predictable replacement cycles for enterprise UPS fleets, opening subscription service channels outside transactional marketplace models. State-level electrical safety regulations govern battery installation standards affecting e-commerce buyer education requirements. Western Australia mining operations pilot authenticated cell provenance frameworks for remote power system reliability.
Asia-Pacific Battery E-Commerce Market Competitive Landscape
Global majors compete with regional champions across certification infrastructure and fulfillment velocity, creating tiered competitive dynamics. BYD Co Ltd leverages captive cell production to undercut marketplace pricing on bulk orders, while Samsung SDI Co Ltd anchors premium segments through stringent cycle-life specifications. The vendor base separates into three strategic archetypes: vertically integrated manufacturers with proprietary portals, platform aggregators controlling consumer gateway access, and specialized subscription service operators. Dominant competitive moves center on backward integration into cathode material processing and direct-sales portal development bypassing aggregator fee structures.
Within the vertically integrated manufacturer tier, BYD Co Ltd, Samsung SDI Co Ltd, and LG Chem Ltd occupy positions defined by captive production capacity and certification infrastructure ownership. BYD Co Ltd exemplifies the Chinese archetype of leveraging upstream cell manufacturing to support direct e-commerce channels. Samsung SDI Co Ltd and LG Chem Ltd represent the Korean model of premium-tier positioning through national standards body alignment and cycle-life specification differentiation. Alibaba sits within the platform aggregator archetype, controlling dominant B2C gateway access while facing displacement pressure from manufacturer-direct channels in industrial segments. Panasonic Corporation occupies a transitional position between mass-market platform presence and specialized industrial direct-sales development.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| Luminous Power Technologies Pvt Ltd |
| Panasonic Corporation |
| TATA AutoComp GY Batteries Pvt Ltd |
| Okaya Power Pvt Ltd |
| LG Chem Ltd |
| Samsung SDI Co Ltd |
| BYD Co Ltd |
| Alibaba |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed Chinese producers anchor cathode precursor supply, compressing margin structures for marketplace sellers unable to match their captive material access and state-supported certification infrastructure.
Pricing Analysis
Input-cost pass-through from lithium carbonate and cobalt sulfate volatility drives contract renegotiation frequency among non-integrated distributors. Three-tier pricing structure across premium, standard, and economy levels separates Samsung SDI's cycle-life-guaranteed cells from BYD's volume-discounted bulk orders and unbranded marketplace listings. Pricing pressure stems from Guangdong province's cathode processing concentration, which grants integrated manufacturers 15-20 point margin advantages. Fleet operators exhibit lowest price sensitivity, while South Asian automotive aftermarket buyers transact almost exclusively on unit cost.
Supply Chain Analysis
Cathode precursor supply rests on Chinese provincial processing clusters in Guangdong and Fujian, with South Korean and Japanese specialty chemical producers holding secondary positions. Lithium carbonate feedstock draws from Australian hard-rock and Chilean brine operations, while cobalt sulfate hinges on DRC concentrate refining. Single-source vulnerability concentrates in China's NMC and LFP precursor capacity, exposing non-integrated sellers to allocation risk during supply crunches. Distribution runs through Alibaba's B2C gateway for consumer transactions, with direct-manufacturer portals capturing enterprise procurement requiring batch-level traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's subsidized precursor processing and India's tightening BIS certification requirements creates margin capture opportunities for vendors with dual-jurisdiction compliance infrastructure.
For Market Incumbents: To counter manufacturer-direct portal displacement, BYD and Samsung SDI should deepen backward integration into cathode material processing while expanding fire-suppression-equipped fulfillment networks across Indonesia and Thailand. Certification investment in India's BIS and South Korea's KC standards represents the critical defensive lever against marketplace algorithmic deprioritization. For New Entrants and Emerging Players: Direct-sales portal development for Vietnam's industrial park operators offers the most penetrable white-space target, as manufacturing zone electrification demand outpaces established vendor direct-channel capacity. Subscription service models for Australian data center UPS replacement cycles provide a second entry vector with recurring revenue mechanics distinct from transactional marketplace competition. For Investors and Strategic Acquirers: Battery manufacturer conglomerates are the most active acquirer in this space, targeting certification-capable marketplace vendors with established BIS or KC infrastructure. Over a five-to-ten year horizon, ownership of testing laboratory networks and hazardous-goods fulfillment assets will outperform pure trading plays. The signal to watch is India's DGFT import classification rule evolution, which will determine cross-border seller eligibility and reshape platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Processing | Guangdong province precursor capacity ownership neutralizes raw material allocation risk for integrated manufacturers. |
| KC Certification Achievement | South Korea's national standards body approval unlocks preferential platform placement and reduced customs friction. |
| Direct-Sales Portal Launch | Manufacturer-hosted channels capture fleet operator demand for batch-level traceability that Alibaba cannot replicate. |
| Subscription Service Development | Australian data center UPS replacement cycle outsourcing creates recurring revenue outside transactional marketplace models. |
| Hazardous Goods Fulfillment Expansion | Fire-suppression-equipped warehouses in Indonesia and Thailand enable lithium-ion inventory density compliance. |
Research Methodology
Coverage spans China, India, South Korea, Vietnam, and Australia, with primary inputs from each market's battery procurement decision-makers. The analysis combines interviews with fleet operators, data center facilities managers, e-commerce platform quality control directors, and hazardous goods logistics specialists with secondary validation from SAMR GB standards filings, BIS certification registries, Korea's Ministry of Trade hazardous goods shipping bulletins, and customs trade data. Bottom-up transaction analysis and top-down market sizing triangulate volume and value estimates.
Granularity-level modeling operates at chemistry-format, sales-channel, and customer-type intersections with regional regulatory cluster differentiation. CAGRs derive from segment-level growth rate aggregation across the projection horizon, with lithium-ion penetration curves, lead acid residual volume decay, and subscription service adoption rates as battery-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state electrolyte commercialization would alter the outlook for liquid lithium-ion format optimization investments. Forecasts reflect assumptions regarding BIS certification enforcement intensity and ASEAN hazardous goods rule harmonization progress. A small set of regulatory triggers—India's DGFT import reclassification, Korea's Ministry of Trade shipping rule amendments, and China's SAMR algorithmic deprioritization thresholds—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Molded Plastics Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
India Data Center Physical Security Market
Others
Thermal Energy Flow Metering Solutions Market
Others
South Korea Smart Home Market
Others
Japan Coal Market
Others
Storage Dewar and Dry Shipper Market
Others
Vacuum Evaporators Market
Others
Europe Travel Retail Market
Others
Air Separation Unit Market
Others
Port Replicator Market
Others
Composite Copper Foil Production Equipment Market
Others
Managed Testing Services Market
Others
AC Switchgear Market
Others
Digital Education Projector Market
Others
Japan Smart Home Market