
 Hookah Tobacco Market | 2026-2036
Hookah Tobacco Market Size, Share, and Industry Trends Forecast 2026-2036
Hookah Tobacco Market Intelligence
ISO 9001 quality management certification is bifurcating the competitive landscape into organized manufacturers and informal producers. Al Fakher Tobacco Trading leverages its vertical integration from leaf sourcing to finished pouches, sustaining cost advantages across Middle Eastern and European distribution channels. Starbuzz Tobacco Inc. dominates the North American specialty retail segment through controlled direct-to-lounge relationships and flavor innovation pipelines.
Hookah tobacco comprises processed tobacco leaves blended with glycerin, molasses, and natural or synthetic flavor extracts, then heat-cured to produce smokeable shisha with specific moisture content and cut specifications for optimal heat management in waterpipe devices. Flavored product types anchor the majority of volume, with mint and fruit profiles commanding premium positioning in Western markets while herbal and nicotine-free alternatives are gaining fastest in regulatory-constrained European jurisdictions. Packaging in ready-to-use tins captures higher margins than bulk formats, though pouches sustain volume leadership in price-sensitive Middle Eastern markets.
FDA oversight of deemed tobacco products, the EU Tobacco Products Directive with its flavor notification requirements, and Egypt's Ministry of Health standards for local manufacturing collectively shape formulation constraints, labeling mandates, and import access across major consumption regions. Stakeholders must monitor pending flavor prohibitions and taxation escalations in core European markets, as these policy trajectories will determine whether manufacturers prioritize reformulation investment or geographic portfolio rebalancing toward less regulated demand centers.
Market Dynamics
Flavor prohibition proposals across core European markets are forcing manufacturers to accelerate reformulation timelines while Egyptian production clusters absorb displaced volume through informal export channels.
Growth Catalysts
- EU Tobacco Products Directive flavor notification pathways:Early movers in Germany and France securing product authorizations before 2025 deadlines capture shelf space as smaller competitors exit.
- Social lounge experiential hospitality:Cairo, Dubai, and Istanbul venues expand consumption occasions through extended-session menu engineering and heat-management device rentals.
- Molasses-glycerin blending automation:Egyptian and Jordanian manufacturers deploying continuous-mixing systems reduce batch-to-batch variability and labor intensity.
Market Restraints
- Raw leaf supply concentration:Zimbabwe and Malawi flue-cured tobacco purchases dominate input costs, with currency volatility in source markets transmitting directly to finished goods pricing.
- Technical heat-management limitations:Traditional foil-and-coal configurations face displacement from electronic heating elements that alter moisture release profiles and require reformulation.
- Regulatory friction from pending flavor bans:Netherlands and Belgium prohibition timelines create inventory stranding risk for distributors holding flavored stock.
Strategic Opportunities
- Underpenetrated Southeast Asian demand:Indonesia and Vietnam urban youth segments show nascent shisha adoption with limited local manufacturing presence.
- Herbal and nicotine-free regulatory tailwind:France ANSM guidance on non-tobacco inhalables opens shelf placement in channels restricted for nicotine-containing products.
- Direct-to-lounge distribution innovation:Bypassing wholesale tiers through captive delivery networks captures margin and consumption data in Saudi Arabia and UAE urban centers.
Industry Challenges
- ISO 9001 certification timeline compression:Egyptian informal producers face 18-24 month compliance gaps as European importers mandate documented quality systems.
- Flavor chemist skill scarcity:Synthetic and natural extract formulation expertise concentrates in European flavor houses, creating recruitment bottlenecks for Middle Eastern manufacturers.
- Heat device integration complexity:Electronic heating system partnerships require co-development investment with hardware suppliers outside traditional tobacco supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hookah Tobacco Market |
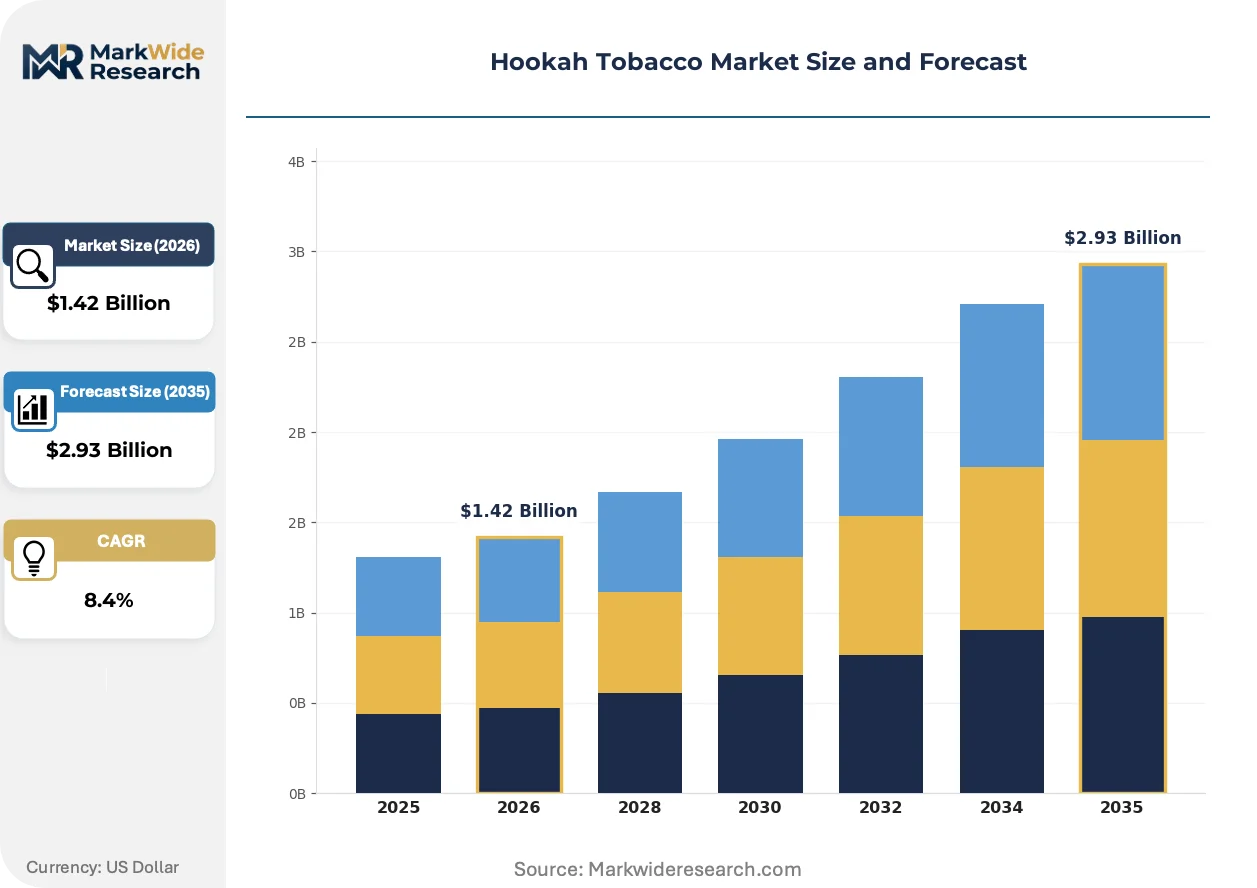
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Herbal, Nicotine-Free Material: Tobacco Leaves, Glycerin, Molasses, Natural Extracts Flavor Profile: Mint, Fruit, Spices, Sweet Packaging Type: Pouches, Tins, Bulk, Ready-to-Use |
| Companies Covered | Al Fakher Tobacco Trading, Starbuzz Tobacco Inc., Fumari Inc., Social Smoke Inc., Haze Tobacco LLC, Japan Tobacco Inc., Nakhla Tobacco, Cloud Tobacco Inc., Tangiers Tobacco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hookah Tobacco Market Strategic Shifts & Innovations
Reformulation science and consumption device engineering are converging to reshape product specifications and channel access requirements across regulated markets.
Heat-not-burn ceramic and alloy chamber technology is fragmenting the accessory market by enabling precise temperature control that demands lower-moisture shisha formulations. North American specialty retailers and Gulf lounge operators are adopting these systems at accelerated replacement cycles. This hardware shift is compressing margins for traditional foil-and-natural-coal suppliers while rewarding manufacturers with reformulation capabilities.
REACH chemical substance restrictions and EU flavor notification requirements are narrowing the approved additive list for products entering Germany, France, and Benelux markets. Industrial consequence includes accelerated migration of formulation R&D to jurisdictions with less restrictive precursor approval pathways. Herbal and synthetic nicotine alternatives face divergent classification pathways across member states, creating compliance fragmentation.
Lounge procurement is consolidating toward exclusive supplier arrangements with volume-commitment pricing and co-branded menu development. Traditional wholesale distributors in Dubai and Cairo are losing share to direct manufacturer-lounge contracts that bundle product, device, and staff training. This channel restructuring is most visible in Saudi Arabia's Riyadh and Jeddah hospitality corridors where sovereign wealth-backed venue rollouts demand single-source accountability.
Hookah Tobacco Market Segmentation
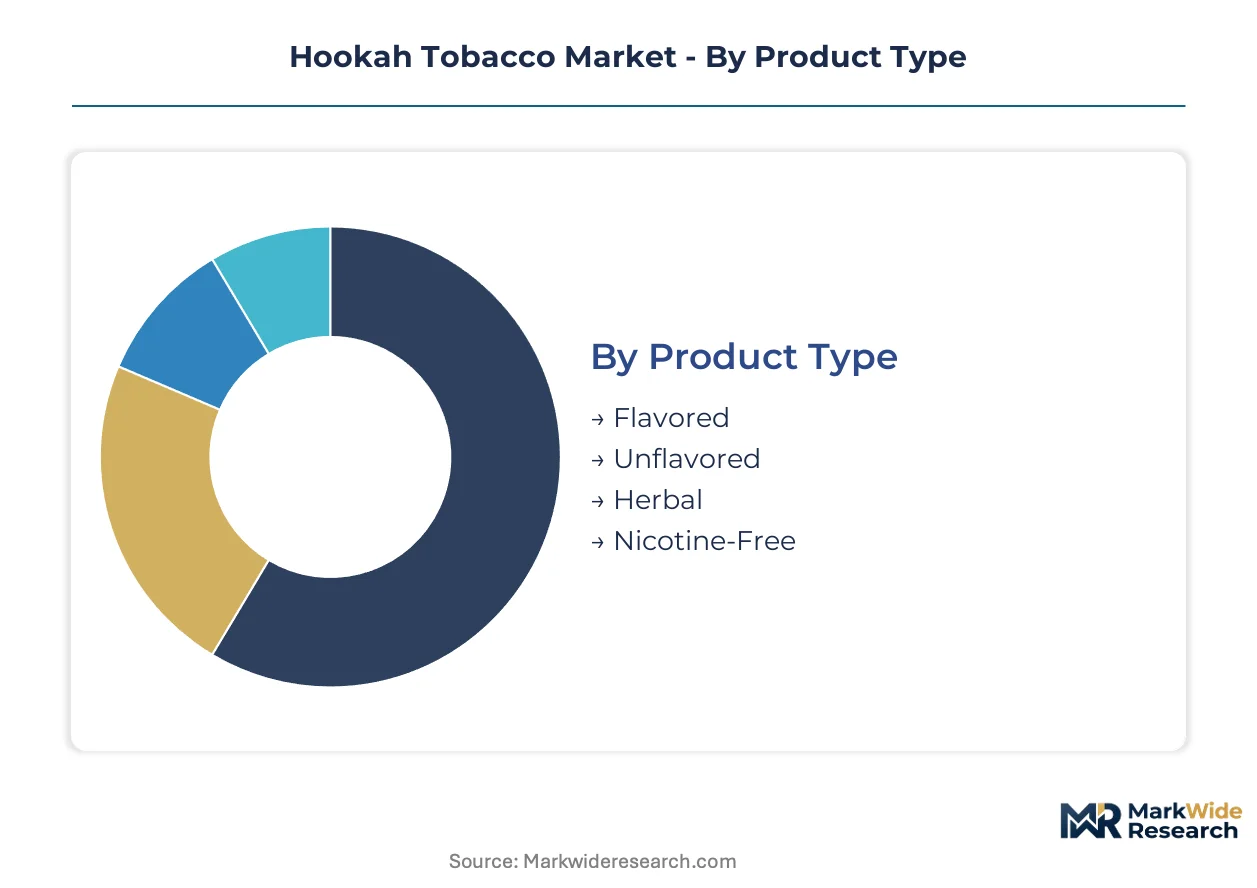
Hookah tobacco segmentation determines channel access and margin capture. Product formulation dictates regulatory pathway, while packaging format locks in distribution tier and price positioning.
Product Type:
Channel flow splits sharply: flavored and herbal variants reach lounges and specialty retailers, while unflavored bulk moves through traditional wholesale in price-sensitive markets.
- Flavored:Glycerin-molasses base infused with synthetic or natural extracts, heat-cured to 20-30% moisture content. Cairo, Dubai, and Istanbul lounges drive volume through extended-session consumption and menu engineering. Mint and fruit profiles command shelf space in German and French specialty channels navigating EU Tobacco Products Directive notification requirements.
- Herbal:Tobacco-free blends using sugar cane fiber, tea leaves, or fruit pulp as substrate, delivering comparable smoke density without nicotine. France ANSM guidance on non-tobacco inhalables opens pharmacy and convenience placement unavailable to nicotine-containing products, accelerating adoption in regulatory-constrained Benelux markets.
- Unflavored:Raw processed leaf with minimal additive load, targeting traditional consumers in Egypt and Levant markets where molasses blending is performed at point of use.
- Nicotine-Free:Synthetic nicotine alternatives or zero-nicotine herbal formulations, positioned for health-conscious segments in North American specialty retail.
By volume, Flavored leads. By growth pace, Herbal is expanding most quickly.
Material:
Cost tier stratification runs from commodity agricultural inputs to precision-blended formulation components.
- Tobacco Leaves:Zimbabwe and Malawi flue-cured varieties dominate input costs. Currency volatility in source markets transmits directly to finished goods pricing, squeezing margin for Egyptian manufacturers without backward integration into leaf procurement.
- Glycerin:Humectant agent controlling moisture release and smoke density. Pharmaceutical-grade vegetable glycerin separates premium formulations from industrial-grade bulk production.
- Molasses:Traditional binding agent and flavor carrier. Egyptian and Jordanian producers deploying continuous-mixing automation reduce batch-to-batch variability.
- Natural Extracts:Mint oils, fruit essences, and spice distillates. REACH chemical restrictions in Germany and France narrow approved additive lists, forcing reformulation investment or geographic portfolio rebalancing.
By margin contribution, Natural Extracts commands premium. By volume scale, Tobacco Leaves dominates.
Flavor Profile:
Application context determines profile selection: mint for refreshment in extended sessions, fruit for entry-level adoption, spices for traditional occasions.
- Mint:Menthol and spearmint variants providing cooling sensation and palate cleansing. Western European specialty retailers and North American lounges position mint as premium standard.
- Fruit:Apple, grape, watermelon, and mixed berry profiles. Entry-point choice for novice consumers in Indonesian and Vietnamese urban youth segments.
- Spices:Cardamom, cinnamon, and clove formulations. Traditional preference in Levant and Gulf markets for ceremonial consumption.
- Sweet:Dessert-inspired profiles including vanilla, caramel, and chocolate. Niche positioning in North American direct-to-lounge channels.
By revenue concentration, Mint leads. By adoption velocity in emerging markets, Fruit is climbing the fastest.
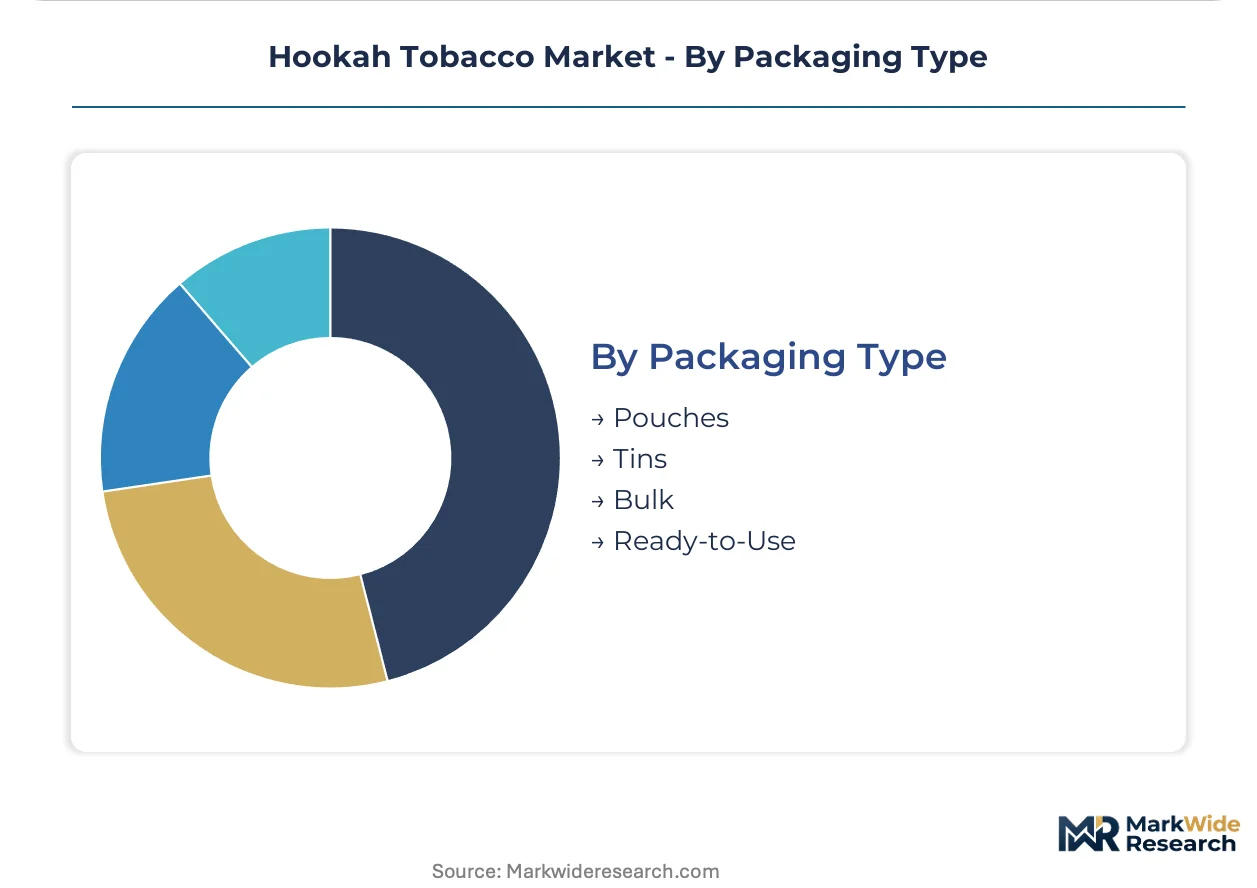
Packaging Type:
Customer type and purchase occasion split the packaging mix: ready-to-use formats for impulse and hospitality, bulk for price-sensitive traditional trade.
- Pouches:Flexible laminate bags with reseal closure, 50g-250g capacity. Volume leadership in Middle Eastern markets where price sensitivity dominates and wholesale tiers remain entrenched.
- Tins:Airtight metal containers preserving moisture and flavor integrity. Higher margin capture in Western European and North American specialty retail, with shelf differentiation and gift positioning.
- Bulk:Multi-kilogram formats for lounge operators and traditional wholesale. Lowest unit cost, minimal branding, concentrated in Egyptian and Levant distribution.
- Ready-to-Use:Pre-portioned single-serve packs with integrated heat-management accessories. Direct-to-lounge innovation in Saudi Arabia and UAE sovereign wealth-backed venue rollouts demanding single-source accountability.
By unit volume, Pouches dominates. By margin expansion, Ready-to-Use shows steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor notification deadlines under the EU Tobacco Products Directive are redrawing import access and shelf placement across Germany and France. Egypt's Ministry of Health standards and informal export channels absorb displaced volume while North American specialty retail tightens direct-to-lounge relationships.
Egypt
Traditional shisha culture sustains high per-capita consumption across Cairo and Alexandria social venues. The Ministry of Health maintains local manufacturing standards that informal producers navigate through documented quality gaps. Production clusters in Cairo's industrial zones supply both domestic lounges and gray-market export flows toward European distributors.
Germany
Specialty retailers in Berlin and Hamburg navigate EU Tobacco Products Directive flavor notification pathways with reformulated product lines. The Federal Institute for Risk Assessment (BfR) evaluates additive safety submissions, compressing timelines for smaller importers. Munich and Frankfurt distribution hubs consolidate toward early movers with secured authorizations before prohibition deadlines.
France
ANSM guidance on non-tobacco inhalables opens pharmacy and convenience placement for herbal alternatives unavailable to nicotine-containing products. Paris and Lyon lounges accelerate menu diversification toward tobacco-free substrates. Marseille and Nice wholesale tiers face inventory stranding risk from pending flavor prohibition implementation.
United States
FDA oversight of deemed tobacco products shapes formulation constraints and import documentation for specialty retail channels. California and New York metro lounges drive experiential hospitality adoption with extended-session menu engineering. Miami and Los Angeles direct-to-lounge relationships bypass traditional wholesale tiers through captive delivery networks.
United Arab Emirates
Dubai and Abu Dhabi hospitality corridors demand single-source accountability from sovereign wealth-backed venue rollouts. MOHAP standards regulate local manufacturing while Riyadh and Jeddah procurement consolidates toward exclusive supplier arrangements. Sharjah distribution hubs lose share to direct manufacturer-lounge contracts bundling product, device, and staff training.
Hookah Tobacco Market Key Industry Players
Player mix skews toward vertically integrated manufacturers and specialty flavor houses. Market structure concentrates around Egyptian production clusters serving Middle Eastern price-sensitive segments and European reformulation requirements. Two strategic archetypes dominate: backward-integrated leaf processors with captive glycerin-molasses blending capacity, and direct-to-lounge specialists controlling retail relationships through flavor innovation pipelines. Competitive moves center on ISO 9001 certification acquisition and exclusive venue procurement contracts.
Within the integrated manufacturing tier, Al Fakher Tobacco Trading and Nakhla Tobacco exemplify archetypes with upstream control over leaf sourcing and finished pouch production. Starbuzz Tobacco Inc. occupies a position among North American direct-to-lounge specialists. These three anchors illustrate how geographic origin and distribution model differentiation separate cost-driven volume players from margin-capturing relationship holders.
| Leading Market Players |
|---|
| Al Fakher Tobacco Trading |
| Starbuzz Tobacco Inc. |
| Fumari Inc. |
| Social Smoke Inc. |
| Haze Tobacco LLC |
| Japan Tobacco Inc. |
| Nakhla Tobacco |
| Cloud Tobacco Inc. |
| Tangiers Tobacco |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts with Zimbabwe and Malawi leaf suppliers lock in raw material access and cost visibility for Egyptian manufacturers serving European importers. These arrangements insulate organized producers from currency volatility while informal competitors absorb spot-market price swings.
Pricing Analysis
Cost-plus contracts indexed to flue-cured tobacco commodity benchmarks dominate procurement between Egyptian manufacturers and European distributors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified tins from uncertified pouches and bulk formats. Pricing pressure stems from REACH compliance costs in Germany and France, where reformulation investment compresses margins for mid-tier importers. Lounge operators in Dubai and Riyadh show lowest price sensitivity, while price-sensitive wholesale tiers in Cairo and Alexandria drive volume through pouch formats.
Supply Chain Analysis
Suez Canal transit underwrites delivery reliability for Egyptian production clusters exporting to European specialty retailers. Raw material sourcing draws from Zimbabwe and Malawi flue-cured tobacco, pharmaceutical-grade vegetable glycerin from European chemical houses, and molasses from regional sugar processors. Single-source vulnerability concentrates in leaf supply, where currency devaluation in source markets transmits directly to finished goods pricing. Distribution runs through Dubai and Cairo wholesale hubs for Middle Eastern price-sensitive segments, while direct-to-lounge contracts bypass traditional tiers in Saudi Arabia and UAE urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic heat-not-burn devices pose a substitution threat that tobacco-based shisha incumbents must navigate through reformulation partnerships and hardware co-development.
For Market Incumbents: Consolidate exclusive supplier arrangements with sovereign wealth-backed lounge rollouts in Riyadh and Jeddah to lock in volume-commitment pricing. Deepen backward integration into leaf procurement in Zimbabwe and Malawi to mitigate currency exposure. Prioritize ISO 9001 certification acceleration for Egyptian production clusters before European importer mandate deadlines. For New Entrants and Emerging Players: Lead with herbal and nicotine-free formulations targeting France ANSM-guided pharmacy and convenience placement unavailable to tobacco competitors. Target underpenetrated Indonesian and Vietnamese urban youth segments where fruit-profile adoption runs ahead of local manufacturing presence. Deploy direct-to-lounge distribution bundling product, device, and staff training to bypass entrenched wholesale tiers. For Investors and Strategic Acquirers: Direct-to-lounge specialists with captive venue relationships and flavor innovation pipelines represent the most defensible acquisition archetype in a market restructuring toward experiential hospitality. Long-term viability hinges on regulatory arbitrage capability between flavor-constrained European markets and less restricted demand centers. Monitor Netherlands and Belgium prohibition implementation timelines as inventory stranding inflection indicators for distributor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Acceleration | Quality system documentation unlocks European import access before flavor notification deadlines. |
| Direct-to-Lounge Distribution Buildout | Captive delivery networks in Saudi Arabia and UAE capture margin and consumption data. |
| Herbal Formulation R&D Investment | France ANSM guidance opens pharmacy placement unavailable to nicotine-containing products. |
| Heat Device Co-Development Partnership | Electronic heating system integration demands reformulation science outside traditional tobacco supply relationships. |
| Backward Integration into Leaf Procurement | Zimbabwe and Malawi sourcing control insulates margin from currency volatility transmission. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with lounge procurement managers, Egyptian manufacturing plant directors, European specialty retail buyers, and flavor chemists at extraction houses. Secondary validation drew from EU Tobacco Products Directive notification databases, Egypt Ministry of Health manufacturing standards, FDA deemed product guidance, and trade flow records through Dubai and Cairo customs authorities. Bottom-up volume modeling triangulated against top-down market sizing across flavored, herbal, unflavored, and nicotine-free product categories.
Across the analysis window, forecasts reflect segmentation by product type, packaging format, flavor profile, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by policy trajectory assessment. Key inputs included flavor prohibition timeline probabilities in core European markets, heat device adoption curves in North American specialty retail, and lounge venue rollout schedules in Gulf sovereign wealth portfolios.
The analysis sits within stated boundaries; outcomes outside EU Tobacco Products Directive implementation schedules, Egypt Ministry of Health enforcement intensity, or heat device technology diffusion rates would require recalibration. Practitioners should keep alternative scenarios live as flavor ban expansions and electronic heating system partnerships evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Profilometer Market
Others
Global Computer Peripherals Market
Others
Global Optical Comparator Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Germany Smart Home Market
Others
Industrial Tablet PC Market
Others
Coalescing Filter Market
Others
Europe Smart Homes Market
Others
Cathode Battery Material Market
Others
Human Enhancement Technology Market
Others
Middle East 3D Printing Construction Market
Others
Industrial Hooters Market
Others
Stand-Up Pouch Valves Market
Others
South Asia Geosynthetics Market
Others
Consumer Video Feedback Software Market
Others
Medical Simulation Market