
 Surgical Sealant and Adhesive Market | 2026-2036
Surgical Sealant and Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Sealant and Adhesive Market Intelligence
Performance in hemostasis and biocompatibility is decoupling the market into high-specification biologic sealants and commodity-level synthetic adhesives. Johnson & Johnson (Ethicon) leverages its extensive clinical trial data to command premium pricing in complex surgical applications. Baxter International specializes in fibrin and synthetic sealants for a wide range of procedures, focusing on ease of use. Medtronic differentiates with its portfolio for spinal and orthopedic surgeries, integrating sealants with its device offerings.
Surgical sealants and adhesives are biomaterials designed to control bleeding, seal tissue, or close wounds without traditional sutures or staples. These products often feature specific polymerization times and bond strengths tailored to different tissue types, such as vascular or dermal. Biologic sealants, particularly fibrin-based products, command the highest value due to their efficacy in critical hemostasis applications. Hospitals remain the dominant end-user segment, driven by the volume of surgical procedures performed.
Market access hinges on stringent regulatory approvals from bodies like the US FDA, Europe's EMA, and China's NMPA, which mandate extensive preclinical and clinical data. These regulations ensure product safety and efficacy, creating high barriers to entry for new formulations. The key decision for manufacturers is whether to invest in novel biodegradable polymers or optimize existing cyanoacrylate and fibrin platforms for new surgical indications.
Market Dynamics
The market's central dynamic is the performance-driven split between high-specification biologic sealants and commodity synthetic adhesives. This bifurcation is driven by the increasing complexity of minimally invasive surgeries and regulatory demands for procedure-specific efficacy data.
Growth Catalysts
- Minimally Invasive Techniques:The shift towards laparoscopic and robotic-assisted surgeries, particularly in cardiovascular and general surgery, necessitates advanced sealants for hemostasis in confined spaces, bypassing the need for traditional sutures.
- Aging Demographics:Advanced economies like Germany and Japan have aging populations with higher incidences of chronic diseases, leading to a greater volume of surgical procedures, especially in orthopedic and cardiovascular applications.
- Regulatory Pathways:The US FDA's 510(k) clearance pathway allows for faster market entry for new synthetic adhesives that demonstrate substantial equivalence to existing, legally marketed devices, encouraging incremental innovation.
Market Restraints
- Cost Containment Pressures:Hospital budgets in many public healthcare systems place significant pressure on the adoption of premium-priced biologic sealants, such as fibrin-based products, favoring lower-cost synthetic alternatives for routine procedures.
- Technical Limitations:Certain cyanoacrylate-based adhesives face limitations in dynamic and high-moisture environments, such as lung tissue, due to their brittle nature and potential for cytotoxic reactions, restricting their use.
- Regulatory Scrutiny:Stringent data requirements from regulatory bodies like the European Medicines Agency (EMA) for novel biomaterials create long and expensive development cycles, acting as a significant barrier to entry.
Strategic Opportunities
- Application-Specific Formulations:There is a significant opportunity in developing sealants with tailored properties, such as specific polymerization times and bond strengths, for underserved specialties like neurosurgery and ophthalmic surgery.
- Biodegradable Polymers:Investment in novel biodegradable polymers offers a pathway to create next-generation products that provide temporary support before being safely absorbed by the body, eliminating the need for removal.
- Emerging Market Penetration:As healthcare infrastructure improves in markets like Brazil and India, there is a growing opportunity to introduce mid-tier synthetic sealants to address the rising volume of surgical procedures.
Industry Challenges
- Divergent Regulatory Frameworks:Manufacturers face complexity and increased costs in generating clinical data that simultaneously satisfies the distinct requirements of the US FDA, Europe's MDR, and China's NMPA.
- Surgeon Training and Adoption:Ensuring surgeons are adequately trained on the precise application techniques for new sealants is critical to achieving optimal outcomes and avoiding product failure or patient complications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Sealant and Adhesive Market |
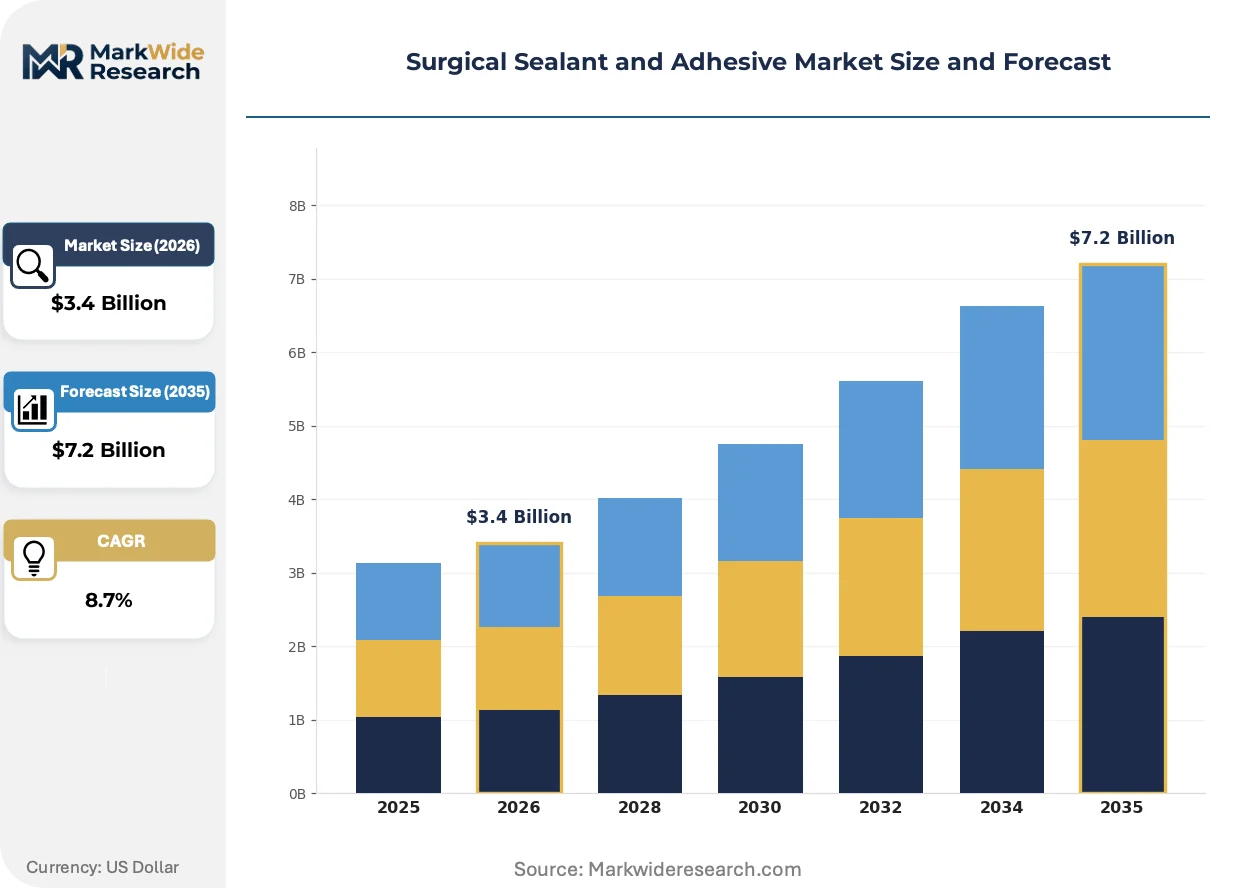
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologic Sealants, Synthetic Adhesives, Natural Polymers, Surgical Tapes End User: Hospitals, Outpatient Surgery Centers, Specialty Clinics, Rehabilitation Facilities Application: Wound Closure, Tissue Engineering, Hemostasis, Surgical Procedures Technology: Hydrogel, Cyanoacrylate, Fibrin, Silicone |
| Companies Covered | Johnson & Johnson (Ethicon), Baxter International, Becton Dickinson and Company, Medtronic, B. Braun Melsungen AG, CryoLife (Artivion), Integra LifeSciences, Cohera Medical, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Sealant and Adhesive Market Strategic Shifts & Innovations
The convergence of material science with specific surgical needs is defining the next generation of sealants. Innovation focuses on enhancing biocompatibility and creating products that actively participate in the healing process rather than just providing mechanical closure.
Bio-absorbable polymers and advanced hydrogels are gaining traction as primary materials for next-generation sealants. Surgical teams in orthopedic and soft tissue repair are adopting these materials for their ability to conform to irregular surfaces and degrade at a predictable rate. This technology is absorbing the function of traditional sutures in delicate procedures, enabling more complex repairs with reduced foreign body response.
Europe's Medical Device Regulation (MDR) is fundamentally changing market access and product lifecycle management. The regulation imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices, including established sealant products. Consequently, manufacturers of fibrin and synthetic sealants are compelled to conduct new clinical investigations to maintain their CE marking for access to the European market.
Hospital value analysis committees are increasingly influencing purchasing decisions, shifting focus from product price to total cost of care. This trend disrupts traditional sales models that relied on relationships with individual surgeons, forcing suppliers to demonstrate economic value through reduced operating time or lower complication rates. This shift is most pronounced in large, integrated delivery networks within the United States.
Surgical Sealant and Adhesive Market Segmentation
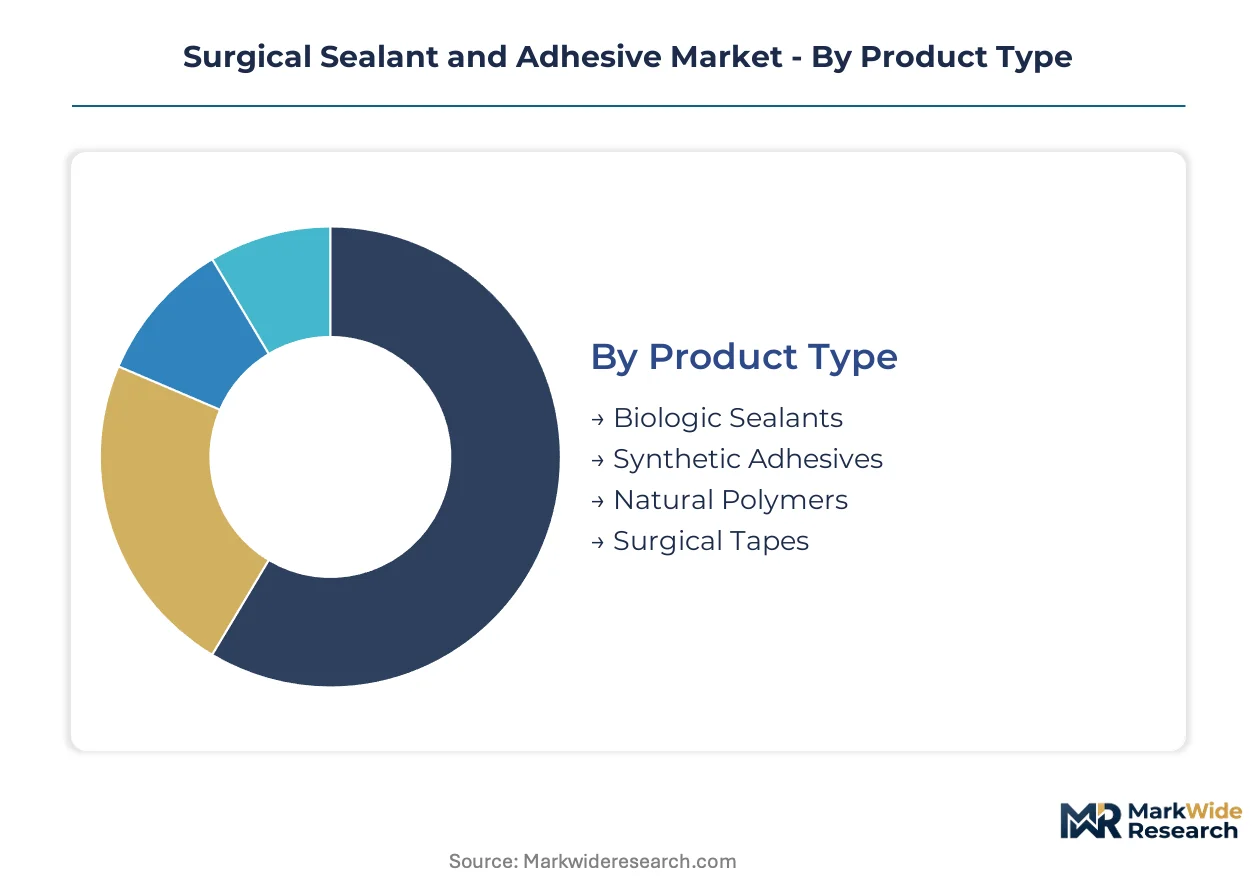
Segmentation analysis provides a granular understanding of the surgical sealant and adhesive market, revealing how diverse product types, end-users, applications, and technologies contribute to overall market dynamics. This breakdown helps stakeholders identify specific growth pockets and strategic investment areas within the evolving healthcare landscape.
Product Type:
The upgrade cycle within surgical sealants and adhesives often dictates material selection and performance requirements across various surgical disciplines.
- Biologic Sealants:These products are derived from biological sources, primarily fibrin, offering superior hemostasis and tissue sealing through natural clotting mechanisms. Demand concentrates in complex cardiovascular and neurosurgical procedures where biocompatibility and rapid action are paramount, commanding premium pricing due to their high efficacy.
- Synthetic Adhesives:Composed of synthetic polymers like cyanoacrylates or polyethylene glycols, these sealants provide strong mechanical bonds and are often more cost-effective than biologic alternatives. Procurement patterns in developed medical markets like Germany favor these for routine procedures, balancing cost containment with reliable performance.
- Natural Polymers:This category includes products based on collagen, gelatin, or albumin, utilized for their biocompatibility and biodegradability in various surgical settings. These polymers often serve as adjuncts to traditional closure methods.
- Surgical Tapes:Non-invasive adhesive strips used for superficial wound closure and securing dressings, providing a less invasive alternative to sutures for minor incisions. These are widely adopted in outpatient settings.
Synthetic Adhesives sits at the top of the volume ranking, with Biologic Sealants climbing the fastest.
End User:
Different customer types within the healthcare ecosystem exhibit distinct procurement patterns and demand profiles for surgical sealants.
- Hospitals:These institutions represent the dominant end-user segment, driven by the high volume and complexity of surgical procedures performed across various specialties. Hospital value analysis committees increasingly influence purchasing decisions, prioritizing products demonstrating total cost of care benefits.
- Outpatient Surgery Centers:These facilities focus on minimally invasive procedures, driving significant demand for advanced sealants that facilitate faster patient recovery and reduced hospital stays. The shift towards ambulatory care in the United States particularly fuels this segment's expansion.
- Specialty Clinics:Clinics specializing in areas like ophthalmology or dermatology utilize specific sealants and adhesives tailored to their precise procedural requirements. These clinics often seek products with minimal scarring properties.
- Rehabilitation Facilities:While not primary users of surgical sealants for initial closure, these facilities may utilize adhesives for wound care management and securing medical devices post-surgery. Their demand is typically for less complex, wound-dressing type adhesives.
Hospitals continue to drive the largest share of demand, while outpatient surgery centers present a rapidly expanding segment.
Application:
Specific surgical applications dictate the required performance characteristics, such as polymerization time and bond strength, for sealants and adhesives.
- Hemostasis:This critical application focuses on controlling bleeding during and after surgical procedures, particularly in high-risk interventions like cardiovascular surgery. Biologic sealants, especially fibrin-based products, are highly valued here for their efficacy.
- Surgical Procedures:This broad application encompasses the use of sealants and adhesives across a wide array of surgeries, including general, orthopedic, and neurological interventions, for tissue approximation and leak prevention. The increasing complexity of robotic-assisted surgeries necessitates specialized formulations.
- Wound Closure:Sealants and adhesives offer an alternative to traditional sutures and staples for closing surgical incisions and traumatic wounds, particularly where cosmetic outcomes are important. These products reduce procedure time.
- Tissue Engineering:In this advanced application, sealants are used as scaffolds or matrices to support cell growth and tissue regeneration, often involving novel biodegradable polymers. This area is characterized by significant research and development investment.
Hemostasis remains a critical application driving innovation in high-specification biologic sealants, with surgical procedures encompassing the broadest usage.
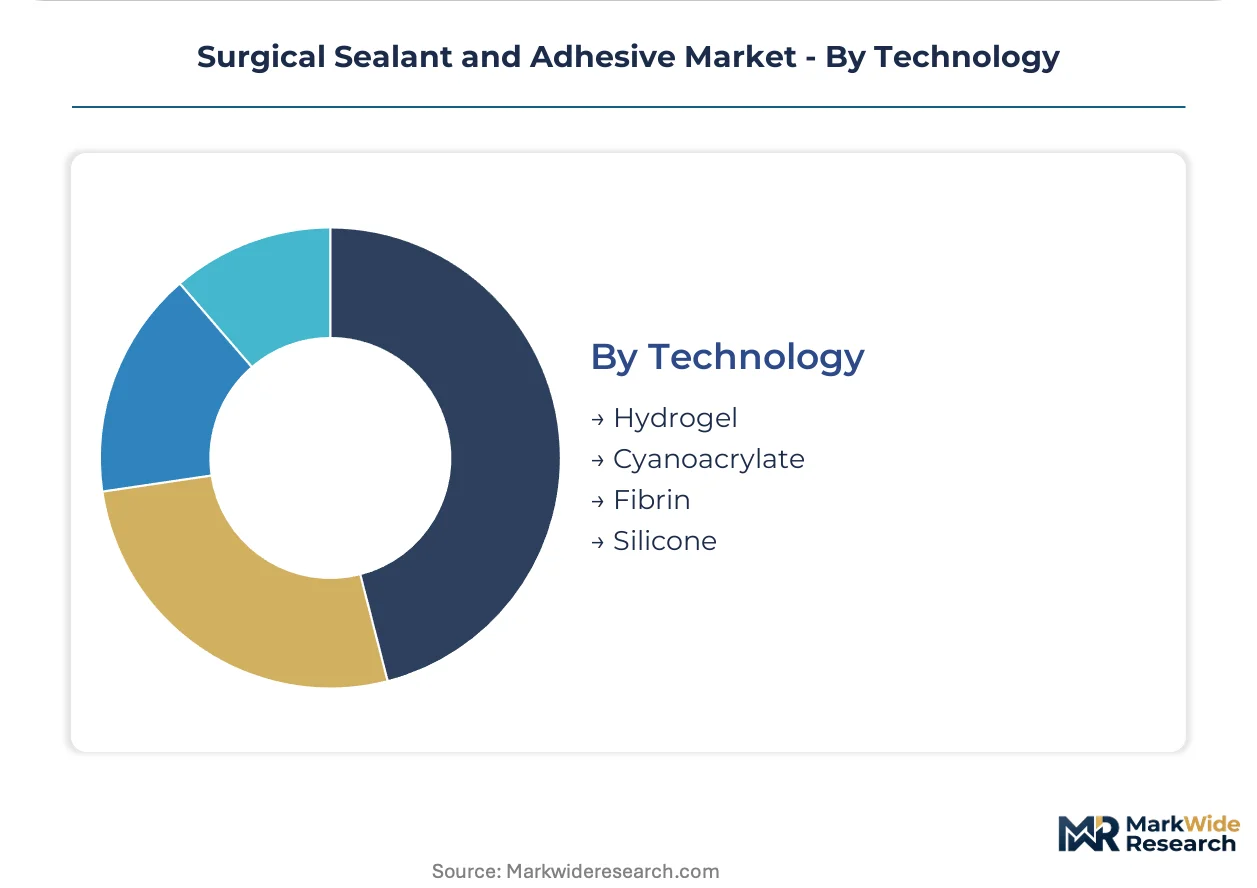
Technology:
Advancements in material science continue to redefine the capabilities and biocompatibility of various sealant technologies.
- Hydrogel:These water-based polymer networks offer excellent biocompatibility and flexibility, making them suitable for sealing tissues in dynamic and high-moisture environments. Novel hydrogels are gaining traction in orthopedic and soft tissue repair due to their conformability.
- Cyanoacrylate:Known for their rapid polymerization and strong adhesive properties, cyanoacrylate-based products are widely used for skin closure and certain internal applications. Regulatory bodies like the US FDA have approved various formulations for medical use.
- Fibrin:Derived from human plasma, fibrin sealants mimic the body's natural clotting cascade, providing effective hemostasis and tissue sealing. Their high efficacy in critical applications, such as cardiovascular surgery, drives their premium value.
- Silicone:Silicone-based adhesives are often used in medical devices and external applications due to their inertness and flexibility. They provide a durable bond for various medical and surgical accessories.
Fibrin-based technologies command premium pricing for critical uses, while cyanoacrylate platforms offer broad utility across numerous surgical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled medical professionals and robust research ecosystems anchor regional demand for surgical sealants. These biomaterials are critical for advanced surgical techniques, particularly in developed economies with aging populations. Emerging markets also show significant growth as healthcare infrastructure expands.
United States
Demand for advanced hemostasis products stems from complex cardiovascular and orthopedic surgeries. The US FDA's 510(k) clearance pathway facilitates market entry for novel synthetic adhesives. Biomedical hubs in Boston and California drive innovation in biodegradable polymers and hydrogel formulations.
Germany
An aging demographic and a preference for minimally invasive procedures boost sealant consumption. Europe's EMA and MDR regulations mandate stringent clinical evidence for market access. Medical technology clusters in Bavaria and North Rhine-Westphalia specialize in high-specification biologic sealants.
Japan
High surgical volumes, particularly in oncology and cardiovascular fields, sustain strong demand for sealants. The PMDA ensures product safety and efficacy through rigorous approval processes for medical devices. Tokyo and Osaka serve as centers for innovation in fibrin-based technologies and application-specific formulations.
China
Expanding healthcare access and increasing patient numbers drive the need for surgical adhesives. The NMPA's regulatory framework supports domestic production while scrutinizing imported medical devices. Manufacturing centers in the Yangtze River Delta focus on scaling production of cost-effective synthetic sealants.
India
Growing surgical procedures and rising healthcare expenditure contribute to sealant market expansion. The CDSCO regulates medical device approvals, balancing patient safety with market accessibility. Bengaluru and Hyderabad are emerging as hubs for medical device R&D, including advanced biomaterials.
Surgical Sealant and Adhesive Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the surgical sealant market. The market structure exhibits a tiered consolidation, with large diversified medical device companies alongside specialized biomaterial innovators. Strategic archetypes include global conglomerates with broad portfolios, niche specialists focusing on specific surgical applications, and regional manufacturers emphasizing cost efficiency. Portfolio diversification and strategic partnerships are dominant competitive moves.
Global conglomerates, like Johnson & Johnson (Ethicon), anchor the premium segment with extensive product lines and robust clinical data. These companies represent integrated offerings across various surgical disciplines, leveraging their established hospital relationships. Medtronic, another major player, exemplifies a diversified medical technology company, integrating sealants within its broader device portfolio for specialized areas like spinal and orthopedic surgeries. Baxter International, meanwhile, occupies a position as a specialist in fibrin and synthetic sealants, focusing on broad procedural applicability and ease of use across a wide range of medical settings.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Baxter International |
| Becton Dickinson and Company |
| Medtronic |
| B. Braun Melsungen AG |
| CryoLife (Artivion) |
| Integra LifeSciences |
| Cohera Medical |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists shape the surgical sealant market by influencing both specialized biomaterial supply and premium pricing strategies. This ownership structure often dictates investment in R&D and market access.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing for surgical sealants, particularly in integrated hospital systems. Per-unit transactional pricing dominates for commodity synthetic adhesives, while value-based pricing applies to high-specification biologic sealants. Price differentiation stems from robust clinical efficacy data and stringent regulatory approval tiers like US FDA clearance. Pricing pressure in routine procedures arises from hospital cost containment, favoring lower-cost synthetic alternatives; outpatient surgery centers are highly price-sensitive, contrasting with critical care departments prioritizing clinical outcomes.
Supply Chain Analysis
Reverse-logistics for surgical sealants primarily involves managing expired product returns and ensuring proper disposal of biohazardous materials. Supply concentration for advanced biomaterials centers in the United States, Germany, and Japan, leveraging their robust R&D infrastructure. Raw material dependencies include human plasma for fibrin sealants and specialized polymers for synthetic adhesives, creating single-source vulnerability for critical biologic components. Downstream distribution relies heavily on established medical device distributors and direct sales forces to hospitals and outpatient centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical sealant and adhesive market acts as a stable compounder, driven by the continuous demand for advanced hemostasis solutions in an aging global population. This consistent need underpins long-term investment viability.
For Market Incumbents: Extend clinical data generation for existing high-specification biologic sealants to counter emerging synthetic adhesive competition. Deepen partnerships with integrated delivery networks to secure formulary positions against cost containment pressures. Invest in novel biodegradable polymers, a key R&D lever, to differentiate product portfolios. This proactive strategy defends market share from asset-light designers and strengthens established hospital relationships.
For New Entrants and Emerging Players: Online professional education platforms offer a direct route to surgeons, bypassing traditional sales channels for novel application-specific formulations. Target underserved specialties like neurosurgery and ophthalmic surgery, where specific polymerization times are critical. Focus on emerging markets, such as India, to introduce mid-tier synthetic sealants. A value-driven go-to-market angle, emphasizing ease of use and consistent performance, facilitates rapid adoption in these expanding healthcare infrastructures.
For Investors and Strategic Acquirers: Large medical device conglomerates are the most active acquirers in this space, seeking to consolidate specialized biomaterial innovators over a 5-10 year window. Target acquisition archetypes include firms with novel biodegradable polymer platforms or unique application-specific formulations for neurosurgery. The long-term viability of this market remains strong, supported by persistent surgical demand. Monitor regulatory shifts from bodies like the EMA for early signals of market access changes or new clinical evidence requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Data Expansion | Strengthening clinical evidence for biologic sealants supports premium pricing and regulatory compliance with EMA standards. |
| Biodegradable Polymer R&D | Investing in novel biodegradable polymers creates next-generation products for orthopedic and soft tissue repair applications. |
| Emerging Market Entry | Penetrating markets like Brazil and India expands volume for mid-tier synthetic sealants in growing healthcare systems. |
| Application-Specific Formulation | Developing tailored sealants for neurosurgery and ophthalmology addresses unmet needs and captures niche market segments. |
| Hospital Value Committee Engagement | Demonstrating total cost of care benefits secures formulary adoption within large US integrated delivery networks. |
Research Approach
Direct dialogue with R&D directors, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads formed the primary research foundation. This qualitative grounding combined with extensive secondary validation from sources like US FDA filings, EMA submissions, and hospital purchasing databases. The study employed a rigorous bottom-up and top-down triangulation approach, cross-referencing data points for accuracy. This comprehensive methodology ensures robust market insights.
Market volume and value projections emerged from a proprietary analytical framework applied across the analysis window. The model segmented data by product type, end-user, application, technology, and tissue type. Compound annual growth rates were derived through a regression analysis of historical trends and projected future demand. Key forecast inputs included surgical procedure volumes and regulatory approval timelines for novel biomaterials.
The model assumes a particular technology adoption path; alternative pathways for advanced hydrogels would alter the outlook. Forecasts reflect assumptions about healthcare policy and surgical innovation; geopolitical events or unforeseen regulatory changes represent key risk factors. Practitioners should monitor clinical trial outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Colon Decompression Kits Market
Medical Supplies
Luer Plug Market
Medical Supplies
Medical Shoe Covers Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Global Hemostats Market
Medical Supplies
Medical Gas Market
Medical Supplies
Arthroscopy Fluid Management Disposables Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Dehydrated Culture Media Market
Medical Supplies
Skin Tac Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Wash Bottle Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Blood Processing Disposables Market
Medical Supplies
Port Access Needles Market