
 Scalp Care Treatment Market | 2026-2036
Scalp Care Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Scalp Care Treatment Market Insights
Botanical extracts and fermented actives are consolidating position as the dominant efficacy platform in premium scalp formulations, displacing conventional surfactant-heavy bases. L'Oréal leverages its dermatological research pipeline to anchor professional-grade scalp protocols across salon and clinic channels. Unilever competes through mass-market accessibility while extending its sustainable sourcing claims into scalp-specific ranges. Shiseido dominates in East Asian markets with fermented ingredient expertise that positions its scalp portfolio in the medical-aesthetic crossover segment.
Scalp care treatment encompasses topical formulations engineered to restore microbiome balance, regulate sebum production, and address follicular inflammation through targeted delivery systems such as liposomal encapsulation or pH-optimized bases. The category serves both cosmetic maintenance and adjunct therapeutic purposes alongside dermatological interventions for conditions ranging from seborrheic dermatitis to androgenetic alopecia. Shampoos and serums capture divergent margin structures, with rinse-off formats facing commodity pressure while leave-in serums command premium positioning through concentrated active loading. Natural extracts and botanicals are gaining formulation share fastest, though synthetic compounds retain cost advantages in mass-market dandruff applications where zinc pyrithione and ketoconazole remain reference standards.
The FDA oversees scalp treatment claims through its cosmetic-drug boundary framework, with any anti-dandruff or hair growth positioning triggering OTC drug or NDA pathways that extend development timelines. ECHA's REACH protocols govern preservative and surfactant approvals in Europe, while the EU Green Deal's chemical sustainability targets are accelerating biodegradable surfactant transitions across supplier networks. China's NMPA and GB standards impose separate registration requirements for imported scalp products containing medicinal claims, fragmenting market access protocols. Stakeholders must monitor regulatory divergence between cosmetic and quasi-drug classifications as jurisdictions tighten evidentiary standards for scalp-specific efficacy assertions.
Market Dynamics
The EU's microplastic ban under REACH protocols is forcing a wholesale reformulation of rinse-off scalp products toward biodegradable surfactant systems, compressing legacy supply chains while opening premium positioning for compliant alternatives.
Growth Catalysts
- Professional salon channel expansion:Trichology clinics across the United States are normalizing scalp health as a distinct treatment category, pulling clinical-grade protocols into mainstream service menus.
- REACH chemical sustainability targets:ECHA's phased restrictions on persistent surfactants are accelerating supplier transitions to biodegradable alternatives, creating first-mover advantages for compliant formulators.
- Fermented active platforms:East Asian biotech expertise in postbiotic extraction is consolidating efficacy claims in the medical-aesthetic crossover segment, displacing conventional botanical extracts.
Market Restraints
- Regulatory pathway fragmentation:The FDA's cosmetic-drug boundary framework triggers OTC drug or NDA requirements for anti-dandruff positioning, extending development timelines by 18-36 months versus standard cosmetic registration.
- Active ingredient concentration costs:Liposomal encapsulation systems and pH-optimized delivery bases carry 3-5x raw material premiums over conventional surfactant formulations, compressing mass-market margins.
- Preservative approval bottlenecks:ECHA's evolving REACH protocols for novel preservative systems create supplier concentration risk among established European chemical houses.
Strategic Opportunities
- Trichology-dermatology integration:Adjunct therapeutic positioning alongside androgenetic alopecia interventions opens reimbursement-adjacent revenue streams in clinical channels.
- China's quasi-drug registration pathway:NMPA's separate framework for scalp products with medicinal claims creates premium positioning for compliant entrants willing to navigate 24-48 month approval timelines.
- Leave-in serum format expansion:Concentrated active loading in non-rinse formats commands 4-6x unit economics versus commodity shampoos, with salon retail and direct-to-consumer channels capturing margin expansion.
Industry Challenges
- Microbiome claim substantiation:Evidentiary standards for scalp-specific efficacy assertions are tightening across FDA, ECHA, and NMPA jurisdictions, requiring clinical endpoint data that extends R&D cycles.
- Surfactant supply reconfiguration:Biodegradable alternative sourcing requires backward integration into oleochemical supply chains or captive partnerships with renewable feedstock processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scalp Care Treatment Market |
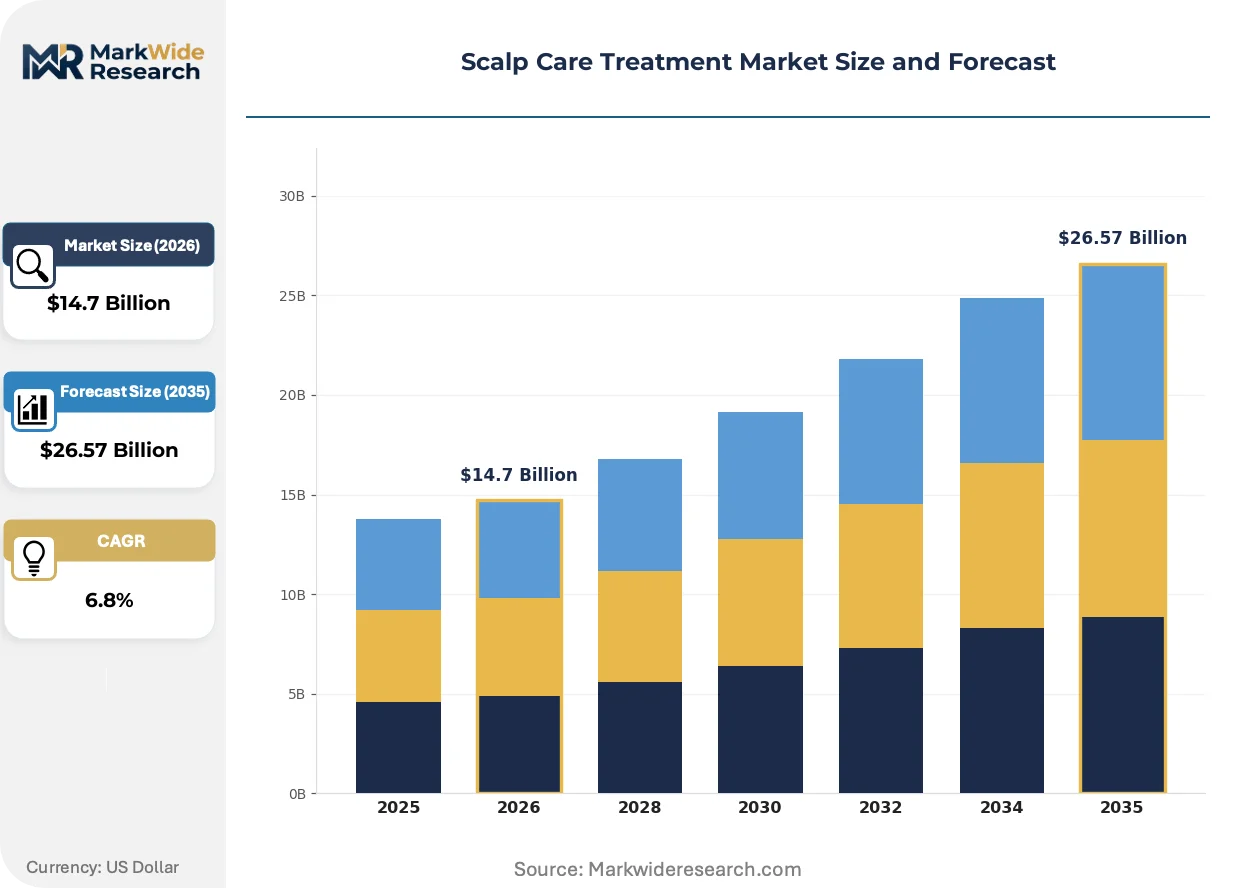
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Serums, Masks Ingredient Type: Natural Extracts, Synthetic Compounds, Essential Oils, Botanicals Target Concern: Dandruff, Dry Scalp, Oily Scalp, Hair Thinning End User: Men, Women, Children, Professionals |
| Companies Covered | L'Oréal, Unilever, Procter & Gamble, Johnson & Johnson, Beiersdorf, Kérastase, Briogeo, Shiseido, Christophe Robin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scalp Care Treatment Market Trends and Innovations
Fermentation-derived postbiotics and precision delivery systems are consolidating as the dominant efficacy platform, while regulatory chemistry restrictions and channel fragmentation reshape competitive positioning across professional and retail segments.
Liposomal encapsulation technology is integrating ceramide and peptide actives into scalp serum formulations, enabling targeted follicular penetration previously limited to pharmaceutical topical applications. Premium salon brands and trichology clinics are adopting these systems at accelerating pace, displacing conventional rinse-off formats in high-margin service protocols. The technology is integrating clinical credibility into cosmetic positioning, compressing the historical gap between dermatological intervention and maintenance care.
REACH microplastic restrictions and the EU Green Deal's chemical sustainability targets are prohibiting synthetic polymer beads and certain acrylate thickeners in rinse-off cosmetics by 2030. European formulators are accelerating biodegradable surfactant transitions, with supplier networks restructuring around oleochemical and fermentation-derived alternatives. Leave-in treatment formats face lighter regulatory burden, shifting R&D investment toward serum and tonic categories.
Direct-to-consumer subscription models are capturing recurring revenue in scalp maintenance regimens, displacing traditional retail dependence for premium serum brands. Clinically-positioned entrants are bypassing salon distribution entirely, leveraging tele-dermatology partnerships and at-home diagnostic tools to build treatment adherence. This channel disintermediation concentrates in the United States, where trichology-informed marketing and influencer credibility reduce reliance on professional recommendation.
Scalp Care Treatment Market Segmentation
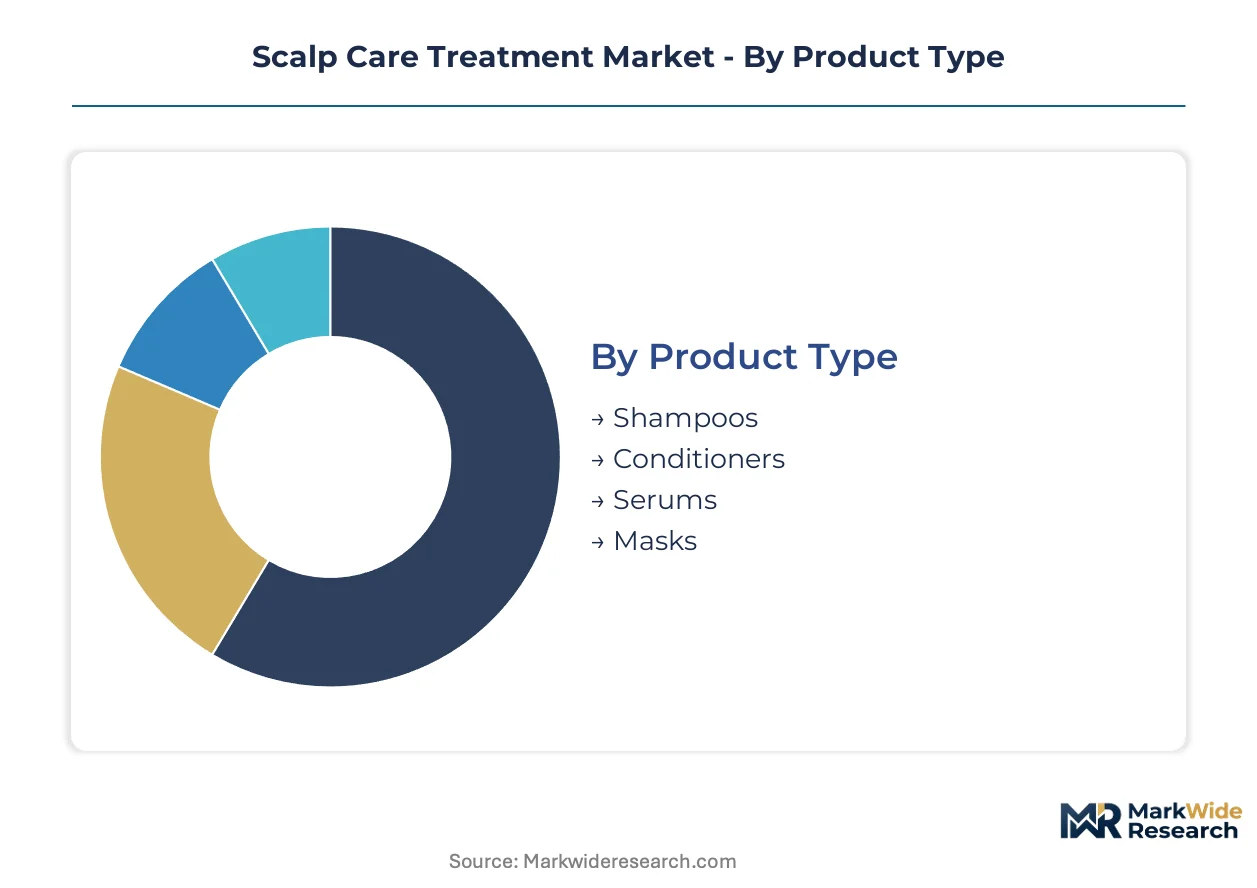
Scalp care treatment markets fragment across formulation chemistry, clinical positioning, and channel economics. Product architecture determines margin capture, while ingredient sourcing drives regulatory compliance costs. Understanding these axes reveals where value concentrates versus where volume commoditizes.
Product Type:
Delivery system technology separates rinse-off formats from leave-in treatments, with encapsulation and pH-optimization capabilities clustering in serum and mask categories.
- Shampoos:Rinse-off surfactant bases face commodity pressure in mass retail, though zinc pyrithione and ketoconazole formulations retain clinical reference status in anti-dandruff positioning. Demand concentrates in United States drugstore channels where FDA OTC monograph compliance creates formulation barriers for new entrants.
- Serums:Liposomal encapsulation enables concentrated active loading with follicular penetration previously limited to pharmaceutical applications. Premium salon and trichology clinic channels in the United States capture margin expansion through clinical-grade protocols that displace conventional maintenance products.
- Conditioners:Secondary rinse-off format with lower active loading requirements; cationic surfactant bases dominate cost-optimized mass market positioning.
- Masks:Periodic intensive treatment format with clay or cream bases; professional service integration drives adoption in salon channels.
Shampoos lead on scale; serums lead on momentum.
Ingredient Type:
Raw material sourcing strategy divides between petroleum-derived cost efficiency and biotechnology-enabled premium positioning, with regulatory chemistry restrictions accelerating transitions.
- Natural Extracts:Fermentation-derived postbiotics and botanical actives command formulation share in premium segments. East Asian biotech supply chains dominate extraction expertise, with Shiseido's medical-aesthetic crossover positioning exemplifying efficacy claims architecture.
- Synthetic Compounds:Zinc pyrithione, ketoconazole, and salicylic acid retain cost advantages in mass-market dandruff applications where FDA OTC drug pathways standardize active concentrations.
- Essential Oils:Terpene-based formulations face ECHA REACH preservative scrutiny; concentration limits fragment European versus Asian market access.
- Botanicals:Plant-derived surfactants and extracts accelerate as EU microplastic bans force biodegradable alternatives; oleochemical supply chain restructuring creates sourcing concentration risk.
Synthetic compounds lead on scale; natural extracts gain share fastest.
Target Concern:
Clinical credibility requirements vary sharply across dermatological condition severity, with hair thinning positioning triggering the most stringent evidentiary standards.
- Hair Thinning:Androgenetic alopecia adjacency requires trichology-dermatology integration; reimbursement-adjacent clinical channels in the United States concentrate demand for peptide and ceramide formulations with follicular penetration claims.
- Dandruff:Seborrheic dermatitis maintenance spans cosmetic-drug boundary; FDA OTC monograph compliance enables mass-market access while limiting differentiation.
- Dry Scalp:Barrier repair positioning with ceramide and fatty acid formulations; seasonal demand concentration in temperate climates.
- Oily Scalp:Sebum regulation claims with zinc PCA and clay-based absorption; professional salon scalp analysis tools drive service attachment.
Dandruff leads on scale; hair thinning climbs the fastest.
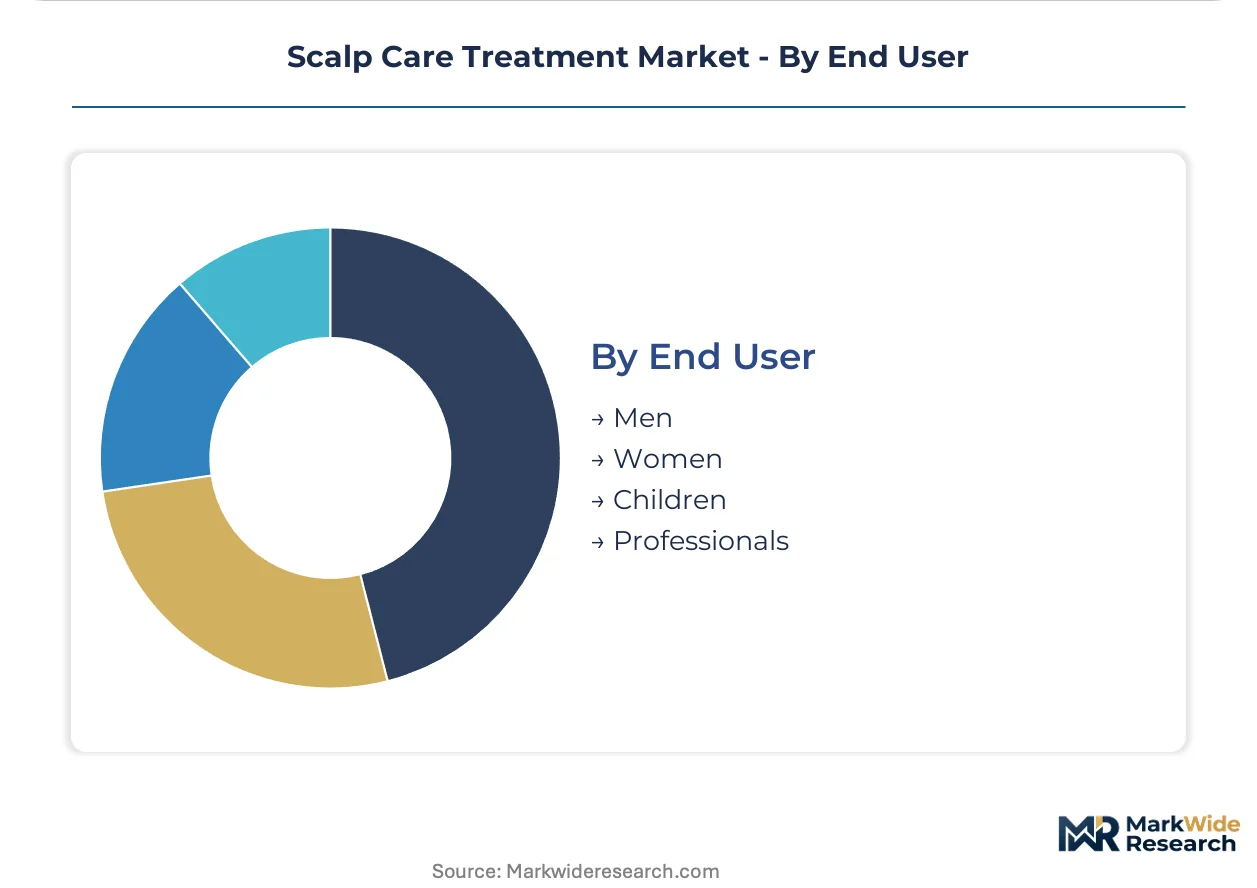
End User:
Demographic targeting reflects channel access patterns and price elasticity divergence, with professional segments commanding service-integration premiums.
- Women:Primary retail purchasers across mass and prestige channels; subscription model adoption concentrates in direct-to-consumer serum brands.
- Men:Hair thinning concern concentration drives clinical channel access; trichology clinic normalization in the United States pulls male demographics into professional service protocols.
- Children:Gentle formulation requirements with restricted preservative palettes; pediatric dermatologist recommendation dependence creates gatekeeper dynamics.
- Professionals:Salon and clinic service providers as indirect end users; training certification requirements for scalp-specific protocol delivery create vendor lock-in.
Women lead on scale; professionals lead on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trichology clinics in the United States anchor professional scalp treatment adoption, while regulatory chemistry shifts in Europe and Asia fragment formulation standards across major consumption clusters.
United States
Trichology clinics and dermatology practices normalize scalp health as a distinct treatment category, pulling clinical-grade protocols into mainstream salon service menus. FDA cosmetic-drug boundary enforcement triggers OTC drug or NDA pathways for anti-dandruff positioning, extending development timelines versus standard cosmetic registration. New York and Los Angeles concentrate premium salon channel expansion, with direct-to-consumer serum brands leveraging tele-dermatology partnerships to bypass traditional retail.
Germany
Professional salon networks accelerate adoption of scalp-specific protocols as premium service differentiators in saturated hair care markets. ECHA REACH phased restrictions on persistent surfactants force supplier transitions to biodegradable alternatives, compressing legacy supply chains. Düsseldorf and Hamburg clusters concentrate formulation R&D investment, with chemical houses restructuring around oleochemical feedstock partnerships.
China
Quasi-drug registration pathways for scalp products with medicinal claims create premium positioning opportunities for compliant entrants navigating 24-48 month NMPA approval timelines. GB standards and SAMR oversight impose separate registration requirements for imported products, fragmenting market access protocols. Shanghai and Guangzhou anchor medical-aesthetic crossover segment development, with domestic biotech firms scaling postbiotic extraction capabilities.
Japan
Fermented active platforms consolidate efficacy claims in the medical-aesthetic crossover segment, leveraging domestic biotech expertise in postbiotic extraction. METI chemical sustainability targets and PMDA oversight tighten evidentiary standards for scalp-specific efficacy assertions. Tokyo-Osaka corridor dominates premium scalp portfolio positioning, with clinics integrating peptide and ceramide formulations into adjuvant therapeutic protocols.
France
Luxury salon channel concentration drives premium scalp treatment adoption, with professional service integration commanding margin expansion over retail formats. EU Green Deal chemical sustainability targets and REACH microplastic prohibitions accelerate biodegradable surfactant transitions by 2030. Paris anchors formulation innovation clusters, as supplier networks restructure around fermentation-derived alternatives to synthetic polymer thickeners.
Scalp Care Treatment Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and channel access, creating a tiered structure where scale-driven portfolios face specialty-positioned entrants. The vendor base separates into dermatological research anchors, mass-market accessibility platforms, and East Asian biotech specialists. Three archetypes dominate: multinational consumer goods conglomerates with salon-clinic channel control, fermentation-technology regional champions, and direct-to-consumer serum pure-plays. Competitive moves concentrate on M&A for biotech extraction capabilities and backward integration into oleochemical supply chains.
Within the dermatological research tier, L'Oréal and Shiseido exemplify contrasting geographic anchoring strategies. L'Oréal leverages its French corporate structure to anchor professional-grade protocols across North American salon and clinic channels. Shiseido occupies a position within the East Asian medical-aesthetic crossover segment, with its Tokyo-based corporate footprint supporting fermented ingredient expertise. Unilever, structured as a British-Dutch consumer goods conglomerate, represents mass-market accessibility archetypes while extending sustainable sourcing claims into scalp-specific ranges.
| Leading Market Players |
|---|
| L'Oréal |
| Unilever |
| Procter & Gamble |
| Johnson & Johnson |
| Beiersdorf |
| Kérastase |
| Briogeo |
| Shiseido |
| Christophe Robin |
| Others |
Pricing and Supply Chain Analysis
Biodegradable surfactant premiums cascade from European oleochemical processors through three distinct pricing tiers, with REACH-compliant inputs commanding 3-5x multiples over petroleum-derived bases before salon channel markups.
Pricing Analysis
Input-cost pass-through from fermentation-derived actives and liposomal encapsulation systems stratifies pricing across premium, standard, and economy tiers. Certification grade under FDA OTC monograph compliance and volume scale differentiate salon-grade serums from mass-market shampoos. Pricing pressure stems from ECHA's phased surfactant restrictions compressing legacy formulation margins. Mass-market drugstore channels exhibit highest price sensitivity; trichology clinics and medical-aesthetic crossover segments demonstrate lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands anchor European hub-and-spoke patterns for professional salon channels. Raw material sourcing draws from East Asian fermentation biotech clusters, Indian oleochemical processors, and domestic European botanical extractors. Single-source vulnerability concentrates in postbiotic extraction capabilities centered on Japanese and South Korean biotech firms. Distribution runs through professional salon networks and direct-to-consumer platforms, with clinic-channel inventory carrying certification documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scalp care treatment functions as a late-cycle quality market where specification premiums widen as clinical credibility becomes the non-negotiable purchase criterion.
For Market Incumbents: Deploy backward integration into oleochemical feedstock partnerships to secure biodegradable surfactant supply ahead of 2030 REACH deadlines. Channel control through trichology clinic certification programs creates vendor lock-in against direct-to-consumer serum pure-plays. Capacity addition in German and French formulation clusters captures regional regulatory proximity advantages. For New Entrants and Emerging Players: Capture white-space in China's quasi-drug registration pathway where 24-48 month NMPA timelines deter multinational resource allocation. The medical-aesthetic crossover segment in Shanghai and Guangzhou offers lowest competitive density. Go-to-market leverage through tele-dermatology partnerships bypasses salon distribution gatekeepers entirely. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation-technology capabilities concentrate among mid-cap East Asian biotech specialists. Five-to-ten year viability favors platforms with captive postbiotic extraction and clinic-channel certification infrastructure. Watch FDA enforcement patterns on cosmetic-drug boundary claims as the inflection signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Supply | REACH microplastic prohibitions by 2030 force captive sourcing of biodegradable surfactant alternatives. |
| Trichology Clinic Certification Programs | Professional service integration creates recurring revenue attachment and vendor lock-in against retail competitors. |
| Direct-to-Consumer Serum Launch | Subscription models bypass salon distribution markups while capturing premium unit economics. |
| China Quasi-Drug Registration Investment | NMPA compliance creates premium positioning moats against entrants unwilling to navigate extended approval timelines. |
| Fermentation Technology Acquisition | Postbiotic extraction capabilities consolidate efficacy claims in the medical-aesthetic crossover segment. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with trichology clinic directors, salon chain procurement managers, formulation R&D leads, and regulatory affairs specialists at cosmetic houses informed demand-side and supply-side assessments. Secondary sources include FDA OTC monograph databases, ECHA REACH substance registrations, NMPA quasi-drug approval filings, and customs trade data on oleochemical imports. Bottom-up product-type volume builds and top-down category value estimates were triangulated against channel shipment data.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects. Segmentation dimensions modeled include product type, ingredient sourcing strategy, target clinical concern, and channel archetype. CAGRs derive from logistic adoption curves fitted to professional salon penetration rates and serum format share gains. Industry-specific inputs incorporate REACH surfactant restriction phase-in schedules and NMPA registration pipeline visibility.
Regulatory enforcement variance, raw material supply disruption, and channel shift acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on compliance timelines and adoption elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Anti-Fungal Treatment Market
Medical Treatment
US Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
Tissue Repair Technologies Market
Medical Treatment
Brain Tumor Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Iron Deficiency Anemia Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Mast Cell Tumors Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market