
 Handheld XRF Spectrometer Market | 2026-2036
Handheld XRF Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld XRF Spectrometer Market Insights
The capability gap between silicon drift detector platforms and older PIN diode architectures is collapsing as component costs fall and firmware optimization spreads. Thermo Fisher Scientific leverages its vertical integration into detector fabrication to sustain margin structures that smaller competitors cannot match. Bruker Corporation anchors its position through deep R&D intensity in calibration algorithms. SciAps competes aggressively on portability and field-service responsiveness, occupying a distinct tier below the instrumentation giants.
A handheld XRF spectrometer is a portable analytical instrument that uses X-ray fluorescence to identify elemental composition in solids, liquids, and coatings, typically detecting elements from magnesium to uranium with detection limits reaching single-digit parts per million depending on the matrix and measurement time. The device serves primary industrial purposes in alloy verification, hazardous substance screening, and geological assay where laboratory access is impractical or time-critical. Energy dispersive technology dominates unit shipments due to its mechanical simplicity and lower power requirements, though wavelength dispersive variants command premium positioning in ultra-trace applications where resolution demands justify the bulkier optical bench. Battery-powered configurations represent the fastest-expanding product configuration as lithium-ion energy density improvements enable full-shift field operation without tethered power, while desktop units retain entrenched positions in quality control labs where throughput and ergonomic stability outweigh portability needs.
The US EPA and OSHA both influence demand through enforcement of workplace exposure limits and waste characterization rules that mandate rapid elemental screening. The European Union's RoHS Directive and REACH Regulation together shape product design requirements, forcing manufacturers to certify instruments for restricted substance detection protocols that differ materially from general alloy analysis. Stakeholders must monitor how evolving battery transport regulations and detector export controls alter supply chain configurations for portable radiation-emitting devices.
Market Dynamics
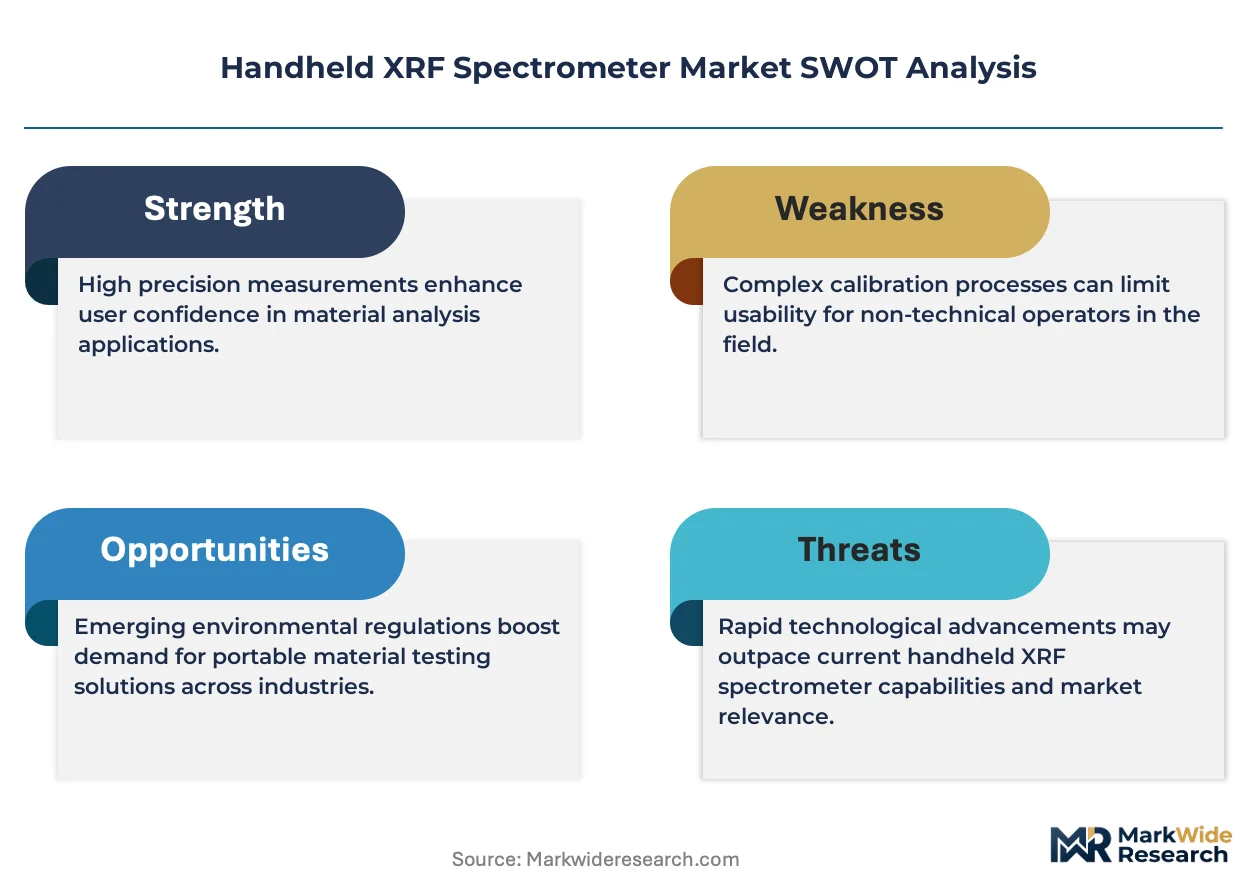
Silicon drift detector architectures are collapsing the price-performance gap that previously separated premium and mid-tier handheld XRF platforms, compressing margins across the vendor base while expanding addressable volume in price-sensitive industrial segments.
Growth Catalysts
- RoHS and REACH enforcement:European Union substance restrictions compel electronics manufacturers to deploy rapid incoming material screening, creating baseline demand for restricted substance detection protocols.
- On-site ore verification:Mining operations in Chile and Australia are expanding field-based assay programs to reduce laboratory turnaround times and optimize bulk shipment decisions.
- Lithium-ion energy density improvements:Battery chemistry advances now enable full-shift field operation without tethered power, removing the operational constraint that previously limited deployment in remote geological surveys.
Market Restraints
- Detector fabrication concentration:High-purity silicon crystal production for drift detectors concentrates among a handful of specialized foundries, creating supply vulnerability for instrument assemblers without captive supply.
- Export control friction:Portable radiation-emitting devices face dual-use classification reviews that delay cross-border shipments and complicate inventory positioning for multinational vendors.
- Competing analytical modalities:Handheld LIBS (laser-induced breakdown spectroscopy) instruments are capturing light-element applications where XRF detection limits prove inadequate for lithium or beryllium quantification.
Strategic Opportunities
- Battery raw material verification:Cobalt and nickel supply chain traceability mandates are opening new inspection points at mining, refining, and cell manufacturing stages where portable elemental confirmation reduces counterparty risk.
- Service model unbundling:Subscription-based calibration and firmware update programs offer recurring revenue streams that decouple vendor economics from hardware replacement cycles.
- Scrap metal sorting automation:Integration of handheld units with robotic sorting arms at recycling facilities creates demand for ruggedized, high-throughput configurations with API-enabled data pipelines.
Industry Challenges
- Calibration algorithm expertise:The scarcity of spectroscopists capable of developing matrix-specific calibration curves limits vendor differentiation and prolongs customer onboarding timelines.
- Multi-jurisdiction certification:Securing NIST-traceable validation for EPA methods, CE marking for EU market access, and country-specific radiation safety licenses stretches product launch schedules across 18-24 month windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld XRF Spectrometer Market |
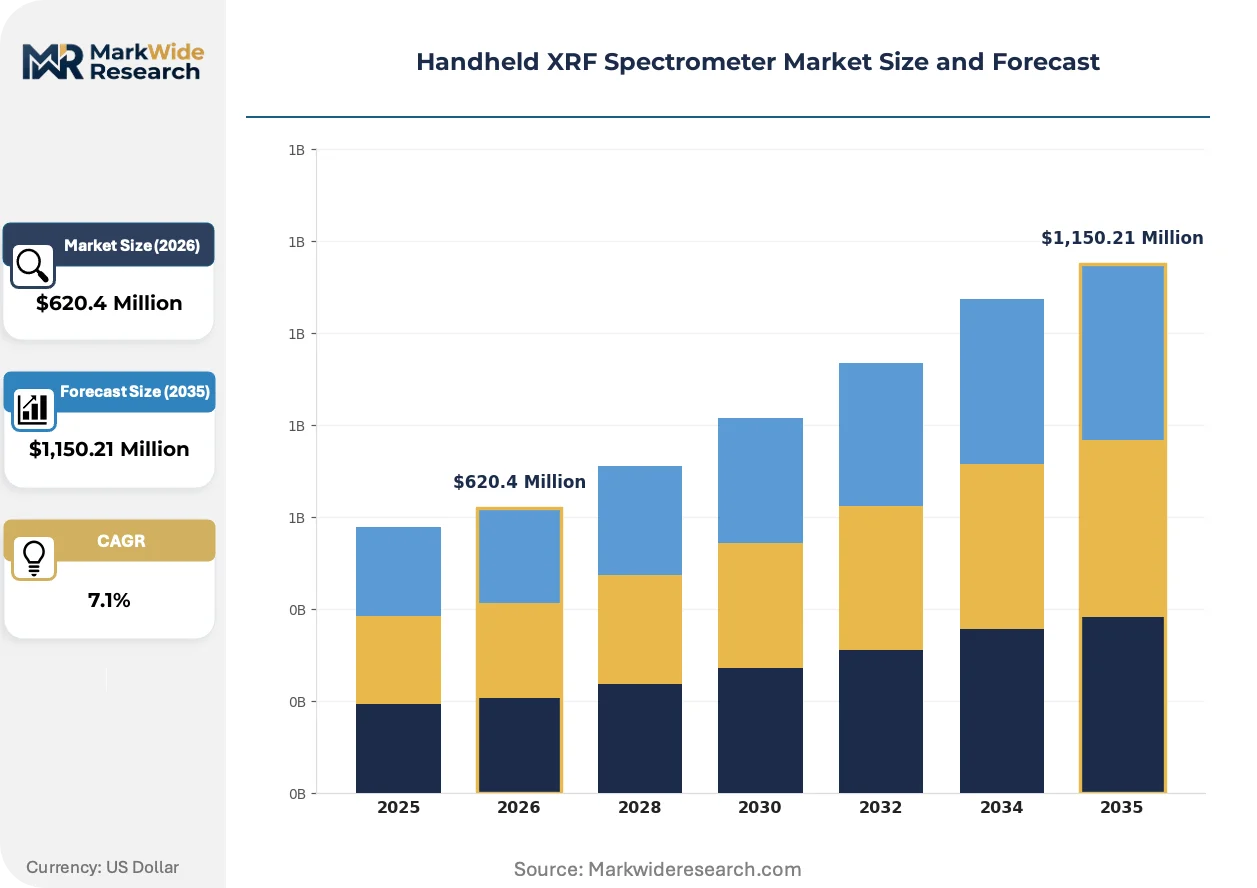
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,150.21 Million |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Desktop, Modular, Battery-Powered Technology: Energy Dispersive, Wavelength Dispersive, X-Ray Fluorescence, Micro-XRF End User: Environmental Agencies, Mining Companies, Manufacturing, Quality Control Labs Application: Material Analysis, Scrap Sorting, Coating Thickness, Archaeological Analysis |
| Companies Covered | Thermo Fisher Scientific, Bruker Corporation, Olympus Corporation, Hitachi High-Tech, Rigaku Corporation, HORIBA Ltd., AMETEK (SPECTRO Analytical), SciAps, Malvern Panalytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld XRF Spectrometer Market Trends and Innovations
Artificial intelligence is embedding into firmware layers to automate spectral deconvolution, reducing operator skill requirements while compressing measurement times for complex alloy matrices. Three interconnected developments are reshaping competitive positioning.
Silicon drift detectors with integrated thermoelectric cooling are supplanting thermoelectrically cooled PIN diode architectures in mid-tier price bands. Scrap yard operators and secondary metal processors are adopting these platforms at replacement rates exceeding prior cycles. The technology shift is compressing the addressable market for legacy detector suppliers while forcing premium vendors to differentiate through software rather than hardware performance.
REACH substance restriction amendments are expanding the catalog of restricted elements beyond the original RoHS six to include additional rare earth and heavy metal contaminants. Electronics contract manufacturers in East Asian clusters must now screen for 12-14 restricted elements versus the historical baseline of six. This regulatory expansion favors instruments with broader elemental libraries and faster multi-element simultaneous detection capabilities.
Buying committees at industrial facilities are unbundling hardware procurement from service contracts, treating calibration maintenance and training as separately negotiable line items. Distributors who previously captured full-stack margins now face disintermediation by factory-direct service organizations. This pattern is most pronounced in German automotive supplier networks where centralized procurement functions mandate multi-year total cost of ownership comparisons over upfront capital expenditure minimization.
Handheld XRF Spectrometer Market Segmentation
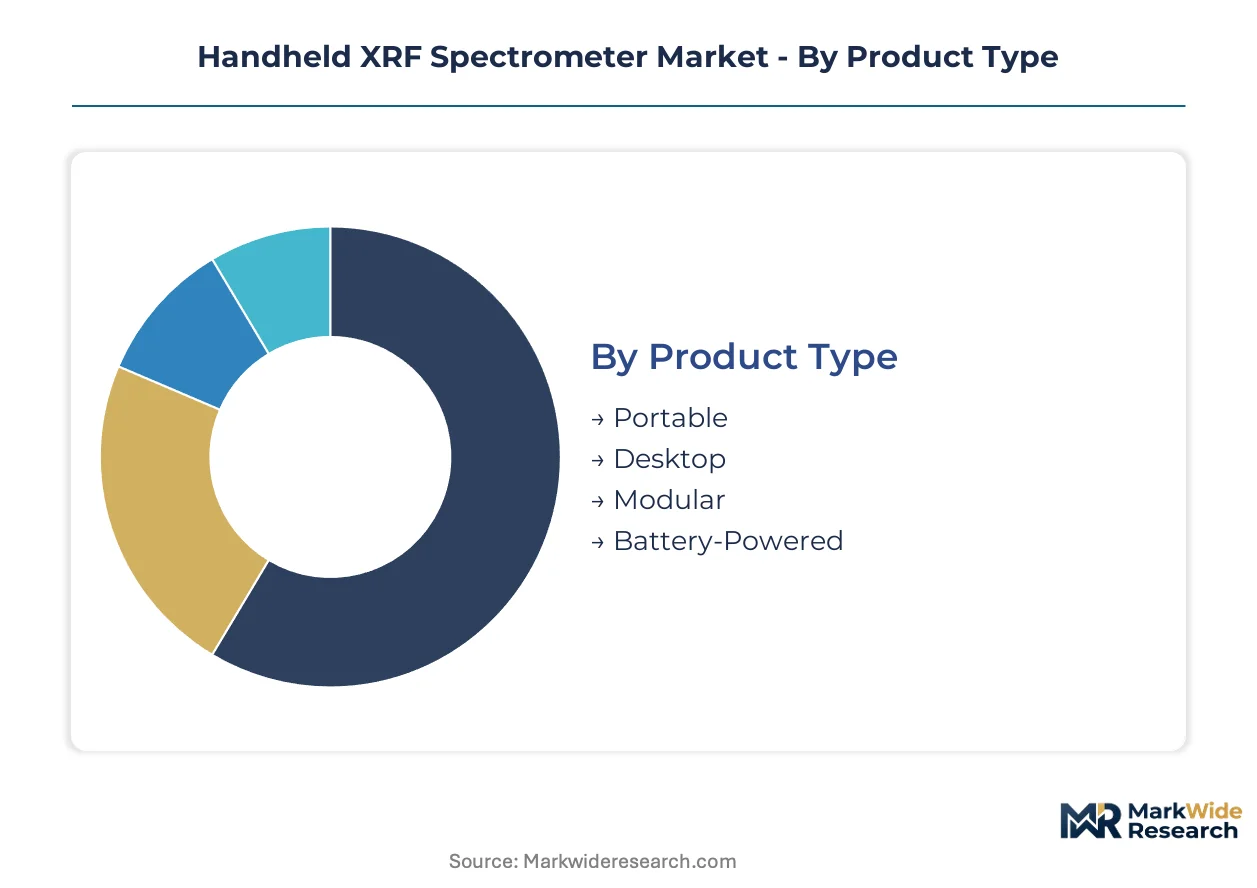
Handheld XRF spectrometer procurement patterns diverge sharply across product configurations, detection technologies, and end-use environments. Understanding these splits reveals where pricing power concentrates and which customer segments drive replacement cycles versus first-time adoption.
Product Type:
Domestic quality control operations favor tethered desktop units, while export-led mining and environmental inspection programs generate disproportionate demand for field-portable configurations.
- Portable:Self-contained units weighing under 2 kg enable single-operator deployment at remote geological sites and scrap yard receiving docks. Mining companies in Chile and Australia are standardizing on these platforms for on-site ore verification, cutting laboratory turnaround from weeks to hours.
- Desktop:Fixed-installation instruments with stabilized optical benches deliver superior precision for alloy certification in automotive supplier labs. German automotive networks treat these as capital equipment with 7-10 year depreciation schedules, insulating the segment from short-term budget cycles.
- Modular:Configurable detector heads and interchangeable X-ray tubes accommodate specialized archaeological or art conservation workflows where sample geometry varies unpredictably.
- Battery-Powered:Lithium-ion energy density advances now support full-shift operation without generator tethering, opening geological surveys in grid-deficient regions of Western Australia and northern Chile.
Desktop configurations command the established base. The steepest expansion runs through battery-powered platforms.
Technology:
Cost tier separation is pronounced: silicon drift detector premiums collapse toward PIN diode price bands, while wavelength dispersive systems maintain 3-4x cost multiples for ultra-trace resolution.
- Energy Dispersive:Solid-state detectors with pulse-processing electronics dominate unit economics through mechanical simplicity and reduced power draw. East Asian electronics manufacturers deploy these for RoHS compliance screening at incoming material gates.
- Wavelength Dispersive:Crystalline diffraction optics resolve elemental lines with 10x better separation than energy-dispersive alternatives, justifying bulk and complexity in semiconductor-grade material certification. Japanese silicon foundries specify these for ultra-trace contamination protocols.
- X-Ray Fluorescence:The foundational excitation-detection architecture spans both handheld and laboratory configurations, with firmware differentiation now exceeding hardware variance in commercial significance.
- Micro-XRF:Focused beam optics with sub-50 micron spot sizes enable non-destructive analysis of museum artifacts and forensic evidence where sample integrity is paramount.
Energy dispersive platforms anchor volume shipment. Wavelength dispersive systems capture margin concentration in semiconductor and aerospace certification chains.
End User:
Customer type determines procurement authority structure: environmental agencies run centralized bidding, while mining companies delegate equipment selection to site geologists.
- Environmental Agencies:US EPA and state-level regulators enforce hazardous waste characterization rules that mandate rapid elemental screening at remediation sites. Procurement flows through federal supply schedules with multi-year calibration service requirements.
- Mining Companies:Copper and lithium producers in Chile deploy field teams with daily assay quotas, prioritizing instrument durability and local service response over specification margins.
- Manufacturing:Electronics contract manufacturers in Taiwan and South Korea integrate handheld units at incoming material inspection stations to satisfy OEM RoHS liability transfer requirements.
- Quality Control Labs:Automotive tier-1 suppliers in Germany operate climate-controlled metrology rooms where ergonomic stability and throughput optimization outweigh portability considerations.
Manufacturing end users drive replacement volume through obsolescence cycles. Mining companies generate the steepest expansion trajectory as on-site verification programs proliferate.
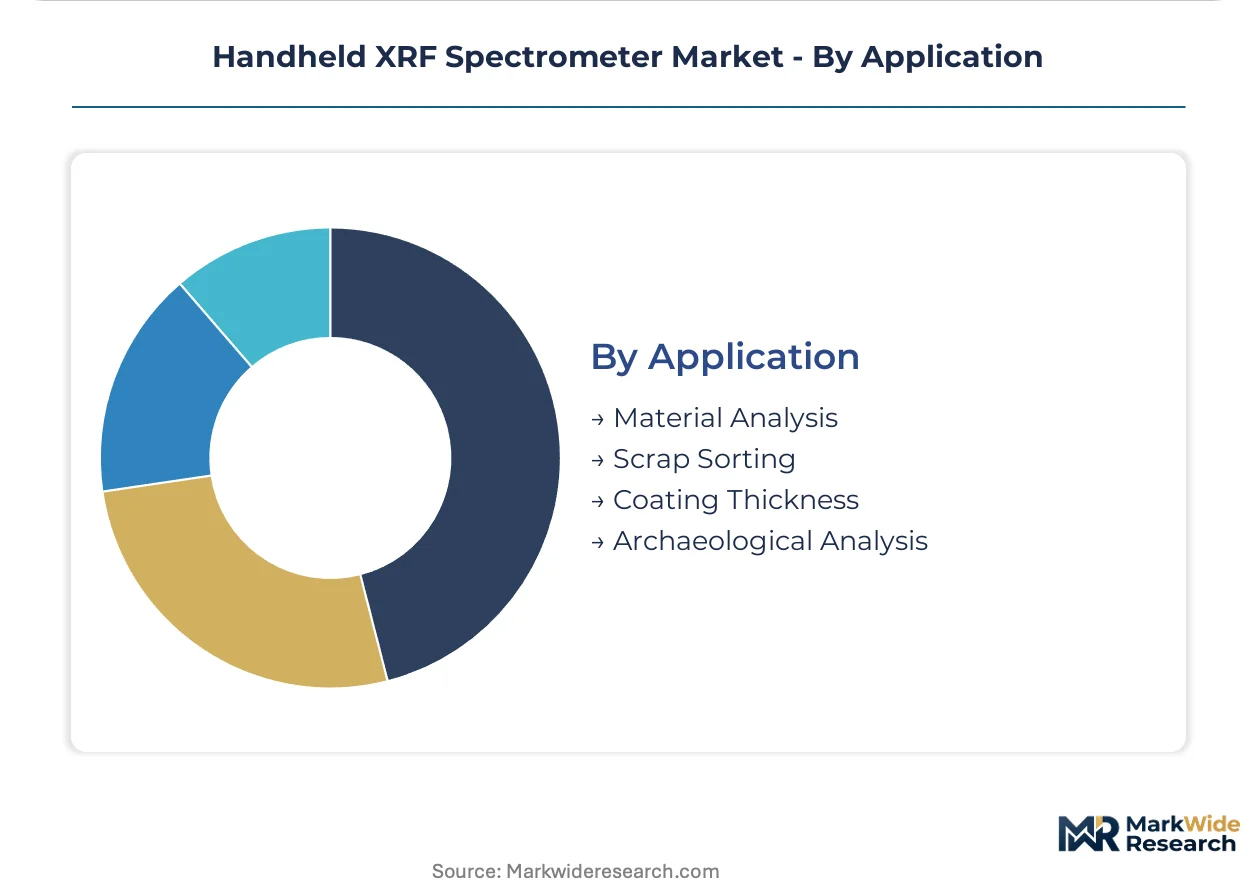
Application:
Application maturity varies: material analysis is saturated with installed base, while battery raw material verification creates emergent inspection points.
- Material Analysis:Alloy grade verification for stainless steel and superalloy stock represents the historical core use case, with established calibration libraries and operator training curricula.
- Scrap Sorting:Secondary metal processors in the US Midwest and European port facilities deploy handheld units to separate nickel-bearing from standard stainless grades, capturing price differentials that justify capital expenditure.
- Coating Thickness:Galvanizing lines and electronics plating operations measure zinc, nickel, and gold layer depths without destructive cross-sectioning, integrating measurements directly into SPC systems.
- Archaeological Analysis:Museums and academic conservation programs source specialized micro-XRF configurations for pigment identification in paintings and alloy provenance in metal artifacts.
Material analysis commands the installed base. Scrap sorting applications are climbing fastest as automated yard systems integrate handheld verification into robotic sorting workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers command pricing premiums for laboratory-grade configurations, while Chinese electronics manufacturers drive volume procurement at compressed margins through standardized incoming material screening protocols.
United States
Environmental remediation contractors and scrap metal processors constitute dual demand pillars. The EPA enforces hazardous waste characterization rules that mandate rapid elemental screening at Superfund sites. Houston petrochemical corridors and Detroit-area automotive supplier networks deploy battery-powered units for field alloy verification.
Germany
Automotive tier-1 suppliers operate centralized procurement functions with multi-year total cost of ownership frameworks. REACH substance restriction amendments expand restricted element catalogs beyond the original RoHS six. Stuttgart and Wolfsburg industrial clusters specify desktop configurations with 7-10 year depreciation schedules.
China
Electronics contract manufacturers in Shenzhen and Dongguan integrate handheld units at incoming material gates to satisfy OEM liability transfer requirements. The country's national environmental regulator enforces waste electrical and electronic equipment directives with escalating inspection frequency. Yangtze River Delta manufacturing hubs standardize on energy-dispersive platforms for RoHS compliance screening.
Australia
Iron ore and lithium producers deploy field teams with daily assay quotas across Western Australia and Queensland. The country's national mining safety regulator mandates radiation safety licensing for portable X-ray devices. Kalgoorlie and Pilbara mining districts prioritize instrument durability and local service response over specification margins.
Chile
Copper mining operations expand on-site ore verification programs to optimize bulk shipment decisions. The national mining regulator oversees radiation safety protocols for field-deployed analytical equipment. Antofagasta and Calama mining districts cut laboratory turnaround from weeks to hours through standardized portable deployment.
Handheld XRF Spectrometer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the handheld XRF spectrometer market. Consolidation concentrates around detector fabrication capabilities and calibration algorithm expertise, while mid-tier assemblers compete on field-service responsiveness and portability optimization. Two strategic archetypes dominate: vertically integrated instrumentation giants with captive detector supply, and specialized portable-device vendors unburdened by legacy laboratory product portfolios. Competitive moves center on firmware subscription unbundling and robotic integration partnerships for scrap sorting automation.
Among US-based instrumentation conglomerates, Thermo Fisher Scientific and AMETEK occupy positions anchored by backward integration into detector fabrication and broad analytical instrumentation portfolios. Bruker Corporation exemplifies the R&D-intensive archetype with deep investment in calibration algorithm development. SciAps represents the agile portable-specialist tier, competing on field-service responsiveness and ergonomic optimization below the instrumentation giants. Japanese precision manufacturers including Hitachi High-Tech and Rigaku Corporation sit within the diversified technology holding company structure, leveraging cross-divisional component sourcing advantages.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bruker Corporation |
| Olympus Corporation |
| Hitachi High-Tech |
| Rigaku Corporation |
| HORIBA Ltd. |
| AMETEK (SPECTRO Analytical) |
| SciAps |
| Malvern Panalytical |
| Others |
Pricing and Supply Chain Analysis
Long-term detector supply contracts lock in silicon crystal allocation for instrument assemblers while fixing cost visibility against spot market volatility in high-purity semiconductor substrates. This contract structure shields premium vendors from raw material price swings that compress margins for smaller competitors sourcing through distributors.
Pricing Analysis
Configured-to-order pricing for silicon drift detector platforms commands spreads of 40-60% above standard PIN diode configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by detector resolution grade and bundled calibration service depth. Cost compression in mid-tier segments is intensifying because firmware optimization erodes hardware-based differentiation. Electronics contract manufacturers in East Asian clusters exhibit highest price sensitivity, while German automotive suppliers accept premium positioning for NIST-traceable certification tiers.
Supply Chain Analysis
Inventory cycles for high-purity silicon crystals now stretch 16-20 weeks as foundry capacity concentrates in Japan, Germany, and the United States. Detector fabrication draws from germanium-doped silicon ingots, thermoelectric cooling modules, and precision-machined collimator assemblies. Single-source vulnerability in drift detector crystal supply creates chokepoint risk for instrument assemblers without captive foundry relationships. Distribution runs through factory-direct service organizations in developed markets and authorized distributor networks in mining-intensive geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against handheld LIBS instruments capturing light-element applications where XRF detection limits prove inadequate. Incumbents must neutralize this threat while exploiting firmware unbundling to capture recurring revenue streams.
For Market Incumbents: Fortify backward integration into detector fabrication to sustain margin structures that smaller competitors cannot replicate. Deepen investment in AI-embedded spectral deconvolution algorithms that compress measurement times and reduce operator skill requirements. Prioritize certification pre-loading for evolving REACH substance restriction amendments that expand restricted element catalogs beyond historical baselines.
For New Entrants and Emerging Players: Firmware subscription gaps in incumbent service portfolios offer entry points for agile competitors unburdened by legacy hardware replacement cycles. Target battery raw material verification workflows at cobalt and nickel refining stages where supply chain traceability mandates create emergent inspection demand. Lead with API-enabled data pipeline integration for robotic scrap sorting automation partnerships.
For Investors and Strategic Acquirers: Portable-specialist vendors with ergonomic optimization expertise and responsive field-service networks represent prime acquisition targets for instrumentation conglomerates seeking geographic expansion. Long-term viability hinges on software differentiation overtaking hardware performance as the primary value driver. Monitor silicon drift detector cost curves as inflection indicator for margin compression velocity across vendor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Detector Fabrication Backward Integration | Captive silicon crystal supply secures margin structures against foundry concentration in Japan and Germany. |
| AI-Embedded Firmware Development | Automated spectral deconvolution reduces operator skill barriers and compresses measurement times for complex matrices. |
| REACH Certification Pre-Loading | Early validation for expanded restricted element catalogs captures electronics manufacturer procurement cycles. |
| Robotic Scrap Sorting Partnerships | API-enabled data pipelines integrate handheld verification into automated recycling facility workflows. |
| Battery Raw Material Verification Service Launch | Cobalt and nickel supply chain traceability mandates open inspection points at mining and refining stages. |
Research Methodology
Initial hypotheses were tested against primary input from instrument engineering directors, mining site geologists, electronics manufacturing quality managers, and environmental remediation contractors and refined through secondary validation against customs trade records, EPA enforcement databases, SEC instrument manufacturer filings, and REACH regulatory amendment notices. Bottom-up triangulation across installed base estimates and top-down cross-checks against end-user procurement budgets anchored volume and value outputs.
Variance decomposition across technology tier, end-use industry, product configuration, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate blending weighted by current period revenue contribution. Forecast inputs incorporated lithium-ion energy density improvement curves and evolving RoHS enforcement intensity indices across East Asian electronics manufacturing hubs.
Underlying assumptions cover detector cost decline trajectories and firmware substitution elasticity, with deviation risk concentrated in export control friction for portable radiation-emitting devices and competing analytical modality displacement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market