
 Boron Analyzer Market | 2026-2036
Boron Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Boron Analyzer Market Analysis
Pharmaceutical quality control is rebalancing toward inline boron detection as biologics manufacturers tighten elemental impurity limits under ICH Q3D guidelines. Thermo Fisher Scientific leverages its mass spectrometry portfolio to anchor high-sensitivity pharmaceutical contracts. Horiba Scientific specializes in compact ion-selective systems for field-deployed environmental monitoring. Yokogawa Electric Corporation dominates process analytics integration for chemical manufacturing corridors in East Asia.
A boron analyzer quantifies boron concentration in liquid or solid matrices through colorimetric, ion-selective electrode, spectrophotometric, or fluorometric detection methods, typically achieving detection limits from parts-per-billion to low parts-per-million depending on optical path length and reagent chemistry. These instruments serve critical functions in nuclear reactor coolant chemistry control, semiconductor ultrapure water verification, and agricultural soil fertility assessment. Benchtop systems retain the largest installed base among product types, though handheld units are capturing faster growth in decentralized environmental testing workflows. Spectrophotometric technology leads in nuclear and semiconductor end uses where trace-level precision commands premium pricing, while colorimetric platforms occupy cost-sensitive agricultural and educational segments with thinner margin structures.
The EPA Safe Drinking Water Act and ICH Q3D elemental impurity guidelines create dual compliance pressures that expand analyzer replacement demand across municipal laboratories and pharmaceutical QC departments. REACH restrictions on boron compounds in industrial applications in Europe redirect testing budgets toward workplace exposure monitoring. Stakeholders must monitor evolving ISO 17294 standards for elemental analysis to anticipate spectrophotometric platform obsolescence cycles and align R&D roadmaps with next-generation plasma-based detection requirements.
Market Dynamics
The EPA's updated drinking water monitoring protocols and ICH Q3D elemental impurity guidelines are compressing replacement cycles, forcing laboratories to retire legacy spectrophotometric systems ahead of scheduled depreciation timelines.
Growth Catalysts
- Stricter coolant chemistry specifications:Nuclear power plant operators are expanding boron monitoring programs to meet tighter regulatory thresholds for reactor safety.
- Semiconductor-grade water verification mandates:German industrial laboratories face compulsory upgrades of legacy systems to satisfy purity requirements for advanced chip manufacturing.
- Inline detection technology:Biologics manufacturers are rebalancing quality control workflows toward continuous boron monitoring to tighten elemental impurity limits under ICH Q3D guidelines.
Market Restraints
- Platinum electrode supply concentration:Ion-selective electrode production depends on South African and Russian platinum group metal refining, exposing manufacturers to geopolitical supply disruptions.
- High-purity reagent cost volatility:Azomethine-H and curcumin reagent synthesis requires pharmaceutical-grade solvents subject to energy-intensive production cost swings.
- Spectrophotometric platform obsolescence risk:Evolving ISO 17294 standards for elemental analysis threaten to render non-plasma-based detection systems non-compliant within current asset lifecycles.
Strategic Opportunities
- Decentralized environmental testing expansion:Handheld colorimetric units are capturing faster growth in field-deployed water quality monitoring across rural municipalities.
- Process analytics integration:Chemical manufacturing corridors in East Asia present untapped demand for inline boron analyzers tied to distributed control systems.
- REACH workplace exposure monitoring:European restrictions on boron compounds in industrial applications redirect testing budgets toward occupational safety instrumentation.
Industry Challenges
- Spectroscopic calibration expertise scarcity:Nuclear and semiconductor end-users struggle to recruit technicians proficient in plasma-based detection method validation.
- Legacy system integration complexity:Municipal laboratories face friction retrofitting benchtop analyzers into existing laboratory information management system architectures.
- Multi-jurisdiction certification timelines:Manufacturers must navigate simultaneous EPA, ISO, and ICH compliance pathways, elongating product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boron Analyzer Market |
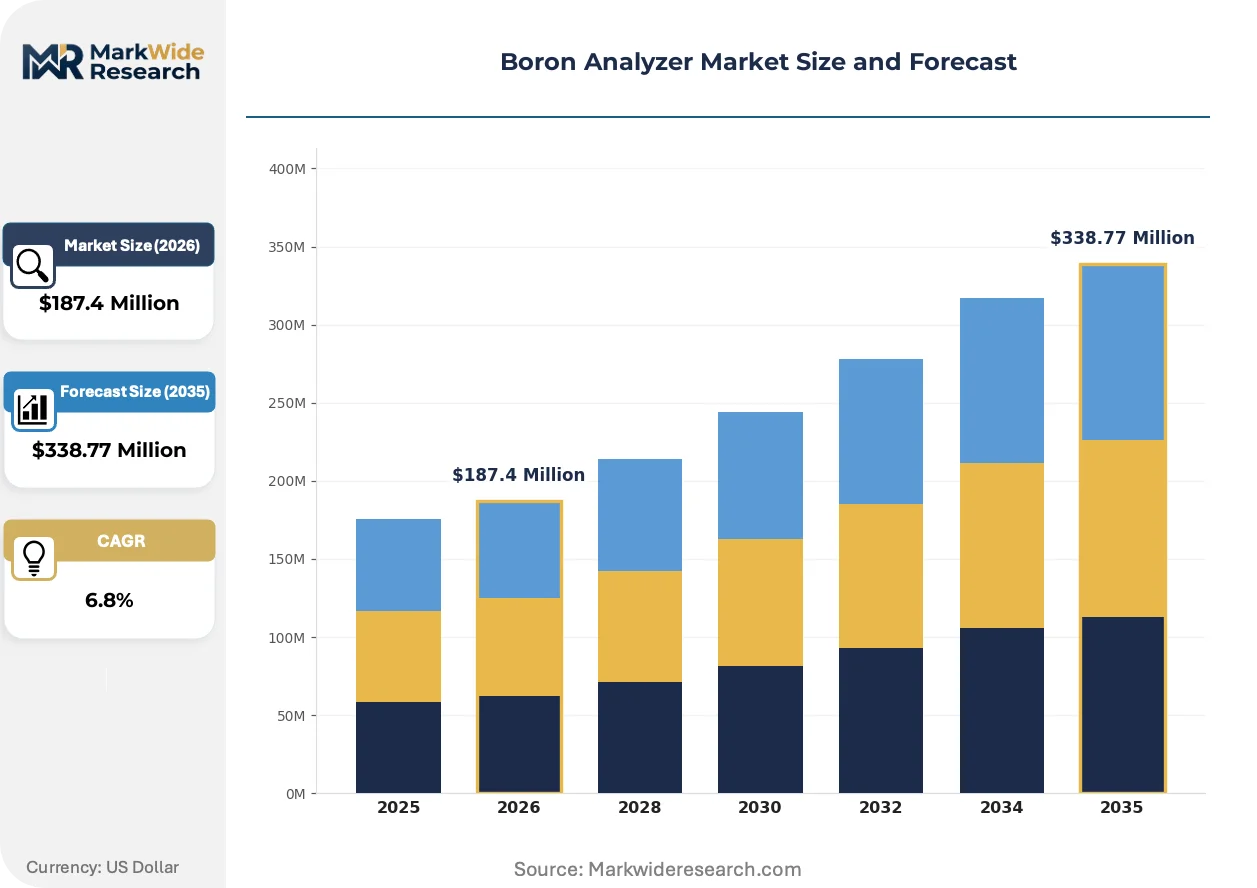
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Benchtop, Multi-Parameter, Lab-Scale Technology: Colorimetric, Ion-Selective, Spectrophotometric, Fluorometric End User: Chemical Manufacturing, Environmental Testing, Agriculture, Pharmaceuticals Application: Water Quality, Soil Testing, Industrial Processes, Research Laboratories |
| Companies Covered | Thermo Fisher Scientific, Horiba Scientific, ABB Ltd., Emerson Electric Co., Yokogawa Electric Corporation, Endress+Hauser Group, Mettler Toledo, Agilent Technologies, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boron Analyzer Market Emerging Trajectories
Detection methodology is bifurcating between high-sensitivity plasma-based platforms for trace analysis and miniaturized field-deployable systems, with software-defined analytics reshaping how operators interpret concentration data.
Laser-induced breakdown spectroscopy is converging with machine learning-based spectral deconvolution to enable real-time boron quantification in solid matrices without sample digestion. Mining laboratories in Australia and Chile are piloting these systems for rapid ore grade assessment. The technology is compressing turnaround times from hours to minutes, displacing traditional fusion-and-dissolution workflows in high-throughput geochemical laboratories.
REACH restrictions on boron compounds are expanding workplace exposure monitoring obligations across European manufacturing facilities. Industrial hygiene departments must now deploy continuous personal monitoring rather than periodic grab sampling. Semiconductor fabrication plants in Germany and the Netherlands are responding by installing networked ion-selective electrode arrays tied to building management systems for automated ventilation control.
Service unbundling is fragmenting traditional analyzer procurement patterns. Municipal water utilities now separate hardware acquisition from reagent supply and calibration service contracts, enabling multi-vendor sourcing strategies. This behavior is most visible in the United States, where EPA Safe Drinking Water Act enforcement has compressed capital equipment approval timelines while extending operational expenditure scrutiny.
Boron Analyzer Market Segmentation
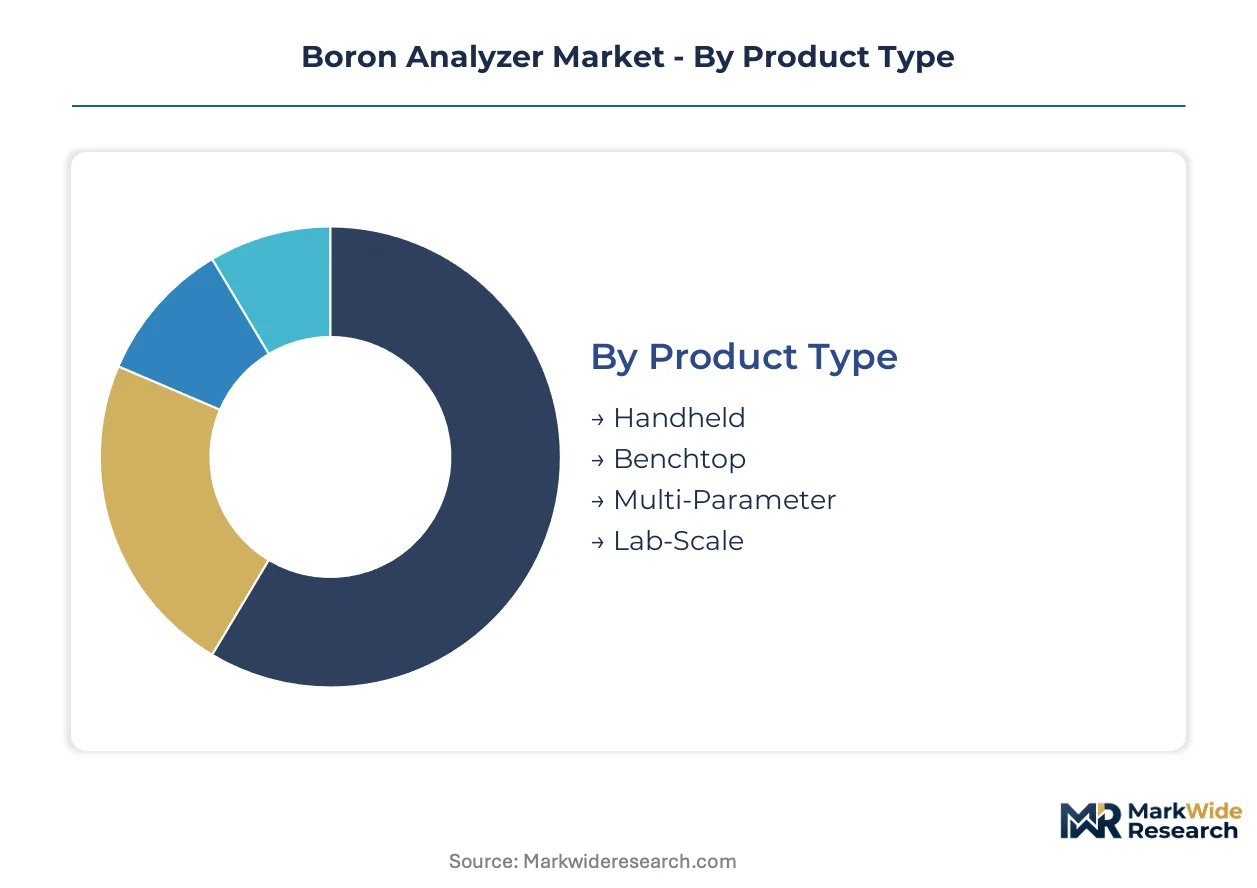
Boron analyzer procurement patterns diverge sharply across deployment contexts, with nuclear coolant chemistry demanding trace-level precision while agricultural soil testing prioritizes field portability. Product specifications, detection methodology, and end-use compliance requirements create distinct commercial pockets with non-overlapping vendor bases.
Product Type:
Benchtop systems concentrate manufacturing capacity among Japanese and German precision optics suppliers, while handheld production gravitates toward Chinese electronics assemblers with MEMS sensor integration capabilities.
- Handheld:Battery-powered units integrate solid-state optical sensors with Bluetooth data transmission for immediate field reporting. Environmental contractors in rural United States municipalities are displacing laboratory send-out workflows with same-day boron screening.
- Benchtop:These systems deploy dual-beam spectrophotometry with thermostatted cuvette chambers achieving parts-per-billion detection limits. Nuclear power plant chemistry laboratories in France and Japan anchor replacement demand as coolant specifications tighten.
- Multi-Parameter:Modular chassis accommodate interchangeable boron, phosphate, and silica detection cartridges. Water utilities in Germany favor these configurations for consolidated laboratory footprints.
- Lab-Scale:Research-grade instruments feature programmable autosamplers and LIMS integration protocols. University agricultural extension services in Australia deploy these for soil fertility mapping programs.
Benchtop systems absorb the bulk of installed capacity; handheld units are expanding most quickly.
Technology:
Detection chemistry cost tiers separate premium plasma-based platforms from reagent-intensive colorimetric alternatives, with ion-selective electrodes occupying a mid-market position sensitive to platinum group metal pricing.
- Colorimetric:Azomethine-H complexation reactions in portable cuvette readers serve cost-sensitive educational and agricultural markets. Brazilian soil testing cooperatives favor these systems for seasonal fertility campaigns.
- Ion-Selective:Polymer membrane electrodes with boron-specific ionophores enable continuous inline monitoring without sample pretreatment. Semiconductor fabrication plants in the Netherlands deploy networked arrays for ultrapure water verification.
- Spectrophotometric:High-resolution UV-Vis platforms with 10-centimeter pathlength cells achieve sub-ppb quantification for nuclear reactor coolant analysis. Japanese utilities mandate these specifications for primary loop chemistry control.
- Fluorometric:Curcumin-based fluorescence detection offers enhanced selectivity in high-salinity matrices. Offshore oilfield water treatment facilities in Norway utilize these for produced water boron monitoring.
Spectrophotometric platforms command the premium pricing tier; fluorometric methods are climbing the fastest in specialized industrial applications.
End User:
Regulatory enforcement intensity varies dramatically across end-use sectors, with pharmaceutical QC departments facing ICH Q3D-driven replacement cycles while agricultural buyers operate on discretionary equipment budgets.
- Chemical Manufacturing:Process analytics integration demands 4-20mA output signals and Modbus connectivity for distributed control system incorporation. Petrochemical corridors along the United States Gulf Coast drive inline analyzer procurement.
- Environmental Testing:EPA Safe Drinking Water Act enforcement compresses capital approval timelines for municipal laboratories. Certified reference material traceability requirements favor established spectrophotometric vendors.
- Agriculture:Extension services and commercial soil testing laboratories prioritize throughput over detection limits. Australian wheat belt cooperatives deploy seasonal rental programs for harvest-time boron assessment.
- Pharmaceuticals:Biologics manufacturers implement continuous verification under ICH Q3D elemental impurity guidelines. Swiss and Irish injectable drug facilities anchor demand for mass spectrometry-coupled detection.
Environmental testing absorbs the bulk of installed capacity; pharmaceutical applications are gaining share fastest.
Application:
Sample matrix complexity dictates instrument selection, with ultrapure water verification requiring fundamentally different optical configurations than soil extract analysis.
- Water Quality:Drinking water, wastewater, and ultrapure process streams each demand distinct detection ranges and interference suppression. German semiconductor fabs enforce the most stringent boron limits for chip rinsing operations.
- Soil Testing:Acid extraction protocols and suspended particle handling constrain optical path design. Canadian prairie agricultural laboratories process seasonal sample surges with automated discrete analyzers.
- Industrial Processes:High-temperature, high-pressure sampling interfaces separate process analytics specialists from laboratory instrument vendors. Nuclear primary coolant analysis requires borated water compatibility and radiation-hardened components.
- Research Laboratories:Method development flexibility and multi-element capability drive specification priorities. Geochemical survey organizations in Chile and Australia pilot laser-induced breakdown spectroscopy for rapid ore characterization.
Water quality applications absorb the bulk of installed capacity; research laboratory deployments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dresden semiconductor cluster and Bavarian chemical corridor concentrate German demand for ultrapure water verification systems. Tax incentives for advanced manufacturing in these zones accelerate instrumentation replacement timelines.
United States
Nuclear utilities along the Gulf Coast and Great Lakes expand boron monitoring programs to meet tightened NRC coolant chemistry specifications. EPA Safe Drinking Water Act enforcement compresses municipal laboratory capital approval cycles. The Texas petrochemical corridor drives inline analyzer procurement for process control integration.
Germany
Semiconductor fabrication plants in Dresden and Munich face compulsory upgrades of legacy spectrophotometric systems under REACH workplace exposure mandates. The country's national environmental regulator enforces stricter boron compound monitoring in industrial hygiene applications. Bavarian chemical manufacturers deploy networked ion-selective electrode arrays for automated ventilation control.
Japan
Utilities operating boiling water reactors in Fukui and Niigata prefectures mandate sub-ppb detection platforms for primary loop chemistry control. METI guidelines on nuclear safety instrumentation accelerate replacement of aging benchtop systems. The Yokohama-Kawasaki manufacturing belt anchors process analytics integration demand from specialty chemical producers.
China
State-owned nuclear operators in Zhejiang and Guangdong provinces expand borated water monitoring capacity under revised GB standards for reactor safety. The country's national environmental ministry tightens discharge monitoring requirements for semiconductor fabs in the Yangtze River Delta. Shanghai-based industrial laboratories drive multi-parameter analyzer procurement for consolidated testing footprints.
Australia
Geochemical survey organizations in Western Australia pilot laser-induced breakdown spectroscopy for rapid ore grade assessment. The country's national mining regulator encourages real-time boron quantification to displace traditional fusion workflows. Queensland agricultural extension services deploy seasonal handheld analyzer rentals for wheat belt soil fertility mapping.
Boron Analyzer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision optics suppliers in Japan and Germany dominating benchtop production while Chinese electronics assemblers capture handheld assembly. The vendor base organizes around three strategic archetypes: diversified analytical instrumentation conglomerates, process control specialists with distributed system integration capabilities, and focused environmental monitoring boutiques. Competitive moves concentrate on strategic partnerships for reagent supply security and technology licensing for plasma-based detection platforms.
Among diversified analytical instrumentation conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions anchoring high-sensitivity pharmaceutical and research laboratory segments. Horiba Scientific exemplifies the specialized optical systems archetype, while Yokogawa Electric Corporation represents process control integration capabilities in East Asian manufacturing corridors. These three companies illustrate how vendor positioning diverges between laboratory precision and industrial durability requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Horiba Scientific |
| ABB Ltd. |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Endress+Hauser Group |
| Mettler Toledo |
| Agilent Technologies |
| Shimadzu Corporation |
| Others |
Supply Flow & Price Mechanics
REACH workplace exposure mandates gate qualified supply for boron analyzer manufacturers seeking premium-tier positioning in European semiconductor and chemical manufacturing corridors. Compliance with these ECHA-enforced restrictions requires reagent-grade certification and platinum-group-metal traceability that only a subset of precision optics suppliers can document, concentrating pricing power among certified vendors while forcing budget-tier competitors toward uncertified agricultural and educational segments.
Pricing Analysis
Short lead-time premiums of thirty to sixty days command fifteen to twenty-five percent markups over standard delivery schedules for spectrophotometric platforms, while spot inventory of handheld colorimetric units clears at distressed levels. Three-tier pricing structure across premium, standard, and economy levels separates ICH Q3D-validated pharmaceutical systems from municipal water utility configurations and agricultural field units. Price differentiation rests on ISO 17025 calibration certification and plasma-based detection capability. Cost compression in colorimetric tiers is intensifying because Chinese MEMS sensor producers are flooding environmental monitoring channels. Municipal laboratories exhibit highest price sensitivity; nuclear utilities demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in China's GB standard compliance framework are reshaping sourcing for reactor safety instrumentation, forcing foreign vendors to localize final assembly in Zhejiang and Guangdong provinces. Manufacturing concentrates in Japan, Germany, and China, with precision optics fabrication anchored in Japanese and German industrial clusters and handheld assembly gravitating toward Chinese electronics corridors. Platinum electrode supply draws from South African and Russian refining operations. Single-source vulnerability in pharmaceutical-grade solvent supply for azomethine-H synthesis threatens reagent cost stability. Distribution runs through analytical instrumentation distributors with certified service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The boron analyzer market sits in a technology-transition phase as laser-induced breakdown spectroscopy displaces fusion-and-dissolution workflows in mining and geochemical applications. Plasma-based detection platforms are rendering legacy spectrophotometric systems obsolete under evolving ISO 17294 standards.
For Market Incumbents: Extend service unbundling strategies to capture recurring revenue from municipal water utilities separating hardware procurement from reagent supply and calibration contracts. Deepen backward integration into platinum-group-metal electrode manufacturing to insulate against South African and Russian supply disruptions. Prioritize ICH Q3D validation investments to defend pharmaceutical QC segment share against mass spectrometry-coupled entrants. For New Entrants and Emerging Players: Environmental testing distributors represent the most accessible channel for handheld colorimetric units targeting rural United States municipalities with compressed EPA capital approval timelines. White-space concentration exists in Australian mining laboratories piloting rapid ore grade assessment and East Asian chemical manufacturing corridors requiring process analytics integration. Position through seasonal rental programs for agricultural soil testing cooperatives. For Investors and Strategic Acquirers: METI guidelines on nuclear safety instrumentation replacement in Japan is the leading indicator that boiling water reactor operator spending will accelerate. Long-term viability favors vendors with plasma-based detection roadmaps and distributed control system integration capabilities. Target acquisition archetype: specialized optical systems boutiques with REACH-compliant reagent supply chains. Watch for ISO 17294 standard finalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma-Based Detection Platform Development | Positions vendors for ISO 17294 compliance ahead of spectrophotometric obsolescence cycles. |
| Reagent Supply Security Partnerships | Locks in azomethine-H and curcumin sourcing amid pharmaceutical-grade solvent volatility. |
| Process Analytics Integration Capability | Captures East Asian chemical manufacturing corridor demand for Modbus-connected inline systems. |
| Service Unbundling and Contract Separation | Aligns procurement patterns of EPA-enforced municipal water utilities toward recurring revenue models. |
| REACH Workplace Exposure Monitoring Expansion | Redirects European industrial hygiene budgets toward networked ion-selective electrode arrays. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving nuclear chemistry laboratory directors, semiconductor fab water quality managers, environmental testing procurement officers, and analytical instrumentation distribution channel heads. EPA Safe Drinking Water Act enforcement databases, ECHA REACH restriction updates, METI nuclear safety instrumentation guidelines, and ICH Q3D implementation reports supplied regulatory trajectory inputs. Bottom-up unit shipment estimates by product type and technology triangulated against top-down spending patterns by end-use sector.
Data-stream reconciliation across detection methodology cost tiers, regional regulatory enforcement intensity, and replacement cycle timing generated volume and value outputs over the projection horizon. Segmentation dimensions modeled include product type, detection technology, end-user industry, application matrix, and geographic regulatory cluster. CAGRs were derived from instrument replacement timelines compressed by evolving compliance standards and technology obsolescence risk. Nuclear coolant chemistry specifications and semiconductor ultrapure water verification thresholds provided industry-specific forecast anchors.
Caveats apply where platinum-group-metal supply disruptions, ISO 17294 standard finalization timing, or ICH Q3D enforcement variance could materially shift the outlook. Forecasts reflect assumptions regarding regulatory implementation pace and technology substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Absorption Spectrometers Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
TDLAS Moisture Analyzers Market