
 Air Sampler Market | 2026-2036
Air Sampler Market Size, Share, and Industry Trends Forecast 2026-2036
Air Sampler Market Analysis
Buyer concentration among pharmaceutical contract manufacturers is hardening as top CDMOs consolidate environmental monitoring spend under enterprise frameworks. Thermo Fisher Scientific leverages its analytical instrument portfolio to bundle air sampling with chromatography workflows, while Sartorius anchors its position through membrane filtration adjacencies that lock in recurring consumables revenue. SKC Inc. competes on occupational safety specialization, sustaining channel control through industrial hygiene distributor networks that larger rivals struggle to replicate.
An air sampler is an instrument engineered to collect representative volumes of atmospheric or process gas for subsequent analysis of particulate, biological, or chemical contaminants, typically achieving flow rates between 2 and 100 liters per minute with calibrated vacuum pump or impaction mechanisms. Its primary commercial purpose is to generate defensible data for regulatory compliance, worker protection, and quality assurance in controlled environments. Active samplers dominate revenue due to their precision in pharmaceutical validation protocols, while passive samplers occupy the fastest-expanding margin pool in long-term ambient monitoring networks where low maintenance costs offset reduced temporal resolution. Filter samplers sustain entrenched demand in industrial stack testing and occupational dust assessment, though gravimetric technology faces displacement where real-time optical sensors achieve regulatory equivalency.
ISO 14698 cleanroom standards, FDA's sterile drug guidance, and EU GMP Annex 1 collectively mandate continuous viable and non-viable particle monitoring, forcing manufacturers to validate sampler recovery rates and calibration traceability. EPA reference methods for ambient air quality and OSHA permissible exposure limits further segment demand between regulatory-grade instrumentation and workplace screening devices. Stakeholders must weigh capital intensity against the risk of regulatory inspection findings that trigger costly production halts or consent decree exposure.
Market Dynamics
The FDA's updated Annex 1 sterile manufacturing guidance is compressing validation timelines and forcing pharmaceutical cleanroom operators to replace legacy environmental monitoring systems before scheduled end-of-life cycles, creating a forced-upgrade cycle across biologics production facilities.
Growth Catalysts
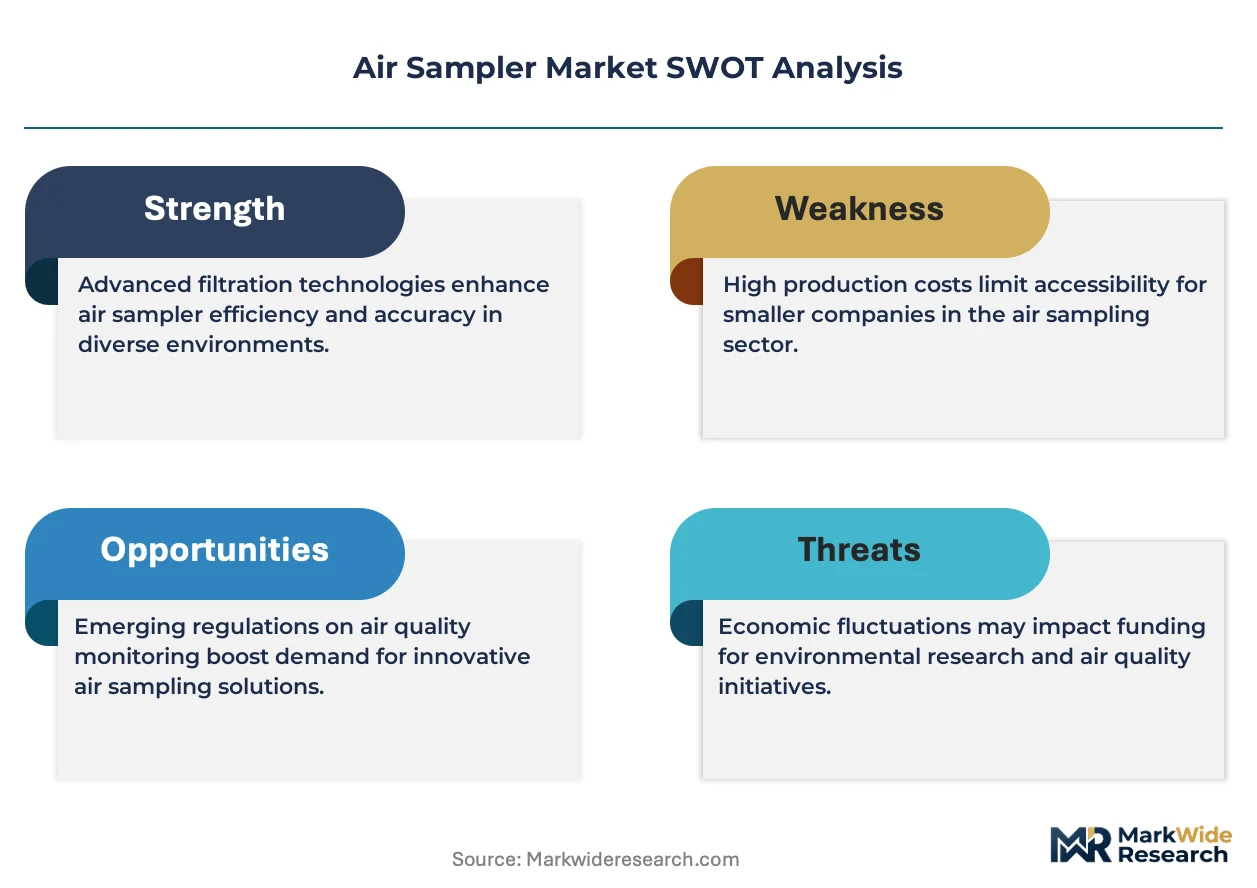
- EU GMP Annex 1 Revision:The tightened requirements for continuous viable particle monitoring in Grade A/B zones compel sterile drug manufacturers to install validated active air sampling systems with demonstrated recovery rates.
- Biologics Manufacturing Expansion:Cell and gene therapy production suites require expanded environmental monitoring protocols, driving instrument density per square meter of cleanroom space.
- Real-Time Optical Sensors:These devices are achieving regulatory equivalency with gravimetric methods in certain OSHA and EPA applications, opening substitution pathways in industrial hygiene monitoring.
Market Restraints
- Calibration Traceability Costs:ISO 17025-accredited calibration services for vacuum pump mechanisms and flow controllers impose recurring operational burdens that compress margin structures for smaller contract manufacturers.
- Filter Media Supply Concentration:Specialized membrane filtration materials for microbial impaction plates concentrate among limited European and Japanese suppliers, exposing buyers to lead-time volatility.
- Passive Sampler Temporal Resolution:The inherent limitation of diffusive collection methods—averaging contaminant levels over days or weeks—restricts deployment in pharmaceutical validation protocols requiring real-time alert capability.
Strategic Opportunities
- India Biopharma Manufacturing:CDSCO-aligned inspection regimes and PLI scheme incentives for domestic biologics production create replacement demand in emerging fill-finish facilities around Hyderabad and Bengaluru.
- Occupational Exposure Banding:OSHA's expanding emphasis on quantitative exposure assessment in pharmaceutical compounding operations extends air sampler deployment beyond traditional manufacturing into hospital pharmacy environments.
- Chromatography Workflow Integration:Converging air sampling data streams with analytical instrument suites enables automated environmental monitoring dashboards that reduce manual transcription errors.
Industry Challenges
- Metrology Talent Scarcity:Qualified technicians capable of executing ISO 14644-3 recovery testing and HEPA filter challenge protocols remain concentrated among specialized service providers, constraining in-house validation capacity expansion.
- Legacy System Integration:Pharmaceutical facilities operating 1990s-era building management systems face protocol incompatibility when connecting modern air samplers with digital output requirements, forcing parallel infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Sampler Market |
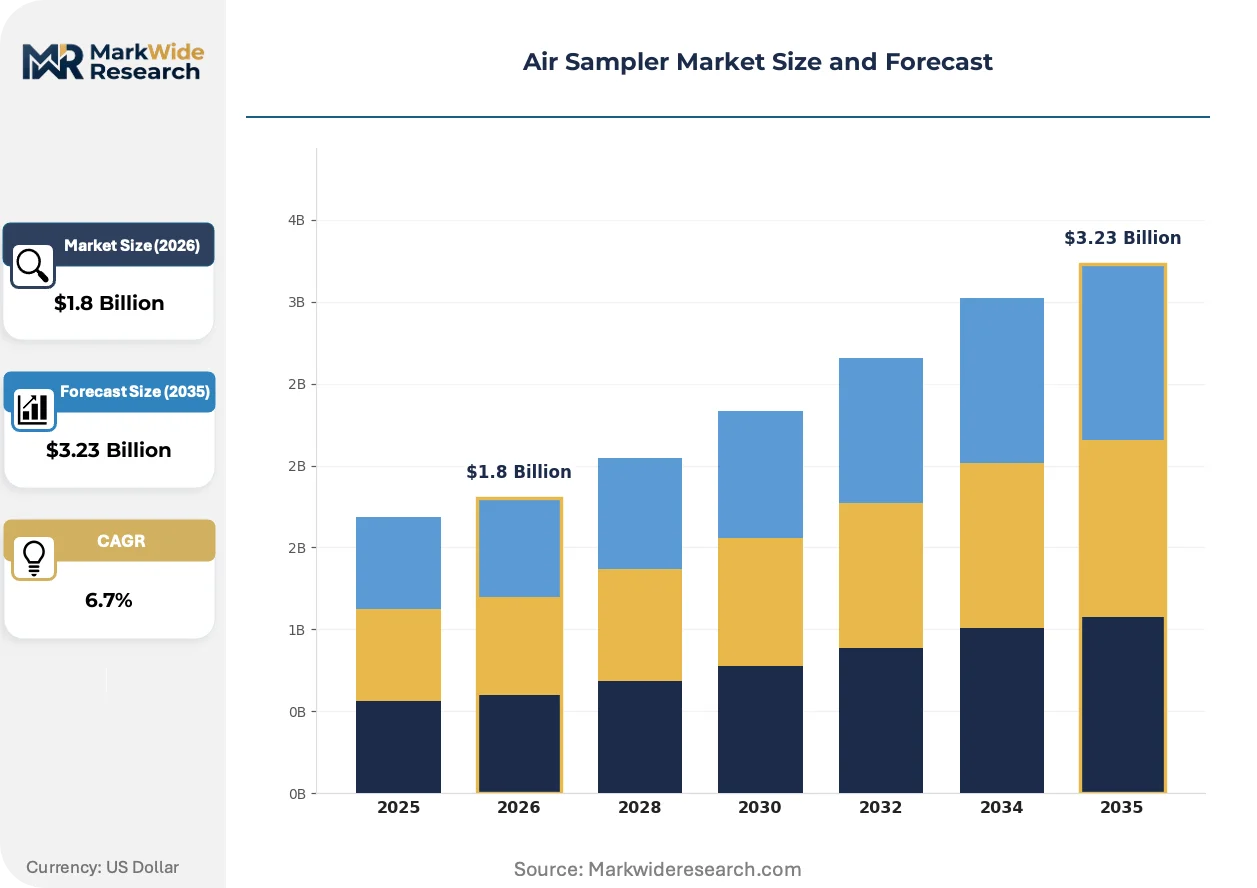
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Samplers, Passive Samplers, Integrated Samplers, Filter Samplers End User: Industrial Facilities, Research Laboratories, Environmental Agencies, Healthcare Settings Technology: Electrostatic, Gravimetric, Impaction, Chemisorption Application: Indoor Air Quality Monitoring, Ambient Air Monitoring, Occupational Safety, Pollution Control |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, SKC Inc., Sartorius, Merck KGaA, Teledyne Technologies, Bertin Technologies, Particle Measuring Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Sampler Market Emerging Trajectories
Portable battery-powered air sampling units are compressing the distinction between fixed installation and survey-grade instrumentation, enabling point-source investigation without permanent infrastructure commitment.
Wireless data transmission architecture is decentralizing environmental monitoring networks by eliminating hardwired connections between sampling heads and central processing units. Pharmaceutical contract manufacturers in Germany and Switzerland are deploying mesh-networked samplers across multi-suite facilities. This topology reduces installation costs in renovated cleanrooms while complicating cybersecurity validation under FDA 21 CFR Part 11 requirements.
REACH regulation amendments restricting per- and polyfluoroalkyl substances are forcing membrane filtration suppliers to reformulate hydrophobic venting materials used in microbial impaction plates. The industrial consequence is a 12-18 month qualification cycle for replacement chemistries before regulatory acceptance. Manufacturers serving EU pharmaceutical markets are accelerating dual-source strategies to mitigate single-supplier exposure during this transition window.
Consolidated procurement frameworks among top CDMOs are unbundling instrument purchase from service contracts, with enterprise buyers negotiating multi-site calibration and maintenance agreements separately from hardware acquisition. This behavior compresses vendor margin on initial equipment sales while extending customer lifetime value for service-capable suppliers. The pattern is most visible in North American and Western European pharmaceutical manufacturing clusters where three to five contract manufacturers control substantial regional instrument demand.
Air Sampler Market Segmentation
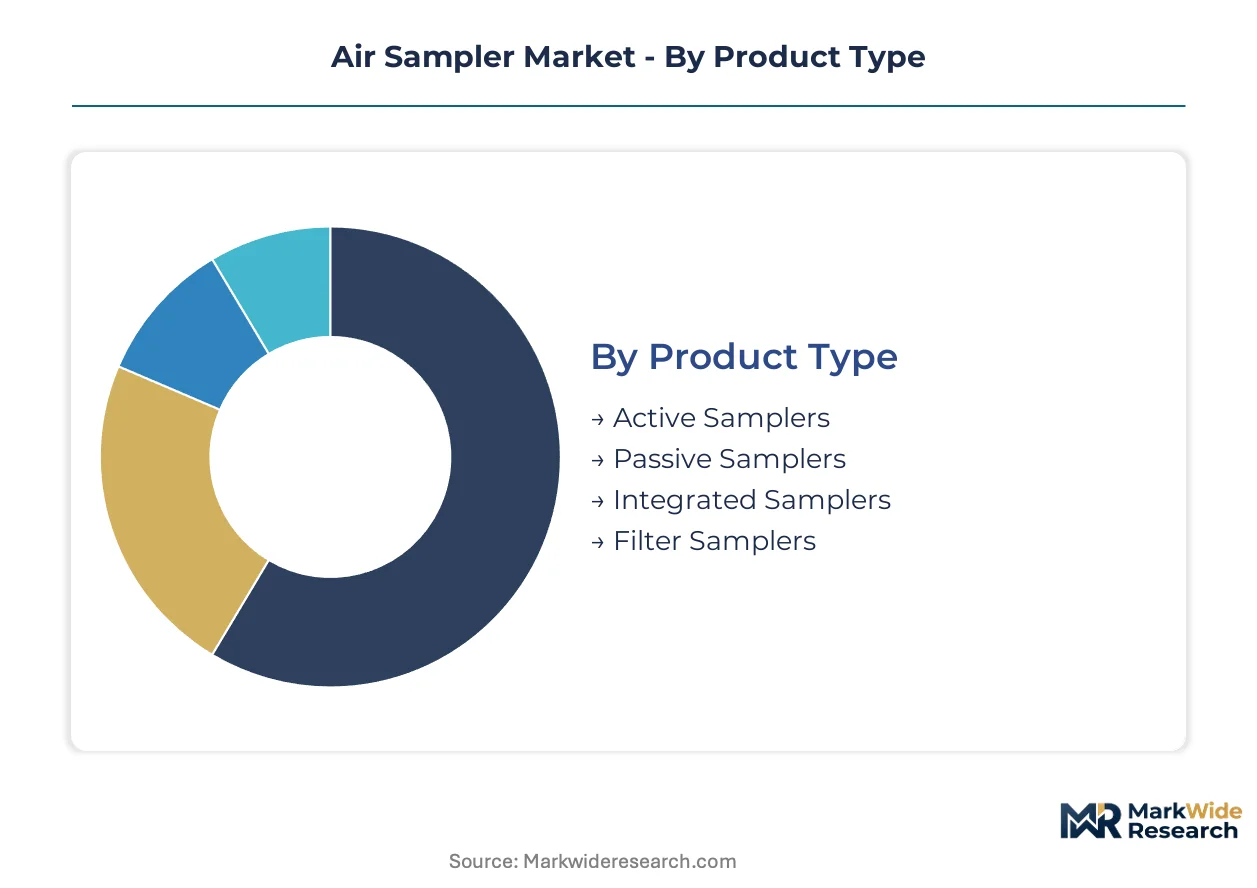
Air sampler procurement decisions pivot on validation requirements, maintenance burden, and integration complexity. Pharmaceutical buyers weight initial capital outlay against recurring calibration costs, while environmental agencies prioritize deployment flexibility across dispersed monitoring networks.
Product Type:
Cost tier and operational intensity shape buyer selection between precision instrumentation and low-maintenance alternatives.
- Active Samplers:Vacuum pump-driven systems achieve calibrated flow rates between 2-100 liters per minute with impaction or filtration mechanisms. Pharmaceutical cleanroom operators in Germany and Switzerland deploy these for continuous viable particle monitoring under EU GMP Annex 1, accepting higher capital and service costs for regulatory defensibility.
- Passive Samplers:Diffusive collection devices operate without powered airflow, averaging contaminant levels over extended deployment periods. Environmental agencies across France and the Netherlands favor these for long-term ambient monitoring networks where maintenance access proves costly, trading temporal resolution for operational simplicity.
- Integrated Samplers:Combined viable and non-viable particle detection units streamline building management system connectivity.
- Filter Samplers:Gravimetric collection on membrane media sustains entrenched demand in industrial stack testing and occupational dust assessment.
Volume sits with active samplers; growth tilts toward passive samplers.
End User:
Application maturity and regulatory stringency divide demand between established industrial protocols and emerging healthcare deployment.
- Industrial Facilities:Manufacturing plants and processing operations deploy air sampling for worker protection and emissions compliance. Chemical producers in Belgium and the Netherlands operate dense monitoring grids under REACH and national occupational exposure limits, driving replacement cycles as optical sensors achieve regulatory equivalency in select applications.
- Healthcare Settings:Hospital pharmacies and compounding suites extend environmental monitoring beyond traditional manufacturing. OSHA's expanding quantitative exposure assessment requirements in pharmaceutical compounding operations are penetrating acute care facilities across the United States, creating instrument demand in previously unserved clinical environments.
- Research Laboratories:Academic and contract research organizations employ samplers for controlled atmosphere validation and experimental reproducibility.
- Environmental Agencies:National and regional authorities operate ambient monitoring networks for regulatory reporting and public health surveillance.
Industrial facilities command the largest installed base; healthcare settings are climbing the fastest.
Technology:
Measurement principle determines accuracy, maintenance burden, and regulatory acceptance across jurisdictions.
- Impaction:Microbial impaction onto agar plates or membrane filters achieves direct colony enumeration with demonstrated recovery rates. Biologics manufacturers in Germany validate these systems under BfArM inspection regimes, accepting 12-18 month qualification cycles for alternative membrane chemistries as REACH restrictions on per- and polyfluoroalkyl substances force material transitions.
- Gravimetric:Mass-based particle collection on pre-weighed filters provides reference-grade measurement traceable to ISO 17025 standards. Industrial hygiene applications in the United States sustain demand despite optical sensor encroachment where EPA or OSHA methods mandate gravimetric equivalence.
- Electrostatic:Charged particle precipitation enables high-efficiency collection with minimal pressure drop.
- Chemisorption:Reactive surface capture targets specific gaseous contaminants at trace concentrations.
Impaction dominates pharmaceutical validation; electrostatic methods are gaining share fastest in portable survey applications.
Application:
Regulatory driver and temporal resolution requirements segment deployment between continuous monitoring and periodic assessment.
- Occupational Safety:Workplace exposure assessment mandates personal and area sampling against permissible exposure limits. Industrial facilities in the United States operate under OSHA enforcement priorities for quantitative exposure assessment, driving instrument density in pharmaceutical compounding and chemical processing operations.
- Indoor Air Quality Monitoring:Commercial and institutional building validation focuses on particulate and biological contaminant control. Healthcare construction in India around Hyderabad and Bengaluru is embedding monitoring infrastructure during facility commissioning to meet CDSCO-aligned inspection expectations.
- Ambient Air Monitoring:Outdoor environmental surveillance tracks regional pollution patterns and regulatory compliance.
- Pollution Control:Industrial emission monitoring verifies stack and fugitive release containment.
Occupational safety holds the deepest installed base; indoor air quality monitoring is expanding most quickly in healthcare construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers in Germany and the United States concentrate instrument demand through enterprise procurement frameworks, while biologics production expansion in India and Switzerland creates secondary demand nodes for validated environmental monitoring systems.
United States
OSHA enforcement priorities for quantitative exposure assessment in pharmaceutical compounding operations extend air sampler deployment into hospital pharmacy environments. FDA's updated Annex 1 guidance on sterile manufacturing compresses validation timelines for biologics facilities. The Greater Boston and San Francisco Bay Area biotech clusters drive replacement cycles as cell and gene therapy production suites expand environmental monitoring protocols.
Germany
BfArM and EMA-aligned inspection regimes force cleanroom operators to demonstrate validated recovery rates and calibration traceability. EU GMP Annex 1 revision mandates continuous viable particle monitoring in Grade A/B zones. The Rhine-Main and Munich biologics manufacturing corridors concentrate replacement demand as facilities accelerate forced-upgrade cycles ahead of scheduled end-of-life.
Switzerland
Swissmedic inspection expectations align with EMA standards, driving pharmaceutical manufacturers toward enterprise-grade environmental monitoring systems. The country's dense contract manufacturing base prioritizes regulatory defensibility over capital cost minimization. Basel and Zurich pharmaceutical clusters deploy mesh-networked samplers across multi-suite facilities to reduce installation costs in renovated cleanrooms.
India
CDSCO-aligned inspection regimes and PLI scheme incentives for domestic biologics production create replacement demand in emerging fill-finish facilities. The country's national pharmaceutical regulator tightens environmental monitoring validation requirements for export-oriented manufacturing. Hyderabad and Bengaluru biopharma construction embeds monitoring infrastructure during facility commissioning to meet inspection expectations.
United Kingdom
MHRA post-Brexit regulatory alignment with EMA standards sustains demand for EU GMP Annex 1-compliant instrumentation. Pharmaceutical manufacturers navigate dual regulatory exposure across UK and continental European markets. The Cambridge and Oxford life science clusters maintain instrument density per square meter as cell therapy production expands.
Air Sampler Market Vendor Landscape
United States-based analytical instrument conglomerates anchor the premium tier; German and Swiss precision engineering specialists hold defensible positions in membrane filtration adjacencies. Market structure concentrates among five to eight vertically integrated players with service capabilities, while regional distributors control access to occupational safety segments. Two strategic archetypes dominate: chromatography-anchored platforms bundling air sampling into analytical workflows, and membrane filtration specialists locking in recurring consumables revenue. Competitive moves center on unbundling instrument sales from multi-site service contracts and converging environmental monitoring data with building management system architectures.
Within the analytical instrumentation tier, Thermo Fisher Scientific and Agilent Technologies exemplify platform bundling strategies that leverage existing chromatography customer relationships. Sartorius occupies a position among filtration-centric specialists where membrane consumables generate recurring revenue streams that offset hardware margin compression. SKC Inc. anchors the occupational safety segment through industrial hygiene distributor networks that larger rivals struggle to replicate.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| SKC Inc. |
| Sartorius |
| Merck KGaA |
| Teledyne Technologies |
| Bertin Technologies |
| Particle Measuring Systems |
| Others |
Supply Flow & Price Mechanics
Real-time optical sensor validation against gravimetric reference methods is compressing cost structures for industrial hygiene applications while concentrating procurement power among pharmaceutical contract manufacturers with enterprise-scale environmental monitoring frameworks. This technological substitution simultaneously erodes pricing power in legacy filter sampler segments and amplifies volume discounts for active sampling systems deployed under EU GMP Annex 1 compliance mandates.
Pricing Analysis
Volume concentrates in active samplers where pharmaceutical cleanroom operators absorb premium pricing for regulatory defensibility; margins compress fastest in passive sampler segments as environmental agencies prioritize operational simplicity over precision. Three-tier pricing structure across pharmaceutical-grade, industrial-hygiene, and survey-instrument levels differentiates based on calibration traceability and ISO 17025 certification status. Pricing pressure stems from consolidated procurement frameworks among top CDMOs unbundling hardware from service contracts. Hospital pharmacy environments show highest price sensitivity due to unfamiliarity with quantitative exposure assessment protocols; biologics manufacturers demonstrate lowest sensitivity given consent decree exposure risk.
Supply Chain Analysis
Reverse logistics for vacuum pump refurbishment and HEPA filter reclamation flows through specialized service providers concentrated in Germany, Switzerland, and the United States. Membrane filtration materials for microbial impaction plates draw from limited European and Japanese suppliers, creating single-source vulnerability as REACH amendments force per- and polyfluoroalkyl substance reformulation. Calibration gas standards and ISO 17025-accredited metrology services rest on regional laboratory networks with 12-18 month qualification cycles for alternative chemistries. Distribution runs through analytical instrument distributors serving pharmaceutical clusters, industrial hygiene specialists, and environmental monitoring agencies with divergent technical support requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time optical sensors achieving regulatory equivalency with gravimetric methods are displacing legacy filter samplers in occupational dust assessment, compressing the technology transition window for incumbent suppliers and creating white-space openings for portable survey-grade instrumentation.
For Market Incumbents: Deepen membrane filtration adjacencies to lock in recurring consumables revenue as hardware margins compress under enterprise procurement consolidation. Accelerate service contract bundling across multi-site pharmaceutical manufacturing networks to offset unbundling pressure from top CDMOs. Prioritize ISO 14644-3 recovery testing capabilities as metrology talent scarcity constrains in-house validation capacity expansion among buyers. For New Entrants and Emerging Players: Industrial hygiene distributor networks offer the most penetrable channel structure for portable battery-powered units targeting hospital pharmacy compounding suites under OSHA quantitative exposure assessment expansion. Target India biopharma construction in Hyderabad and Bengaluru where CDSCO-aligned inspection regimes create first-mover advantage for integrated environmental monitoring infrastructure. Deploy chromatography workflow integration as the primary go-to-market angle to differentiate from established active sampler suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to analytical instrument conglomerates seeking environmental monitoring platform expansion over the coming decade. Acquisition targets should display service revenue exceeding hardware sales and demonstrated FDA 21 CFR Part 11 compliance for pharmaceutical validation protocols. Monitor BfArM and EMA inspection finding trends for early signals of forced-upgrade cycle intensity across German biologics manufacturing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Chromatography Workflow Integration | Converges air sampling data with analytical instrument suites to automate environmental monitoring dashboards and reduce manual transcription errors in pharmaceutical facilities. |
| Multi-Site Service Contract Expansion | Extends customer lifetime value through calibration and maintenance agreements unbundled from initial hardware sales under consolidated CDMO procurement frameworks. |
| Membrane Chemistry Qualification Acceleration | Mitigates single-supplier exposure during REACH-mandated per- and polyfluoroalkyl substance transitions through dual-source strategies for hydrophobic venting materials. |
| Wireless Mesh Network Deployment | Reduces installation costs in renovated cleanrooms across Basel and Zurich pharmaceutical clusters while complicating cybersecurity validation under FDA 21 CFR Part 11. |
| Hospital Pharmacy Channel Penetration | Captures OSHA-driven quantitative exposure assessment demand in previously unserved clinical environments extending beyond traditional manufacturing operations. |
Methodological Framework
Independent corroboration across cleanroom validation engineers, pharmaceutical quality assurance directors, and industrial hygiene consultants underwrites the qualitative findings on procurement behavior and regulatory compliance drivers. Secondary validation draws from FDA guidance documents, EMA inspection reports, ISO 14698 cleanroom standards, and OSHA enforcement memoranda. Bottom-up instrument demand estimates triangulate against top-down pharmaceutical manufacturing capacity expansion data across the analysis window.
Rate-of-change decomposition separates volume growth from price trajectory across active sampler, passive sampler, and filter sampler product categories, with additional segmentation by end-user type and measurement technology. CAGRs derive from regression analysis of historical replacement cycles and regulatory-driven forced-upgrade patterns, incorporating biologics manufacturing expansion rates and cell therapy facility commissioning timelines as industry-specific demand inputs.
Caveats apply where FDA inspection priority shifts or REACH amendment implementation delays could materially shift the outlook for membrane filtration material qualification timelines. Practitioners should monitor BfArM inspection finding publication rates and CDSCO guidance revision schedules for early signals of validation requirement stringency changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Discrete Analyzers Market
Analytical Instruments
Vapor Pressure Analyzer Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Automated Microscopy Market
Analytical Instruments
Dew Point Analyzer Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market