
 Digital Vernier Caliper Market | 2026-2036
Digital Vernier Caliper Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Vernier Caliper Market Insights
Aftermarket calibration services is fragmenting across regional service networks and OEM-certified centers, eroding centralized margin pools that once flowed to original manufacturers. Mitutoyo Corporation sustains dominance through captive calibration networks and direct institutional relationships. Fowler High Precision competes on value-engineered product lines for mid-tier machine shops. Sylvac differentiates via Bluetooth-enabled digital interfaces that integrate with shop-floor data systems.
A digital vernier caliper is a precision linear measurement instrument combining a sliding jaw assembly with an electronic digital display, typically resolving to 0.01 mm or 0.0005 inches via capacitive or inductive encoder strips. Its primary industrial purpose is dimensional verification of machined components, castings, and formed parts against engineering tolerances. Electronic product variants with data output capability command the strongest margin pools as manufacturers pursue automated quality documentation. Educational end-user demand is shifting toward lower-cost units with simplified interfaces, while aerospace buyers prioritize water-resistant models certified to contamination-controlled environments.
ISO 17025 calibration standards, China's GB/T measurement regulations, and the EU's CE marking requirements collectively shape product design, export eligibility, and recurring service revenue structures for instrument vendors. Japan's METI industrial standards and the United States' NIST-traceable calibration mandates further segment market access by certification depth. Stakeholders must monitor whether emerging factory-automation protocols force open digital interfaces or reinforce proprietary data formats.
Market Dynamics
Automotive quality control departments are expanding procurement of connected metrology tools, forcing instrument vendors to embed data-output capabilities into standard product lines or surrender margin to aftermarket integrators.
Growth Catalysts
- China's dual carbon goals:GB standards now mandate tighter calibration traceability for imported instruments, compelling manufacturers to establish certified service networks within the country.
- Bluetooth-enabled digital interfaces:Shop-floor data systems in precision manufacturing clusters across Germany, Japan, and the United States require seamless instrument integration.
- Machine shops:Mid-tier fabrication facilities are retiring analog calipers to meet customer audit requirements for automated quality documentation.
Market Restraints
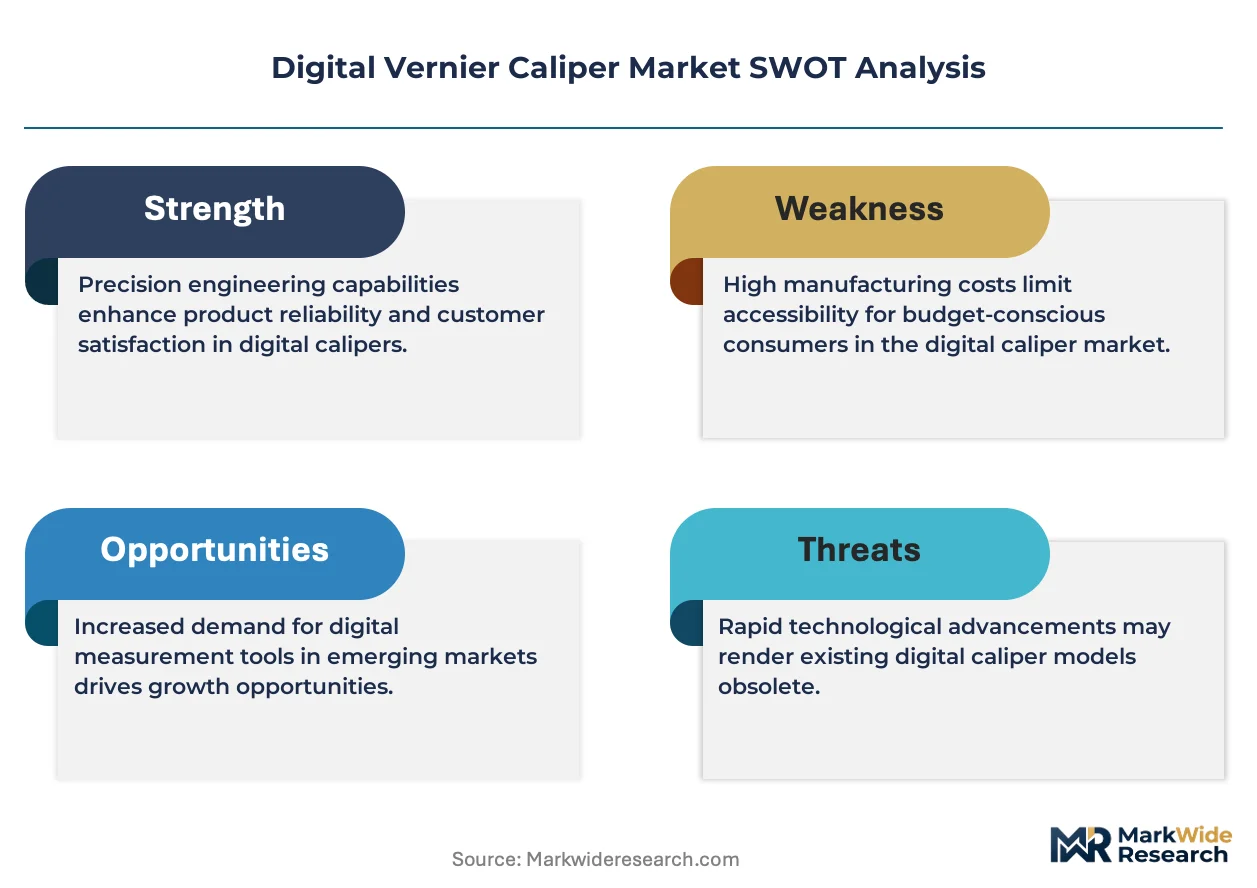
- Encoder strip supply concentration:Capacitive and inductive encoder manufacturing concentrates among a handful of Asian component suppliers, exposing vendors to input cost volatility.
- ISO 17025 certification timelines:Laboratory accreditation processes extend 12-18 months in key markets, delaying new entrant market access.
- Optical measurement substitution:Vision-based non-contact systems are displacing contact calipers in high-volume electronics assembly applications.
Strategic Opportunities
- Educational end-users:Technical training institutions in India and Southeast Asia represent underpenetrated demand for simplified-interface units at economy price points.
- EU Green Deal procurement mandates:Public sector metrology tenders increasingly specify energy-efficient instrument designs and recyclable packaging.
- 5G-enabled predictive calibration:Convergence of cellular connectivity and cloud-based asset management creates recurring revenue streams from usage-based maintenance contracts.
Industry Challenges
- Dimensional metrology technician scarcity:Specialized calibration and repair skills are concentrating among retiring workforce cohorts in mature manufacturing economies.
- Legacy ERP integration:Shop-floor data systems from the 1990s lack native digital instrument protocols, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Vernier Caliper Market |
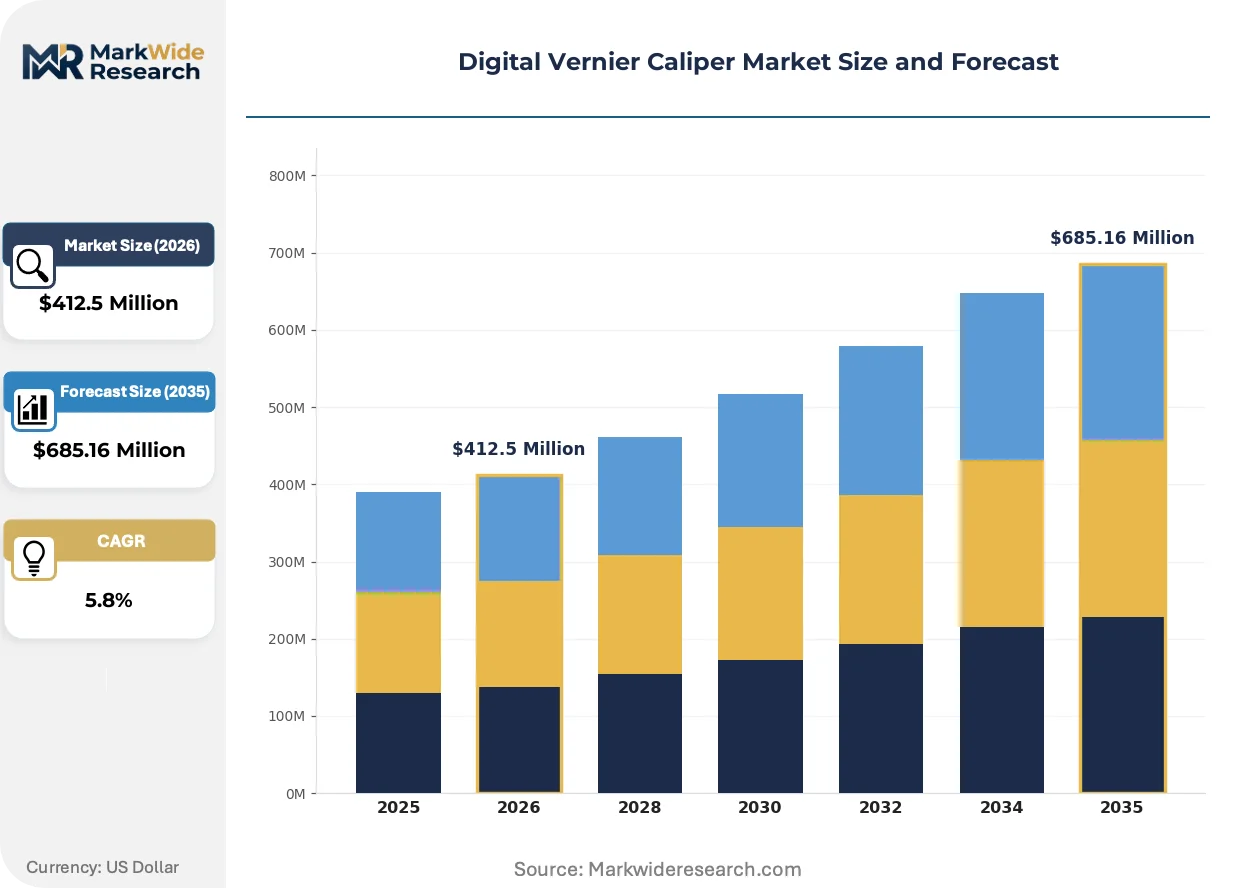
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic, Mechanical, Analog, Digital End User: Manufacturing, Aerospace, Automotive, Educational Feature: Water Resistant, Bluetooth Connectivity, Automatic Shutoff, Large Display Sales Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Mitutoyo Corporation, Starrett, Fowler High Precision, Hexagon AB, Sylvac, TESA, Moore & Wright, Baker Gauges, Guilin Measuring & Cutting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Vernier Caliper Market Trends and Innovations
Electronic product variants with data output capability are commanding the strongest margin pools as manufacturers pursue automated quality documentation and real-time statistical process control.
Capacitive encoder strips with enhanced resolution stability are digitizing dimensional verification workflows in aerospace contamination-controlled environments. Water-resistant caliper models certified to IP67 ratings are displacing standard units in coolant-heavy machining centers. The technology is digitizing audit trail generation, compressing the gap between measurement capture and quality system documentation from hours to seconds.
REACH substance restrictions and RoHS compliance mandates are reshaping material selection for electronic caliper housings and circuit assemblies. Vendors must reformulate plastic compounds and solder compositions to maintain CE marking eligibility. Aerospace buyers in Germany and France are prioritizing suppliers with demonstrated compliance documentation ahead of contract awards.
Aftermarket calibration services are fragmenting across regional service networks and OEM-certified centers, eroding centralized margin pools that once flowed to original manufacturers. Machine shops are unbundling instrument purchase from service contracts, selecting lowest-cost calibration providers regardless of instrument brand. This pattern is most visible in the United States, where NIST-traceable mandates create fungible service qualifications across competing vendor networks.
Digital Vernier Caliper Market Segmentation
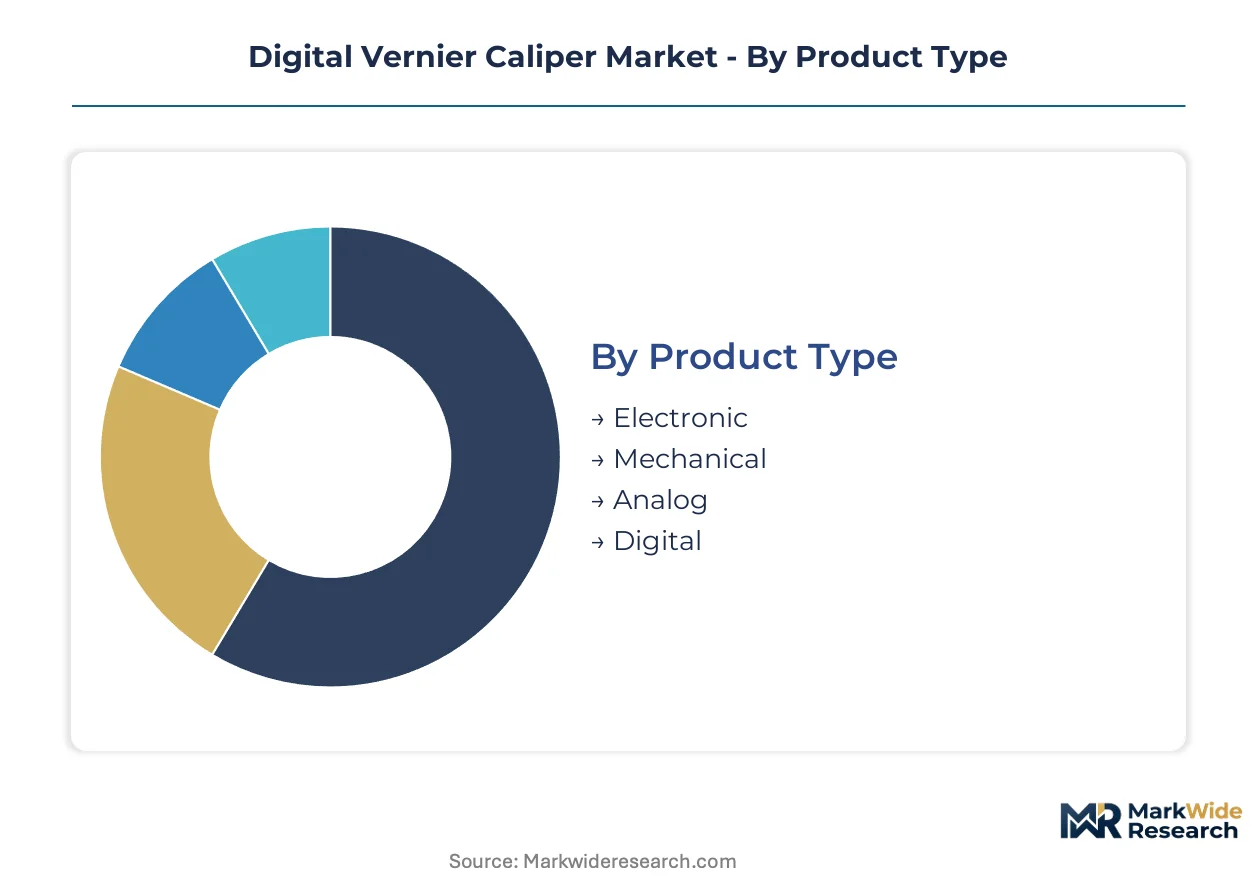
Segmentation in the digital vernier caliper market maps directly to procurement authority structures and certification requirements. Buyers organize specifications around environmental resilience, data connectivity, and institutional compliance rather than measurement resolution alone.
Product Type:
Use cases span from legacy quality documentation to automated shop-floor integration, with each product architecture carrying distinct margin and service attachment profiles.
- Electronic:Capacitive encoder strips deliver 0.01 mm resolution with RS-232 or USB data output. Automotive quality control departments in Stuttgart and Detroit specify electronic units for automated statistical process control integration.
- Digital:LCD displays with absolute encoding eliminate zero-reset errors during repetitive measurement sequences. Machine shops across Japan's Aichi Prefecture prioritize digital units for coolant-heavy environments where analog scales degrade.
- Mechanical:Rack-and-pinion drives with vernier scales serve educational institutions requiring durability without battery dependency.
- Analog:Traditional dial calipers persist in maintenance departments with limited metrology training budgets.
The dominant share belongs to Electronic, while Digital is closing the gap fastest.
End User:
Customer archetypes separate by audit intensity, with aerospace and automotive buyers imposing traceability requirements that educational and general manufacturing segments rarely match.
- Manufacturing:Contract machine shops and OEM component suppliers constitute volume demand, with procurement decisions driven by customer audit requirements for ISO 17025 calibration records.
- Aerospace:AS9100-certified suppliers in Toulouse and Seattle mandate water-resistant IP67 ratings and contamination-controlled packaging for coolant-exposed measurement tasks.
- Automotive:Tier-1 suppliers embed calipers into production line quality gates, requiring data-output capability for real-time SPC feedback.
- Educational:Technical training institutes in India and Vietnam source simplified-interface units at economy price points for introductory metrology instruction.
Manufacturing commands the largest procurement volume, though Aerospace generates the highest per-unit margins.
Feature:
Feature selection correlates with environmental exposure and data system maturity, creating tiered pricing architecture that vendors exploit for margin expansion.
- Water Resistant:IP67-rated sealing protects encoder electronics in machining centers using water-based coolants. German automotive suppliers specify these for 24/7 production environments.
- Bluetooth Connectivity:Wireless data transmission to shop-floor tablets eliminates cable management. Sylvac and Mitutoyo compete aggressively here for smart factory integration contracts.
- Automatic Shutoff:Battery conservation circuits extend operational life in intermittent-use maintenance applications.
- Large Display:Oversized LCDs accommodate aging workforces and dimly lit inspection stations.
Water Resistant features anchor standard product lines, while Bluetooth Connectivity is expanding most quickly among precision manufacturing clusters.
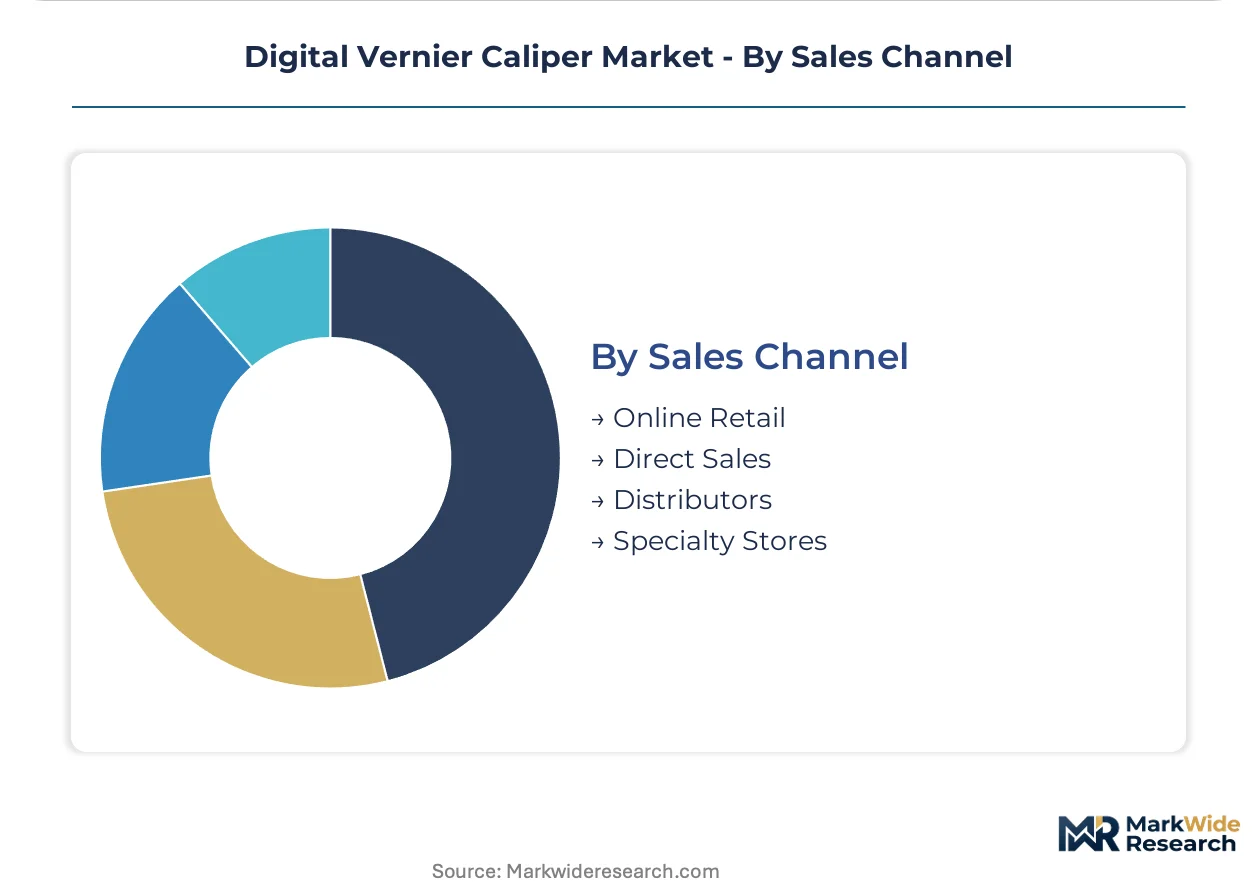
Sales Channel:
Channel structure reflects unbundling of instrument purchase from calibration service contracts, with buyers increasingly separating procurement decisions from ongoing metrology support.
- Distributors:Industrial supply houses with NIST-traceable calibration laboratories capture mid-tier machine shop volume across the United States.
- Direct Sales:OEM field engineers cultivate institutional relationships with automotive and aerospace quality directors, attaching multi-year service agreements to hardware purchases.
- Online Retail:Amazon Business and Alibaba serve educational buyers and small maintenance departments with minimal technical support requirements.
- Specialty Stores:Regional metrology equipment dealers in Japan and Germany provide same-day calibration turnaround for production-critical applications.
Distributors hold the deepest penetration, though Direct Sales is climbing the fastest as vendors pursue captive service revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Educational buyers in India and Southeast Asia demand economy-priced units with minimal calibration infrastructure, while aerospace procurement in Germany and the United States tolerates premium pricing for certified traceability. This elasticity divide shapes vendor portfolio strategy across geographies.
China
MIIT's GB/T measurement regulations and dual carbon goals mandate tighter calibration traceability for imported instruments, compelling foreign vendors to establish certified service networks in Shanghai and Shenzhen. Precision manufacturing clusters in Jiangsu and Zhejiang provinces drive replacement demand as domestic machine shops retire analog calipers to meet customer audit requirements.
Germany
Automotive Tier-1 suppliers in Stuttgart and Munich embed connected metrology tools into production line quality gates, requiring data-output capability for real-time statistical process control. KBA oversight of supplier quality systems reinforces ISO 17025 calibration mandates. The Baden-Württemberg precision engineering corridor concentrates demand for IP67-rated water-resistant models in coolant-heavy machining centers.
Japan
METI industrial standards segment market access by certification depth, with JIS-compliant instruments dominating institutional procurement in Aichi Prefecture's automotive supplier base. Nagoya-area machine shops prioritize digital units with absolute encoding to eliminate zero-reset errors in repetitive measurement sequences. Bluetooth-enabled interfaces from domestic vendors integrate with legacy shop-floor data systems prevalent in Chubu region factories.
United States
NIST-traceable calibration mandates create fungible service qualifications across competing vendor networks, enabling machine shops to unbundle instrument purchase from service contracts. Detroit automotive quality control departments specify electronic units with RS-232 or USB output for automated documentation. Industrial supply houses with captive calibration laboratories capture mid-tier volume across the Midwest and Southeast manufacturing belts.
India
BIS technical standards for measurement instruments are tightening import compliance requirements while PLI scheme incentives expand domestic precision manufacturing capacity. Technical training institutes in Maharashtra and Karnataka source simplified-interface units at economy price points for introductory metrology instruction. Pune and Chennai industrial corridors represent underpenetrated demand as contract fabrication facilities upgrade from analog to digital verification tools.
Digital Vernier Caliper Market Competitive Landscape
Captive calibration networks and direct institutional relationships split the market between integrated service providers and component-focused specialists. Mitutoyo Corporation sustains dominance through backward integration into certified service infrastructure that locks in multi-year automotive and aerospace contracts. Fowler High Precision competes on value-engineered product lines for mid-tier machine shops. Sylvac differentiates via wireless digital interfaces. M&A activity concentrates on regional calibration service acquisitions, while portfolio diversification pushes vendors into educational-market economy tiers.
Among Japanese precision instrument manufacturers, Mitutoyo Corporation exemplifies the integrated-service archetype through captive calibration networks. Fowler High Precision occupies a position within the value-engineered tier for North American machine shop demand. Sylvac sits within the connectivity-focused specialist segment, representing Bluetooth-enabled differentiation for smart factory integration. These three anchors illustrate the strategic vectors—service integration, cost engineering, and digital interface specialization—that define competitive positioning.
| Leading Market Players |
|---|
| Mitutoyo Corporation |
| Starrett |
| Fowler High Precision |
| Hexagon AB |
| Sylvac |
| TESA |
| Moore & Wright |
| Baker Gauges |
| Guilin Measuring & Cutting |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian encoder strip manufacturing is compressing component costs while simultaneously eroding supplier pricing power across the digital vernier caliper value chain. This utilization slack feeds directly into vendor procurement strategies, enabling mid-tier manufacturers to source capacitive and inductive encoder assemblies at favorable terms while OEMs with captive supply lines defend margin through backward integration into certified calibration networks.
Pricing Analysis
Aftermarket calibration service contracts generate the dominant share of lifetime value, with multi-year maintenance agreements often exceeding original hardware revenue by three-to-one ratios. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified units with IP67 ratings and NIST-traceable documentation from educational-market simplified interfaces. Cost compression in the mid-tier machine shop segment is intensifying because buyers unbundle instrument purchase from service contracts, selecting lowest-cost calibration providers regardless of brand. Educational end-users in India and Southeast Asia exhibit highest price sensitivity, while aerospace procurement in Germany and the United States tolerates premium positioning for certified traceability.
Supply Chain Analysis
Capacitive encoder strip feedstock draws from concentrated manufacturing bases in Japan, South Korea, and coastal China provinces. Raw material dependencies center on precision-machined aluminum extrusions, injection-molded ABS housings, and semiconductor-grade sensor substrates. Single-source vulnerability in inductive encoder componentry exposes vendors to input cost volatility when regional logistics chokepoints emerge. Distribution runs through industrial supply houses with captive NIST-traceable calibration laboratories across the United States Midwest and Southeast manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital vernier caliper market functions as a defensive-moat story where regulatory entrenchment locks in incumbent positions. ISO 17025 certification timelines extending 12-18 months create structural barriers that favor established players with accredited service infrastructure.
For Market Incumbents: Build captive calibration network moats by acquiring regional service centers in China and India before GB standards and BIS technical regulations tighten further. Optical measurement substitution in high-volume electronics assembly threatens contact caliper relevance, necessitating R&D investment in hybrid contact-non-contact instrument platforms. Backward integration into encoder strip manufacturing secures supply continuity against Asian component supplier consolidation.
For New Entrants and Emerging Players: India's technical training institutes in Maharashtra and Karnataka represent underpenetrated demand for economy-priced simplified-interface units. The educational segment offers lowest certification barriers and fastest procurement cycles among all end-user archetypes. A direct-to-institution sales model bypassing distributor markups captures price-sensitive volume while building brand recognition for eventual mid-tier manufacturing penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across educational-market economy tiers as offshore manufacturing scales and component standardization advances. Regional calibration service networks with established NIST-traceable or ISO 17025 credentials represent the most defensible acquisition targets, offering recurring revenue streams and customer lock-in. Monitor 5G-enabled predictive calibration contract signings as the signal for smart factory integration inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Acquisition | Captures recurring revenue streams from ISO 17025-accredited regional laboratories in China and the United States. |
| Bluetooth-Enabled Interface Development | Integrates with legacy shop-floor data systems prevalent in Japan's Chubu region automotive supplier base. |
| Educational Market Economy Tier Launch | Addresses underpenetrated demand from technical training institutes in India's Maharashtra and Karnataka states. |
| IP67 Water-Resistant Product Line Expansion | Meets AS9100-certified aerospace supplier requirements in Toulouse and Seattle contamination-controlled environments. |
| Predictive Calibration Platform Partnership | Leverages 5G connectivity and cloud-based asset management for usage-based maintenance contract revenue. |
Research Methodology
Operator-level perspectives from quality control directors at automotive Tier-1 suppliers, calibration laboratory managers, metrology equipment distributors, and technical training institute procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, SEC filings from precision instrument manufacturers, NIST calibration registry records, and GB standards documentation from China's MIIT. Bottom-up demand modeling across end-user segments triangulated with top-down macroeconomic indicators to establish volume and value parameters.
Scenario-bracketing framed the analytical approach, with sensitivity testing across automotive production volatility, educational procurement budget cycles, and aerospace certification timeline variations over the projection horizon. Segmentation dimensions modeled included product architecture, end-user audit intensity, environmental resilience requirements, data connectivity protocols, and regional regulatory cluster. CAGRs were derived from instrument replacement cycle analysis, customer audit requirement diffusion rates, and shop-floor automation adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by optical measurement system vendors or unlicensed calibration service networks would shift outcomes. Cross-checking against IHS Markit industrial production indices and regional manufacturing PMI surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Micro Balances Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Portable Gas Chromatograph Market