
 Laser Scanning Microscopes Market | 2026-2036
Laser Scanning Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Scanning Microscopes Market Foresight
OEM-direct and specialty distributor channels is reconfiguring how laser scanning microscopes reach end users in pharmaceutical and semiconductor verticals. Carl Zeiss leverages its captive optics foundry to control component quality from objective lenses to scan heads. Leica Microsystems sustains dominance in neurobiology applications through deep integration with tissue clearing protocols. Nikon Corporation competes aggressively in Asia-Pacific materials science labs with localized service infrastructure.
Laser scanning microscopes employ galvanometer-driven mirrors to raster-scan a focused laser beam across a specimen, collecting fluorescence or reflected light through a confocal pinhole to generate optical sections with sub-micron resolution; systems typically operate at frame rates of 1-30 Hz and wavelengths from 405 nm to 640 nm for live-cell and fixed-sample imaging. Confocal microscope hardware retains the largest installed base but generates thinner margin pools as replacement cycles lengthen. Multiphoton microscope configurations command premium positioning in deep-tissue neuroimaging where phototoxicity constraints dominate experimental design. Digital holographic imaging technology is displacing traditional phase-contrast methods in semiconductor wafer inspection applications.
FDA 21 CFR Part 11 compliance requirements shape software architecture decisions for clinical laboratory deployments, while the EU MDR and IVDR frameworks impose design-history documentation burdens on manufacturers serving European pathology labs. ISO 13485 quality management certification operates as a de facto gate for access to pharmaceutical company procurement lists. Stakeholders must weigh regulatory validation costs against the margin premium available in clinical-grade instrument configurations as research funding cycles tighten across OECD economies.
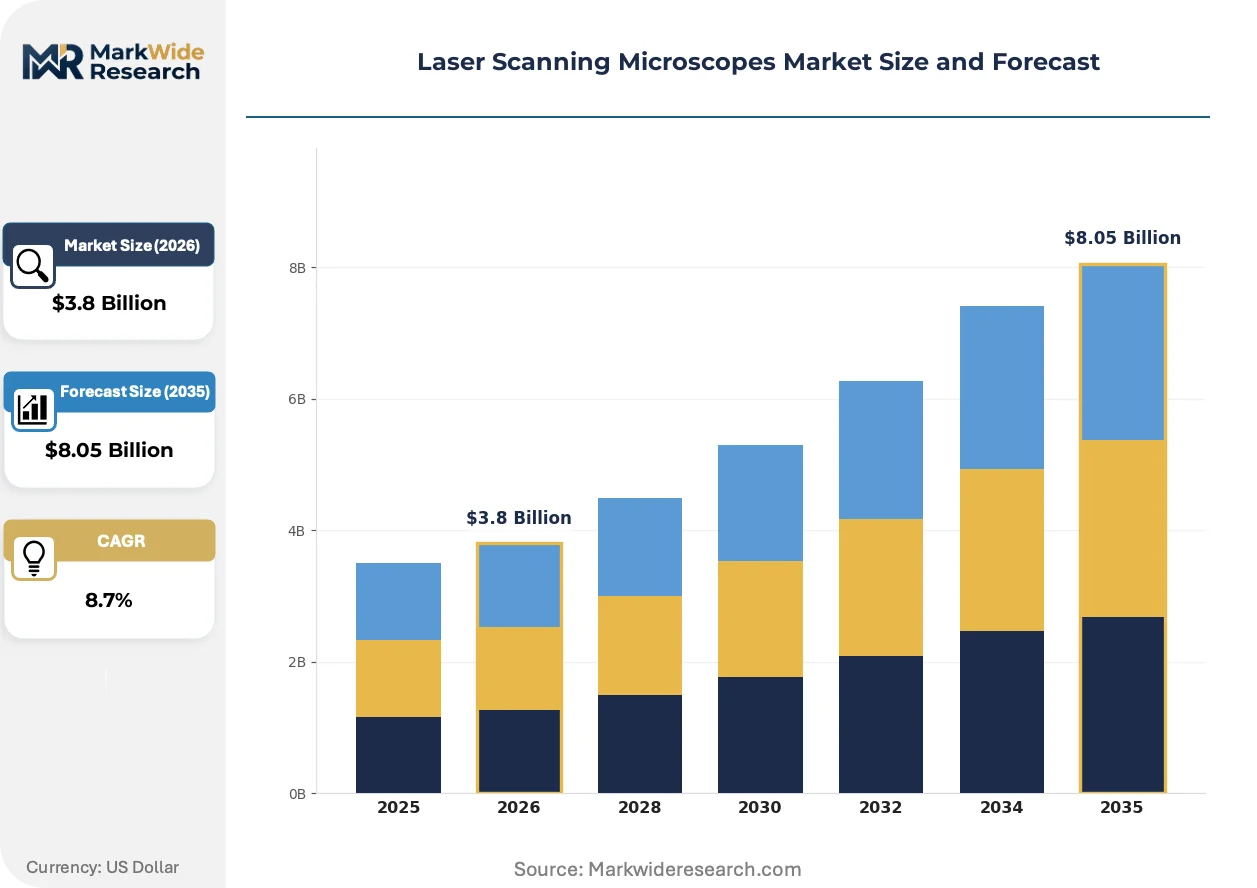
Market Dynamics
Pharmaceutical and semiconductor end-users are consolidating procurement around integrated imaging platforms that bundle hardware, software, and compliance validation, compressing vendor margins while raising barriers for component-only suppliers.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in US clinical laboratories are accelerating replacement cycles for non-compliant legacy systems, creating pull-through demand for validated software architectures.
- Deep-tissue neuroimaging:Multiphoton configurations are capturing expanded budgets in brain-mapping consortia where phototoxicity constraints render confocal methods unusable for living specimens.
- German precision optics cluster:Concentration of applied research institutions around Jena and Wetzlar generates localized demand spillover into adjacent Benelux and Nordic markets.
Market Restraints
- Objective lens supply concentration:German and Japanese specialty glass foundries control critical fluorite and apochromatic element production, exposing downstream OEMs to 12-18 month lead time volatility.
- EU MDR documentation burden:Design-history file requirements for clinical-grade instruments are extending product development timelines and freezing SME entrants out of European pathology lab procurement lists.
- Digital holographic substitution:Semiconductor wafer inspection applications are migrating toward label-free quantitative phase imaging, eroding addressable market for traditional laser scanning configurations in this vertical.
Strategic Opportunities
- India pharmaceutical CRO expansion:Contract research organizations in Hyderabad and Bengaluru are scaling preclinical imaging infrastructure, creating first-mover advantage for vendors establishing localized service depots.
- AI-assisted image analysis convergence:Integration of deep-learning segmentation tools with acquisition hardware is enabling premium pricing for autonomous workflow systems in high-throughput screening environments.
- EU AI Act validation protocols:Automated imaging classification requirements are mandating algorithmic transparency standards that favor incumbent OEMs with established quality management systems.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in laser cavity design and adaptive optics is concentrating at a handful of academic programs, constraining R&D scaling for mid-tier manufacturers.
- ISO 13485 certification timelines:Eighteen-to-twenty-four month quality system audits are delaying market entry for clinical-grade product lines, locking revenue recognition into distant fiscal periods.
- Legacy system integration friction:Pharmaceutical IT departments face mounting complexity bridging proprietary file formats from installed confocal bases with modern cloud-based data lakes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Scanning Microscopes Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Confocal Microscope, Multiphoton Microscope, Spinning Disk Microscope, Fluorescence Microscope Technology: Laser-Based Imaging, Digital Holographic Imaging, Adaptive Optics, High-Content Screening Application: Biological Research, Materials Science, Semiconductors, Pathology End User: Research Institutions, Pharmaceutical Companies, Academic Laboratories, Clinical Laboratories |
| Companies Covered | Carl Zeiss, Leica Microsystems, Olympus Corporation, Nikon Corporation, Bruker Corporation, Thorlabs, Motic Instruments, Thomas Scientific, Hitachi High-Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Scanning Microscopes Market Shifts & Advancements
Computational imaging methods are displacing purely hardware-based resolution enhancement, while regulatory frameworks on both sides of the Atlantic are hardening software validation requirements into competitive differentiators rather than check-box compliance exercises.
Adaptive optics modules with deformable mirrors and wavefront sensors are digitizing aberration correction that previously required painstaking manual alignment, enabling live-cell imaging at depths exceeding 500 micrometers. Neurobiology departments at Max Planck Institutes and Howard Hughes Medical Institute campuses are adopting these configurations at replacement-cycle velocity. The technology is digitizing service revenue models by embedding predictive maintenance algorithms that anticipate mirror degradation before image quality degradation becomes experiment-compromising.
REACH restrictions on fluorinated optical coatings are forcing reformulation of anti-reflective treatments for ultraviolet-excitation objectives, compressing supplier margins while extending qualification timelines. German and Swiss component vendors are absorbing the bulk of retooling costs, passing through partial recovery via tiered pricing to OEM customers. Clinical microscopy segments serving European pathology networks are most exposed, with procurement committees now requiring explicit substance compliance declarations in tender documentation.
Research consortia are unbundling after-sales service contracts from hardware acquisition, opting instead for multi-vendor maintenance pools managed by third-party scientific equipment specialists. This behavior is disrupting the traditional captive-service model that sustained Nikon and Zeiss profitability in Asia-Pacific materials science installations. The shift is most visible in Singapore and South Korea, where national research foundation procurement guidelines now explicitly favor competitive service bidding separated from capital equipment awards.
Laser Scanning Microscopes Market Segmentation
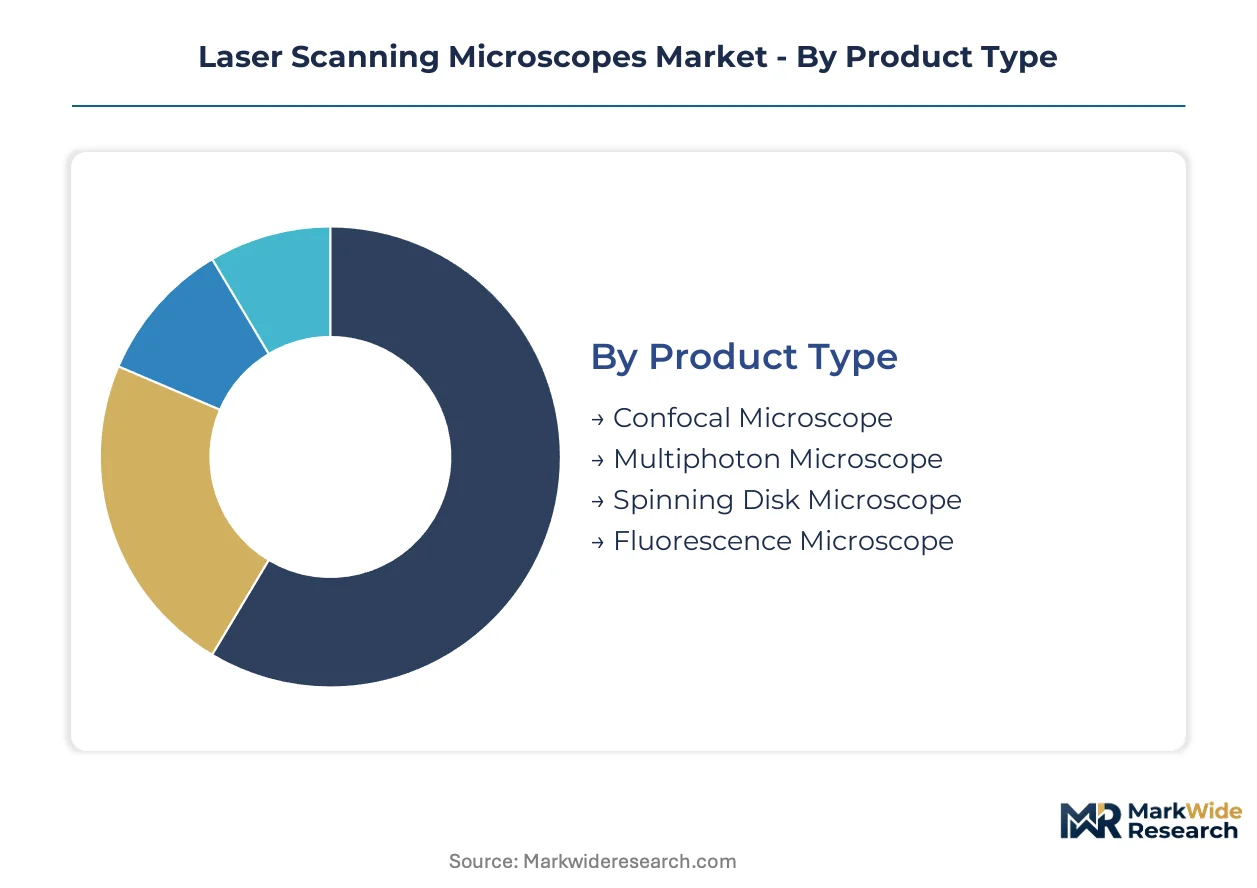
Segmentation in laser scanning microscopes separates configurations by optical depth capability, software validation tier, and end-use compliance burden. Pharmaceutical procurement committees weight 21 CFR Part 11 readiness as heavily as resolution specifications when evaluating capital allocations.
Product Type:
Cost tier differentiation across product types reflects capital intensity, service revenue potential, and replacement cycle velocity.
- Confocal Microscope:Galvanometer-mirror raster systems with pinhole-based optical sectioning dominate installed bases in fixed-cell pathology workflows. Pharmaceutical quality control labs in Germany and Massachusetts concentrate procurement here, though margin compression accelerates as replacement cycles extend beyond seven years.
- Multiphoton Microscope:Ti:sapphire laser sources enable excitation at 800-1100 nm wavelengths, penetrating tissue depths exceeding 500 micrometers with minimal phototoxicity. Howard Hughes Medical Institute campuses and Max Planck neurobiology departments drive demand where living specimen constraints exclude confocal methods.
- Spinning Disk Microscope:Nipkow disk configurations sacrifice some optical sectioning purity for frame rates reaching 100 Hz, serving high-throughput screening environments.
- Fluorescence Microscope:Widefield epifluorescence systems with laser illumination retrofit paths retain presence in budget-constrained academic settings.
Confocal configurations command the established base. The steepest expansion runs through multiphoton systems.
Technology:
Technology segmentation tracks the displacement of hardware-dependent resolution enhancement by computational and adaptive methods.
- Laser-Based Imaging:Conventional galvanometer-scanning architectures with solid-state laser sources from 405 nm to 640 nm retain dominance in clinical-grade configurations requiring FDA-validated optical paths.
- Digital Holographic Imaging:Quantitative phase imaging without fluorescent labels is displacing traditional laser scanning in semiconductor wafer inspection, eroding addressable market for confocal methods in this vertical.
- Adaptive Optics:Deformable mirror modules with wavefront sensor feedback correct spherical aberration in deep-tissue neuroimaging.
- High-Content Screening:Integrated plate-handling robotics with AI-assisted segmentation serve pharmaceutical lead-optimization workflows.
Laser-based imaging anchors current revenue. Digital holographic methods are climbing the fastest as semiconductor fabs retool inspection lines.
Application:
Application segmentation reveals divergent compliance burdens and funding stability across research versus industrial end-uses.
- Biological Research:Live-cell and fixed-specimen imaging with sub-micron resolution requirements consumes the largest share of multiphoton and confocal shipments, concentrated at NIH-funded institutions and European Research Council grant holders.
- Materials Science:Reflected-light confocal configurations with ultraviolet excitation serve metallurgical and polymer characterization, with Nikon Corporation capturing share through localized Asia-Pacific service infrastructure.
- Semiconductors:Wafer-level defect inspection is migrating toward label-free phase imaging, compressing traditional fluorescence-based laser scanning penetration.
- Pathology:Clinical diagnostic deployments require ISO 13485-certified hardware with 21 CFR Part 11 software validation, freezing out non-compliant vendors.
Biological research holds the deepest installed base. Materials science applications are expanding most quickly in Asia-Pacific national laboratory procurement.
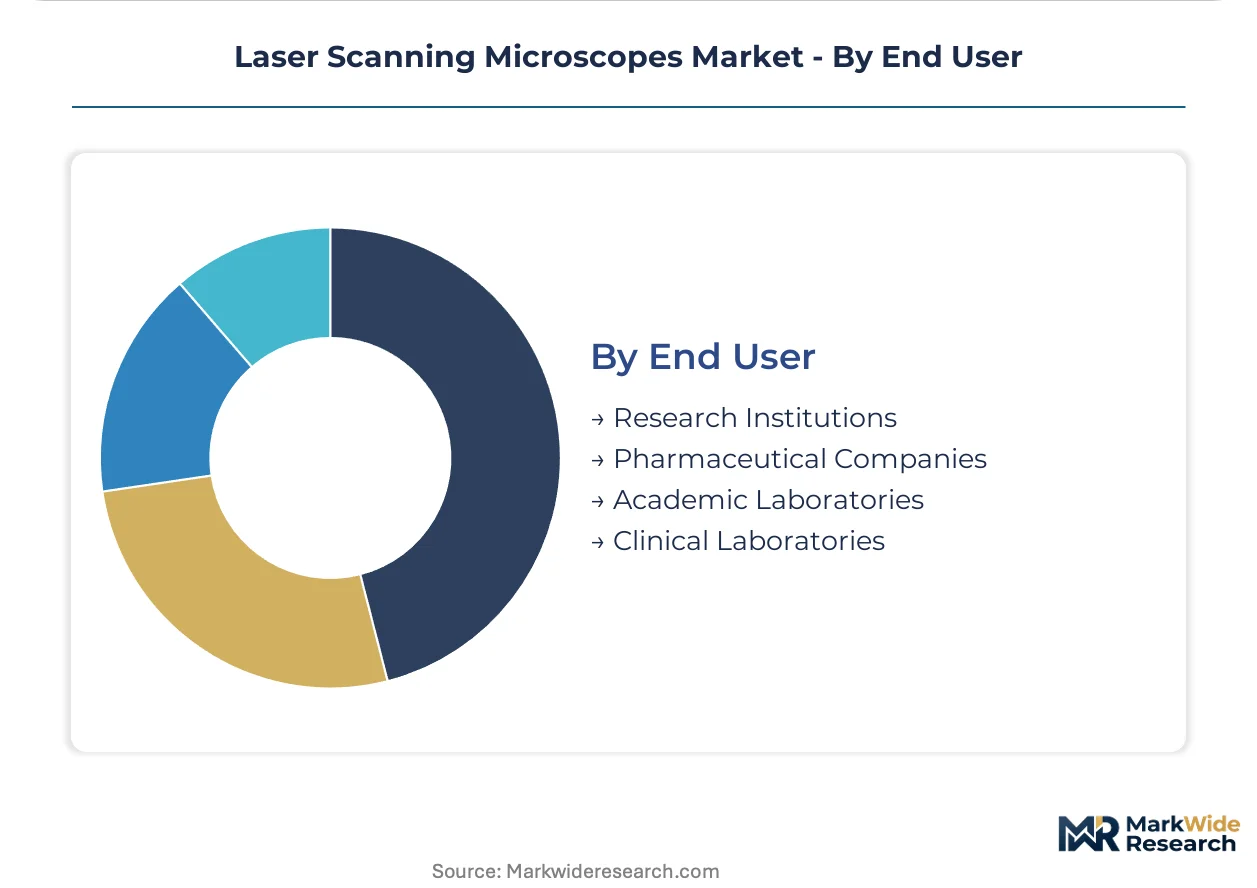
End User:
End user segmentation distinguishes funding stability, procurement cycle length, and service contract attachment rates.
- Research Institutions:Howard Hughes Medical Institute, Max Planck Society, and RIKEN centers operate on multi-year equipment refresh cycles with captive service capabilities, pressuring OEM service margins.
- Pharmaceutical Companies:Pfizer, Novartis, and Roche imaging cores demand bundled validation documentation for 21 CFR Part 11 compliance, consolidating procurement around integrated platform vendors.
- Academic Laboratories:University core facilities face NIH budget flatness, extending replacement timelines and favoring refurbished or entry-tier configurations.
- Clinical Laboratories:Hospital pathology networks in Germany and the US require MDR and FDA-compliant instruments with design-history file traceability.
Pharmaceutical companies dominate premium-tier purchasing. Clinical laboratories are gaining share fastest as diagnostic imaging digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main logistics corridor channels precision optics exports from central Germany to pharmaceutical hubs across the continent, underwriting Europe's dominance in high-end instrument manufacturing.
Germany
Pharmaceutical quality control labs in Frankfurt and Heidelberg drive confocal system procurement for drug stability testing. The EU MDR framework mandates design-history documentation for clinical-grade instruments, extending product development timelines. Jena and Wetzlar host dense clusters of applied research institutions and precision optics foundries that generate localized demand spillover.
United States
NIH-funded institutions in Bethesda and Boston operate multi-year equipment refresh cycles for live-cell imaging infrastructure. FDA 21 CFR Part 11 electronic records requirements accelerate replacement cycles for non-compliant legacy systems. Howard Hughes Medical Institute campuses concentrate multiphoton adoption where deep-tissue neuroimaging constraints dominate experimental design.
Japan
Materials science laboratories at RIKEN centers and national universities sustain reflected-light confocal demand for metallurgical characterization. METI funding programs support domestic precision manufacturing capabilities in optical component supply. Osaka and Tokyo metropolitan areas anchor semiconductor wafer inspection applications migrating toward phase imaging methods.
India
Contract research organizations in Hyderabad and Bengaluru scale preclinical imaging infrastructure for pharmaceutical outsourcing workflows. CDSCO regulatory alignment with international standards enables contract manufacturing organization integration with global drug development pipelines. National research foundation procurement guidelines in Delhi-NCR increasingly favor competitive service bidding separated from capital equipment awards.
South Korea
National laboratory procurement in Daejeon-Sejong concentrates materials science imaging for advanced materials characterization. MFDS medical device regulations impose quality system requirements that parallel FDA and EU frameworks for clinical-grade instrument entry. Busan-Ulsan industrial corridors sustain semiconductor inspection demand despite migration toward holographic phase methods.
Laser Scanning Microscopes Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors that bundle hardware, software, and compliance validation documentation. Tiered competitive positioning separates captive-optics manufacturers from component-assemblers and regional service specialists. Strategic archetypes include vertically integrated precision optics houses, Asia-Pacific service infrastructure builders, and adaptive optics technology licensors. Dominant competitive moves encompass strategic partnerships for AI-assisted image analysis integration and geographic expansion through localized service depot establishment.
Among German precision optics specialists, Carl Zeiss and Leica Microsystems exemplify the vertically integrated archetype through captive control over objective lens and scan head manufacturing. Nikon Corporation occupies a position within the Asia-Pacific service infrastructure tier, while Bruker Corporation represents the analytical instrumentation conglomerate archetype diversifying into imaging platforms. These three anchors illustrate how competitive positioning stratifies across manufacturing depth, geographic service density, and portfolio breadth rather than single-product specialization.
| Leading Market Players |
|---|
| Carl Zeiss |
| Leica Microsystems |
| Olympus Corporation |
| Nikon Corporation |
| Bruker Corporation |
| Thorlabs |
| Motic Instruments |
| Thomas Scientific |
| Hitachi High-Technologies Corporation |
| Others |
Supply & Pricing Matrix
German and Japanese specialty glass foundries controlling fluorite and apochromatic element production concentrate upstream margin capture, forcing downstream OEMs into tiered pricing architectures that separate FDA-validated clinical configurations from research-grade alternatives. This concentration pattern leaves objective lens supply as the primary cost driver across confocal and multiphoton system categories.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical procurement committees purchasing bundled validation packages from academic core facilities negotiating entry-tier configurations. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling depth. Cost compression in confocal replacement cycles intensifies as seven-year refresh timelines extend, while multiphoton systems retain pricing power through deep-tissue neuroimaging exclusivity. Academic laboratories exhibit highest price sensitivity; clinical pathology networks demonstrate lowest.
Supply Chain Analysis
Tariff exposure between Germany and China in precision optics components dominates supply chain risk assessment for downstream assemblers. Manufacturing concentrates in Germany, Japan, and Switzerland for critical fluorite elements, scan head assemblies, and adaptive optics modules. Raw material dependencies span rare-earth-doped laser crystals, ultraviolet-grade fused silica, and deformable mirror substrates. Single-source vulnerability in Ti:sapphire laser cavity production constrains multiphoton scaling. Distribution runs through OEM-direct channels and specialty scientific equipment distributors serving pharmaceutical and semiconductor verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser scanning microscopes market is reshaping around AI-assisted image analysis convergence and EU AI Act validation protocols, creating structural advantage for incumbents with established quality management systems while compressing timelines for new entrant certification.
For Market Incumbents: Entrench regulatory compliance as a competitive moat by accelerating FDA 21 CFR Part 11 software architecture investments ahead of replacement cycle peaks. Deepen backward integration into objective lens foundries to insulate margin pools from German and Japanese supply volatility. Prioritize adaptive optics module development to capture neurobiology department budgets at Howard Hughes Medical Institute and Max Planck Society campuses.
For New Entrants and Emerging Players: Preclinical imaging infrastructure at Hyderabad and Bengaluru contract research organizations represents the most penetrable entry point for vendors establishing localized service depots ahead of multinational incumbent expansion. AI-assisted segmentation tools for high-throughput pharmaceutical screening environments offer a differentiated go-to-market angle that bypasses capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated precision optics specialists with captive fluorite element production and established ISO 13485 certification timelines. Long-term viability across the analysis window favors manufacturers with clinical-grade instrument pipelines rather than research-only configurations. Monitor EU MDR documentation burden enforcement as a signal for which OEMs can sustain European pathology lab procurement access.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Optics Module Development | Deformable mirror systems enable 500-micrometer live-cell imaging at Max Planck neurobiology departments. |
| AI-Assisted Image Analysis Integration | Deep-learning segmentation tools command premium pricing in Pfizer and Novartis high-throughput screening environments. |
| Localized Service Depot Establishment | Hyderabad and Bengaluru infrastructure captures pharmaceutical CRO expansion ahead of Nikon and Zeiss regional buildout. |
| FDA 21 CFR Part 11 Software Validation | Electronic records compliance accelerates replacement cycles for legacy systems in US clinical laboratories. |
| Backward Integration into Objective Lens Foundries | Captive fluorite element production insulates Carl Zeiss and Leica Microsystems from 12-18 month supply volatility. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with microscopy core facility directors, pharmaceutical imaging platform managers, regulatory affairs specialists at precision optics manufacturers, and biomedical procurement officers at European pathology networks; alongside secondary validation through FDA 510(k) filings, EU MDR design-history documentation, SEC 10-K instrument segment disclosures, and NIH equipment grant award databases. Bottom-up triangulation across product type, technology, application, and end-user segments was cross-checked against top-down market sizing from installed base estimates and replacement cycle velocity.
Forecast inputs incorporated multiphoton adoption rates at neurobiology consortia, confocal replacement cycle extension patterns in academic settings, and semiconductor wafer inspection migration toward digital holographic methods. Segmentation dimensions modeled include optical depth capability, software validation tier, end-use compliance burden, and regional regulatory cluster. CAGRs were derived from weighted average replacement timelines and premium-tier penetration assumptions across pharmaceutical versus academic procurement channels.
Practitioners should monitor REACH restriction enforcement on fluorinated optical coatings, EU AI Act algorithmic transparency standard finalization, and NIH budget allocation shifts for early signals of forecast revision triggers. Macroeconomic funding contraction in OECD research economies, regulatory timeline acceleration for clinical-grade instruments, or breakthrough displacement in label-free quantitative phase imaging would prompt forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Global UV Spectroscopy Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Portable Chromatography Systems Market