
 ICP-OES Spectrometer Market | 2026-2036
ICP-OES Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
ICP-OES Spectrometer Market Outlook
Direct sales channels for analytical instrumentation is narrowing as vendors consolidate relationships with large environmental and mining laboratories. Agilent Technologies leverages its chromatography-installed base to cross-sell ICP-OES systems into existing pharmaceutical accounts. Thermo Fisher Scientific anchors its position through service contracts and consumables bundling that locks in multi-year customer commitments. PerkinElmer differentiates by specializing in high-throughput configurations tailored to agricultural testing cooperatives.
An inductively coupled plasma optical emission spectrometer excites liquid samples in an argon plasma torch at temperatures exceeding 6,000 Kelvin, then measures characteristic wavelengths emitted by ionized elements to quantify concentrations at parts-per-billion sensitivity. Its primary purpose centers on rapid multi-element analysis for regulatory compliance and process control across heavy industries. Benchtop systems dominate installed bases in routine quality control labs where throughput requirements are moderate and capital budgets are constrained. Portable configurations represent the fastest-expanding category, driven by demand for on-site mining assays and emergency environmental response where laboratory transport is impractical. Dual view technology captures both axial and radial plasma observations, extending dynamic range and capturing margin pools in semiconductor and high-purity materials applications.
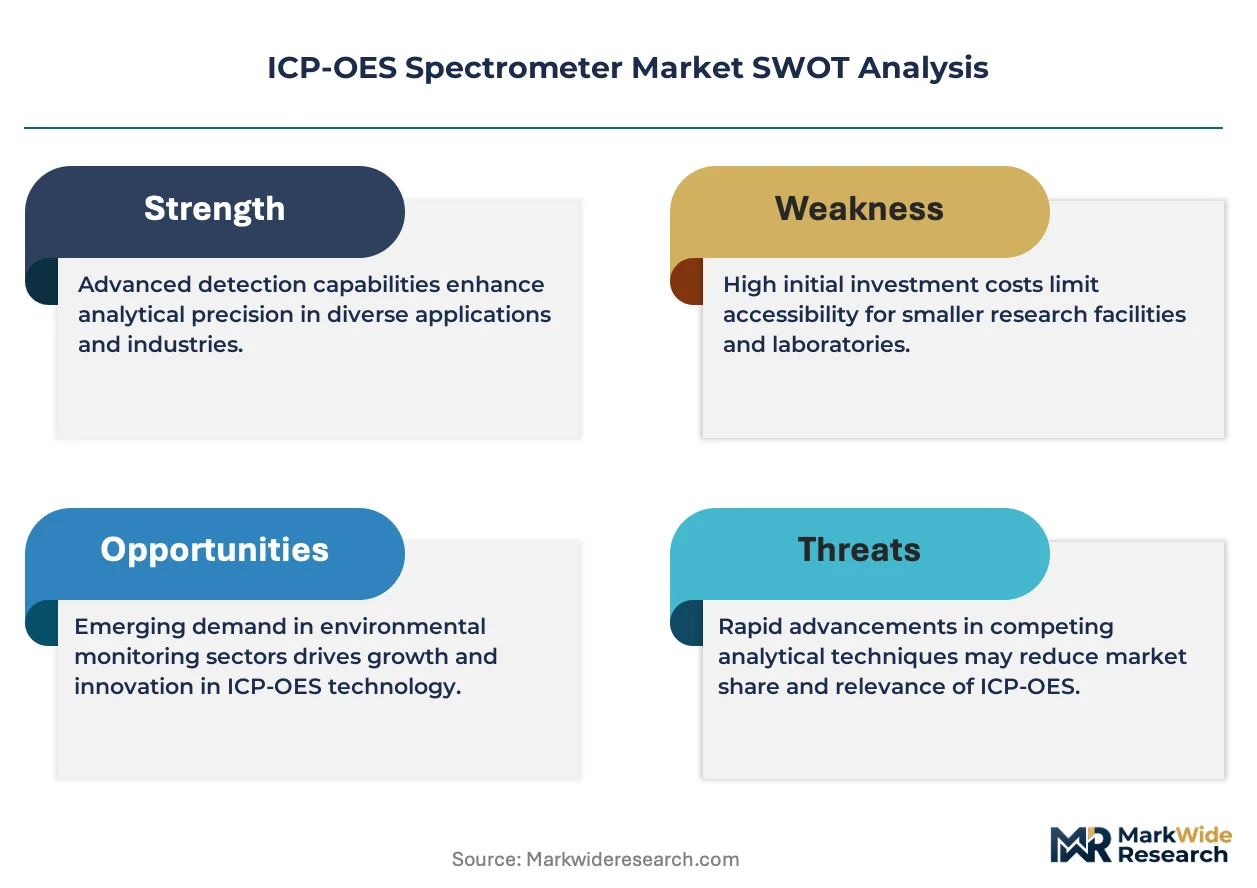
EPA Method 200.7 and ISO 11885 establish elemental analysis protocols that directly shape ICP-OES product specifications and validation requirements for water testing laboratories. EU REACH restrictions on hazardous substance thresholds compel manufacturers to deploy precise metal screening across supply chains, reinforcing instrument demand in European industrial labs. China's MEE enforces increasingly stringent wastewater discharge standards that provincial monitoring stations must meet through certified analytical methods. Stakeholders must monitor evolving PFAS and rare earth element regulations, as these emerging contaminant classes will reshape detection limit requirements and plasma source specifications across the next product replacement cycle.
Market Dynamics
Regulatory tightening on heavy metal discharge limits is forcing industrial laboratories to replace legacy atomic absorption systems with multi-element capable ICP-OES platforms, compressing replacement cycles and concentrating procurement among certified vendors.
Growth Catalysts
- EPA Method 200.7 compliance:Water testing laboratories in the United States must upgrade to ICP-OES systems to meet federally mandated trace metal detection protocols for drinking water certification.
- Semiconductor fabrication:High-purity chemical suppliers deploy dual-view ICP-OES configurations to monitor sub-ppb contamination in etching solutions and deposition precursors.
- China's MEE wastewater standards:Provincial environmental monitoring stations across Shandong, Jiangsu, and Guangdong provinces are procuring certified instruments to enforce stricter discharge permits.
Market Restraints
- Argon supply volatility:Plasma torch operation consumes 15-20 liters per hour of high-purity argon, exposing laboratories to price swings from industrial gas supply concentration.
- Technical skill barriers:ICP-OES operation requires trained spectroscopists capable of matrix interference correction and method development, constraining deployment in resource-limited facilities.
- ICP-MS substitution:Mass spectrometry platforms offer superior detection limits for ultra-trace applications, capturing budget allocations in pharmaceutical and clinical reference laboratories.
Strategic Opportunities
- Portable field deployment:Mining operations in remote locations are adopting battery-powered ICP-OES units for on-site ore grade verification without sample transport logistics.
- Rare earth element screening:Supply chain due diligence regulations in the European Union are creating demand for certified rare earth quantification in magnet and battery materials.
- AI-assisted spectral deconvolution:Machine learning algorithms are automating complex matrix interference correction, reducing analyst training requirements and expanding addressable user bases.
Industry Challenges
- ISO 17025 accreditation timelines:Testing laboratories face 12-18 month validation periods for new ICP-OES methods, delaying revenue generation from upgraded capabilities.
- Legacy LIMS integration:Older laboratory information management systems lack native ICP-OES data protocols, requiring costly middleware development for automated reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICP-OES Spectrometer Market |
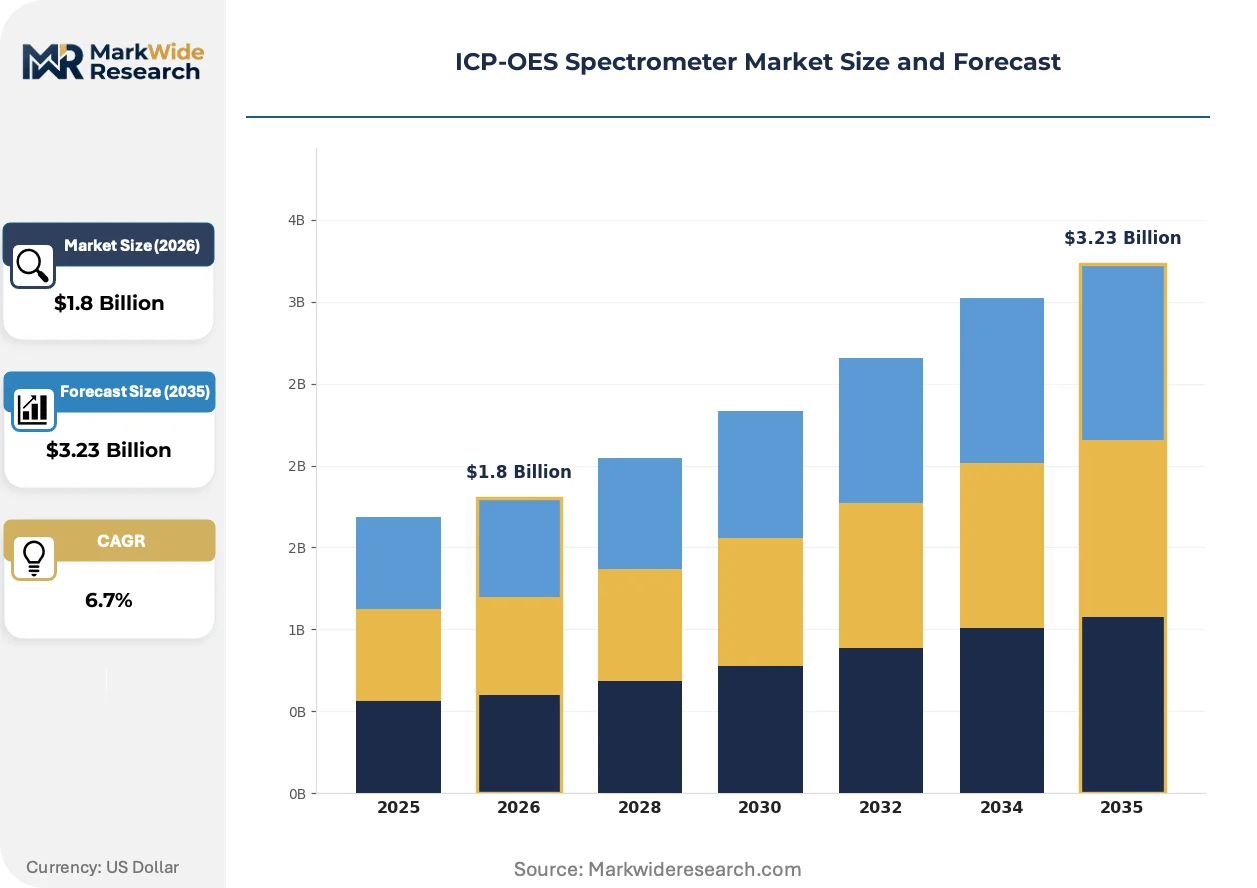
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop, Portable, Miniaturized, Desktop Technology: Inductively Coupled Plasma, Optical Emission Spectroscopy, Dual View, Axial View End User: Agricultural Labs, Environmental Testing, Mining, Manufacturing Application: Metal Analysis, Water Quality Testing, Material Characterization, Quality Control |
| Companies Covered | Agilent Technologies, Inc., SPECTRO Analytical Instruments GmbH, Thermo Fisher Scientific, Teledyne Leeman Labs, Analytik Jena AG, PerkinElmer Inc., HORIBA Ltd., GBC Scientific Equipment, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICP-OES Spectrometer Market Strategic Shifts
Spectroscopy vendors are embedding intelligence into hardware platforms while regulatory agencies expand elemental monitoring mandates into emerging contaminant classes. These forces are compressing product lifecycles and reshaping service revenue models.
Solid-state detector arrays are replacing photomultiplier tubes in mid-range ICP-OES systems, enabling simultaneous multi-wavelength acquisition without mechanical scanning. Environmental testing cooperatives in agricultural regions are adopting these configurations for rapid soil nutrient profiling. The technology is digitizing method development workflows and reducing per-sample analysis time from minutes to seconds.
EU REACH restrictions on hazardous substance thresholds are compelling electronics manufacturers to deploy precise metal screening across multi-tier supply chains. Industrial laboratories serving automotive and consumer electronics sectors must now certify compliance for cadmium, lead, and mercury at parts-per-million limits. This regulatory pressure is accelerating instrument procurement in German and French industrial testing hubs.
Service contract unbundling is emerging as laboratories seek flexibility in maintenance spend. Large environmental testing networks are negotiating à la carte calibration and repair agreements rather than comprehensive multi-year bundles. This behavioral shift is most pronounced in North American municipal water laboratories facing constrained operating budgets.
ICP-OES Spectrometer Market Segmentation
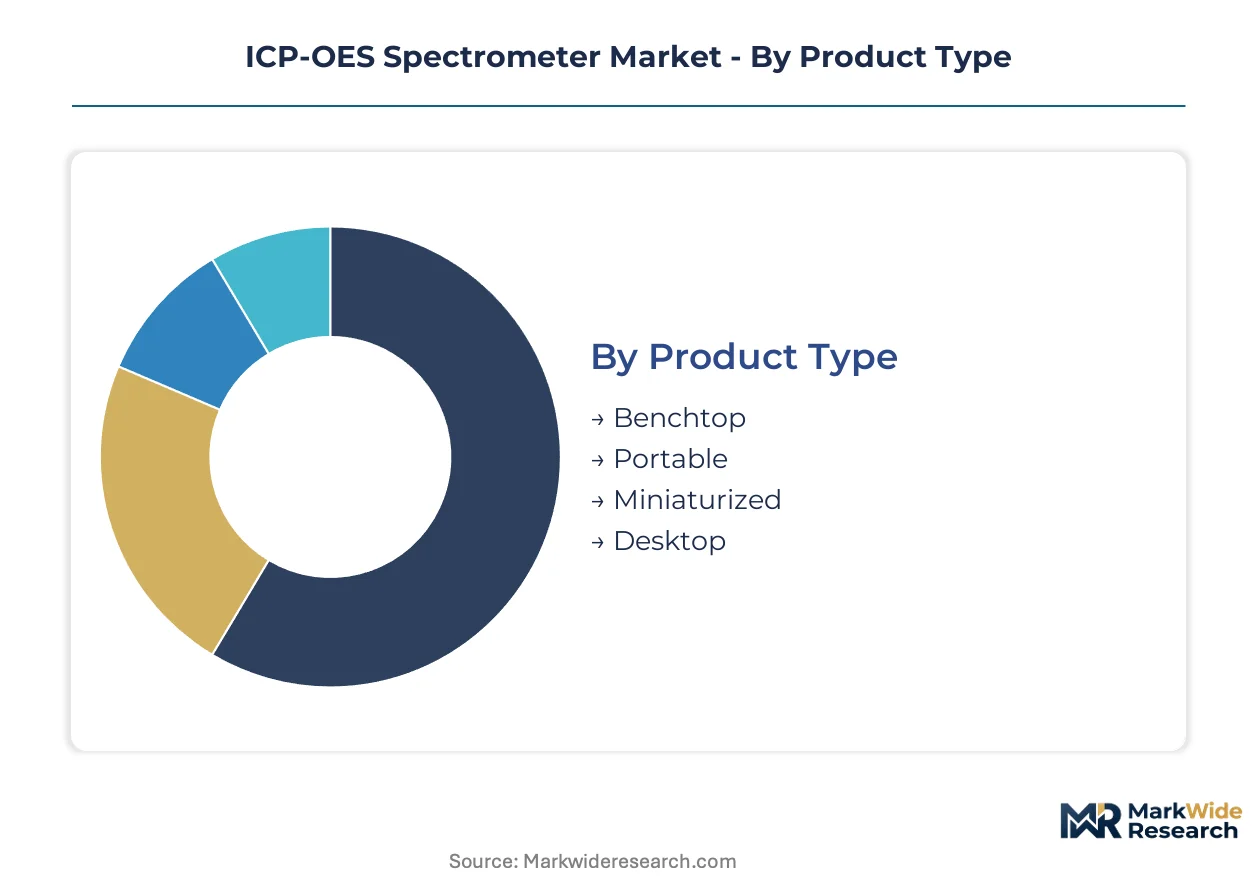
Segmentation in ICP-OES instrumentation reveals distinct service intensity profiles across product tiers. Benchtop systems generate recurring consumables revenue while portable units demand field calibration networks. Technology choices determine plasma source complexity and detector replacement cycles. End-user verticals impose divergent compliance documentation burdens. Application focus shapes method development depth and analyst training requirements.
Product Type:
After-sales-service intensity varies sharply across form factors, with plasma torch maintenance and detector calibration driving multi-year contract economics.
- Benchtop:Stationary laboratory systems integrate solid-state detector arrays and automated sample introduction. Demand concentrates in municipal water laboratories across the United States and Germany where EPA Method 200.7 and EU Drinking Water Directive compliance mandates routine heavy metal screening. These installations anchor vendor service revenue through argon supply contracts and quarterly maintenance protocols.
- Portable:Battery-powered field units weigh under 15 kilograms and operate without external gas cylinders. Mining operations in Western Australia and Chilean copper districts deploy these for on-site ore grade verification, eliminating sample transport logistics and laboratory turnaround delays. Ruggedized enclosures and shock-mounted optics withstand harsh extraction environments.
- Miniaturized:Compact footprints suit mobile environmental response teams and confined industrial spaces. Chinese provincial monitoring stations in Jiangsu deploy these for rapid wastewater screening.
- Desktop:Mid-range configurations balance throughput and capital expenditure for agricultural cooperatives. Brazilian soy export labs use these for soil nutrient profiling.
Benchtop systems hold the largest share; momentum sits with portable configurations gaining share fastest in remote resource extraction.
Technology:
Cost tier stratification separates research-grade dual-view platforms from routine axial-only systems, with detector technology driving price multiples.
- Dual View:Simultaneous axial and radial plasma observation extends dynamic range across eight orders of magnitude. Semiconductor chemical suppliers in South Korea and Taiwan deploy these for sub-ppb contamination monitoring in high-purity etching solutions. The configuration captures margin pools in electronics manufacturing where trace sodium and potassium detection determines wafer yield.
- Axial View:Single-axis observation optimizes sensitivity for alkali and alkaline earth metals at moderate cost. Environmental testing networks in France and Italy standardize on these for routine water quality compliance.
- Inductively Coupled Plasma:The core excitation source operates at 6,000+ Kelvin with argon consumption of 15-20 liters hourly. Gas supply contracts represent 30-40% of operating expenditure.
- Optical Emission Spectroscopy:Wavelength dispersive detection enables simultaneous multi-element quantification. Solid-state detector arrays are displacing photomultiplier tubes in mid-range systems.
Dual View commands premium pricing; Axial View delivers volume expansion in routine compliance laboratories.
End User:
Customer type determines procurement authority structure, with centralized mining conglomerates negotiating enterprise contracts versus fragmented agricultural labs purchasing through distributors.
- Environmental Testing:Commercial and government laboratories face ISO 17025 accreditation timelines of 12-18 months for new method validation. China's MEE provincial stations in Shandong and Guangdong are procuring certified instruments to enforce stricter wastewater discharge permits. Regulatory tightening compresses replacement cycles for legacy atomic absorption systems.
- Mining:Exploration divisions and assay laboratories require ruggedized configurations for geochemical surveys. Australian iron ore operations and South African platinum belt facilities prioritize uptime guarantees in service negotiations.
- Agricultural Labs:Soil testing cooperatives in the US Midwest and Ukrainian grain regions seek rapid nutrient profiling for fertilizer recommendation programs. Solid-state detector arrays enable simultaneous multi-wavelength acquisition.
- Manufacturing:Quality control departments in automotive and electronics supply chains deploy metal screening for EU REACH compliance on cadmium and lead thresholds.
Environmental Testing represents the largest installed base; Mining shows the steepest expansion trajectory as on-site assay adoption accelerates.
Application:
Application focus dictates method development depth, with metal analysis requiring extensive matrix interference libraries versus streamlined quality control protocols.
- Metal Analysis:Multi-element quantification at parts-per-billion sensitivity supports regulatory compliance and process control. Rare earth element screening for EU supply chain due diligence is emerging as a specialized sub-segment. Magnet and battery material certification demands precise lanthanide quantification.
- Water Quality Testing:Drinking water and wastewater monitoring drives the largest instrument procurement volumes. EPA Method 200.7 and ISO 11885 protocols directly shape product specifications.
- Material Characterization:High-purity chemicals and advanced alloys require contamination verification. Semiconductor precursor suppliers in Japan and Germany utilize dual-view configurations.
- Quality Control:Routine industrial testing emphasizes throughput and operator simplicity. Pharmaceutical excipient screening and food contact material certification dominate this segment.
Metal Analysis generates the highest service contract attachment rates; Water Quality Testing delivers the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port and Yangtze River Delta logistics corridor underwrite China's dominance in analytical instrumentation procurement, with bulk argon supply chains feeding provincial testing networks.
United States
EPA Method 200.7 compliance mandates drive municipal water laboratory upgrades across the Midwest and Southwest. The EPA enforces federally certified trace metal detection protocols for drinking water safety. Houston's petrochemical corridor and California's semiconductor fabrication clusters anchor industrial quality control demand for dual-view configurations.
Germany
Automotive supply chain metal screening and REACH compliance certification dominate procurement patterns in Baden-Württemberg. ECHA restrictions on hazardous substance thresholds compel electronics manufacturers to deploy precise cadmium and lead quantification. The Rhine-Ruhr industrial belt concentrates environmental testing laboratory capacity for EU-wide export certification.
China
Provincial environmental monitoring stations in Jiangsu and Guangdong provinces procure certified instruments under MEE wastewater discharge enforcement. Stricter effluent standards accelerate replacement of legacy atomic absorption systems. The Yangtze River Delta manufacturing corridor generates sustained demand for high-throughput quality control configurations.
Japan
Semiconductor precursor suppliers in Kyushu and Kansai regions deploy sub-ppb contamination monitoring for etching solution purity. METI industrial standards shape validation requirements for high-purity materials certification. Tokyo-Yokohama analytical service clusters support pharmaceutical and electronics manufacturing compliance documentation.
Australia
Western Australian iron ore operations and Queensland mining districts adopt portable field units for on-site ore grade verification. Remote extraction logistics eliminate laboratory transport delays for geochemical survey programs. Perth-based assay laboratories anchor service networks for Pilbara basin exploration divisions.
ICP-OES Spectrometer Market Competitive Environment
On the supply side, the industry is consolidating around multi-instrument platform vendors with established chromatography and mass spectrometry installed bases. Three archetypes dominate: integrated life science conglomerates leveraging cross-selling synergies, specialized spectroscopy houses with deep plasma source expertise, and regional equipment fabricators serving price-sensitive emerging markets. Competitive intensity centers on service contract bundling and consumables lock-in strategies rather than hardware differentiation alone.
Within the integrated platform tier, Thermo Fisher Scientific and Agilent Technologies occupy positions defined by chromatography-installed base leverage and pharmaceutical account penetration. PerkinElmer exemplifies the specialized analytical instrumentation archetype with focused agricultural and environmental testing configurations. SPECTRO Analytical Instruments GmbH and Analytik Jena AG represent European spectroscopy heritage with plasma source technical depth. Among Asia-Pacific-based manufacturers, Shimadzu Corporation and HORIBA Ltd. anchor regional supply chains with localized service infrastructure.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| SPECTRO Analytical Instruments GmbH |
| Thermo Fisher Scientific |
| Teledyne Leeman Labs |
| Analytik Jena AG |
| PerkinElmer Inc. |
| HORIBA Ltd. |
| GBC Scientific Equipment |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese argon production facilities compresses plasma torch operating costs while simultaneously eroding regional supplier margins, forcing instrumentation vendors to absorb gas supply volatility through bundled service contracts or pass-through pricing clauses to municipal laboratory buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates dual-view semiconductor-grade configurations from routine axial-view water testing systems and entry-level portable field units. Price differentiation rests on detector technology sophistication and ISO 17025 certification bundling rather than hardware alone. Pricing pressure stems from ICP-MS substitution in pharmaceutical reference laboratories capturing ultra-trace analysis budgets. Agricultural cooperatives exhibit highest price sensitivity due to capital constraints, while semiconductor chemical suppliers demonstrate lowest sensitivity given yield-critical contamination monitoring requirements.
Supply Chain Analysis
Export-control regimes restricting high-purity optical component flows from Germany and Japan constrain dual-view detector array availability for non-allied manufacturing destinations. Supply concentrates in United States, Germany, and China for complete system assembly, with Japan and South Korea anchoring solid-state detector fabrication. Raw material dependencies center on high-purity argon sourcing, fused silica optics, and radio-frequency generator components. Single-source vulnerability runs through argon liquefaction capacity concentrated near industrial gas production hubs. Distribution runs through direct vendor relationships with large environmental testing networks and specialized analytical instrumentation distributors serving fragmented agricultural laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as portable field deployment penetrates remote mining operations previously dependent on centralized assay laboratory logistics, with battery-powered unit adoption accelerating replacement of sample transport infrastructure.
For Market Incumbents: Insulate installed base positions through consumables lock-in strategies anchoring multi-year argon supply and detector calibration contracts. Prioritize backward integration into radio-frequency generator component production to mitigate semiconductor-grade electronics sourcing constraints. Defend against ICP-MS substitution threat by embedding AI-assisted spectral deconvolution into mid-range axial-view platforms, reducing analyst training barriers that constrain deployment in resource-limited facilities.
For New Entrants and Emerging Players: Brazilian agricultural testing cooperatives represent underpenetrated white-space opportunity given solid-state detector cost compression enabling simultaneous multi-wavelength acquisition at price points below established vendor configurations. Target miniaturized system deployment for Chinese provincial environmental monitoring stations facing MEE wastewater enforcement capacity expansion. Pursue service contract unbundling as go-to-market angle, negotiating à la carte calibration agreements with North American municipal water laboratories confronting constrained operating budgets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized spectroscopy houses with deep plasma source expertise and established agricultural testing cooperative relationships, generating sustained consumables and maintenance contract streams. Long-term viability favors vendors with demonstrated ISO 17025 method validation support capabilities and regional service infrastructure density. Acquisition target archetype: European spectroscopy heritage firms with technical depth in dual-view optical configurations. Signal to watch: EU rare earth element supply chain due diligence regulation enforcement accelerating certified quantification demand in magnet and battery material screening applications.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Spectral Deconvolution Development | Machine learning automation reduces analyst training requirements, expanding addressable user bases in resource-limited environmental testing facilities. |
| Portable Field Unit Battery Optimization | Extended off-grid operation enables Western Australian and Chilean mining operations to eliminate sample transport logistics entirely. |
| Rare Earth Element Method Certification | EU REACH supply chain due diligence mandates create specialized quantification service revenue streams in magnet material testing. |
| Argon Supply Contract Vertical Integration | Captive liquefaction capacity insulates municipal laboratory customers from industrial gas price volatility exposure. |
| Solid-State Detector Array Platform Migration | Photomultiplier tube displacement enables simultaneous multi-wavelength acquisition, compressing per-sample analysis time from minutes to seconds. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC instrument manufacturer filings, EPA method validation databases, and EU ECHA regulatory guidance documents. Primary interviews engaged product managers at spectroscopy vendors, laboratory directors at environmental testing networks, and procurement officers at semiconductor chemical suppliers. Secondary validation drew from customs trade data, ISO 17025 accreditation body records, and industrial gas supply chain disclosures. Bottom-up instrument shipment tracking triangulates against top-down laboratory capacity expansion estimates across municipal water and provincial environmental monitoring networks.
Forecast inputs encompass product type segmentation across benchtop, portable, miniaturized, and desktop configurations; technology tiering between dual-view and axial-view observation modes; end-user verticals spanning environmental testing, mining, agricultural laboratories, and manufacturing quality control; and application focus across metal analysis, water quality testing, material characterization, and routine quality control. CAGRs derive from replacement cycle compression analysis, regulatory mandate enforcement timelines, and emerging contaminant class detection requirement evolution. Industry-specific inputs include argon supply contract pricing trajectories and solid-state detector cost curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated life science conglomerates leveraging chromatography-installed base cross-selling would shift competitive dynamics and pricing structures. Material shifts in EPA or EU drinking water contaminant monitoring mandates, or breakthrough ICP-MS cost compression threatening mid-range ICP-OES positioning, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Digital Turbidity Meter Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Automatic Polarimeter Market