
 Laser Cleaning Market | 2026-2036
Laser Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cleaning Market Analysis
Buyer concentration across European automotive supply chains is recalibrating procurement standards for surface preparation equipment. Han's Laser leverages integrated fiber laser architectures to serve high-volume manufacturing contracts across Asia. Coherent sustains technology leadership through advanced beam delivery systems that target precision restoration applications. Trumpf anchors its competitive position with automated cleaning cells designed for heavy industrial deployment.
Laser cleaning employs high-intensity pulsed or continuous-wave beams to vaporize contaminants, oxides, and coatings without substrate abrasion, typically operating at wavelengths between 1064 nm and 10,600 nm with power outputs from 20 W to 1000 W. Fiber laser systems dominate the technology landscape due to superior beam quality and maintenance intervals, while CO2 laser platforms retain niche strength in organic residue removal for historical restoration. The application mix tilts toward industrial equipment maintenance where repeat cleaning cycles generate recurring revenue, though surface preparation for adhesive bonding represents the fastest-expanding use case as manufacturers abandon chemical etching. Automated installation configurations command premium positioning as labor costs and precision requirements escalate simultaneously.
OSHA exposure limits for airborne particulates and chemical solvents are compressing traditional abrasive and wet cleaning methods across United States manufacturing facilities. The EU F-Gas Regulation and REACH chemical restrictions are accelerating substitution toward laser-based dry processes in European metal fabrication. Stakeholders must monitor evolving ISO cleanliness standards for bonded joints and assess how emerging pulsed laser safety classifications reshape operator certification requirements and equipment design protocols.
Market Dynamics
REACH restrictions on chemical solvents across Europe are redirecting capital toward dry surface treatment methods, compressing the timeline for laser cleaning adoption in precision manufacturing clusters.
Growth Catalysts
- REACH chemical restrictions:European manufacturers face mandatory phase-out of chlorinated solvents in metal finishing, accelerating substitution toward laser-based dry processes for component cleaning.
- Fiber laser architectures:Superior beam quality and extended maintenance intervals reduce total cost of ownership, pulling high-volume automotive suppliers away from CO2 platforms.
- Aerospace maintenance divisions:Turbine blade refurbishment programs across Germany and France are expanding laser cleaning adoption to meet airworthiness directives without substrate damage.
Market Restraints
- Capital intensity:Automated cleaning cells require substantial upfront investment in beam delivery systems and robotic integration, limiting adoption among mid-tier fabricators.
- Technical wavelength limitations:1064 nm fiber systems struggle with certain organic residues, forcing dual-platform investments or process compromises in heritage restoration applications.
- Supply concentration in fiber laser sources:Dependence on specialized resonator manufacturers creates vulnerability to input bottlenecks and extended lead times.
Strategic Opportunities
- Surface preparation for adhesive bonding:Automotive lightweighting programs are abandoning chemical etching for laser texturing, opening recurring revenue streams in bonded joint certification.
- EU F-Gas Regulation:Accelerated refrigerant phase-down is pressuring metal fabricators to eliminate solvent-based cleaning, creating regulatory tailwind for dry alternatives.
- Historical restoration niche:CO2 laser platforms retain unmatched capability for delicate organic residue removal, positioning specialized service providers for heritage conservation contracts.
Industry Challenges
- ISO cleanliness certification timelines:Bonded joint standards for automotive and aerospace applications require extensive validation cycles, delaying equipment deployment and revenue recognition.
- Laser safety operator classification:Emerging pulsed laser categories demand recertification of existing workforce, compressing available talent pools and extending training overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cleaning Market |
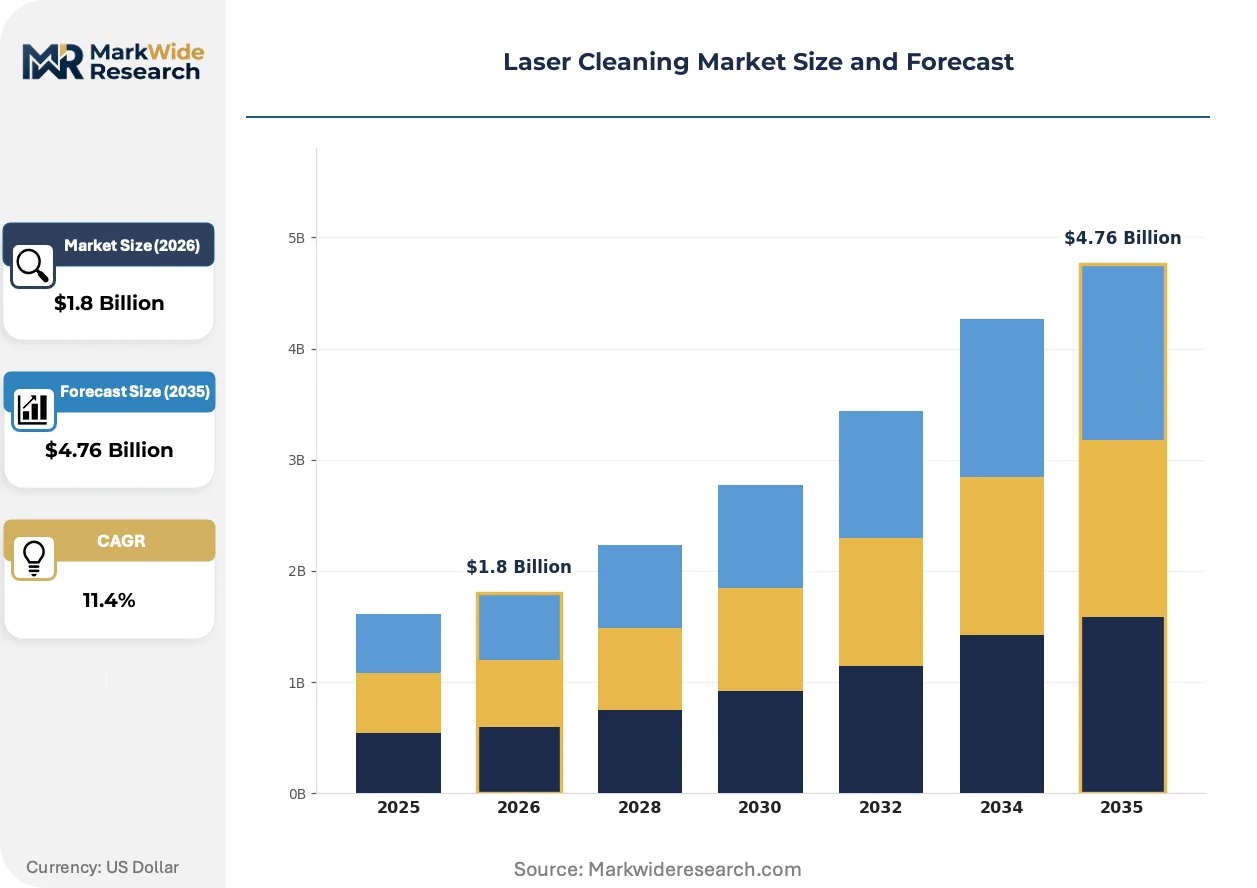
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Laser, CO2 Laser, Nd:YAG Laser, Solid State Laser Application: Industrial Equipment, Historical Restoration, Surface Preparation, Chemical Removal End User: Manufacturing, Aerospace, Automotive, Marine Installation: Portable Systems, Stationary Systems, Automated Systems, Mobile Units |
| Companies Covered | Han's Laser, Coherent, CleanLASER, NKT Photonics, GW Laser, IPG Photonics, Laserax, YiHai Laser, Trumpf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cleaning Market Emerging Trajectories
Beam delivery architectures and regulatory chemistry mandates are converging to reshape competitive positioning across surface treatment equipment. Equipment manufacturers must navigate simultaneous pressure for precision, automation, and compliance.
Ultrafast pulsed laser systems are absorbing market share in precision restoration applications where thermal damage thresholds are critical. Heritage conservation laboratories and aerospace MRO facilities are adopting these platforms to remove oxides and coatings without substrate alteration. The technology is absorbing capital that previously flowed to micro-abrasive methods, compressing the addressable market for competing dry processes.
EU F-Gas Regulation phase-down schedules are forcing metal fabricators to eliminate solvent-based vapor degreasing by mandated deadlines. The restriction removes a legacy cleaning pathway for bonded joint preparation, redirecting process engineering resources toward laser texturing validation. German automotive suppliers and French aerospace subcontractors face the most compressed transition timelines.
Buyer consolidation across European automotive supply chains is concentrating procurement authority at tier-one integrators. These consolidated purchasing functions are unbundling after-sales service contracts from initial equipment sales, pressuring OEM margins and favoring vendors with dedicated regional service infrastructure. Stuttgart and Munich industrial clusters exhibit the most pronounced procurement centralization.
Laser Cleaning Market Segmentation
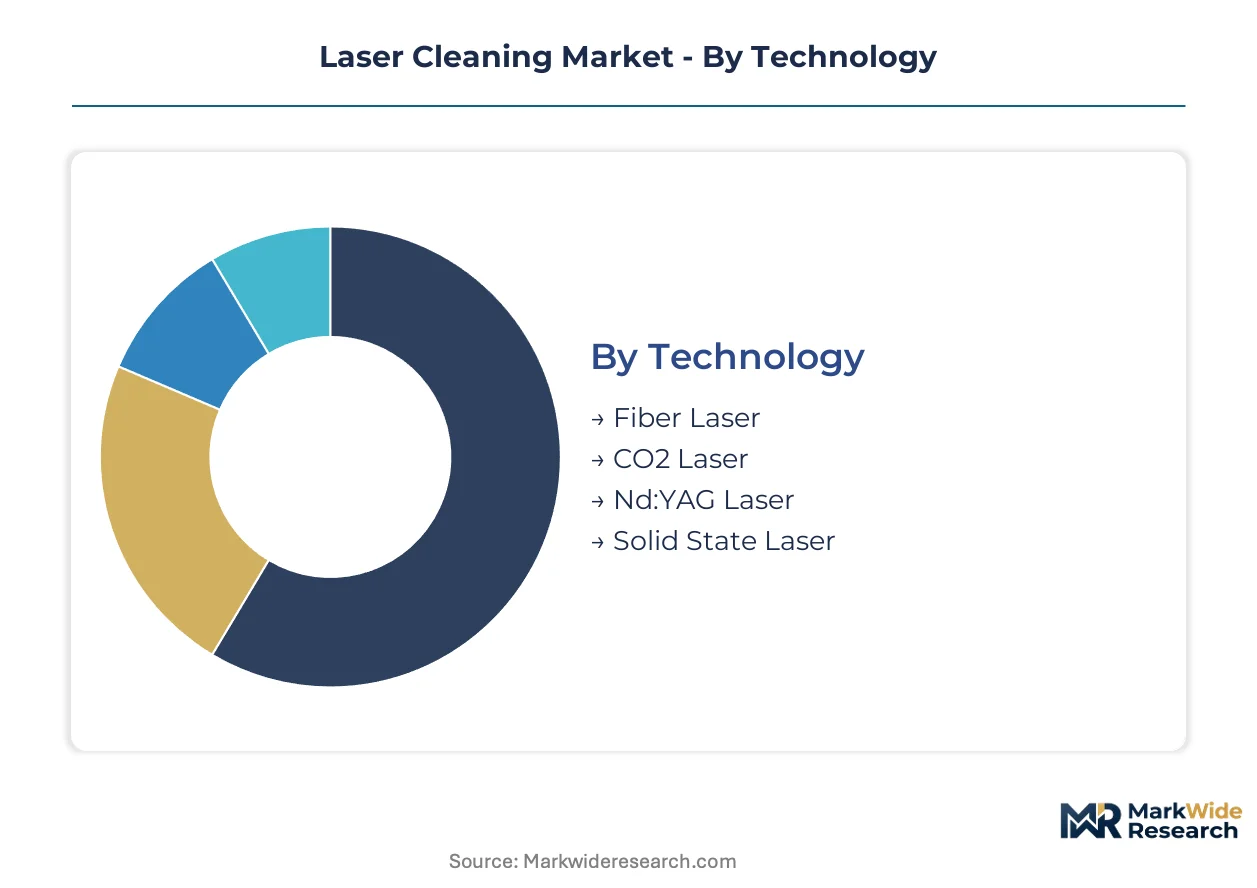
Laser cleaning equipment segments diverge sharply between precision-demanding aerospace contracts and high-throughput automotive lines. Procurement patterns across these segments reveal distinct technology preferences and service intensity requirements.
Technology:
Customization intensity ranges from fully configurable beam parameters in solid-state architectures to standardized fiber laser platforms optimized for factory-floor repeatability.
- Fiber Laser:These systems leverage ytterbium-doped fiber resonators operating at 1064 nm with superior beam quality (M² < 1.3) and maintenance intervals exceeding 50,000 hours. Demand concentrates in German automotive supply chains around Stuttgart, where REACH-mandated solvent elimination is compressing adoption timelines for bonded joint preparation.
- CO2 Laser:Gas-discharge platforms at 10,600 nm wavelength deliver unmatched absorption on organic substrates with thermal damage thresholds below 50°C surface temperature rise. French heritage conservation laboratories and Italian marble restoration workshops anchor demand as EU F-Gas Regulation forces solvent-based alternatives into phase-out.
- Nd:YAG Laser:Flashlamp-pumped or diode-pumped solid-state architectures at 1064 nm and 532 nm serve specialized aerospace MRO applications requiring portable deployment.
- Solid State Laser:Ultrafast picosecond and femtosecond platforms enable cold ablation with minimal heat-affected zones for precision electronics and medical device cleaning.
Leading the category by volume: Fiber Laser. Growing fastest: Solid State Laser.
Application:
Application segments track directly to end-use margin structures, from recurring maintenance contracts in industrial equipment to project-based revenue in heritage restoration.
- Industrial Equipment:Turbine blade refurbishment, mold cleaning, and production line maintenance generate recurring revenue streams with 3-5 year replacement cycles. Aerospace MRO divisions in France and Germany are expanding adoption to meet airworthiness directives without substrate damage.
- Surface Preparation:Laser texturing for adhesive bonding represents the steepest expansion trajectory as automotive lightweighting programs abandon chemical etching. German tier-one suppliers around Munich are validating ISO cleanliness standards for bonded joints in aluminum-intensive vehicle architectures.
- Historical Restoration:Delicate stone, wood, and pigment cleaning commands premium pricing with project-based procurement through conservation laboratories and museum technical services.
- Chemical Removal:Paint stripping and coating removal for marine vessels and infrastructure maintenance serves mid-tier fabricators with cost-sensitive procurement.
Highest margin concentration: Historical Restoration. Steepest volume climb: Surface Preparation.
End User:
End-user segments reflect divergent certification burdens, from aerospace airworthiness documentation to automotive PPAP validation requirements.
- Aerospace:OEM-approved cleaning processes for turbine blades, landing gear, and structural components demand extensive qualification cycles with FAA and EASA documentation. German and French MRO facilities are consolidating procurement authority at divisional level.
- Automotive:Tier-one integrators in Stuttgart and Munich industrial clusters are unbundling after-sales service contracts from initial equipment sales, pressuring OEM margins.
- Manufacturing:General metal fabrication and electronics production lines favor standardized platforms with minimal operator training overhead.
- Marine:Shipyard and offshore platform maintenance applications prioritize portable systems for field deployment with salt-corrosion resistance specifications.
Most stringent certification requirements: Aerospace. Fastest procurement cycle compression: Automotive.
Installation:
Installation configurations segment by labor substitution intensity, from fully manual portable units to lights-out automated cells with robotic beam delivery.
- Automated Systems:Robotic integration with 6-axis beam delivery and real-time surface monitoring commands 40-60% price premiums over manual alternatives. German automotive suppliers are mandating automated configurations for bonded joint preparation to eliminate operator-induced variability.
- Portable Systems:Handheld or cart-mounted units below 50 kg enable field deployment for infrastructure and marine applications with battery or generator power options.
- Stationary Systems:Fixed-position workstations serve high-volume production lines with conveyor integration and centralized fume extraction.
- Mobile Units:Containerized or vehicle-mounted configurations deliver on-site cleaning services for construction equipment and emergency restoration.
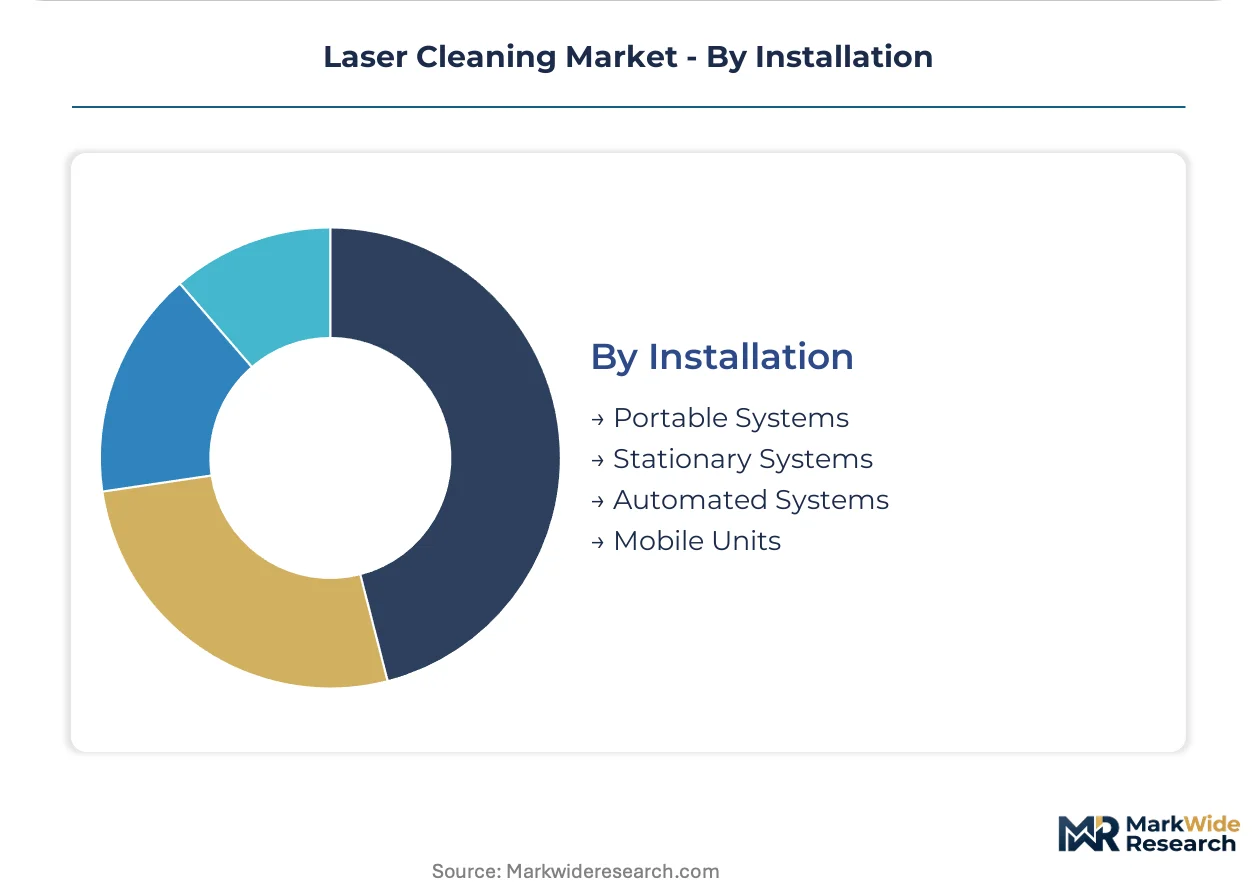
Fastest share gain: Automated Systems. Highest unit volume: Portable Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority for laser cleaning equipment concentrates in Germany's automotive belt and France's aerospace maintenance corridors, with regulatory chemistry mandates compressing adoption timelines across both markets. REACH restrictions and EU F-Gas Regulation phase-downs are redirecting capital toward dry surface treatment methods in precision manufacturing clusters. Industrial buyers in Stuttgart, Munich, and Toulouse are consolidating vendor relationships around automated cleaning configurations.
Germany
Tier-one automotive suppliers around Stuttgart and Munich are validating ISO cleanliness standards for bonded joint preparation in aluminum-intensive vehicle architectures. ECHA's REACH enforcement on chlorinated solvents eliminates legacy chemical etching pathways by mandated deadlines. The Baden-Württemberg industrial corridor exhibits the most pronounced procurement centralization, with consolidated purchasing functions unbundling after-sales service contracts from initial equipment sales.
France
Aerospace MRO divisions in Toulouse and Paris are expanding laser cleaning adoption for turbine blade refurbishment to meet EASA airworthiness directives without substrate damage. The EU F-Gas Regulation accelerates refrigerant phase-down pressures on metal fabricators, eliminating solvent-based vapor degreasing alternatives. Heritage conservation laboratories in Paris anchor demand for CO2 laser platforms with unmatched capability for delicate organic residue removal on stone and pigment surfaces.
United States
OSHA exposure limits for airborne particulates and chemical solvents are compressing traditional abrasive and wet cleaning methods across manufacturing facilities in Michigan, Ohio, and the industrial Midwest. FAA documentation requirements for OEM-approved cleaning processes drive qualification cycles among aerospace subcontractors in the Southeast and Pacific Northwest. Automotive lightweighting programs in the Detroit metro area are abandoning chemical etching for laser texturing in bonded joint certification.
China
Domestic fiber laser source manufacturers are capturing share in high-volume automotive supply chains across the Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT industrial upgrading guidelines prioritize automated surface treatment equipment in smart factory deployments. Shenzhen and Shanghai industrial clusters are integrating laser cleaning cells into production lines for electronics and battery component preparation.
Italy
Marble restoration workshops in Carrara and Florence retain demand for CO2 laser platforms with thermal damage thresholds below 50°C surface temperature rise for heritage conservation contracts. Metal fabrication SMEs in Lombardy and Emilia-Romagna face compressed transition timelines under EU F-Gas Regulation solvent elimination mandates. The Veneto industrial district exhibits emerging adoption for mold cleaning applications in specialty manufacturing.
Laser Cleaning Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision restoration and ultrafast pulsed architectures. The vendor base distributes across three maturity tiers: integrated fiber laser architects with captive resonator supply, specialized beam delivery system designers, and automated cell integrators with robotic partnership networks. Competitive moves concentrate on strategic partnerships for regional service infrastructure and portfolio diversification into adjacent surface treatment modalities.
Within the integrated platform tier, Han's Laser and Trumpf exemplify divergent geographic anchoring strategies. Zhengzhou YiHai Laser Co., Ltd. occupies a position among Chinese fabricators targeting cost-sensitive procurement in high-volume manufacturing segments. CleanLASER GmbH represents the specialized European archetype with heritage conservation and precision restoration positioning. Coherent sits within the beam delivery technology tier with advanced optical system architectures.
| Leading Market Players |
|---|
| Han's Laser |
| Coherent |
| CleanLASER |
| NKT Photonics |
| GW Laser |
| IPG Photonics |
| Laserax |
| YiHai Laser |
| Trumpf |
| Others |
Supply Flow & Price Mechanics
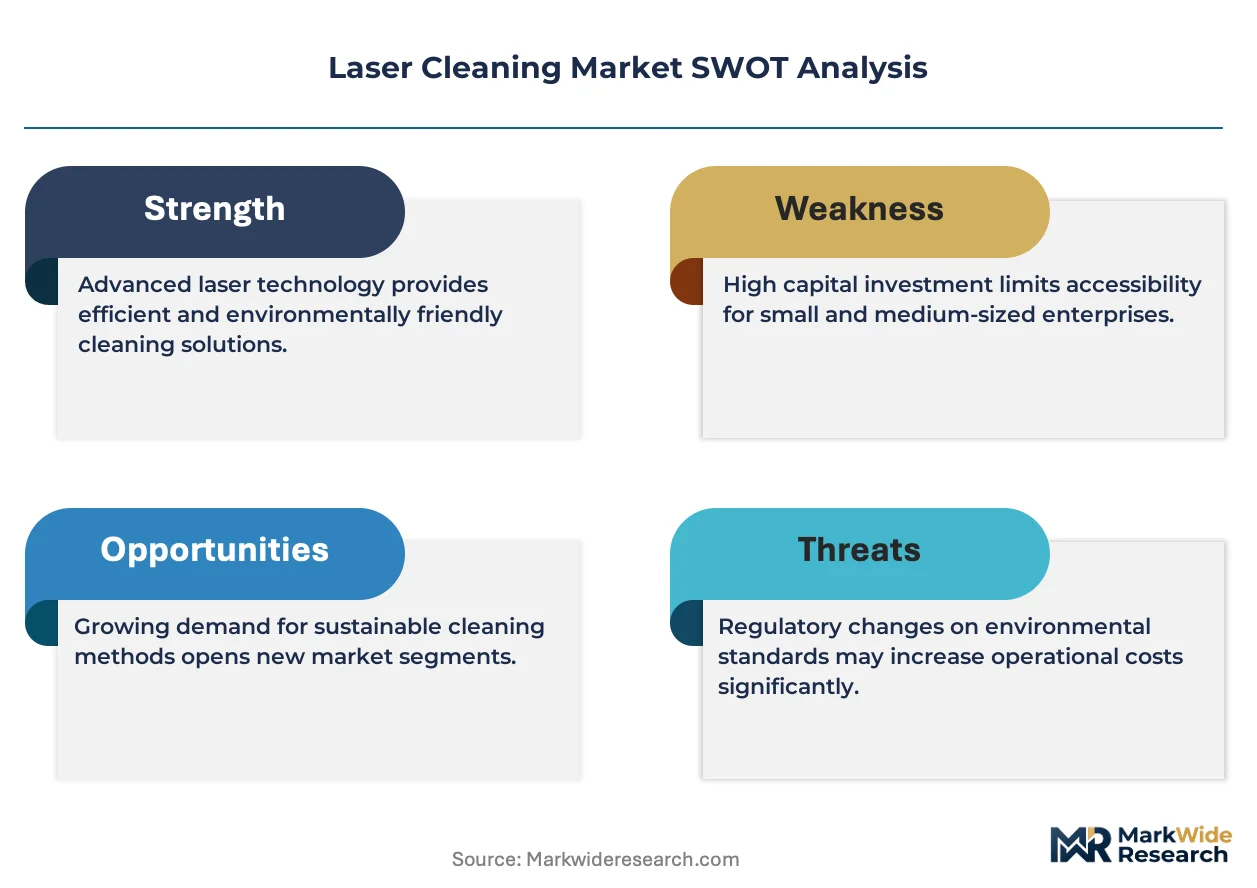
Private-equity-rolled-up fiber laser specialists anchor supply discipline through captive resonator manufacturing, compressing margin pressure on independent system integrators while sustaining premium positioning for automated cleaning cells in German automotive procurement.
Pricing Analysis
Volume-scale fiber laser platforms compete on total cost of ownership against margin-rich ultrafast solid-state systems serving aerospace MRO and heritage restoration. Three-tier pricing structure across premium automated cells, standard stationary workstations, and economy portable units tracks certification grade and after-sales bundling intensity. Cost compression in mid-tier configurations is intensifying because tier-one automotive suppliers unbundle service contracts from equipment sales. Price sensitivity concentrates among Lombardy metal fabrication SMEs facing EU F-Gas transition mandates, while French aerospace MRO divisions exhibit lowest sensitivity due to airworthiness documentation requirements.
Supply Chain Analysis
Single-source vulnerability sits with ytterbium-doped fiber resonator manufacturing concentrated in China, Germany, and the United States. Beam delivery optics and robotic integration modules draw from Japanese precision motion control suppliers and German automation engineering clusters. Supply chain risk centers on extended lead times for specialized resonator components under export control classifications. Distribution runs through direct OEM sales forces for automated systems and regional distributor networks for portable configurations serving marine and infrastructure maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber laser source capacity constraints prop pricing power for integrated platform manufacturers, compressing adoption timelines for mid-tier fabricators dependent on external resonator supply.
For Market Incumbents: Extend captive resonator production into automated cleaning cell architectures serving Stuttgart and Munich automotive clusters. Deepen backward integration over beam delivery optics to offset margin pressure from unbundled service contracts. Fortify regional service infrastructure against emerging Chinese platform competitors targeting cost-sensitive procurement. For New Entrants and Emerging Players: Ultrafast pulsed laser architectures offer technology-first wedge into precision electronics cleaning and medical device surface preparation where thermal damage thresholds command premium positioning. White-space concentrates in Italian marble restoration workshops and French heritage conservation laboratories requiring CO2 platforms with sub-50°C thermal specifications. Go-to-market through specialized conservation equipment distributors bypasses entrenched industrial OEM channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated cell integrators with robotic partnership networks in German industrial corridors. Long-term viability hinges on software-defined surface monitoring capabilities and recurring service revenue attachment. Watch EASA airworthiness directive expansion timelines as inflection indicator for aerospace MRO capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Manufacturing | Captive ytterbium-doped fiber supply secures margin control against IPG Photonics and NKT Photonics pricing power. |
| Regional Service Infrastructure Expansion | Dedicated technical centers in Stuttgart and Toulouse defend against Han's Laser and YiHai Laser cost aggression. |
| Ultrafast Pulsed Platform Development | Picosecond architectures penetrate aerospace MRO and heritage restoration where cold ablation commands 40-60% price premiums. |
| Automated Bonded Joint Certification Systems | Robotic beam delivery with real-time ISO cleanliness validation captures automotive lightweighting program procurement. |
| Heritage Conservation Equipment Specialization | CO2 platforms with organic residue specificity anchor project-based revenue in EU F-Gas-driven solvent substitution. |
Methodological Framework
Multi-period observation of fiber laser source lead times, REACH enforcement timelines, and aerospace MRO capital expenditure patterns anchored the trend analysis, supplemented by interviews with maintenance directors at German automotive tier-one suppliers, plant engineers in French aerospace subcontractor facilities, aftermarket service heads at laser system OEMs, and procurement leads in Italian metal fabrication SMEs. Secondary validation drew from ECHA regulatory filings, EU F-Gas Regulation implementation schedules, SEC 10-K disclosures from listed laser equipment manufacturers, and customs trade data for fiber laser component imports. Bottom-up equipment shipment tallies and top-down industrial capital expenditure estimates were triangulated to cross-validate market sizing.
Segment-weighting across technology type, application, end-user industry, and installation configuration structured the analytical framework across the projection horizon. CAGRs were derived from regression analysis against industrial production indices, regulatory phase-out schedules, and substitution elasticity estimates for solvent-based cleaning methods. Forecast inputs incorporated EASA airworthiness directive expansion assumptions and automotive bonded joint certification timeline validation cycles specific to aluminum-intensive vehicle architectures.
Several conditions sit outside the modeled scope, including unilateral trade policy shifts affecting fiber laser component tariffs, breakthrough advances in competing dry cleaning technologies, and accelerated REACH chemical restrictions beyond currently published phase-out schedules. Deviation in EASA or FAA regulatory expansion timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
Femtosecond Fiber Lasers Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
Cartridge Heaters Market