
 Europe Tempered Glass Cutting Machine Market | 2026-2036
Europe Tempered Glass Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tempered Glass Cutting Machine Market Insights
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across Europe's tempered glass machinery base. LISEC Group leverages its Austria-centered service network to capture recurring revenue from installed CNC cutting lines. Bottero S.p.A. anchors its position through deep specialization in diamond wheel refurbishment and consumables logistics. Glaston Corporation extends its Finnish engineering heritage into predictive maintenance contracts for architectural glass processors.
A tempered glass cutting machine severs thermally strengthened glass panels—typically 4–19 mm thick—using diamond scoring, thermal shock, or abrasive water jet methods without compromising internal stress equilibrium. The equipment serves primarily architectural fabricators and automotive suppliers requiring dimensional precision within ±0.5 mm for safety-rated installations. Automated cutting machines dominate volume shipments across Europe, while laser cutting systems represent the fastest-expanding technology segment as photovoltaic glass specifications tighten. Water jet cutting technology sustains premium positioning for thick-glass architectural applications where edge quality determines lamination bond strength.
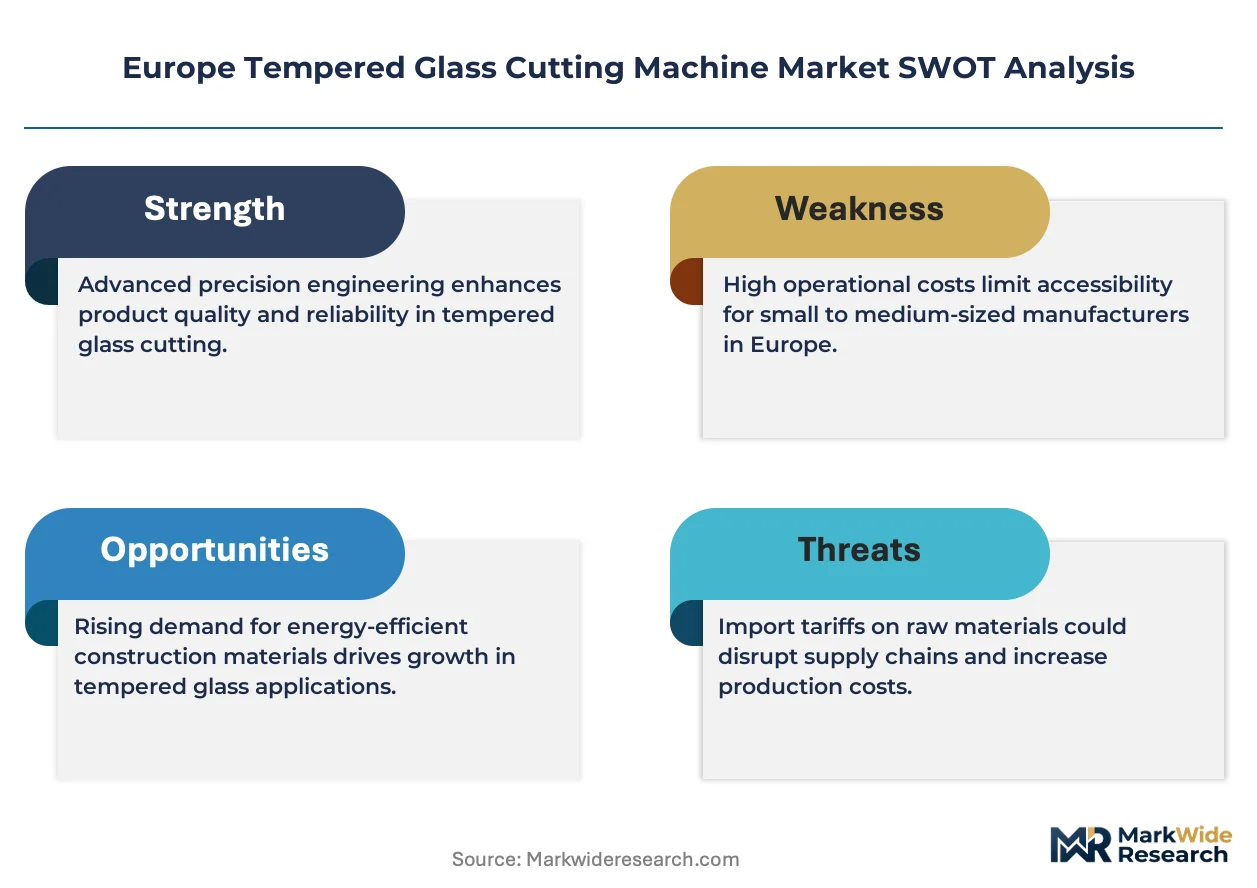
CE marking under the EU Machinery Directive governs operational safety and electromagnetic compatibility for all tempered glass cutting equipment placed on the European market. REACH compliance constrains coolant chemistry and abrasive material composition, particularly affecting diamond slurry formulations used in Bottero and Bavelloni systems. Germany's KBA and France's ANSM do not regulate this equipment directly, but national workplace safety inspectorates enforce OSHA-equivalent noise and silica exposure limits that shape machine enclosure design. Stakeholders must monitor whether the EU AI Act's risk classification framework will capture autonomous defect-detection modules now migrating into next-generation CNC controllers.
Market Dynamics
Automation investments by architectural glass fabricators across Germany, France, and Italy are compressing replacement cycles for legacy mechanical cutting systems. The EU Green Deal's building renovation mandates are forcing precision upgrades that favor CNC-controlled equipment over manual scoring operations.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory energy-efficiency retrofits across member states are accelerating demand for high-performance glazing. Fabricators require precision cutting equipment to meet thermal performance specifications.
- Photovoltaic glass fabrication expansion:Solar module manufacturers in Germany and the Netherlands are commissioning specialized cutting lines for thin-film and bifacial panel substrates.
- Rhine corridor glass processing clusters:Concentrated demand from fabricators along the Mainz-to-Cologne industrial corridor creates localized economies of scale for equipment suppliers.
Market Restraints
- Industrial electricity price volatility:German and Italian fabricators face input cost uncertainty that delays capital expenditure approvals for automated cutting lines.
- Diamond wheel supply concentration:Synthetic diamond abrasive production concentrates in Asian manufacturing centers, exposing European OEMs to logistics disruptions and currency fluctuation.
- REACH chemical compliance:Coolant formulation restrictions constrain diamond slurry chemistry options, limiting process optimization for thick-glass applications.
Strategic Opportunities
- Eastern European fabrication greenfield sites:Poland and Czech Republic glass processors are expanding capacity without legacy equipment burdens, favoring fully automated cutting configurations.
- EU AI Act risk classification framework:Autonomous defect-detection modules in next-generation CNC controllers may qualify as high-risk AI systems, creating first-mover advantage for compliant suppliers.
- Predictive maintenance service contracts:Finnish and Austrian engineering heritage positions regional vendors to monetize installed-base data analytics rather than pure equipment sales.
Industry Challenges
- CNC programming specialist scarcity:Glass fabricators struggle to recruit operators capable of optimizing cutting paths for complex architectural geometries.
- CE marking timeline compression:Machinery Directive conformity assessment delays for novel laser cutting configurations extend time-to-revenue for equipment introductions.
- Legacy mechanical system integration:Hybrid workflows combining automated scoring with existing tempering furnaces create workflow friction and quality variance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tempered Glass Cutting Machine Market |
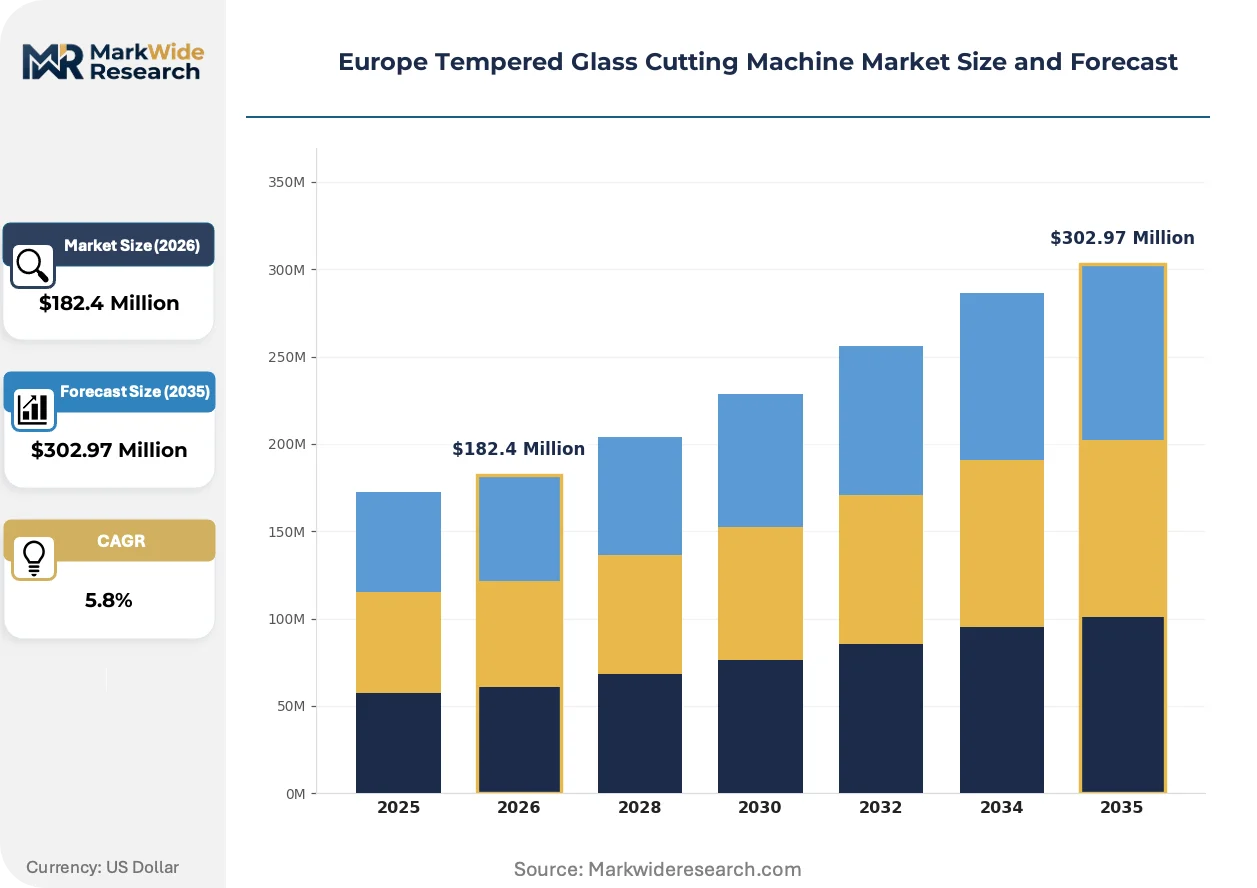
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $302.97 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cutting Machines, Automated Cutting Machines, CNC Cutting Machines, Laser Cutting Machines End User: Construction, Automotive, Electronics, Furniture Technology: Water Jet Cutting, Diamond Cutting, Hot Cutting, Cold Cutting Application: Architectural Glass, Shower Doors, Windows, Display Cases |
| Companies Covered | LISEC Group, Bottero S.p.A., Glaston Corporation, Adelio Lattuada S.r.l., Intermac Glass Division, Bystronic Glass GmbH, CMS Glass Machinery, Bavelloni SpA, HEGLA GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tempered Glass Cutting Machine Market Trends and Innovations
Digital twin technology is virtualizing machine commissioning and operator training workflows across European glass fabrication facilities. Three convergent developments are reconfiguring competitive positioning in precision cutting equipment.
Laser cutting systems for photovoltaic glass applications are virtualizing traditional mechanical scoring workflows. Solar module manufacturers in the Netherlands and Germany are adopting fiber-laser configurations for thin-film panel substrates at accelerating pace. This technology is virtualizing the boundary between cutting and edge-sealing operations, compressing total process steps.
REACH enforcement by ECHA is tightening constraints on diamond slurry coolant chemistry used in Bottero and Bavelloni cutting systems. Industrial consequence includes accelerated R&D investment in water-based and synthetic alternatives by Italian equipment specialists. German fabricators operating under stricter workplace safety inspectorate oversight are most affected, responding with enclosed cutting environments and automated coolant recovery.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles across the European vendor base. Architectural glass processors in France and Italy now separately procure diamond wheel refurbishment, consumables logistics, and predictive analytics. This pattern is most visible among mid-cap fabricators seeking to optimize total cost of ownership rather than upfront capital expenditure.
Europe Tempered Glass Cutting Machine Market Segmentation
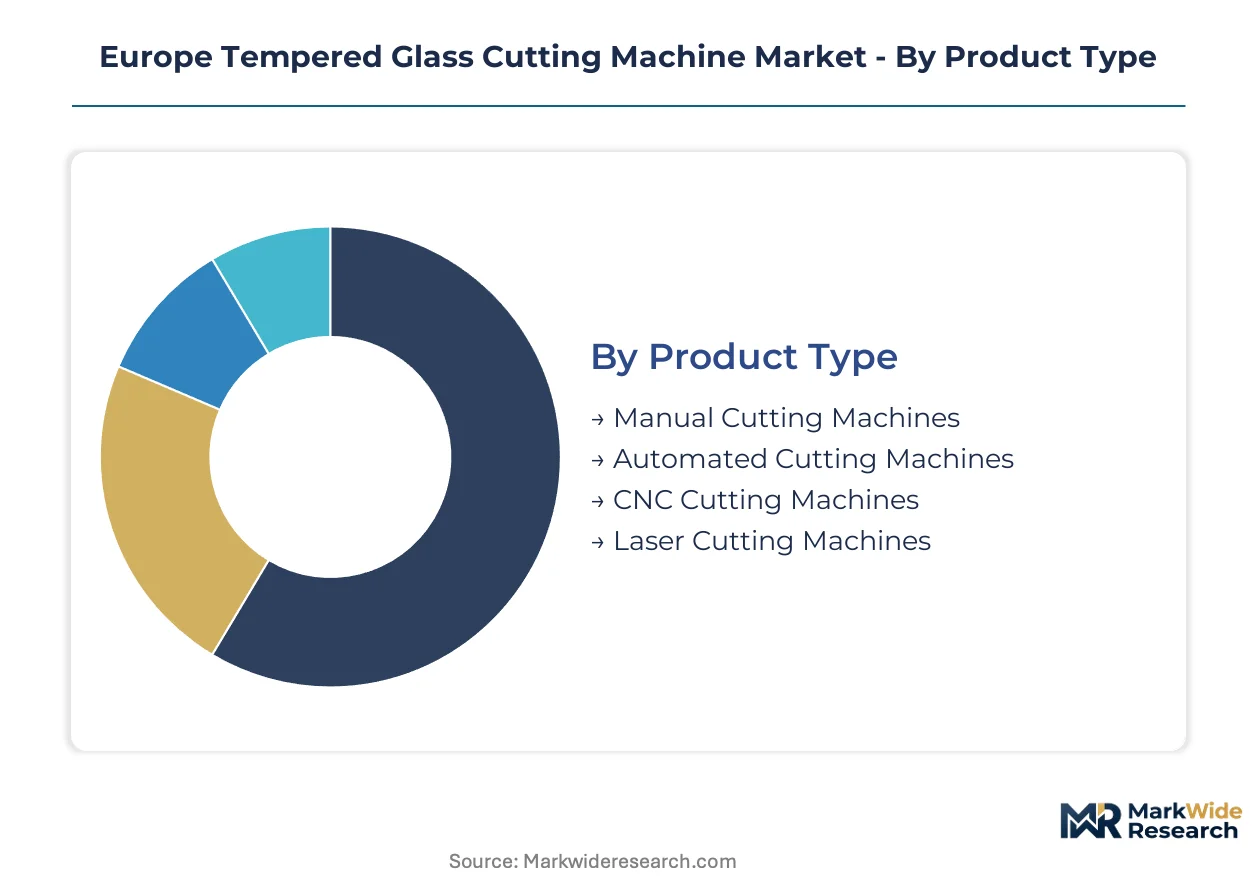
Segmentation reveals how after-sales service intensity varies dramatically across equipment tiers in Europe's tempered glass machinery base. CNC and laser configurations demand specialized maintenance contracts that reconfigure vendor margin pools away from pure hardware sales.
Product Type:
After-sales service intensity peaks with automated precision equipment where predictive maintenance contracts and consumables logistics generate recurring revenue streams exceeding original equipment margins.
- Manual Cutting Machines:Basic scoring tools for small-batch architectural fabricators with minimal automation. Demand concentrates in Eastern European greenfield sites where Polish and Czech processors prioritize capital efficiency over throughput.
- Automated Cutting Machines:Servo-driven scoring systems with programmable stop positions. Rhine corridor fabricators in Germany deploy these for medium-volume thermal glazing production under EU Green Deal renovation mandates.
- CNC Cutting Machines:Computer-numerical-control platforms with multi-axis positioning and automated loading. Italian glass processors along the Veneto-Friuli industrial cluster favor these for complex geometric patterns in high-performance facades.
- Laser Cutting Machines:Fiber-laser configurations severing thin-film photovoltaic substrates without mechanical contact. Netherlands and German solar module manufacturers commission these for bifacial panel fabrication where edge quality determines electrical isolation.
By volume, automated cutting machines lead. By growth pace, laser cutting machines are expanding most quickly.
End User:
Cost tier segmentation separates premium precision requirements from standard architectural applications where tolerance relaxation permits simpler equipment configurations.
- Construction:Architectural fabricators serving EU Green Deal building retrofits require ±0.5 mm dimensional precision for thermal performance glazing. German processors along the Mainz-to-Cologne corridor anchor demand concentration.
- Automotive:Safety-rated tempered glass for windshields and side windows demands automated inspection integration. French automotive suppliers near the Franco-German border prioritize CNC lines with embedded defect detection.
- Electronics:Thin-glass substrates for displays and touch panels. Dutch and German electronics manufacturers commission specialized cutting for cover glass where edge chipping compromises structural integrity.
- Furniture:Decorative tempered glass for tables and shelving with relaxed tolerance specifications. Italian furniture clusters in Lombardy favor cost-optimized automated scoring over premium CNC configurations.
Construction absorbs the highest equipment volume. Electronics shows the steepest expansion trajectory as display manufacturers diversify supply chains.
Technology:
Margin structure diverges sharply between consumables-intensive methods and capital-intensive alternatives with different aftermarket revenue profiles.
- Water Jet Cutting:Abrasive high-pressure streams cutting thick architectural glass up to 19 mm without thermal damage. German fabricators serving premium lamination applications specify these for edge quality that determines interlayer bond strength.
- Diamond Cutting:Synthetic diamond wheel scoring with coolant-dependent slurry systems. REACH compliance constraints on diamond slurry chemistry concentrate R&D investment among Italian equipment specialists serving enclosed cutting environments.
- Hot Cutting:Thermal shock methods leveraging residual stress in tempered glass. Limited adoption outside specialty automotive applications where fracture propagation control is critical.
- Cold Cutting:Mechanical scoring without thermal assistance for thin-glass electronics substrates. Dutch display glass processors favor these for cover glass where thermal distortion risks optical performance.
Diamond cutting dominates installed base. Water jet cutting commands premium positioning.
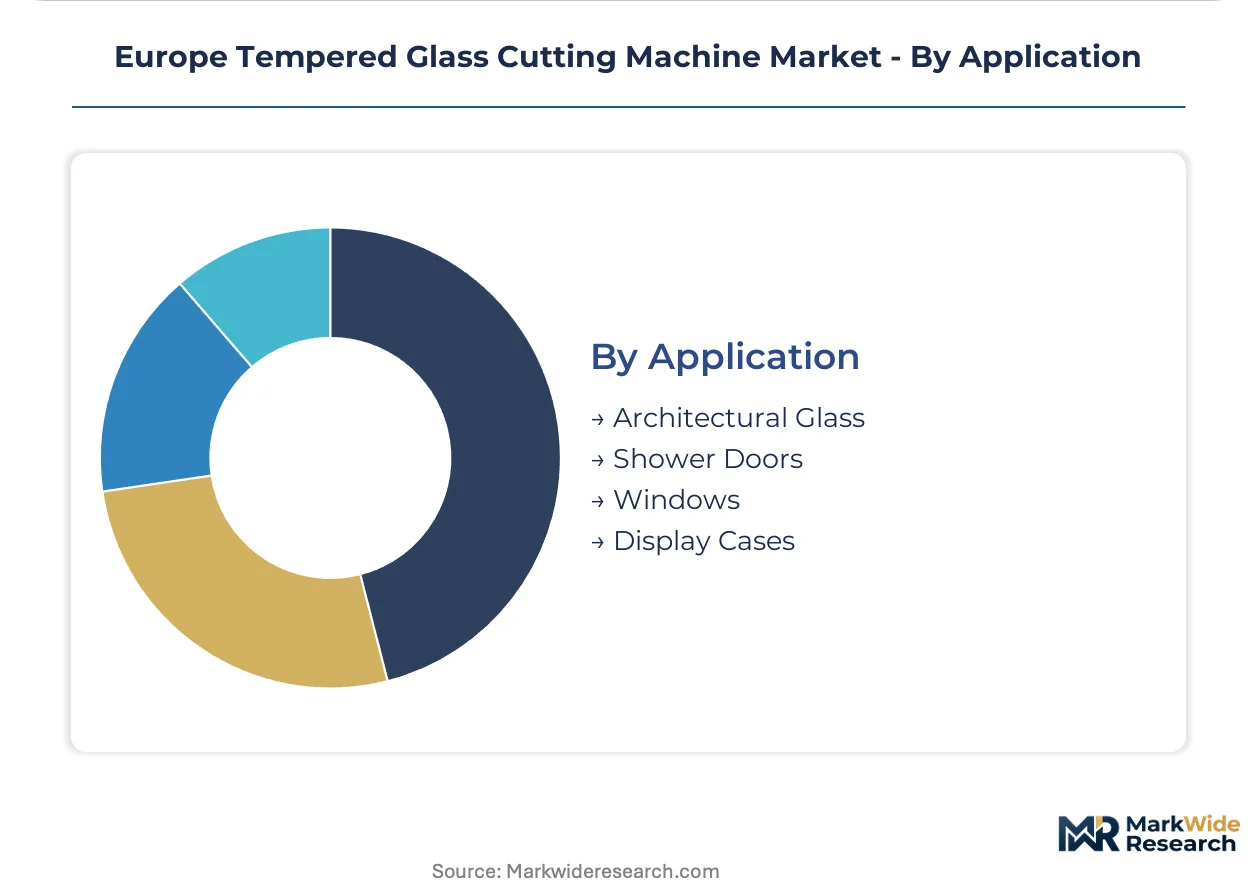
Application:
Customer type segmentation separates high-volume standardized producers from custom fabricators where programming complexity and setup frequency determine equipment specification.
- Architectural Glass:Large-format panels for curtain walls and structural glazing. French fabricators serving Paris-region commercial retrofits specify CNC lines capable of complex geometric optimization.
- Shower Doors:Standardized tempered panels with drilled hinge and handle penetrations. Italian manufacturers in the Veneto region automate these high-volume, low-variance production runs.
- Windows:Insulated glass unit components with precise edge deletion requirements. German window fabricators integrate cutting lines with automatic spacer bar placement downstream.
- Display Cases:Retail fixture glass combining tempered safety with optical clarity. Polish greenfield processors entering this segment favor fully automated configurations without legacy workflow constraints.
Architectural glass generates the highest absolute equipment demand. Display cases are climbing the fastest as Eastern European fabrication capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators deploy CNC systems for high-precision architectural glazing, while Italian processors favor automated scoring for furniture and shower door volume production. This consumption-mix differential reflects divergent end-use specialization across national glass processing clusters.
Germany
Rhine corridor fabricators between Mainz and Cologne anchor European demand for precision cutting equipment serving EU Green Deal building retrofits. KBA workplace safety inspectorates enforce stringent noise and silica exposure limits that shape enclosed machine designs. Bavarian glass processors in the Munich-Stuttgart industrial zone commission predictive maintenance contracts for installed CNC lines.
Italy
Veneto-Friuli glass clusters specialize in complex geometric facade patterns requiring multi-axis CNC positioning capability. REACH compliance constraints on diamond slurry chemistry concentrate R&D investment among domestic equipment specialists. Lombardy furniture manufacturers automate high-volume tempered glass production with cost-optimized scoring configurations.
France
Paris-region commercial retrofit projects drive demand for CNC lines capable of thermal performance glazing specifications. ANSM does not regulate cutting equipment directly, but national workplace safety inspectorates enforce exposure limits affecting machine enclosure standards. Franco-German border automotive suppliers prioritize automated inspection integration for safety-rated windshield production.
Netherlands
Solar module manufacturers commission fiber-laser cutting configurations for thin-film and bifacial photovoltaic panel substrates. ECHA enforcement of REACH coolant chemistry restrictions accelerates water-based formulation development among equipment users. Dutch electronics manufacturers specify cold cutting methods for display cover glass where thermal distortion risks optical performance.
Poland
Greenfield glass processors expand capacity without legacy equipment constraints, favoring fully automated cutting configurations from initial commissioning. EU Machinery Directive CE marking governs operational safety for all imported equipment. Warsaw-region fabricators serving display case and retail fixture markets adopt automated lines to capture Western European outsourcing demand.
Europe Tempered Glass Cutting Machine Market Competitive Landscape
Capability concentration sits with Austrian and Finnish engineering specialists; scale advantage sits with Italian machinery fabricators serving volume architectural markets. The vendor base organizes around three strategic archetypes: integrated solution providers bundling equipment with predictive maintenance contracts, consumables-intensive specialists monetizing diamond wheel refurbishment and slurry logistics, and precision automation houses targeting photovoltaic and electronics substrate applications. Competitive moves concentrate on geographic expansion into Eastern European greenfield sites and technology licensing for laser cutting configurations.
Among Austria-centered engineering houses, LISEC Group exemplifies the integrated solution archetype through service network density. Italian specialists Bottero S.p.A. and Bavelloni SpA occupy positions within the consumables-intensive tier, leveraging deep regional fabrication relationships. Finnish engineering heritage represented by Glaston Corporation anchors the predictive maintenance contract model for architectural glass processors.
| Leading Market Players |
|---|
| LISEC Group |
| Bottero S.p.A. |
| Glaston Corporation |
| Adelio Lattuada S.r.l. |
| Intermac Glass Division |
| Bystronic Glass GmbH |
| CMS Glass Machinery |
| Bavelloni SpA |
| HEGLA GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Synthetic diamond abrasive production concentrates in Asian manufacturing centers, tethering European OEM margin pools to logistics disruptions and currency fluctuation while downstream fabricators face compressed capital expenditure timelines. This upstream concentration forces pricing power toward consumables-intensive specialists who control diamond wheel refurbishment and slurry logistics networks.
Pricing Analysis
Long-term service contracts dominate the European tempered glass machinery base, with predictive maintenance agreements and consumables logistics generating recurring revenue streams that exceed original equipment margins. Price differentiation separates premium CNC configurations with embedded AI defect-detection from standard automated scoring systems and economy manual cutting tools. Pricing pressure stems from industrial electricity price volatility in Germany and Italy, which delays fabricator capital approvals and extends replacement cycles. Mid-cap architectural processors exhibit highest price sensitivity, prioritizing total cost of ownership optimization over upfront equipment expenditure.
Supply Chain Analysis
Export-control regimes on high-power fiber-laser components constrain technology flows into European photovoltaic glass fabrication, limiting sourcing options for Dutch and German solar module manufacturers. Supply chains draw from China for synthetic diamond abrasives, Germany for precision servo-drive components, and Italy for CNC controller platforms. Single-source vulnerability concentrates in diamond slurry chemistry, where REACH compliance restrictions constrain formulation alternatives. Distribution runs through Austria-centered service networks and Italian machinery fabricators serving volume architectural markets across the Rhine corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's tempered glass cutting machine market sits in early-cycle expansion, with EU Green Deal building renovation mandates accelerating precision equipment adoption ahead of legacy system replacement saturation.
For Market Incumbents: Insulate installed-base revenue through predictive maintenance contract expansion and captive diamond wheel refurbishment capacity. Counter laser cutting substitution threats by embedding AI defect-detection modules ahead of EU AI Act high-risk system classification. Prioritize vertical integration into coolant recovery systems to offset REACH compliance cost pressure. For New Entrants and Emerging Players: Establish a beachhead in Polish and Czech greenfield fabrication sites where legacy equipment absence favors fully automated configurations from commissioning. Target display case and retail fixture applications climbing fastest as Eastern European capacity expands. Deploy direct service network presence rather than distributor partnerships to capture aftermarket margin pools. For Investors and Strategic Acquirers: Capital is best deployed toward consumables-intensive specialists with deep regional fabrication relationships and diamond slurry logistics control. Long-term viability centers on vendors monetizing installed-base data analytics rather than pure hardware sales across the projection horizon. Watch photovoltaic glass specification tightening as inflection signal for laser cutting technology migration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | LISEC Group and Glaston Corporation anchor recurring revenue from Bavarian and Rhine corridor CNC installations. |
| Laser Cutting Technology Licensing | Fiber-laser configurations for Dutch solar manufacturers compress process steps between cutting and edge-sealing. |
| Diamond Slurry Chemistry R&D Investment | Italian equipment specialists accelerate water-based alternatives under ECHA REACH enforcement pressure. |
| Eastern European Greenfield Market Entry | Polish and Czech processors without legacy constraints favor fully automated configurations from initial commissioning. |
| AI Defect-Detection Module Integration | Autonomous CNC controllers may trigger EU AI Act high-risk classification, favoring first-mover compliance investment. |
Research Methodology
Initial hypotheses were tested against primary input from glass fabrication plant managers, OEM procurement teams, aftermarket service heads, and architectural glazing project engineers and refined through secondary validation. Primary fieldwork combined structured interviews with equipment operators and maintenance directors across German Rhine corridor clusters, Italian Veneto-Friuli glass processing regions, and Polish greenfield sites. Secondary sources encompassed EU Machinery Directive CE marking databases, ECHA REACH compliance filings, customs trade records for diamond abrasive imports, and SEC disclosures from listed machinery vendors. Bottom-up equipment shipment tallies were triangulated against top-down construction and automotive glass demand estimates.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by product type, end user, technology, and application dimensioning the forecast framework. CAGRs were derived from installed base replacement cycles, greenfield capacity expansion timelines, and technology substitution elasticities. Industry-specific inputs included EU Green Deal building retrofit penetration rates, photovoltaic glass fabrication capacity buildouts in the Netherlands and Germany, and CNC programming specialist scarcity indices affecting automation adoption velocity.
Stress conditions across industrial electricity price volatility, diamond abrasive supply disruption scenarios, and EU AI Act implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Rhine corridor demand concentration and REACH compliance evolution. Material shifts in EU Green Deal funding allocation or synthetic diamond supply chain restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Roller Bearings Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Above 300mm Cooling Fans Market
Industrial Equipment
Actuators Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Digital Tube Roller Market