
 Digital Tube Roller Market | 2026-2036
Digital Tube Roller Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tube Roller Market Insights
REACH compliance is broadening the cost-of-entry calculus for European suppliers of digital tube rollers, forcing material traceability and control-system documentation upgrades. Thermo Scientific leverages its global service infrastructure to sustain recurring revenue from biopharma contract manufacturers. Benchmark Scientific competes on price-performance positioning in academic research procurement channels. Qingdao Yosion Intelligent Technology anchors its position through in-house production of stepper motor control modules.
A digital tube roller is a benchtop or floor-mounted electromechanical device that rotates cylindrical vessels at programmable speeds, typically between 1 and 80 revolutions per minute, to achieve homogeneous mixing, coating, or cell culture suspension. Its primary industrial purpose spans pharmaceutical quality-control labs, materials-testing facilities, and battery-manufacturing cleanrooms where reproducible rotational kinematics determine batch consistency. Automatic units command premium pricing due to integrated programmable logic controllers and multi-vessel parallel processing capacity, while manual and semi-automatic configurations retain share in budget-constrained educational institutions. Digital technology adoption is displacing legacy pneumatic actuation in high-throughput screening environments where closed-loop speed regulation directly impacts experimental reproducibility.
The FDA's 21 CFR Part 11 framework governs electronic records in U.S. pharmaceutical applications, while the EU MDR imposes design-dossier requirements on devices used in medical-device manufacturing workflows. China's NMPA has aligned its digital medical equipment standards with IEC 61010 safety protocols, tightening market access for imported control systems. Stakeholders must monitor divergent electromagnetic compatibility certification timelines across FDA, EMA, and NMPA jurisdictions when planning multi-regional product launches.
Market Dynamics
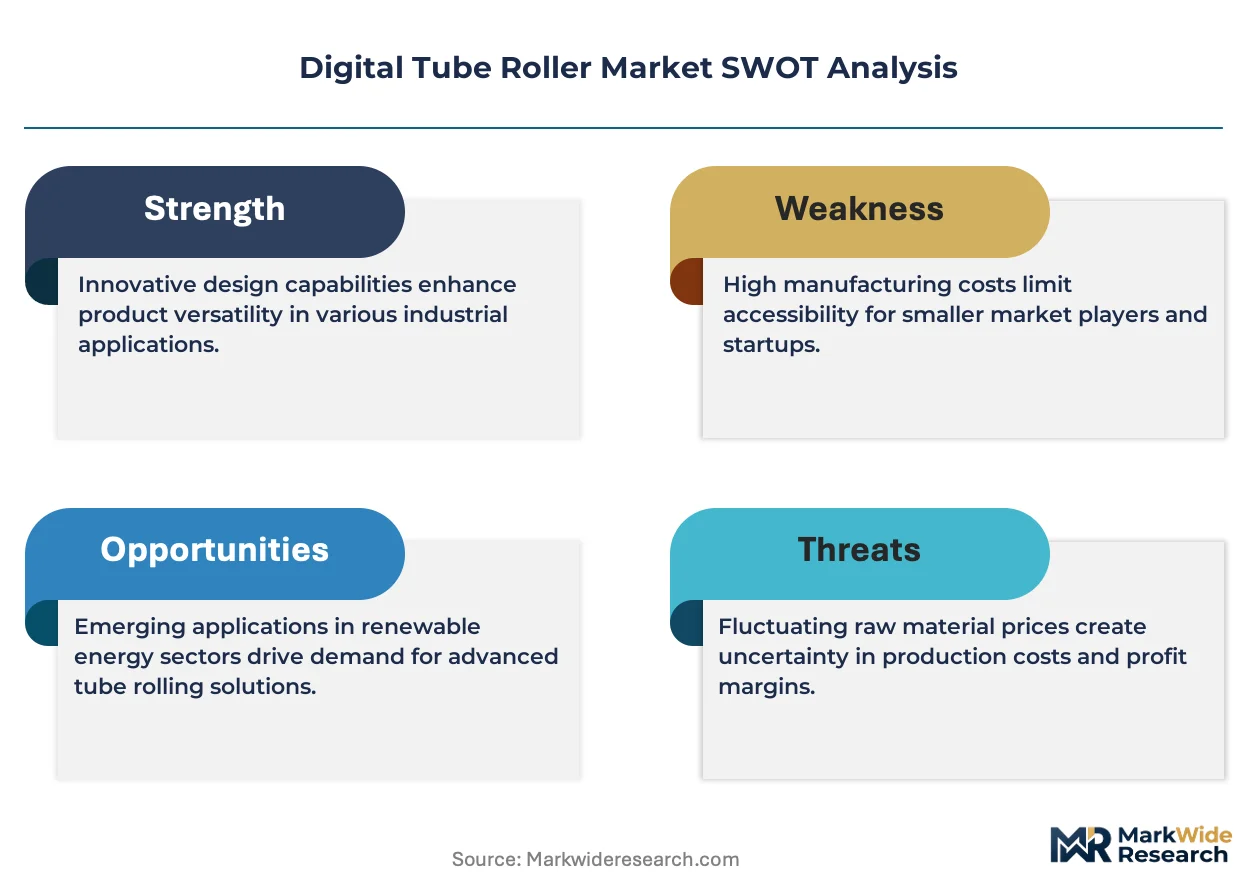
Automated sample preparation workflows in biopharmaceutical quality-control labs are displacing pneumatic actuation systems, forcing control-system suppliers to integrate programmable logic controllers with closed-loop speed regulation. This technology shift compresses procurement cycles for legacy equipment while elevating validation requirements.
Growth Catalysts
- 21 CFR Part 11 Mandate:The FDA's electronic records framework compels U.S. pharmaceutical manufacturers to replace analog tube rollers with validated digital control systems that capture audit trails.
- Cell Culture Suspension Demand:Biopharma contract manufacturers in the Boston-Cambridge corridor require multi-vessel parallel processing capacity to scale monoclonal antibody production.
- Battery Manufacturing Cleanrooms:Solid-state battery developers in Germany's precision instrumentation cluster demand reproducible rotational kinematics for electrode coating consistency.
Market Restraints
- Stepper Motor Supply Concentration:Control module production concentrates in East Asian component suppliers, exposing European OEMs to lead-time volatility.
- REACH Compliance Burden:ECHA material traceability requirements force material substitutions and documentation upgrades that inflate unit economics for mid-tier suppliers.
- Academic Budget Constraints:Manual and semi-automatic configurations retain procurement share in educational institutions, capping average selling price expansion.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for pharmaceutical manufacturing equipment create localized assembly opportunities for automated tube roller systems.
- ISO 13485 Convergence:Medical-device manufacturing workflows increasingly demand quality-management certification, opening premium positioning for validated equipment vendors.
- Service Revenue Unbundling:Biopharma contract manufacturers seek standalone calibration and validation contracts separate from hardware procurement.
Industry Challenges
- Control Systems Integration:Legacy laboratory information management systems require custom middleware development for seamless digital tube roller connectivity.
- Electromagnetic Compatibility Certification:Divergent FCC, EMA, and NMPA timelines delay multi-regional product launches and compress revenue recognition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tube Roller Market |
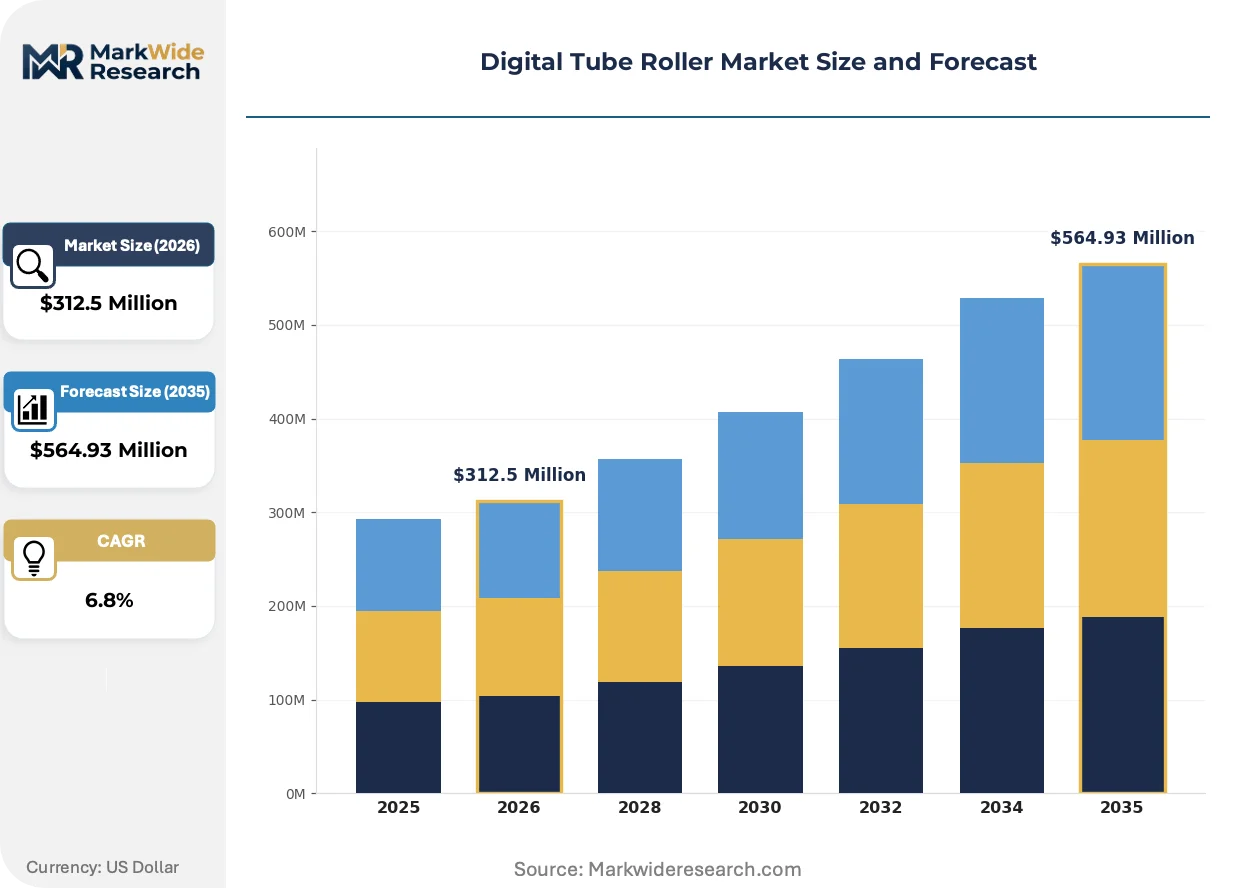
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Electric End User: Manufacturing, Construction, Aerospace, Automotive Application: Pipe Bending, Tube Forming, Welding, Assembly Technology: Hydraulic, Mechanical, Pneumatic, Digital |
| Companies Covered | Thermo Scientific, Benchmark Scientific, Crystal Industries, Qingdao Yosion Intelligent Technology, Xiamen TOB New Energy, AHN Biotechnologie, Wuxi NEST Biotechnology, Globe Scientific, Starlab International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tube Roller Market Trends and Innovations
Closed-loop speed regulation and multi-parameter process monitoring are compressing equipment replacement cycles while elevating service contract attach rates. These shifts favor suppliers with captive calibration infrastructure.
Brushless DC motor technology with integrated encoder feedback is expanding into high-throughput screening environments. Pharmaceutical quality-control labs in North America are adopting these systems to achieve sub-rpm precision for dissolution testing protocols. This capability compression is eliminating pneumatic actuation from mid-tier procurement specifications.
EU MDR design-dossier requirements are extending validation timelines for devices used in medical-device manufacturing workflows. European OEMs must submit technical documentation to notified bodies before commercial placement. Germany's precision instrumentation cluster is responding by consolidating regulatory affairs functions across product families.
Biopharma procurement teams are unbundling after-sales service from capital equipment purchases. Contract manufacturers now issue separate RFPs for installation qualification, operational qualification, and ongoing calibration. This pattern is most visible in the Boston-Cambridge life sciences corridor where specialized service providers are capturing recurring revenue streams.
Digital Tube Roller Market Segmentation
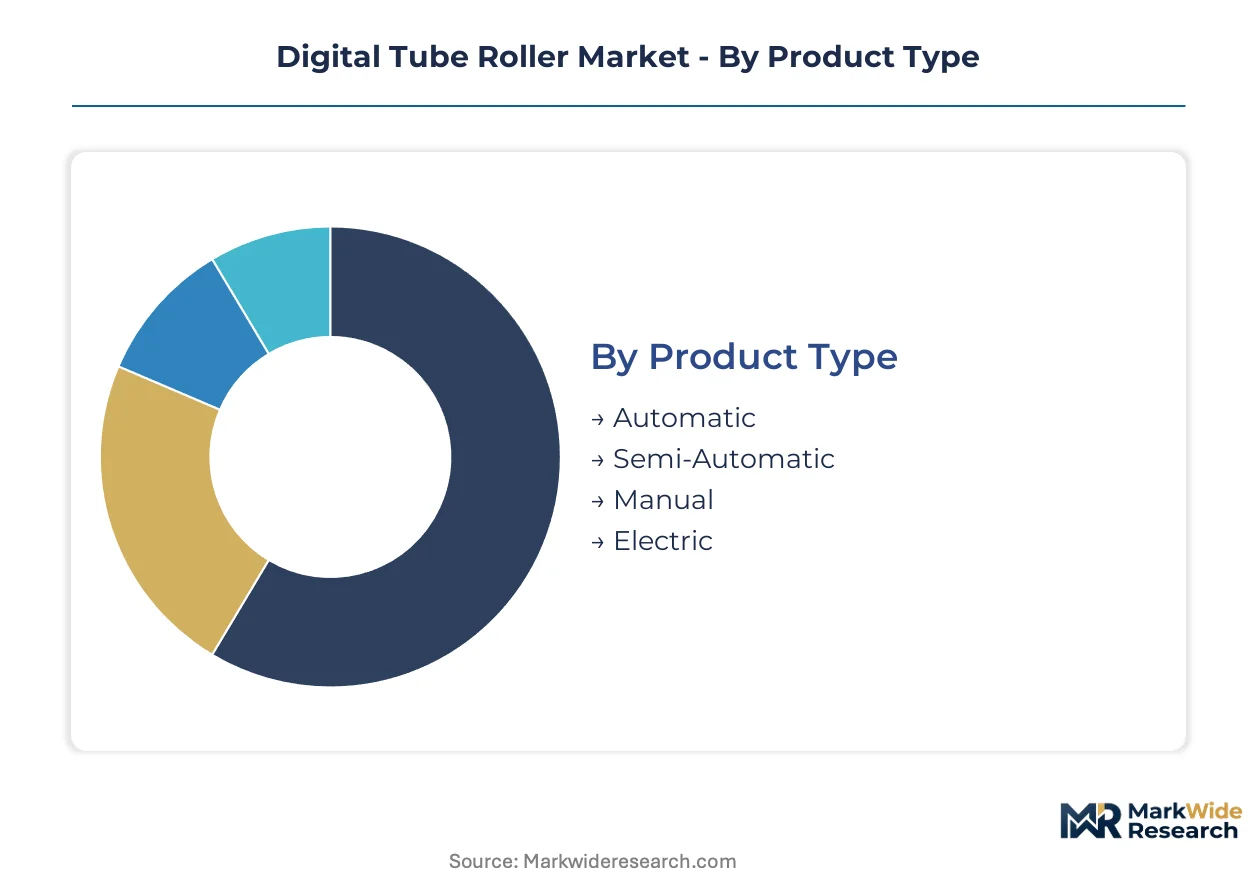
Equipment replacement cycles in pharmaceutical quality-control labs are fragmenting demand across automation tiers. Procurement teams now segment purchases by validation requirements rather than throughput alone.
Product Type:
Upgrade trajectories from manual to automatic configurations are compressing replacement windows as FDA 21 CFR Part 11 mandates take hold.
- Automatic:Integrated programmable logic controllers enable closed-loop speed regulation between 1-80 RPM with full audit trail capture. Biopharma contract manufacturers in the Boston-Cambridge corridor require multi-vessel parallel processing to scale monoclonal antibody production.
- Semi-Automatic:Hybrid designs combine digital speed display with manual vessel loading. Academic research institutions in Germany balance budget constraints against basic reproducibility needs.
- Manual:Hand-cranked rotation without electronic control dominates educational procurement where capital budgets are capped.
- Electric:AC motor-driven systems with analog speed control serve legacy manufacturing workflows not yet subject to electronic records mandates.
Volume placements concentrate in Semi-Automatic; the faster expansion belongs to Automatic.
End User:
Cost tier differentiation separates validated equipment buyers from specification-driven commodity purchasers.
- Manufacturing:Battery electrode coating operations in Germany's precision instrumentation cluster demand sub-rpm precision for solid-state cell consistency.
- Construction:Materials-testing facilities specify ruggedized housings for field-portable dissolution testing of geopolymer samples.
- Aerospace:Specialty alloy tube forming for hydraulic systems requires programmable rotational kinematics to prevent work-hardening.
- Automotive:EV battery pack manufacturers in Stuttgart adopt automated tube rollers for thermal interface material mixing.
Manufacturing commands the steepest expansion trajectory; Construction maintains the largest installed base.
Application:
Customer type segmentation reveals divergent specification priorities between R&D and production environments.
- Pipe Bending:Mandrel-supported rotation prevents ovality in thin-wall tubing for medical-device manufacturing workflows.
- Tube Forming:Incremental shaping of cylindrical vessels requires precise angular positioning for heat-exchanger production.
- Welding:Continuous rotation during orbital welding ensures penetration consistency in pharmaceutical-grade stainless steel.
- Assembly:Component coating operations in cleanrooms demand enclosed chamber designs with HEPA filtration integration.
Assembly applications are gaining share fastest; Pipe Bending retains the deepest specification history.
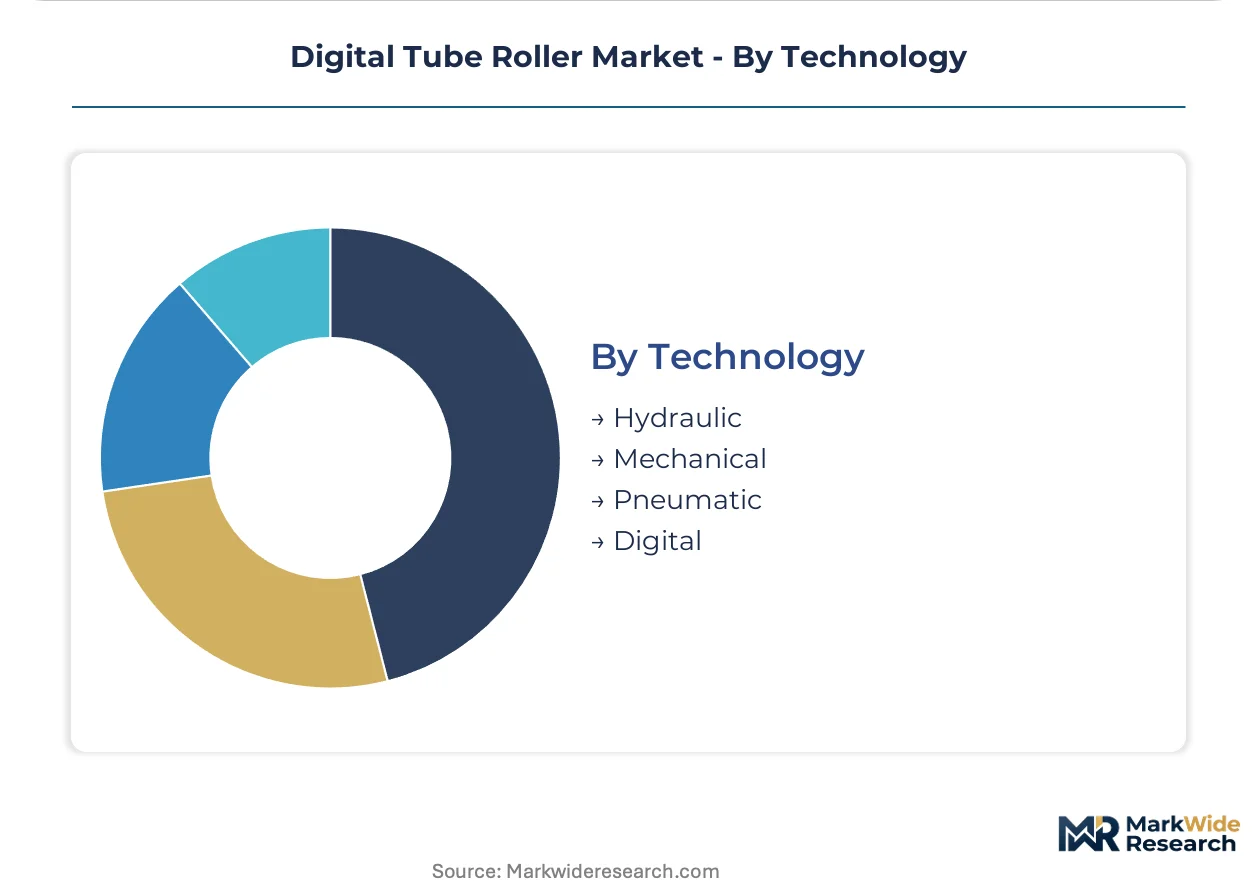
Technology:
Supply concentration in East Asian stepper motor suppliers is forcing technology migration decisions.
- Hydraulic:High-torque fluid power systems persist in heavy-wall tube forming where electric motors lack sufficient stall torque.
- Mechanical:Gear-driven rotation remains cost-competitive for single-speed educational equipment.
- Pneumatic:Compressed air actuation is being displaced from high-throughput screening environments by digital closed-loop alternatives.
- Digital:Brushless DC motors with encoder feedback achieve sub-rpm precision for dissolution testing protocols in North American pharmaceutical labs.
Digital systems are climbing the fastest; Hydraulic retains niche dominance in heavy-forming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical production-linked incentive zones are pulling assembly capacity away from traditional East Asian component hubs. Special economic zones in Gujarat and Telangana now host tube roller system integrators serving contract research organizations.
United States
FDA's 21 CFR Part 11 enforcement is accelerating replacement of analog equipment in Boston-Cambridge biopharma corridors. The mandate requires electronic audit trails for all quality-control equipment used in drug manufacturing. Massachusetts-based contract manufacturers now specify programmable logic controllers with closed-loop speed regulation as baseline procurement requirements.
Germany
Solid-state battery developers in Stuttgart's precision instrumentation cluster demand sub-rpm rotational precision for electrode coating consistency. ECHA's REACH material traceability requirements are forcing suppliers to upgrade documentation systems for stepper motor control modules. Baden-Württemberg's automotive supply base is repurposing metrology expertise toward cleanroom equipment validation.
China
NMPA alignment with IEC 61010 safety protocols is tightening market access for imported digital control systems. Domestic manufacturers in Shenzhen and Suzhou are capturing share through in-house production of encoder feedback modules. The Yangtze River Delta concentration of battery research institutes is driving demand for multi-vessel parallel processing systems.
India
CDSCO's harmonization with international medical device standards is elevating validation requirements for pharmaceutical manufacturing equipment. PLI scheme incentives for pharmaceutical machinery are attracting localized assembly of automated tube roller systems. Hyderabad's vaccine manufacturing corridor represents the fastest-growing demand pocket for validated digital control systems.
Japan
PMDA's quality management system inspections are extending validation timelines for equipment used in regenerative medicine production. METI funding for next-generation battery research is driving demand in Osaka-Kobe industrial zones. Kansai-based precision motor manufacturers are supplying brushless DC systems for dissolution testing protocols.
Digital Tube Roller Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Thermo Scientific leverages global service infrastructure to capture recurring calibration revenue from biopharma contract manufacturers. Mid-tier suppliers compete on price-performance positioning in academic procurement channels. Consolidation pressure is intensifying as REACH compliance costs force material documentation upgrades that favor scaled players with captive regulatory affairs functions.
Among laboratory equipment conglomerates, Thermo Scientific anchors the premium service-integrated tier through its validated system offerings. Benchmark Scientific occupies a position within the mid-tier price-performance segment serving educational institutions. Qingdao Yosion Intelligent Technology exemplifies the vertically integrated specialist archetype through its captive stepper motor control module production. These three patterns represent the dominant competitive configurations in current procurement environments.
| Leading Market Players |
|---|
| Thermo Scientific |
| Benchmark Scientific |
| Crystal Industries |
| Qingdao Yosion Intelligent Technology |
| Xiamen TOB New Energy |
| AHN Biotechnologie |
| Wuxi NEST Biotechnology |
| Globe Scientific |
| Starlab International |
| Others |
Pricing and Supply Chain Analysis
Biopharma contract manufacturers in the Boston-Cambridge corridor now mandate closed-loop speed regulation and full audit trail capture as baseline procurement requirements, forcing control module suppliers to qualify dual-source encoder feedback vendors and absorb documentation upgrade costs that compress mid-tier margins.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to brushless DC motor systems with integrated encoder feedback, while spot inventory of legacy pneumatic actuators trades at distressed levels. Pricing stratifies across validated automatic, semi-automatic, and manual tiers, with FDA 21 CFR Part 11 certification and ISO 13485 quality management driving the widest spreads. Cost compression in semi-automatic configurations is intensifying because REACH compliance forces material substitutions and documentation upgrades. Academic research institutions in Germany exhibit the highest price sensitivity, while biopharma contract manufacturers in North America prioritize validation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European OEMs now mandate qualified suppliers for stepper motor control modules in both China and Japan, reducing single-source exposure to Shenzhen component vendors. Production draws from concentrated encoder feedback manufacturing in Suzhou, brushless DC motor assembly in Osaka-Kobe, and precision machining in Stuttgart. Tariff exposure on Chinese control electronics threatens margin stability for mid-tier suppliers without captive Asian assembly. Distribution runs through laboratory equipment distributors serving pharmaceutical quality-control labs, with direct OEM relationships dominating high-volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race where captive production of stepper motor control modules determines margin defense and supply security against East Asian component volatility.
For Market Incumbents: Lock in biopharma contract manufacturers through unbundled service contracts covering installation qualification, operational qualification, and ongoing calibration. Acquire specialized validation service providers in the Boston-Cambridge corridor to deepen regulatory affairs capabilities. Threats include Qingdao Yosion's backward integration into encoder feedback production and REACH compliance costs that favor scaled players with captive documentation systems.
For New Entrants and Emerging Players: India's PLI scheme for pharmaceutical manufacturing equipment opens a window for localized assembly of automated tube roller systems serving Hyderabad's vaccine manufacturing corridor. Target academic research institutions in Germany with semi-automatic configurations that balance basic reproducibility against budget constraints. Pursue a go-to-market angle emphasizing rapid customization of vessel capacity and speed ranges for contract research organizations.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive control module production and established regulatory dossiers. Long-term viability hinges on service revenue unbundling and recurring calibration contract attach rates. Watch for consolidation signals when REACH compliance costs force mid-tier suppliers to seek scaled partners with consolidated material traceability systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Modules | Captive stepper motor production insulates margins from East Asian lead-time volatility. |
| Regulatory Dossier Consolidation | EU MDR design-dossier submissions across product families reduce validation timelines for German OEMs. |
| Service Revenue Unbundling | Separate RFPs for IQ/OQ/calibration capture recurring streams from biopharma contract manufacturers. |
| Localized Assembly in India | PLI scheme incentives attract system integrators to Gujarat and Telangana pharmaceutical zones. |
| Brushless DC Platform Migration | Encoder feedback systems achieve sub-rpm precision for North American dissolution testing protocols. |
Research Methodology
Multi-period observation of equipment replacement cycles, regulatory submission timelines, and procurement specification changes anchored the trend analysis, supplemented by interviews with biopharma quality-control directors, laboratory equipment procurement managers, regulatory affairs specialists at European OEMs, and aftermarket service heads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH substance databases, NMPA medical device registration filings, and IEC 61010 safety standard revisions. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis.
Input-output matrices mapped brushless DC motor adoption rates, validation requirement tiering, and regional regulatory cluster alignment across the projection horizon. Segmentation dimensions included automation tier, end-use industry, application type, and technology platform. CAGRs derived from fitted growth curves applied to equipment installed base turnover and biopharma capacity expansion pipelines. Forecast inputs incorporated monoclonal antibody production scaling in the Boston-Cambridge corridor and solid-state battery electrode coating demand in Stuttgart.
The model assumes a particular technology adoption path; alternative pathways for pneumatic-to-digital displacement would alter the outlook if battery research priorities shift or academic budget constraints prolong legacy equipment retention. Deviation in stepper motor supply chain consolidation or REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Europe Industrial Centrifuge Market