
 Liquid Cold Plates Market | 2026-2036
Liquid Cold Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Cold Plates Market Foresight
Asset-light leasing models for thermal infrastructure is narrowing the capital barrier for mid-tier data center operators seeking liquid cooling upgrades. Boyd Corporation leverages in-house production of aluminum microchannel plates to sustain margin control across North American deployments. Sanhua Holding Group anchors its position through backward integration into precision extrusion and brazing operations. Trumony competes by specializing in copper flat-plate architectures for high-performance computing clusters.
Liquid cold plates are metal heat transfer devices featuring internal fluid channels—typically machined, brazed, or diffusion-bonded—that circulate coolant to remove heat from electronic components, with channel widths often ranging from 0.5 mm to 3 mm depending on thermal flux requirements. Microchannel plates command premium positioning due to their superior heat transfer coefficients in power electronics and laser systems. Flat plates occupy the volume tier across automotive battery packs where packaging constraints dominate design priorities. Copper material configurations lead in aerospace and defense applications where thermal conductivity thresholds exceed 350 W/m·K.
The EPA regulates refrigerant emissions under Section 608 of the Clean Air Act, pushing industrial cooling toward closed-loop liquid systems that eliminate vapor-compression dependencies. Ecodesign requirements under the EU F-Gas Regulation mandate progressive reduction of hydrofluorocarbon use, directly expanding addressable demand for liquid cold plate alternatives in European electronics manufacturing. China's MIIT enforces GB standards for energy efficiency in data centers, creating compliance-driven retrofit cycles across server farms in Beijing and Shenzhen. Stakeholders must weigh material substitution timelines against channel geometry investments as regulatory stringency diverges across these three jurisdictions.
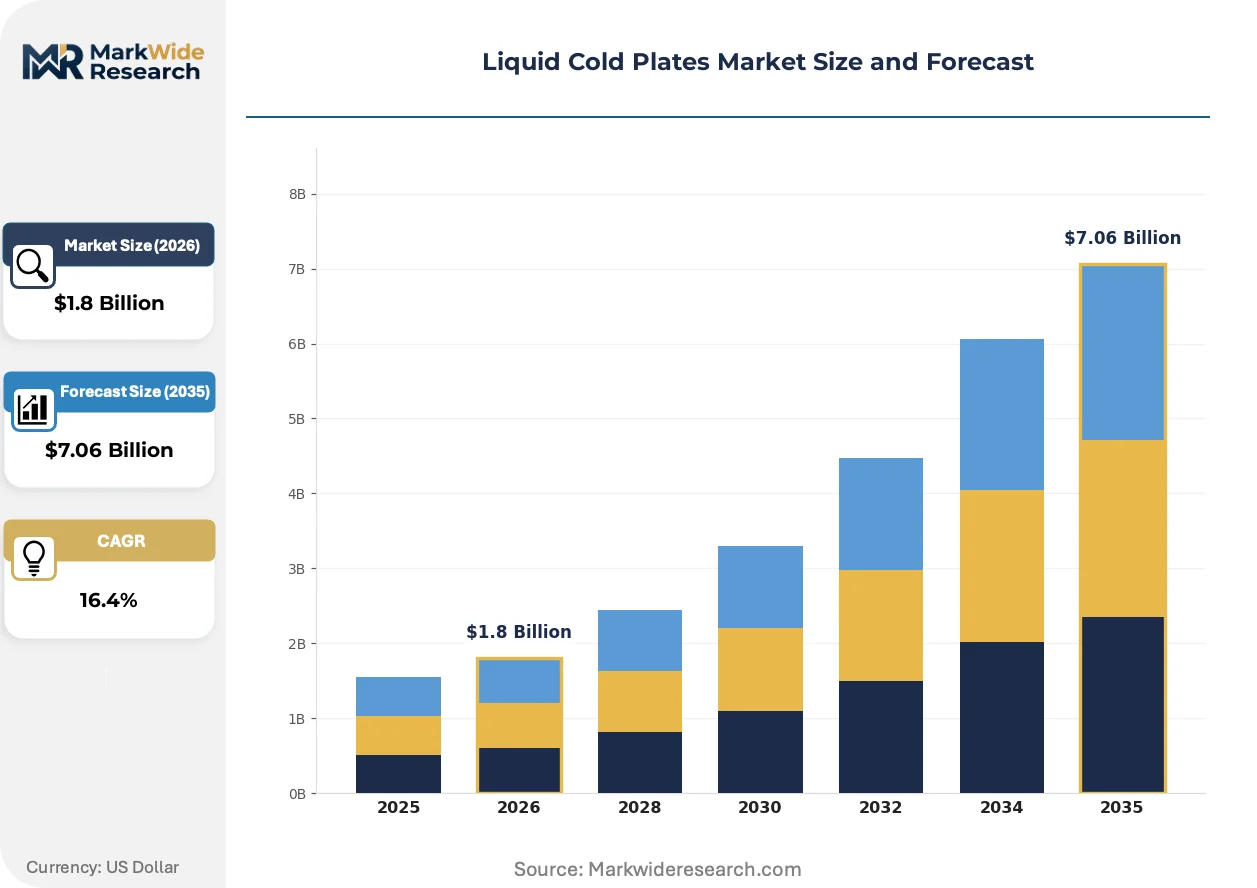
Market Dynamics
Server rack densities exceeding 50 kW per unit are forcing thermal management architectures toward direct liquid contact, collapsing the historical air-cooling design window and accelerating specification cycles across hyperscale and colocation facilities.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions are eliminating vapor-compression alternatives in precision electronics manufacturing, redirecting procurement toward closed-loop liquid cold plate systems.
- AI training clusters:GPU-intensive workloads in generative AI infrastructure are demanding heat flux capabilities beyond 500 W/cm², specifications only microchannel liquid architectures can satisfy.
- Beijing-Shenzhen corridor:China's MIIT GB standards for data center PUE enforcement are triggering retrofit mandates across server farms in these metropolitan clusters.
Market Restraints
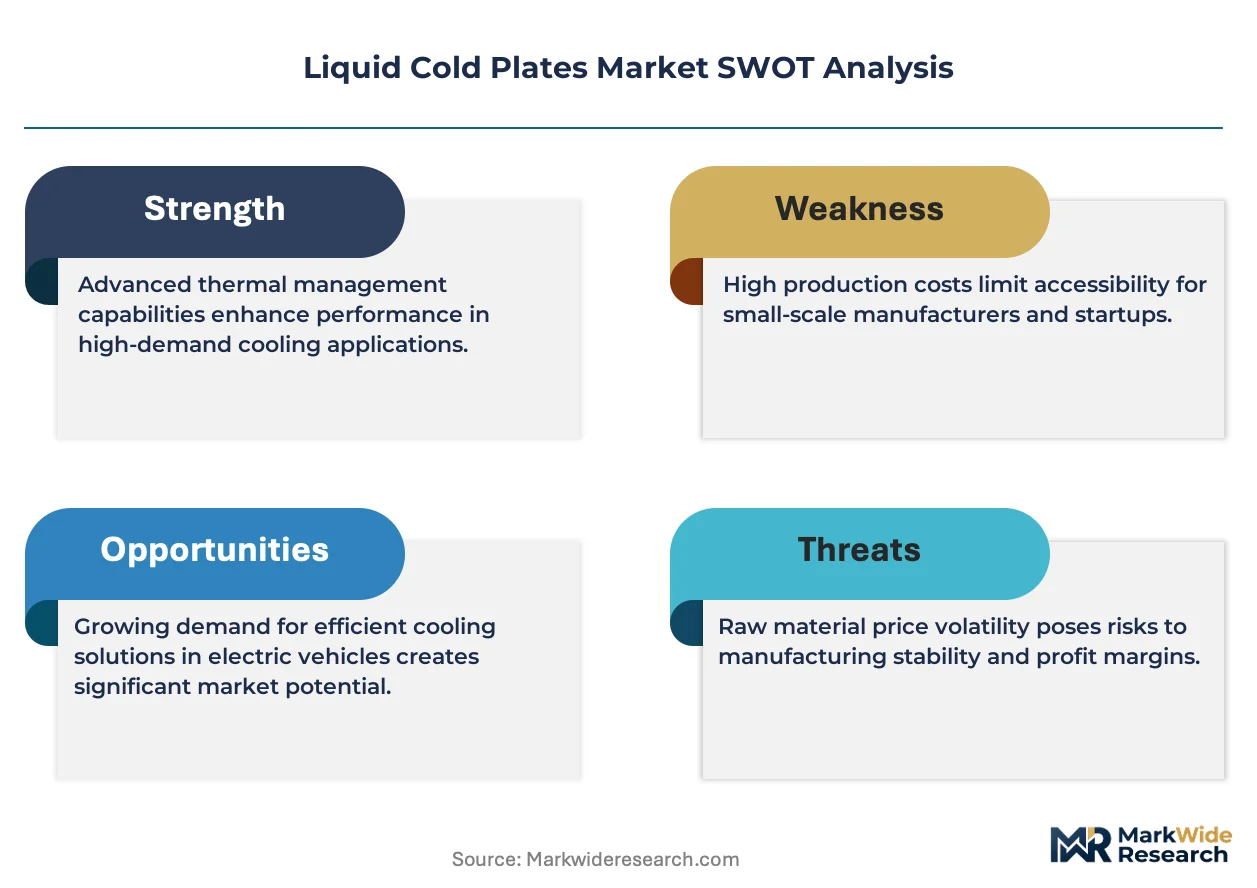
- Copper price volatility:Aerospace-grade thermal conductivity requirements exceeding 350 W/m·K lock designs into copper substrates, exposing margins to London Metal Exchange commodity swings.
- German brazing concentration:Precision diffusion-bonding capacity for microchannel plates clusters in Baden-Württemberg and Bavaria, creating single-source vulnerability for North American module assemblers.
- Refrigerant transition friction:EPA Section 608 technician certification requirements slow field retrofit velocity, compressing deployment timelines for legacy chiller replacements.
Strategic Opportunities
- India data center buildout:Underpenetrated liquid cooling deployment across Noida and Mumbai hyperscale projects offers first-mover positioning before BIS thermal efficiency mandates crystallize.
- Automotive 800V architectures:Silicon carbide inverter integration in battery electric vehicles is converging with liquid cold plate thermal management, opening volume tier design contracts.
- Asset-light leasing models:Thermal infrastructure-as-a-service channels are emerging for mid-tier colocation operators, collapsing upfront capital barriers that previously blocked liquid cooling adoption.
Industry Challenges
- Microchannel machining expertise:Channel widths below 1.0 mm require precision CNC and electrochemical machining competencies concentrated among German and Japanese tool suppliers, constraining workforce scalability.
- Multi-jurisdictional certification lag:Simultaneous EPA, REACH, and GB standard compliance for coolant chemistry and pressure vessel ratings extends product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Cold Plates Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plates, Microchannel Plates, Flat Plates, Wavy Plates End User: Aerospace, Electronics, Automotive, Industrial Material: Copper, Aluminum, Stainless Steel, Composites Application: Heat Exchangers, Cooling Systems, Process Cooling, Thermal Management |
| Companies Covered | Yinlun, FRD, Sanhua Holding Group, Trumony, IKD, Boyd Corporation, RETEK, CoolIT Systems, Winshare Thermal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Cold Plates Market Shifts & Advancements
Additive manufacturing of conformal cooling channels is collapsing the tooling cost barrier for low-volume, high-complexity cold plate geometries that traditional machining cannot economically produce.
Topology-optimized lattice structures are digitizing thermal-fluid design workflows by embedding generative algorithms directly into CAD-CAM pipelines. Aerospace prime contractors in Toulouse and Seattle are adopting these tools for satellite payload thermal control. The technology is digitizing how engineering teams iterate channel geometries, compressing prototype cycles from weeks to days.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing coolant formulation shifts across European electronics manufacturing. Industrial consequence includes accelerated qualification of propylene glycol and ionic liquid alternatives. Server OEMs with European assembly footprints are responding by dual-qualifying fluid chemistries to avoid supply interruption.
Hyperscale procurement teams are consolidating supplier panels from twelve-plus vendors to three preferred partners with captive extrusion and brazing capabilities. Channel disruption is most visible in North American cloud infrastructure, where direct OEM-engineering relationships are displacing traditional thermal component distributors. This concentration is compressing margin structures for mid-tier cold plate fabricators without upstream metalworking assets.
Liquid Cold Plates Market Segmentation
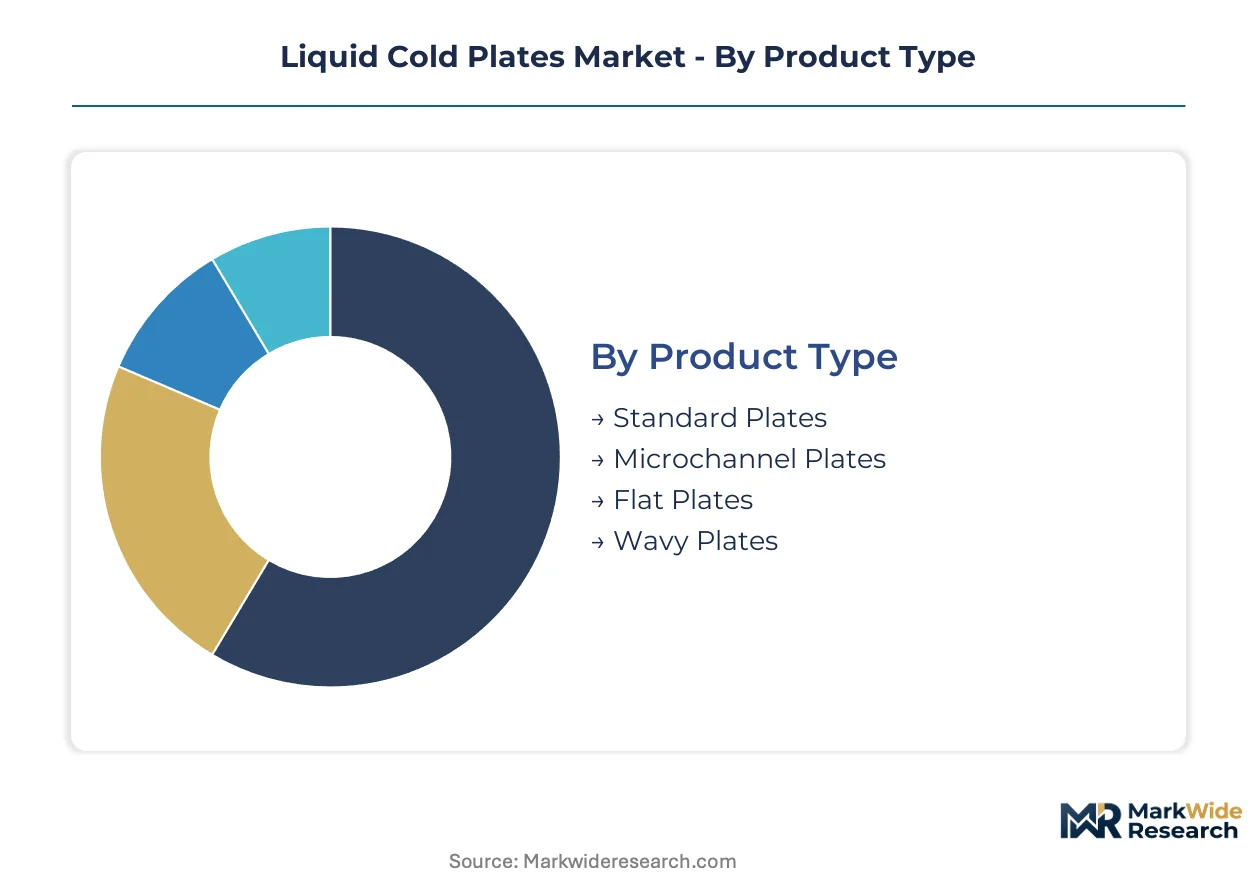
Liquid cold plate architectures diverge sharply across thermal flux requirements and cost constraints. Channel geometry and material selection lock in performance ceilings that reshape procurement patterns across defense, automotive, and hyperscale computing verticals.
Product Type:
Channel architecture spans precision-machined microstructures to stamped wavy geometries, with each design point trading thermal performance against tooling investment and unit economics.
- Standard Plates:Conventional machined or drilled-channel constructions using straight parallel flow paths. Demand concentrates in industrial motor drives and legacy power electronics where thermal loads remain below 200 W/cm² and cost sensitivity dominates procurement decisions in Chinese manufacturing zones.
- Microchannel Plates:Precision structures with hydraulic diameters below 1 mm, typically fabricated via diffusion bonding or electrochemical machining. GPU clusters in generative AI training facilities are absorbing capacity as heat flux requirements exceed 500 W/cm², forcing direct liquid contact architectures.
- Flat Plates:Simple planar geometries optimized for battery pack integration where packaging volume constraints override absolute thermal performance. Automotive 800V silicon carbide inverters are standardizing on aluminum flat-plate configurations.
- Wavy Plates:Corrugated channel profiles enhancing turbulence and heat transfer coefficients through geometric disruption. Process cooling in chemical manufacturing deploys these for fouling resistance.
Established volume favors Standard Plates; emerging adoption favors Microchannel Plates.
End User:
Regulatory pressure and compute intensity are fragmenting demand across sectors with divergent certification timelines and performance thresholds.
- Aerospace:Satellite payload thermal control and avionics cooling demand copper substrates exceeding 350 W/m·K thermal conductivity. FAA certification cycles for manned aircraft systems extend qualification timelines.
- Electronics:Server farms and semiconductor fabrication equipment are driving microchannel specification as rack densities climb. China's MIIT GB standards are retrofitting Beijing and Shenzhen facilities.
- Automotive:Battery electric vehicle battery packs and traction inverters are absorbing aluminum flat-plate capacity. 800V architectures are converging with liquid cooling as standard.
- Industrial:Motor drives, welding equipment, and chemical process cooling sustain demand for cost-optimized standard and wavy plate geometries.
Electronics claims the steepest expansion trajectory; Industrial retains the largest installed base.
Material:
Thermal conductivity hierarchies and commodity price exposure are reshaping material selection across end-use verticals.
- Copper:Unmatched thermal conductivity above 380 W/m·K positions this material for aerospace and defense applications where performance thresholds are non-negotiable. London Metal Exchange price volatility compresses margins for North American fabricators locked into military specifications.
- Aluminum:Density advantages and extrusion compatibility dominate automotive and volume electronics applications. Boyd Corporation's in-house microchannel extrusion capabilities illustrate backward integration strategies.
- Stainless Steel:Corrosion resistance in aggressive chemistries and food-grade process cooling applications. Chemical manufacturing and pharmaceutical equipment specify 316L grades.
- Composites:Emerging aluminum-graphite and copper-diamond metal matrix configurations for coefficient-of-thermal-expansion matching in semiconductor packaging.
Aluminum commands the broadest addressable demand; copper defends the premium tier.
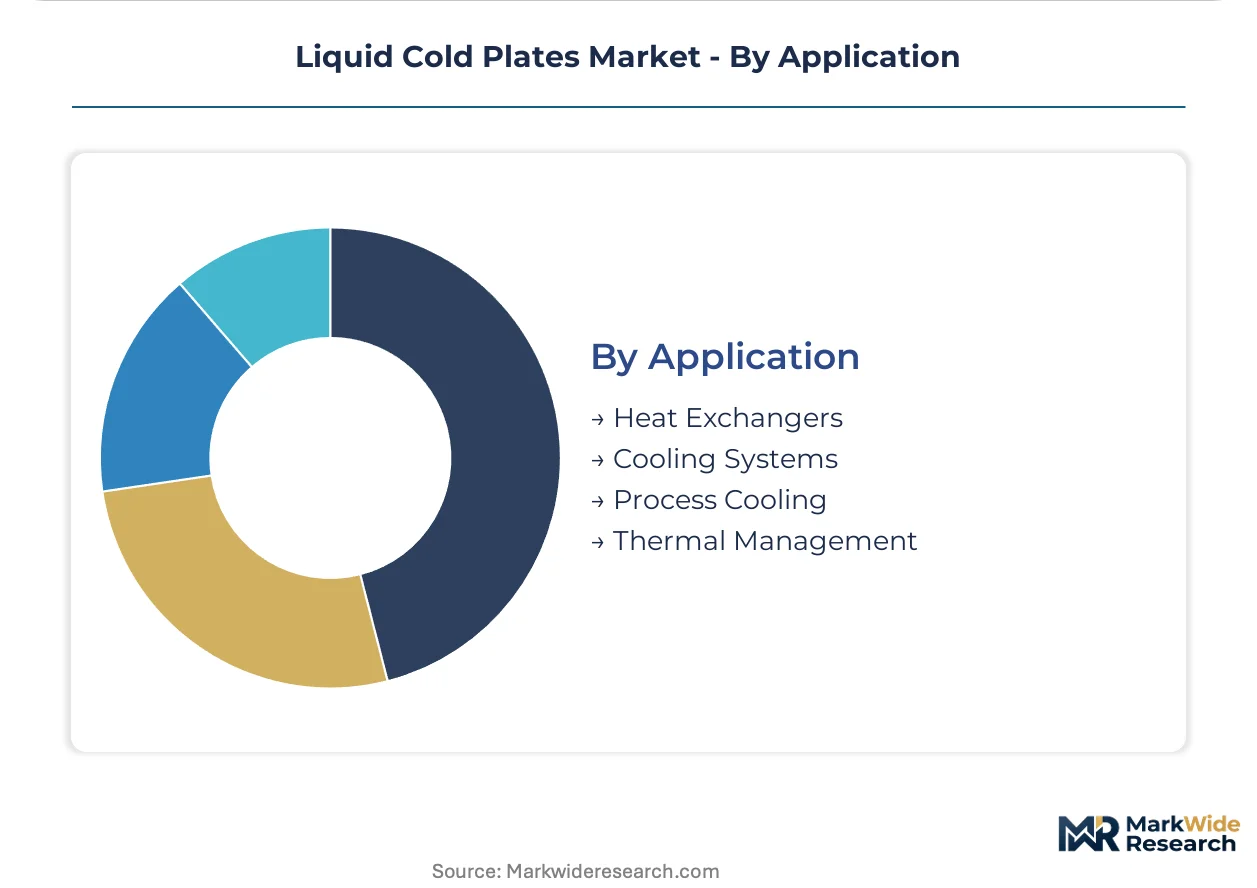
Application:
System-level integration determines whether cold plates function as standalone components or embedded subsystems within larger thermal architectures.
- Heat Exchangers:Cold plates integrated into fluid-to-fluid or fluid-to-air heat exchange systems for secondary cooling loops. Data center chiller replacements under EPA Section 608 are redirecting procurement.
- Cooling Systems:Direct-to-chip and direct-to-component liquid cooling loops in high-performance computing. GPU-intensive AI clusters are collapsing historical air-cooling design windows.
- Process Cooling:Industrial manufacturing equipment including welding power supplies, induction heating, and chemical reactors. Wavy plate geometries address fouling-prone environments.
- Thermal Management:System-level architectures integrating multiple heat transfer modes. Satellite payload design in Toulouse and Seattle is adopting topology-optimized lattice structures.
Cooling Systems is gaining share fastest; Process Cooling maintains replacement-cycle stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory phase-downs of hydrofluorocarbon refrigerants are redirecting procurement toward liquid cooling architectures across multiple jurisdictions. National efficiency mandates and hyperscale data center buildouts are creating divergent adoption timelines.
United States
Hyperscale cloud operators in Northern Virginia and Oregon are retrofitting facilities as server rack densities exceed 50 kW per unit. EPA Section 608 of the Clean Air Act restricts refrigerant emissions from legacy vapor-compression systems. Ashburn-Dulles corridor data centers are consolidating supplier panels to three preferred partners with captive extrusion capabilities.
China
MIIT GB standards for data center PUE enforcement are triggering retrofit mandates across Beijing and Shenzhen server farms. The dual carbon goals framework accelerates liquid cooling substitution in electronics manufacturing zones. Yangtze River Delta and Pearl River Delta clusters concentrate domestic microchannel plate fabrication capacity.
Germany
EU F-Gas Regulation hydrofluorocarbon restrictions are eliminating vapor-compression alternatives in precision electronics manufacturing. Ecodesign requirements mandate progressive refrigerant reduction across industrial cooling applications. Baden-Württemberg and Bavaria host precision diffusion-bonding capacity for aerospace-grade microchannel architectures.
India
Noida and Mumbai hyperscale projects remain underpenetrated for liquid cooling deployment ahead of anticipated BIS thermal efficiency mandates. PLI scheme incentives for electronics manufacturing are expanding addressable demand for thermal management components. Maharashtra and Karnataka industrial corridors are absorbing initial direct-to-chip cooling installations.
Japan
METI energy efficiency guidelines for data centers are pressuring legacy air-cooled facilities in Tokyo and Osaka metro areas. JIS standards for industrial cooling equipment shape procurement specifications for domestic semiconductor fabrication. Kanto and Kansai regions concentrate precision machining expertise for sub-1.0 mm channel geometries.
Liquid Cold Plates Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around backward-integrated metal fabricators and captive coolant system integrators. The vendor base separates into three archetypes: aluminum extrusion specialists with in-house microchannel capacity, copper flat-plate fabricators serving high-performance computing, and full-loop thermal system providers bundling cold plates with pumping infrastructure. Dominant competitive moves include geographic expansion into underpenetrated data center corridors and technology licensing agreements for additive manufacturing of conformal cooling channels.
Among China-based fabricators, Yinlun, FRD, and Sanhua Holding Group occupy positions spanning standard plate volume production through precision microchannel supply. Sanhua Holding Group exemplifies backward integration into precision extrusion and brazing operations. Boyd Corporation represents North American capacity with in-house aluminum microchannel plate production. Trumony anchors specialization in copper flat-plate architectures for high-performance computing clusters.
| Leading Market Players |
|---|
| Yinlun |
| FRD |
| Sanhua Holding Group |
| Trumony |
| IKD |
| Boyd Corporation |
| RETEK |
| CoolIT Systems |
| Winshare Thermal |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion and trans-Pacific container rate volatility are amplifying cost differentials between Chinese microchannel fabricators and North American module assemblers, concentrating pricing power among backward-integrated suppliers with captive extrusion capacity while squeezing margins for distributor-dependent buyers.
Pricing Analysis
Certification level (REACH-compliant coolant chemistry vs. standard propylene glycol formulations) creates the primary spread between premium and standard tiers. Three-tier pricing structure across aerospace-grade copper microchannels, automotive aluminum flat-plates, and industrial standard geometries reflects material conductivity thresholds and machining complexity. Cost compression in the mid-tier standard plate segment is intensifying because Chinese fabricators are absorbing aluminum extrusion capacity expansion. Hyperscale data center operators exhibit the lowest price sensitivity due to thermal performance guarantees, while mid-tier colocation providers remain highly sensitive to upfront capital outlays.
Supply Chain Analysis
Extended payment terms from 60 to 90 days among German precision brazing houses are straining working capital for North American module assemblers sourcing microchannel substrates. Manufacturing gravity centers on China for aluminum extrusion, Germany for diffusion-bonding equipment, and the United States for final system integration. Raw material dependencies encompass London Metal Exchange copper cathodes, primary aluminum billets, and nickel-based brazing alloys. Single-source vulnerability concentrates in Baden-Württemberg precision machining capacity. Distribution runs through direct OEM-engineering relationships that are displacing traditional thermal component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment—specifically multi-jurisdictional certification requirements spanning EPA, REACH, and GB standards—erects 8-14 month qualification barriers that protect incumbent positions.
For Market Incumbents: Insulate margin structures by deepening captive extrusion capabilities in the Yangtze River Delta and securing long-term offtake agreements for aerospace-grade copper. Threat vectors include additive manufacturing entrants collapsing tooling costs for conformal cooling geometries. Certification investment in dual REACH-EPA coolant qualification represents the critical defensive lever.
For New Entrants and Emerging Players: Mid-market colocation operators in India seeking thermal infrastructure-as-a-service represent the most penetrable entry point before BIS efficiency mandates crystallize. Automotive 800V silicon carbide inverter retrofits in European legacy manufacturing facilities offer a secondary white-space target. A leasing-model go-to-market angle collapses upfront capital barriers that previously blocked adoption.
For Investors and Strategic Acquirers: Precision diffusion-bonding specialists with established MIIT GB standard compliance in the Beijing-Shenzhen corridor represent the priority acquisition archetype. Long-term viability rests on regulatory complexity deepening rather than simplifying across the analysis window. The signal to monitor is hyperscale procurement panel consolidation from twelve-plus vendors to three preferred partners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Extrusion | Boyd Corporation's captive aluminum microchannel capacity illustrates margin control across North American deployments. |
| Dual Coolant Chemistry Qualification | Server OEMs with European assembly footprints are hedging REACH substance restrictions through propylene glycol and ionic liquid parallel validation. |
| Additive Manufacturing Licensing | Aerospace prime contractors in Toulouse and Seattle are adopting topology-optimized lattice structures for satellite payload thermal control. |
| Asset-Light Thermal Infrastructure Leasing | Mid-tier colocation operators are accessing liquid cooling without capital expenditure through emerging as-a-service channels. |
| Geographic Expansion into Underpenetrated Data Center Corridors | Noida and Mumbai hyperscale projects offer first-mover positioning before Indian BIS thermal efficiency mandates crystallize. |
Research Methodology
Operator-level perspectives from data center thermal engineering directors, precision metal fabrication plant managers, hyperscale procurement leads, and automotive power electronics specialists anchored the qualitative base. Primary interview findings triangulated against secondary sources including MIIT GB standard filings, EPA Section 608 enforcement data, EU F-Gas Regulation implementation reports, and London Metal Exchange commodity price series. Bottom-up capacity assessments across Baden-Württemberg brazing facilities and Yangtze River Delta extrusion plants converged with top-down demand modeling from hyperscale capex disclosures.
Scenario-bracketing framed the analytical approach across the analysis window, with low-case assumptions incorporating copper price volatility spikes and high-case assumptions reflecting accelerated AI training cluster deployment. Segmentation dimensions encompassed channel geometry, material conductivity tier, end-use vertical, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and greenfield data center buildout pipelines. Industry-specific inputs included GPU heat flux specifications exceeding 500 W/cm² and MIIT PUE enforcement timelines.
Macroeconomic conditions sit as an overlay; deviation in London Metal Exchange copper pricing, trans-Pacific freight rates, or central bank interest rate trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory phase-down schedules and technology substitution curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
Commercial Refrigeration System Market