
 Linear Transfer System Market | 2026-2036
Linear Transfer System Market Size, Share, and Industry Trends Forecast 2026-2036
Linear Transfer System Market Analysis
Asset-light leasing models for modular automation equipment is tilting competitive dynamics toward system integrators with strong balance sheets. Bosch Rexroth leverages its captive supply of linear motion components to control margins across conveyor system deployments. Beckhoff Automation anchors its position through PC-based control architectures that extend software-defined flexibility into transfer car operations. Siemens competes by bundling digital twin capabilities with its electromechanical portfolio, creating integrated value propositions for automotive end users.
A linear transfer system comprises motorized conveyor belts, pallet-based carriers, or rail-guided vehicles engineered to move discrete workpieces between manufacturing stations with positioning accuracy typically below 0.1 millimeter. These systems synchronize with programmable logic controllers and robotic arms to enable continuous-flow assembly, packaging, and sorting operations in high-throughput environments. Conveyor systems dominate installed bases across mature manufacturing economies, while magnetic drive technology represents the fastest-expanding segment due to its elimination of mechanical wear components and compatibility with cleanroom food processing standards. Electromechanical platforms command premium pricing in precision assembly line applications, whereas pneumatic technology retains share in cost-sensitive warehousing material handling deployments.
The EPA enforces energy-efficiency requirements on motorized industrial equipment sold in the United States, directly shaping electromechanical system specifications and testing protocols. ISO 10218 governs robot safety integration with transfer systems internationally, while the EU Machinery Directive mandates CE conformity for linear transfer equipment deployed across European manufacturing units. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional content requirements that could reconfigure supplier qualification criteria for cross-border automation projects.
Market Dynamics
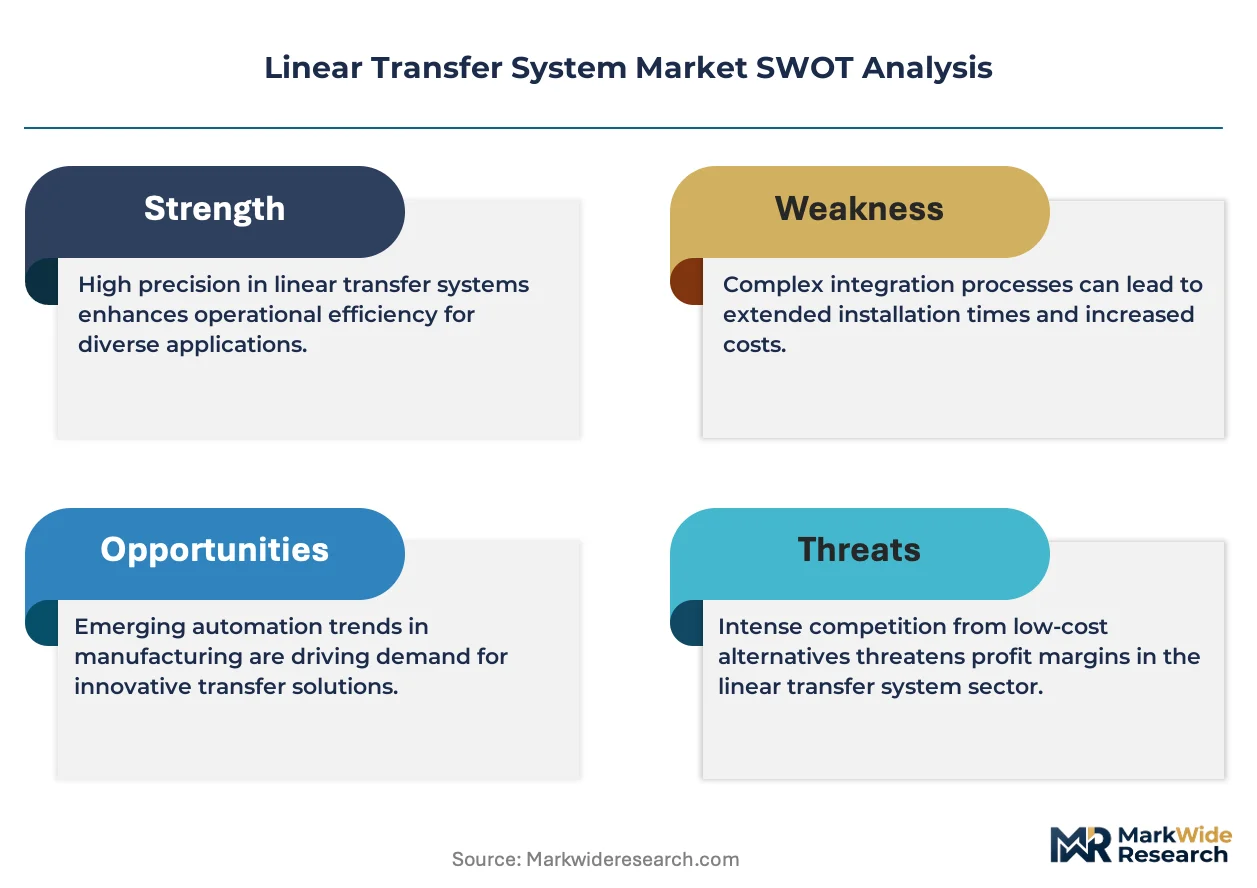
Electromechanical platforms are displacing pneumatic systems across precision assembly lines as manufacturers pursue ISO 10218 compliance and EPA energy-efficiency certifications, compressing upgrade cycles and reshaping supplier qualification criteria.
Growth Catalysts
- Automotive assembly expansion:German and United States plants are retrofitting lines with magnetic drive technologies to satisfy EPA benchmarks and ISO robot safety mandates.
- REACH compliance pressure:European food processors are abandoning pneumatic systems with lubricated components in favor of cleanroom-compatible magnetic drives.
- Precision material handling upgrade wave:Manufacturers across China, Japan, and South Korea are replacing legacy conveyors with electromechanical pallet carriers for sub-0.1 millimeter positioning accuracy.
Market Restraints
- Rare earth magnet supply concentration:Magnetic drive production depends on neodymium processing concentrated in China, exposing buyers to export quota volatility.
- Electromechanical capex premium:Pneumatic systems retain cost advantage in warehousing deployments where positioning tolerance exceeds 0.5 millimeters.
- EU Machinery Directive friction:CE conformity testing for modular transfer systems adds 4-6 month certification timelines that delay project commissioning.
Strategic Opportunities
- India manufacturing acceleration:PLI scheme incentives for electronics assembly are creating first-mover advantage for electromechanical system providers establishing local integration partnerships.
- Battery cell handling applications:Solid-state and lithium-ion production lines require contamination-free magnetic transfer for electrode stacking operations.
- Software-defined control convergence:PC-based architectures merging real-time motion control with digital twin simulation are opening subscription-based service revenue streams.
Industry Challenges
- Mechatronics talent scarcity:System integrators face acute shortages of engineers proficient in both servo motor tuning and PLC programming for synchronized multi-axis transfer.
- Legacy pneumatic infrastructure lock-in:Brownfield automotive plants confront complex retrofit engineering to integrate electromechanical carriers with existing compressed air distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linear Transfer System Market |
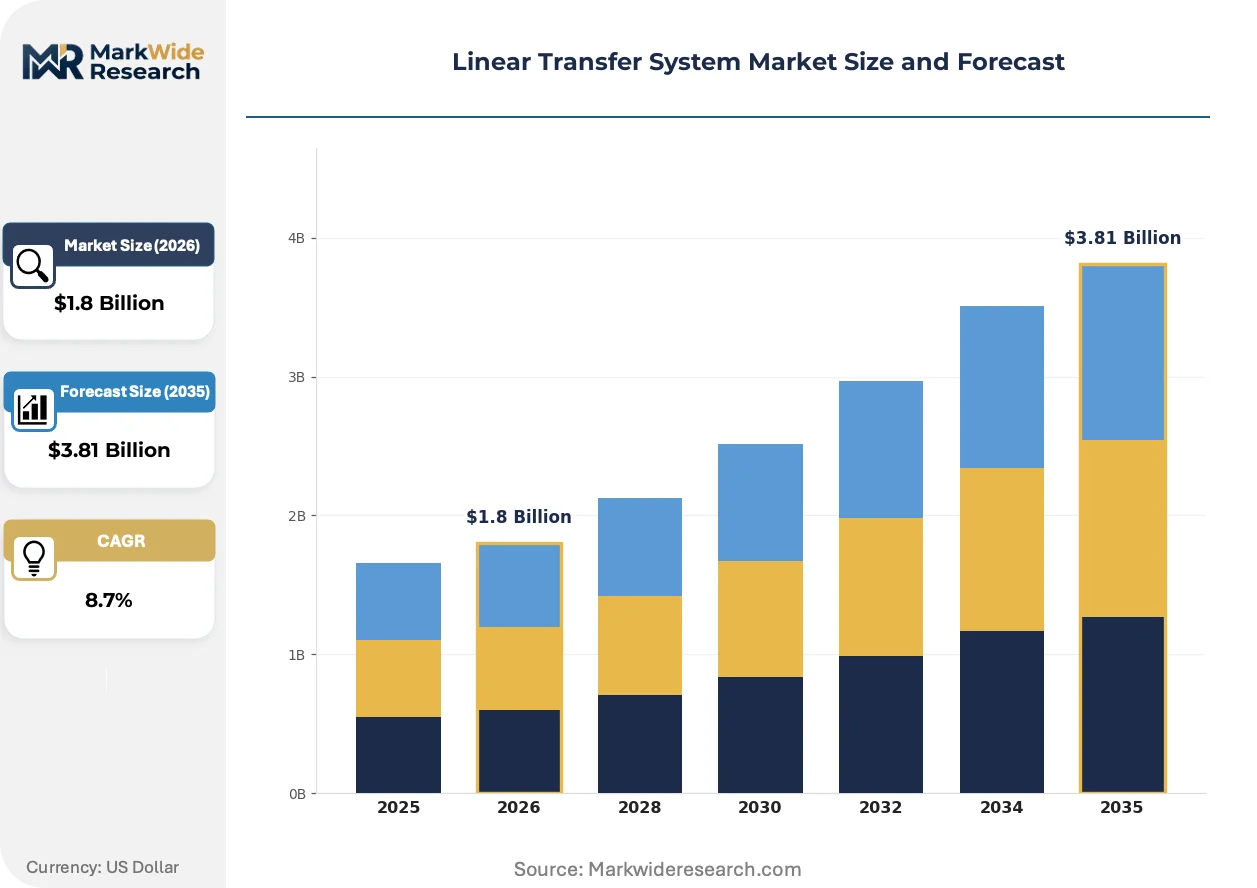
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyor Systems, Transfer Cars, Automated Guided Vehicles, Robotics Technology: Electromechanical, Pneumatic, Hydraulic, Magnetic End User: Manufacturing Units, Warehousing, Automotive Assembly, Food Processing Application: Material Handling, Assembly Line, Packaging, Sorting |
| Companies Covered | Bosch Rexroth, Beckhoff Automation, ATS Automation, Siemens, Rockwell Automation, Festo, ABB, THK Co., Ltd., NSK Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linear Transfer System Market Emerging Trajectories
Digital twin technology is virtualizing commissioning workflows and compressing deployment timelines for complex multi-station transfer systems. Three convergent developments are restructuring how buyers evaluate and deploy linear transfer infrastructure.
Digital twin software is virtualizing electromechanical system commissioning by simulating pallet flow dynamics, collision detection, and cycle time optimization before physical installation. Automotive OEMs in Germany and the United States are mandating virtual factory acceptance testing to reduce line startup risk. This capability is compressing supplier selection criteria toward vendors with integrated simulation platforms rather than standalone hardware offerings.
EPA energy-efficiency testing protocols for motorized industrial equipment are tightening electromechanical motor specifications and driving permanent magnet synchronous motor adoption over induction alternatives. The regulation mandates third-party verification of standby power consumption and regenerative braking efficiency. System integrators serving United States automotive and food processing end-uses are responding by pre-certifying platform configurations to accelerate customer procurement cycles.
Asset-light leasing structures for modular automation equipment are displacing traditional capital purchase models in mid-volume manufacturing segments. Contract manufacturers in Mexico and Eastern Europe are adopting pay-per-output arrangements that transfer obsolescence risk to system integrators with strong balance sheets. This shift concentrates procurement influence among CFOs and operations executives rather than engineering departments alone.
Linear Transfer System Market Segmentation
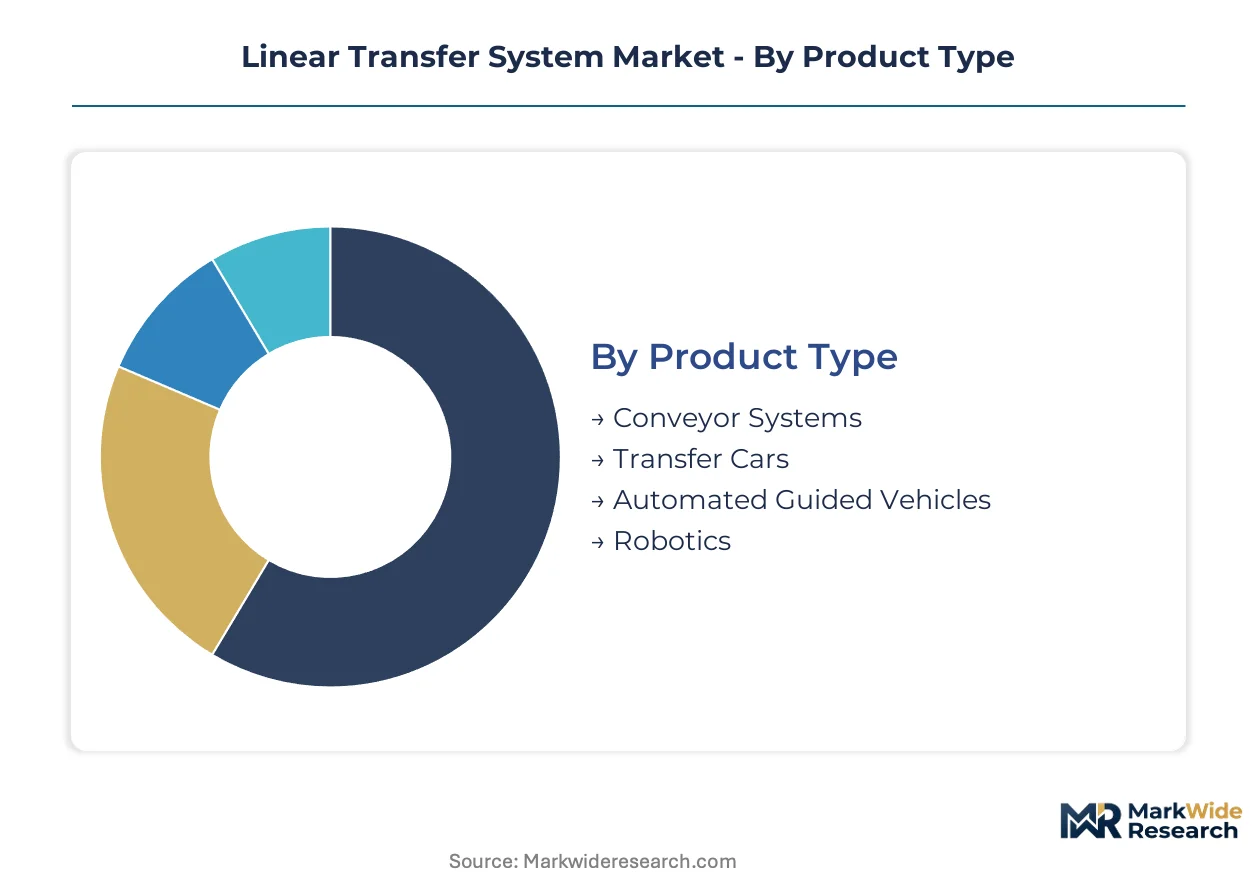
Linear transfer systems fragment across four critical dimensions that determine procurement specifications and supplier selection criteria. Product type and technology choices directly impact positioning accuracy and energy compliance, while end-user verticals and application requirements shape integration complexity and lifecycle economics.
Product Type:
Cost tier determines hardware selection, with premium electromechanical platforms commanding multiples over pneumatic alternatives in precision environments.
- Conveyor Systems:Motorized belt or chain configurations transport discrete workpieces through continuous-flow manufacturing sequences. German and United States automotive assembly plants dominate demand as these facilities retrofit lines to satisfy EPA energy-efficiency benchmarks and ISO 10218 robot safety mandates.
- Transfer Cars:Rail-guided vehicles engineered for station-to-station pallet movement with sub-0.1 millimeter repeatability. Chinese, Japanese, and South Korean manufacturers concentrate upgrade demand here as they replace legacy conveyors with electromechanical carriers for precision material handling applications.
- Automated Guided Vehicles:Self-navigating mobile platforms for flexible routing in dynamic warehouse environments.
- Robotics:Articulated or Cartesian manipulators integrated with transfer infrastructure for pick-place and assembly operations.
Conveyor systems command the established base. The steepest expansion runs through transfer cars.
Technology:
Application requirements dictate drive mechanism selection, with cleanroom food processing and battery cell handling imposing contamination-free constraints.
- Electromechanical:Servo motor and ball-screw configurations delivering programmable positioning with regenerative braking capability. United States automotive and food processing end-uses drive specification tightening as EPA protocols mandate third-party verification of standby power consumption.
- Magnetic:Linear motor drives eliminating mechanical wear components through electromagnetic propulsion. European food processors under REACH compliance pressure abandon pneumatic systems with lubricated components in favor of this cleanroom-compatible architecture.
- Pneumatic:Compressed air actuation retains cost advantage in warehousing deployments where positioning tolerance exceeds 0.5 millimeters.
- Hydraulic:Fluid power systems for heavy-load material handling in industrial forging and metalworking operations.
Pneumatic technology anchors legacy installed capacity. Magnetic drive platforms are climbing the fastest as manufacturers pursue contamination-free handling.
End User:
Customer type determines integration complexity, with automotive OEMs mandating digital twin validation while contract manufacturers prioritize leasing flexibility.
- Automotive Assembly:Multi-station transfer lines synchronizing electromechanical carriers with robotic welding and fastening operations. German plants expand magnetic drive adoption to meet ISO 10218 safety standards and EPA energy-efficiency benchmarks simultaneously.
- Manufacturing Units:Discrete production facilities across electronics, consumer goods, and industrial equipment sectors. India's PLI scheme incentives for electronics assembly create first-mover advantage for electromechanical providers establishing local integration partnerships.
- Warehousing:Distribution centers prioritizing throughput volume over positioning precision in material handling operations.
- Food Processing:Cleanroom environments requiring contamination-free transfer for packaging and sorting sequences.
Manufacturing units represent the broadest installed footprint. Automotive assembly generates the steepest technology upgrade intensity.
Application:
Volume throughput requirements separate continuous-flow assembly from intermittent handling operations, with battery cell production imposing unique contamination constraints.
- Material Handling:Workpiece transport between storage, processing, and shipping zones with variable routing flexibility. Solid-state and lithium-ion production lines require magnetic transfer for electrode stacking operations given strict contamination protocols.
- Assembly Line:Synchronized station-to-station movement with robotic integration for continuous-flow manufacturing. German and United States automotive OEMs mandate virtual factory acceptance testing through digital twin platforms to reduce startup risk.
- Packaging:End-of-line operations integrating transfer systems with case forming, filling, and palletizing equipment.
- Sorting:High-speed diverting and sequencing for distribution and fulfillment operations.
Material handling applications anchor system deployment volume. Assembly line integration delivers the steepest expansion trajectory as digital twin adoption compresses commissioning timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs command premium pricing for precision electromechanical platforms, while Chinese suppliers compete on magnetic drive volume through concentrated rare earth processing. This asymmetry shapes procurement patterns across major manufacturing economies.
United States
Automotive assembly plants in Michigan and South Carolina are retrofitting transfer lines with electromechanical carriers to satisfy EPA energy-efficiency benchmarks and ISO 10218 robot safety mandates. The EPA's third-party verification requirements for standby power consumption are tightening motor specifications nationwide. Detroit-area OEMs now mandate virtual factory acceptance testing through digital twin platforms before commissioning multi-station transfer systems.
Germany
Bavarian and Baden-Württemberg automotive clusters are expanding magnetic drive adoption to meet REACH compliance pressure and EU Machinery Directive CE conformity requirements simultaneously. The EU Machinery Directive's 4-6 month certification timelines are compressing supplier selection toward pre-certified platform providers. Stuttgart-based OEMs are bundling digital twin capabilities with electromechanical portfolio offerings for integrated value propositions.
China
Manufacturers across the Yangtze River Delta and Pearl River Delta are upgrading from pneumatic to magnetic drive technologies for sub-0.1 millimeter positioning accuracy in precision material handling. The country's concentrated neodymium processing creates supply leverage but also exposes buyers to export quota volatility. Shanghai and Shenzhen electronics assembly hubs are driving demand for contamination-free transfer systems under MIIT industrial upgrading directives.
Japan
Precision equipment makers in the Chubu and Kansai regions are replacing legacy conveyors with electromechanical pallet carriers for electronics and automotive component assembly. METI's support for smart factory initiatives is accelerating software-defined control adoption. Nagoya-area automotive suppliers are integrating PC-based architectures with real-time motion control for synchronized multi-axis transfer operations.
India
Electronics manufacturers in Maharashtra and Karnataka are leveraging PLI scheme incentives to establish electromechanical system integration partnerships for smartphone and component assembly. The scheme's production-linked benefits are creating first-mover advantage for providers establishing local technical capabilities. Pune and Bengaluru industrial corridors are emerging as primary deployment zones for modular automation equipment.
Linear Transfer System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying linear motion elements and control architectures. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive component supply, pure-play automation specialists with software-defined control platforms, and precision mechanics fabricators with deep servo motor expertise. Competitive moves concentrate on geographic expansion through local integration partnerships and portfolio diversification into battery cell handling applications.
Among Germany-based diversified industrial groups, Bosch Rexroth and Siemens occupy positions spanning component supply through system integration, while Beckhoff Automation exemplifies the PC-based control specialist archetype. THK Co., Ltd. and NSK Ltd. represent Japanese precision mechanics fabricators with concentrated expertise in linear motion components. These named entities anchor competitive dynamics without constraining the full competitive set.
| Leading Market Players |
|---|
| Bosch Rexroth |
| Beckhoff Automation |
| ATS Automation |
| Siemens |
| Rockwell Automation |
| Festo |
| ABB |
| THK Co., Ltd. |
| NSK Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese magnetic drive component fabrication is compressing margins for electromechanical system integrators while simultaneously accelerating price competition in European and North American precision assembly markets. This utilization dynamic forces suppliers to absorb neodymium magnet cost volatility rather than pass through to automotive OEMs locked into long-term platform contracts.
Pricing Analysis
Configured-to-order electromechanical platforms command 40-60 percent premiums over standard conveyor configurations due to servo motor customization and digital twin integration requirements. Pricing stratifies across premium certified tiers (EPA-verified energy efficiency, ISO 10218 safety compliance), standard modular configurations, and economy pneumatic alternatives for warehousing applications. Cost compression in mid-tier electromechanical systems is intensifying because German automotive OEMs are consolidating supplier panels and demanding bundled software-hardware pricing. Contract manufacturers in Mexico and Eastern Europe exhibit highest price sensitivity due to pay-per-output leasing structures, while German automotive clusters show lowest sensitivity given total cost of ownership calculations spanning decade-long asset lifecycles.
Supply Chain Analysis
Contract manufacturing concentration for linear motion components sits with THK, NSK, and Bosch Rexroth captive fabrication facilities across Japan, Germany, and China. Geographic supply concentration centers on Chinese neodymium processing for magnetic drives, German precision machining for ball-screw assemblies, and Japanese servo motor production. Raw material dependencies draw from rare earth magnet supply, high-grade steel alloys, and semiconductor content for motion controllers. Single-source vulnerability in Chinese neodymium export quotas exposes integrators to forced substitution toward induction motor alternatives. Distribution runs through system integrator direct sales for automotive OEMs and regional distributor networks for mid-volume manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moat characteristics rooted in regulatory entrenchment—ISO 10218 safety certification and EPA energy-efficiency verification create multi-year qualification barriers that protect incumbent positions against unproven challengers.
For Market Incumbents: Pre-empt margin erosion by deepening backward integration into neodymium magnet supply through offtake agreements with Chinese processors, and accelerate pre-certification of platform configurations under EU Machinery Directive timelines to compress competitor sales cycles. Magnetic drive technology substitution from emerging Asian challengers threatens pricing power in precision material handling segments. For New Entrants and Emerging Players: Pursue battery cell handling applications in solid-state and lithium-ion production lines where contamination-free magnetic transfer requirements favor new technology architectures over legacy pneumatic infrastructure. India's PLI scheme electronics assembly corridors represent the most penetrable geography given first-mover gaps in local integration partnerships. A software-defined control go-to-market angle—merging PC-based architectures with subscription simulation services—sidesteps capital-intensive hardware competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular automation leasing segments as pay-per-output models transfer asset ownership risk to balance-sheet-strong integrators. Long-term viability favors platform providers with captive linear motion component supply and digital twin software capabilities. Acquisition target archetypes include precision mechanics fabricators with deep servo motor expertise lacking control architecture integration. Watch for neodymium export quota announcements from Chinese regulators as inflection indicators for magnetic drive cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Virtual factory acceptance testing mandated by Stuttgart OEMs compresses commissioning risk and supplier selection criteria. |
| Backward Integration into Rare Earth Supply | Captive neodymium offtake agreements insulate margins from Chinese export quota volatility in magnetic drive production. |
| Pre-Certification Under EU Machinery Directive | CE conformity acceleration eliminates 4-6 month project delays that disadvantage uncertified competitors. |
| Leasing Model Expansion | Pay-per-output structures in Mexico and Eastern Europe concentrate procurement influence among CFOs over engineering departments. |
| Battery Cell Handling Application Development | Contamination-free magnetic transfer for electrode stacking operations opens high-growth solid-state and lithium-ion production lines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and system integrator technical directors; and secondary validation against customs trade records, SEC filings from listed automation suppliers, EPA energy-efficiency certification databases, and ISO 10218 compliance registries. Bottom-up and top-down triangulation cross-checked segment sizing against installed base estimates and replacement cycle assumptions.
Forecast inputs considered electromechanical versus pneumatic technology substitution rates, REACH compliance pressure timelines in European food processing, and PLI scheme incentive disbursement patterns in Indian electronics assembly. Segmentation modeling spanned product type, drive technology, end-user vertical, and application complexity across the projection horizon. CAGRs were derived from regression analysis of historical capital expenditure patterns correlated with automotive production forecasts and industrial upgrading directives.
Sensitivities concentrate around neodymium export quota revisions, EPA standby power consumption threshold adjustments, and EU Machinery Directive certification timeline changes. Forecasts reflect assumptions regarding technology upgrade cycle compression and regional manufacturing incentive durability. Quarterly review of rare earth magnet pricing indices, automotive OEM platform standardization announcements, and MIIT smart factory directive implementations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Precision Dispensing Accessories Market