
 GCC Crane Market | 2026-2036
GCC Crane Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Crane Market Intelligence
Saudi crane manufacturing capacity is decoupling from traditional European supply chains as domestic assembly investments expand. Liebherr-International AG anchors its Gulf position through regional service hubs and tower crane specialization. XCMG Group competes aggressively on mobile crane cost structures, while SANY Group Co., Ltd. leverages electric-hybrid R&D to differentiate in urban deployment zones. Tadano Ltd. sustains premium positioning through all-terrain crane reliability ratings across UAE project sites.
A crane is a powered lifting machine using wire ropes, sheaves, and boom assemblies to raise and lower loads vertically and move them horizontally, with load capacities ranging from under one ton to over 3,000 tons depending on configuration and counterweight design. Its primary purpose is material handling in construction, port logistics, energy installation, and heavy manufacturing where human or mechanical alternatives cannot safely manage mass or reach. Mobile cranes lead GCC product type demand due to flexibility across dispersed desert and urban sites, while tower cranes dominate high-rise construction in Dubai and Riyadh. Electric and hybrid technology segments are expanding fastest as Saudi Vision 2030 and UAE net-zero policies restrict diesel-only equipment on government-backed developments.
Gulf Standardization Organization (GSO) technical regulations mandate crane safety certification for cross-border trade among member states, while Saudi Standards, Metrology and Quality Organization (SASO) enforces local conformity assessment for imported lifting equipment. The UAE's Ministry of Industry and Advanced Technology coordinates with emirate-level municipalities to align crane operator licensing with federal occupational safety frameworks. Buyers should monitor how Saudi local content requirements and UAE green procurement criteria reshape supplier qualification criteria and fleet replacement cycles.
Market Dynamics
Saudi Arabia's mega-project pipeline is compressing crane procurement cycles as developers demand faster mobilization timelines for gigawatt-scale solar installations and linear city construction. Fleet operators face pressure to align equipment specifications with evolving GSO technical regulations while managing desert terrain logistics.
Growth Catalysts
- SASO conformity mandates:Saudi Standards, Metrology and Quality Organization certification requirements for imported lifting equipment are accelerating fleet replacement among contractors seeking government contract eligibility.
- Hybrid-electric R&D pipelines:UAE net-zero building codes and Dubai Municipality green procurement criteria are pulling electric-hybrid crane configurations into urban high-rise zones.
- Qatar's infrastructure buildout:Stadium-to-logistics conversion projects and port expansion works are sustaining mobile crane utilization rates above regional averages.
Market Restraints
- Steel input volatility:Boom and mast fabrication costs fluctuate with global H-beam and high-tensile plate pricing, compressing OEM margin buffers on fixed-price contracts.
- European component dependency:Hydraulic systems and precision-engineered winch assemblies concentrate supply among German and Italian specialists, exposing GCC assemblers to extended lead times.
- Desert corrosion regimes:Abrasive sand particulate and extreme thermal cycling degrade wire rope and bearing lifespans below temperate-climate engineering assumptions.
Strategic Opportunities
- Kuwait's residential verticalization:Government-funded housing authority projects are underpenetrated relative to Saudi and UAE crane intensity, offering first-mover positioning for mobile fleet operators.
- Rental channel professionalization:Equipment-as-a-service platforms with telematics-enabled utilization tracking are displacing traditional broker-mediated spot markets in Dubai and Riyadh.
- Oman's port-industrial corridor:Duqm Special Economic Zone container terminal and dry dock developments are generating demand for heavy-lift crawler configurations above current regional supply.
Industry Challenges
- Certified operator scarcity:Federal occupational safety frameworks in the UAE and Saudi Arabia require license reciprocity verification that extends project startup timelines.
- Telematics integration complexity:Legacy diesel crane fleets lack CAN bus architecture compatibility with predictive maintenance platforms, forcing costly retrofit programs.
- Cross-border GSO harmonization gaps:Member state interpretation variance in crane safety certification creates documentation friction for fleet redeployment between Saudi Arabia, UAE, and Qatar.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Crane Market |
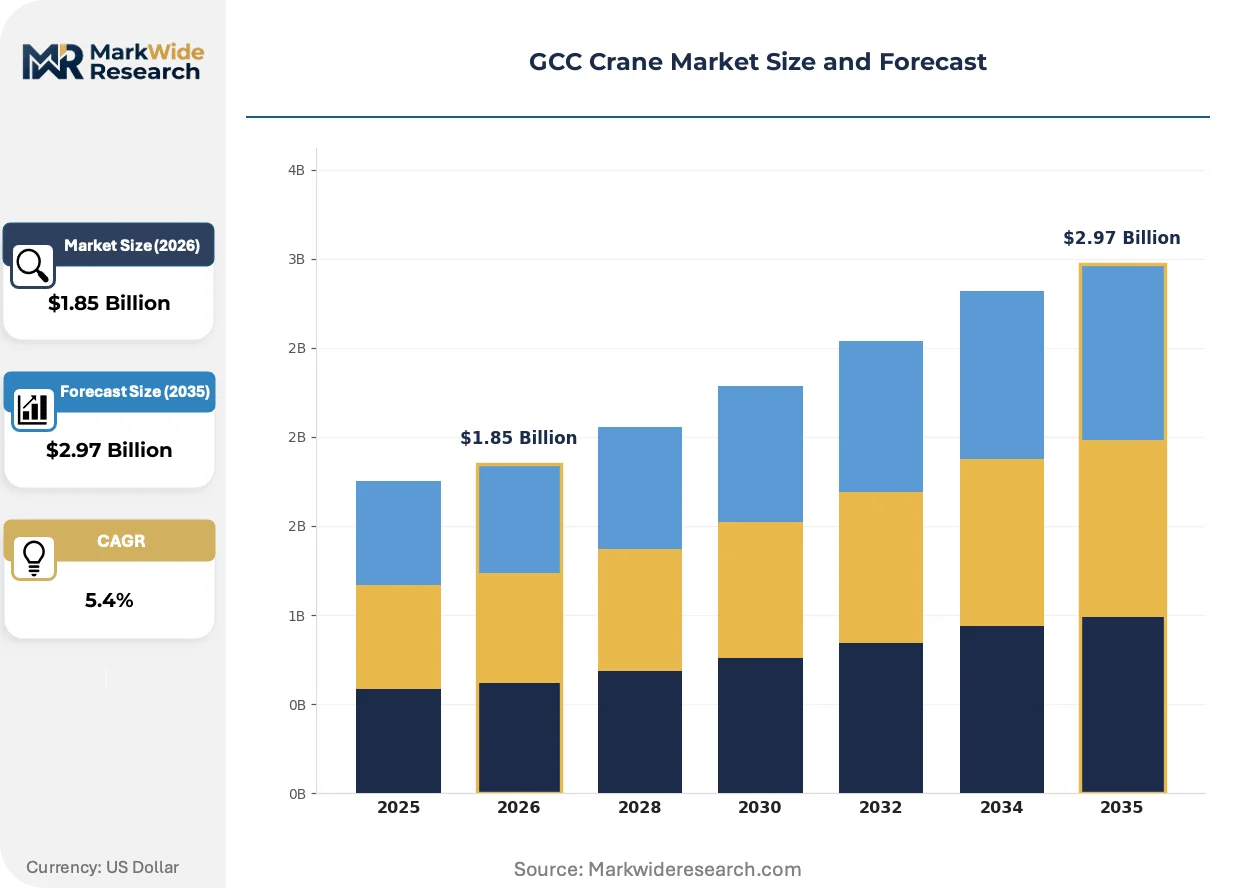
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Crane, Tower Crane, Crawler Crane, Overhead Crane Technology: Hydraulic, Electric, Pneumatic, Hybrid End User: Construction, Shipping, Manufacturing, Energy Deployment: Onshore, Offshore, Urban, Rural |
| Companies Covered | Manitowoc Cranes, LLC, XCMG Group, Liebherr-International AG, Kobelco Construction Machinery Co., Ltd., SANY Group Co., Ltd., Terex Corporation, Zoomlion Heavy Industry Science & Technology Co., Ltd., SENNEBOGEN Maschinenfabrik GmbH, Tadano Ltd., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Crane Market Strategic Shifts & Innovations
Electrification and digitalization are compressing traditional equipment procurement models across the Gulf. Operators now prioritize total cost of ownership metrics over upfront capital expenditure, reshaping supplier relationships and fleet composition strategies.
Lithium-ion battery packs paired with onboard power electronics are consolidating mobile crane propulsion architectures. Saudi Aramco contractors and UAE-based EPC firms are specifying electric-hybrid rough-terrain units for indoor refinery maintenance and urban construction zones. This configuration is consolidating market share from conventional diesel-only alternatives by eliminating exhaust ventilation requirements and reducing fuel logistics overhead.
Gulf Standardization Organization crane safety certification protocols are tightening cross-border equipment mobility. SASO and UAE Ministry of Industry and Advanced Technology alignment efforts are forcing OEMs to harmonize load moment indicator calibration standards and structural inspection intervals. Tower crane deployments in Dubai and Riyadh high-rise zones face the steepest compliance cost adjustments.
Equipment rental platforms with integrated telematics are fragmenting traditional ownership models. Major Saudi contractors now specify utilization-guaranteed contracts with real-time availability dashboards, displacing spot-hire broker networks. This behavioral shift is most visible in Riyadh's King Abdullah Financial District and Jeddah Economic City megaprojects where crane scheduling complexity demands centralized fleet visibility.
GCC Crane Market Segmentation
Crane procurement in the Gulf Cooperation Council follows distinct capital allocation patterns across product configurations, propulsion systems, and deployment environments. Segment selection directly determines financing structures, maintenance protocols, and regulatory compliance burdens for fleet operators.
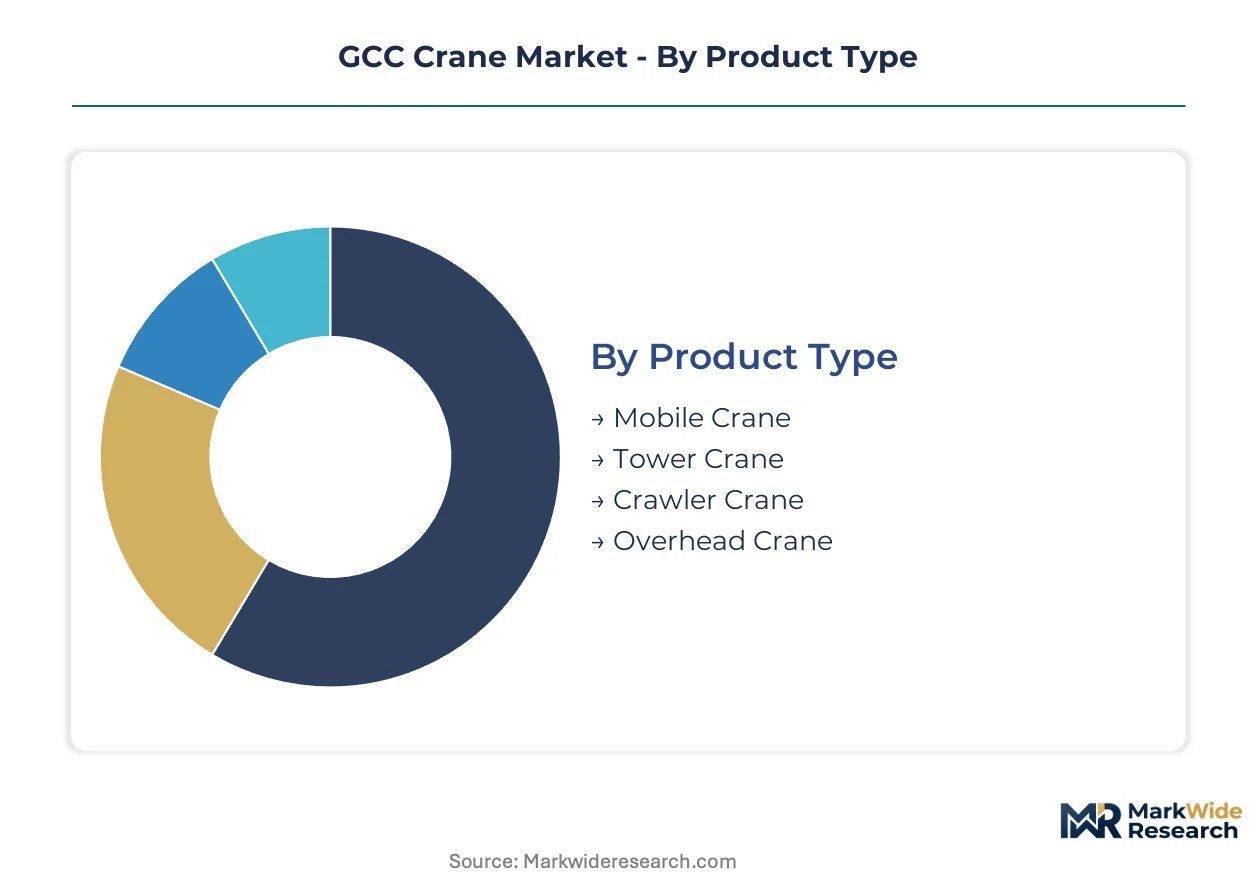
Product Type:
Capital intensity varies sharply across crane architectures, with crawler configurations demanding the highest upfront investment due to specialized transport and assembly requirements.
- Mobile Crane:Truck-mounted and all-terrain variants dominate fleet composition through rapid site-to-site redeployment capability. Saudi Aramco contractors and UAE-based EPC firms prioritize these units for refinery turnarounds and linear city construction where mobilization speed governs project economics.
- Tower Crane:Fixed-base luffing and hammerhead configurations anchor high-rise vertical construction in Dubai's Business Bay and Riyadh's King Abdullah Financial District. Installation requires substantial foundation engineering and climbing sequence planning that extends project startup timelines.
- Crawler Crane:Lattice boom and telescopic crawler units command premium capital deployment for heavy-lift energy infrastructure. Duqm Special Economic Zone port developments in Oman and Qatar's North Field expansion are absorbing crawler capacity above current regional supply.
- Overhead Crane:Bridge and gantry systems serve manufacturing and logistics facilities with fixed-runway installations. Saudi industrial city developments and UAE free zone warehouses are standardizing electric overhead configurations for material handling efficiency.
Most installed capacity flows through mobile crane segments given flexibility demands across dispersed Gulf project sites. Expansion is steepest in crawler crane configurations as gigawatt-scale solar installations and port-industrial corridors multiply heavy-lift requirements.
Technology:
Propulsion system selection increasingly hinges on total cost of ownership calculations rather than acquisition price alone, with fuel logistics and ventilation infrastructure reshaping procurement mathematics.
- Hydraulic:Diesel-hydraulic powertrains retain dominance in rough-terrain and all-terrain mobile fleets through proven torque characteristics and field-serviceability. Desert particulate ingress and thermal cycling stress seal integrity, compressing maintenance intervals below temperate-climate assumptions.
- Electric:Grid-connected and battery-electric configurations are consolidating share in indoor refinery maintenance and urban high-rise zones where exhaust ventilation costs dominate project planning. Saudi Aramco maintenance contractors and Dubai Municipality-governed developments are specifying electric rough-terrain units to eliminate diesel logistics overhead.
- Pneumatic:Compressed-air actuation serves specialized explosive atmosphere applications in petrochemical processing facilities. Limited deployment reflects narrow suitability for standard construction and logistics workflows across Gulf markets.
- Hybrid:Diesel-electric and battery-diesel architectures are bridging operational requirements for intermittent-duty cycles with strict emissions constraints. UAE net-zero building codes and Saudi Vision 2030 procurement criteria are accelerating hybrid specification in government-backed megaprojects.
Hydraulic systems still carry the majority of active fleet hours. Hybrid configurations are climbing the fastest as regulatory thresholds harden across Saudi Arabia and the United Arab Emirates.
End User:
Customer segment concentration reflects the Gulf's project-driven economic structure, with construction and energy commanding disproportionate equipment allocation relative to manufacturing scale.
- Construction:General contracting and specialty trade contractors absorb the dominant share of mobile and tower crane capacity across residential, commercial, and infrastructure verticals. Riyadh and Dubai high-rise corridors drive tower crane intensity, while linear city and gigaproject construction spreads mobile fleet demand across Saudi Arabia's dispersed geography.
- Shipping:Port terminal operators and shipyard facilities require heavy-lift crawler and mobile configurations for container handling and vessel construction. Duqm Port expansion and Qatar's Hamad Port logistics conversion are sustaining above-average utilization rates for maritime-suitable crane specifications.
- Manufacturing:Industrial facility operators deploy overhead crane systems for production line material flow and assembly operations. Saudi industrial city developments and UAE free zone manufacturing clusters are standardizing electric bridge crane installations as production capacity expands.
- Energy:Upstream oilfield services, downstream refinery maintenance, and renewable power installation contractors specify rough-terrain, crawler, and all-terrain configurations for module lifting and equipment positioning. Saudi Aramco's solar and hydrogen project pipelines are redirecting crawler crane demand toward renewable energy construction.
Construction commands the largest installed base by unit count. Energy sector demand is expanding most quickly as the renewable buildout accelerates across Saudi Arabia.
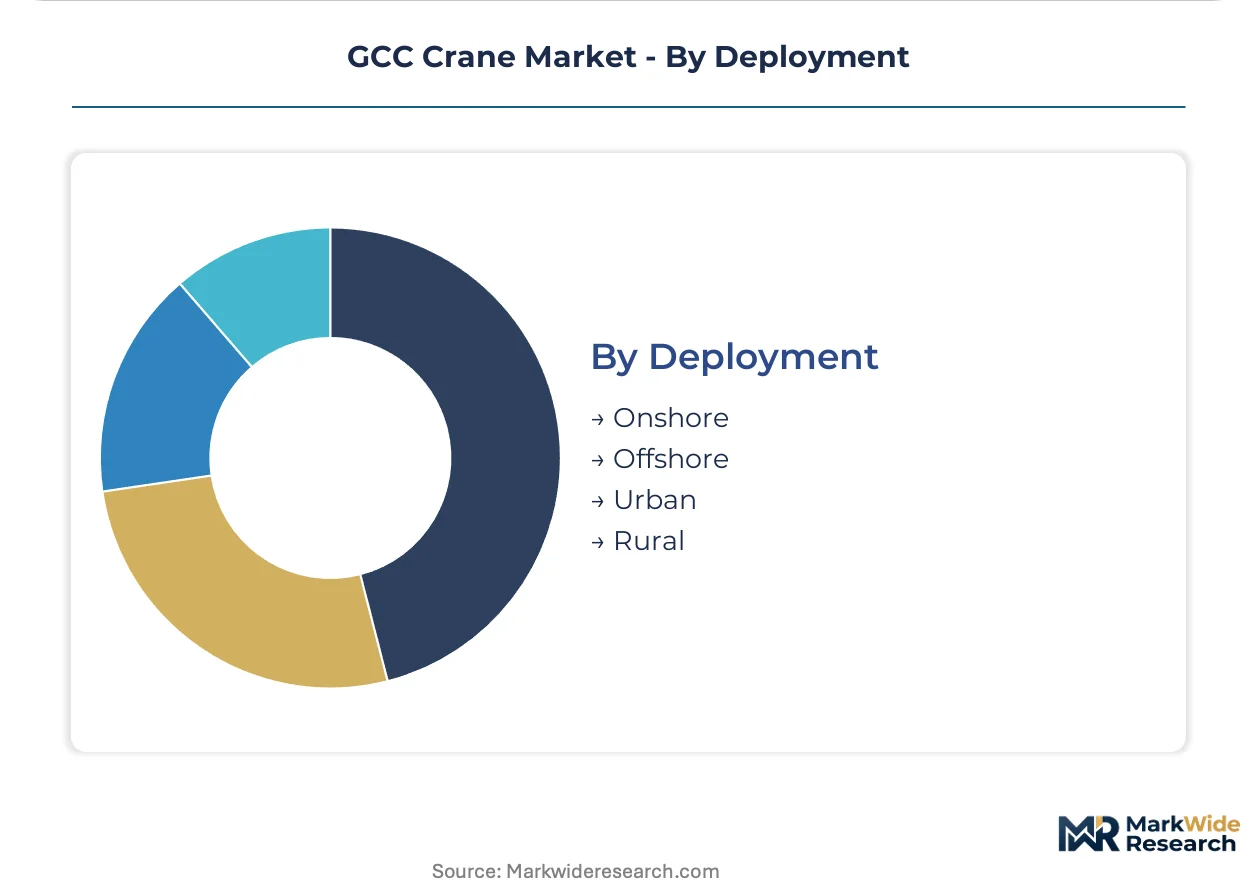
Deployment:
Site classification determines equipment specification, logistics complexity, and regulatory jurisdiction with meaningful cost implications for fleet operators.
- Onshore:Desert terrain and established urban zones encompass the vast majority of Gulf crane operating hours. Abrasive sand particulate and extreme thermal cycling degrade wire rope and bearing lifespans, forcing accelerated replacement schedules relative to temperate-climate engineering assumptions.
- Offshore:Platform supply vessel and jack-up barge-mounted crane operations serve oilfield installation and maintenance in Arabian Gulf waters. Specialized marine certification and dynamic positioning requirements restrict supplier participation to experienced offshore equipment providers.
- Urban:High-density construction zones in Dubai, Riyadh, and Doha impose strict emissions, noise, and safety constraints that favor electric and hybrid configurations. Dubai Municipality green building codes and Saudi municipal regulations are progressively restricting diesel-only equipment from central business district projects.
- Rural:Dispersed infrastructure and energy projects across Saudi Arabia's vast interior and Oman's hinterland demand self-propelled mobile crane autonomy. Fuel logistics and service network gaps elevate total cost of ownership calculations for remote deployment contracts.
Onshore settings absorb the bulk of fleet utilization. Urban deployment is gaining share fastest as vertical construction intensifies in Riyadh and Dubai under stricter environmental regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between Saudi Arabia and the UAE is redirecting crane procurement flows as contractors seek compliance efficiency. SASO certification timelines and Dubai Municipality green building codes create distinct cost-of-compliance profiles. Fleet operators now optimize deployment across Gulf borders based on project eligibility requirements rather than pure logistics proximity.
Saudi Arabia
Gigaproject execution at NEOM and the Red Sea Project is absorbing crawler and mobile crane capacity at unprecedented scale. SASO conformity assessment mandates for imported lifting equipment are accelerating fleet replacement cycles among contractors bidding on government-backed developments. Riyadh's King Abdullah Financial District and Jeddah Economic City concentrate tower crane demand as vertical construction intensifies.
United Arab Emirates
Dubai Municipality net-zero procurement criteria are restricting diesel-only equipment from central business district megaprojects. The Ministry of Industry and Advanced Technology coordinates emirate-level operator licensing with federal occupational safety frameworks. Abu Dhabi's industrial city developments and Dubai's Business Bay corridor anchor hybrid-electric crane specification for high-rise construction zones.
Qatar
Stadium-to-logistics conversion projects following the 2022 FIFA World Cup are sustaining mobile crane utilization above regional averages. The country's central planning authority directs port expansion investments at Hamad Port that demand heavy-lift crawler configurations. Doha's high-density construction zones impose emissions constraints that favor electric-hybrid equipment specifications.
Oman
Duqm Special Economic Zone container terminal and dry dock developments are generating demand for heavy-lift crawler configurations that exceed current regional supply availability. The Special Economic Zone Authority coordinates infrastructure timelines with port-industrial corridor investors. Muscat-based contractors are expanding fleet capacity to capture cross-border deployment opportunities into Saudi Arabia's western region.
Kuwait
Government-funded housing authority projects remain underpenetrated relative to Saudi and UAE crane intensity metrics. The Public Authority for Housing Welfare is accelerating residential verticalization programs that will shift demand toward tower crane configurations. Al Ahmadi and Jahra industrial zones currently absorb overhead crane installations for manufacturing facility material handling.
GCC Crane Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue electrification specialization and telematics-enabled rental platforms. The vendor base stratifies across three distinct tiers: full-line manufacturers with Gulf service infrastructure, regional assemblers leveraging domestic content requirements, and rental-platform operators consolidating spot-hire markets. European-origin and Chinese-origin archetypes dominate equipment supply, while local distributors compete on certification compliance speed. Competitive moves concentrate on strategic partnerships with EPC firms and capacity expansion into Saudi assembly facilities.
Among German-origin full-line specialists, Liebherr-International AG and SENNEBOGEN Maschinenfabrik GmbH exemplify the premium-tier archetype through regional service hub deployment. Chinese-origin manufacturers XCMG Group and SANY Group Co., Ltd. occupy the scale-driven positioning vector. Japanese-origin Tadano Ltd. represents the reliability-focused specialization segment. These three archetypes—European premium service, Chinese cost-scale, Japanese precision-reliability—structure competitive positioning across Saudi Aramco, UAE EPC, and Qatar infrastructure procurement channels.
| Leading Market Players |
|---|
| Manitowoc Cranes, LLC |
| XCMG Group |
| Liebherr-International AG |
| Kobelco Construction Machinery Co., Ltd. |
| SANY Group Co., Ltd. |
| Terex Corporation |
| Zoomlion Heavy Industry Science & Technology Co., Ltd. |
| SENNEBOGEN Maschinenfabrik GmbH |
| Tadano Ltd. |
| Others |
Cost & Logistics Intelligence
Electrification of rough-terrain and crawler crane configurations is compressing cost structures while redrawing supplier power dynamics across the GCC. Lithium-ion battery pack integration and onboard power electronics eliminate exhaust ventilation infrastructure for Saudi Aramco contractors and Dubai Municipality projects, yet concentrate tier-one component sourcing among a narrowing set of qualified cell suppliers and powertrain integrators.
Pricing Analysis
Distributor margin layers in the GCC crane market typically absorb 12-18 percent of landed equipment value before contractor delivery. Three-tier pricing structure across premium European service-backed configurations, mid-market Chinese scale offerings, and economy-tier regional assemblers reflects certification grade and after-sales bundling intensity. Cost compression in mid-market hydraulic mobile units is intensifying because XCMG and SANY are expanding direct regional service presence, bypassing traditional markup structures. Saudi EPC contractors exhibit highest price sensitivity due to local content compliance costs, while UAE-based developers prioritize total cost of ownership metrics over acquisition price alone.
Supply Chain Analysis
Freight costs for crawler crane lattice boom sections and counterweight modules from European assembly plants to Jeddah and Dubai ports have doubled as a share of delivered equipment value since container market volatility began. Manufacturing concentrates in Germany, China, and Japan for precision-engineered winch assemblies and hydraulic systems. Steel input volatility in high-tensile plate and H-beam fabrication, combined with single-source vulnerability for German hydraulic component suppliers, exposes GCC fleet operators to extended lead times. Distribution runs through manufacturer-owned regional hubs in Dammam and Jebel Ali, with certified pre-delivery inspection facilities mandated by SASO and GSO protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC crane market functions as a stable compounder anchored by Saudi Vision 2030 and UAE net-zero infrastructure commitments that guarantee multi-year equipment replacement cycles regardless of hydrocarbon price volatility.
For Market Incumbents: Cement Gulf market position by expanding Saudi-based assembly capacity to satisfy SASO local content requirements for government contract eligibility. Prioritize telematics platform integration to defend against equipment-as-a-service rental platforms that are fragmenting traditional ownership models in Riyadh and Dubai. Vertical integration into lithium-ion battery pack assembly would reduce exposure to single-source cell supplier concentration. For New Entrants and Emerging Players: Digital rental marketplaces with real-time availability dashboards offer the most penetrable route into a market where spot-hire broker networks still mediate significant transaction volume. Target Kuwait's government-funded housing authority projects, which remain underpenetrated relative to Saudi and UAE crane intensity metrics. Lead with hybrid-electric rough-terrain units to differentiate on Dubai Municipality green procurement compliance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with SASO certification capabilities and established EPC contractor relationships rather than manufacturing assets. The five-to-ten year viability window favors consolidation plays in rental platform technology and aftermarket service networks. Monitor Saudi Aramco renewable energy procurement announcements as the inflection signal for crawler crane demand redirection toward solar and hydrogen construction.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Fleet Conversion | Saudi Aramco and Dubai Municipality procurement criteria now restrict diesel-only equipment from megaprojects. |
| Regional Assembly Capacity Expansion | SASO local content mandates accelerate domestic crane assembly investments to maintain government contract eligibility. |
| Telematics-Enabled Rental Platform | Real-time utilization tracking displaces traditional broker-mediated spot markets in Riyadh and Dubai high-rise zones. |
| Certified Operator Training Infrastructure | Federal occupational safety frameworks in Saudi Arabia and UAE extend project timelines due to license reciprocity verification gaps. |
| Aftermarket Service Hub Localization | Liebherr and SENNEBOGEN regional service presence anchors premium-tier positioning against Chinese cost-scale competition. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a grounded demand model for GCC crane procurement. Primary discussions with EPC contract managers, fleet operations directors at Saudi Aramco contractors, Dubai Municipality project engineers, and GSO certification specialists informed equipment specification trends and regulatory compliance burdens. Secondary validation drew from customs trade data for crane imports through Jeddah and Jebel Ali, SASO technical regulation filings, SEC 10-K disclosures from listed OEMs, and project development databases tracking NEOM and Red Sea Project timelines. Bottom-up fleet composition estimates triangulated against top-down construction spend forecasts.
Historical reference periods anchored the projection horizon to observed replacement cycles through Saudi Vision 2030 announcement and Dubai Expo 2020 preparation phases. The analytical framework modeled demand across product type, propulsion technology, end-use sector, and deployment environment dimensions, with particular attention to urban emissions restrictions and desert terrain logistics complexity. CAGRs derived from equipment shipment trajectories and project pipeline visibility rather than macroeconomic extrapolation alone. Key inputs included Saudi Aramco renewable energy construction schedules and UAE Ministry of Industry crane operator licensing harmonization progress.
The model assumes a particular technology adoption path; alternative pathways for battery-electric rough-terrain configurations would alter the outlook if charging infrastructure deployment lags regulatory mandates. Forecasts reflect assumptions about GSO certification harmonization progress and Saudi local content threshold evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Asia-Pacific Hydraulic Equipment Market
Construction Equipment
Concrete Testers Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Piles Turner Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Electric Shovel Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Roadheaders Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Rotomolding Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Rotary Dryers Market