
 Wood Milling Machine Market | 2026-2036
Wood Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Milling Machine Market Analytics
The EU Green Deal is shifting procurement criteria for wood milling equipment across European furniture and construction supply chains. HOMAG Group leverages its integrated software-hardware platforms to anchor automated panel processing workflows for large manufacturers. SCM Group competes through extensive service networks spanning Mediterranean and Central European woodworking hubs. Biesse Group specializes in compact CNC configurations tailored to mid-size cabinet makers upgrading from manual equipment.
A wood milling machine is a powered machining tool that removes material from timber or engineered wood stock using rotary cutters, typically achieving spindle speeds from 3,000 to 24,000 RPM depending on density and finish requirements. Its primary purpose is to shape, groove, profile, or surface-finish wood components for downstream assembly in furniture, construction, and millwork applications. CNC milling machines dominate capital expenditure among industrial buyers due to repeatability and labor substitution, while hybrid machines represent the fastest-growing technology category as smaller shops phase in automation without full replacement of existing manual assets. Panel processing commands the largest application share because flat-pack furniture and modular construction systems require precision dimensioning at volume.
The EU F-Gas Regulation and CE machinery directives shape coolant system designs and operator safety enclosures for equipment sold across Europe. EPA wood dust exposure limits in the United States drive demand for enclosed milling centers with integrated extraction. Japan's METI energy-efficiency labeling program influences spindle motor specifications for machines exported to East Asian markets. Stakeholders should monitor how carbon border adjustments and embodied carbon disclosure rules reshape equipment replacement cycles and supplier qualification criteria.
Market Dynamics
EU Green Deal embodied carbon tracking requirements are compressing equipment replacement cycles as furniture manufacturers retrofit automated panel processing lines to maintain supplier qualification status. This regulatory pressure intersects with labor scarcity in Germany's Black Forest machining cluster, where OEMs and job shops co-locate.
Growth Catalysts
- EU F-Gas Regulation:Coolant system redesign mandates are accelerating demand for enclosed milling centers with integrated extraction, particularly among panel processing facilities seeking CE machinery directive compliance.
- Flat-pack furniture manufacturers:Automated production line expansions to handle custom order volumes are pulling CNC spindle replacements and hybrid machine upgrades.
- Japan's METI energy-efficiency labeling:Spindle motor specification changes for East Asian exports are creating specification upgrade cycles among motor suppliers serving woodworking equipment OEMs.
Market Restraints
- High-alloy steel input volatility:Cutting tool and spindle component costs fluctuate with specialty steel availability, compressing margins for mid-tier equipment suppliers.
- German supplier concentration:Precision ball screw and linear motion component production clusters heavily in Baden-Württemberg, exposing buyers to single-region supply risk.
- Manual equipment substitution:Used and refurbished three-axis machines from decommissioned European furniture plants compete against new compact CNC sales to price-sensitive cabinet shops.
Strategic Opportunities
- Modular construction systems:Cross-laminated timber and mass timber building codes in Austria and Switzerland are opening precision dimensioning demand from construction contractors outside traditional woodworking.
- Retrofit automation kits:Sensor packages and open-architecture CNC controllers allow job shops to phase in automation without full machine replacement, capturing budget-constrained buyers.
- Carbon border adjustment mechanisms:Anticipated embodied carbon tariffs are incentivizing early equipment replacement among exporters to EU markets, front-loading demand for energy-efficient models.
Industry Challenges
- CNC programming and maintenance technician scarcity:Furniture manufacturing regions face pipeline gaps in mechatronics training, extending commissioning timelines and raising service contract costs.
- Legacy pneumatic system integration:Hybrid machine installations often require custom interfacing with existing shop air infrastructure, complicating retrofit project scoping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Milling Machine Market |
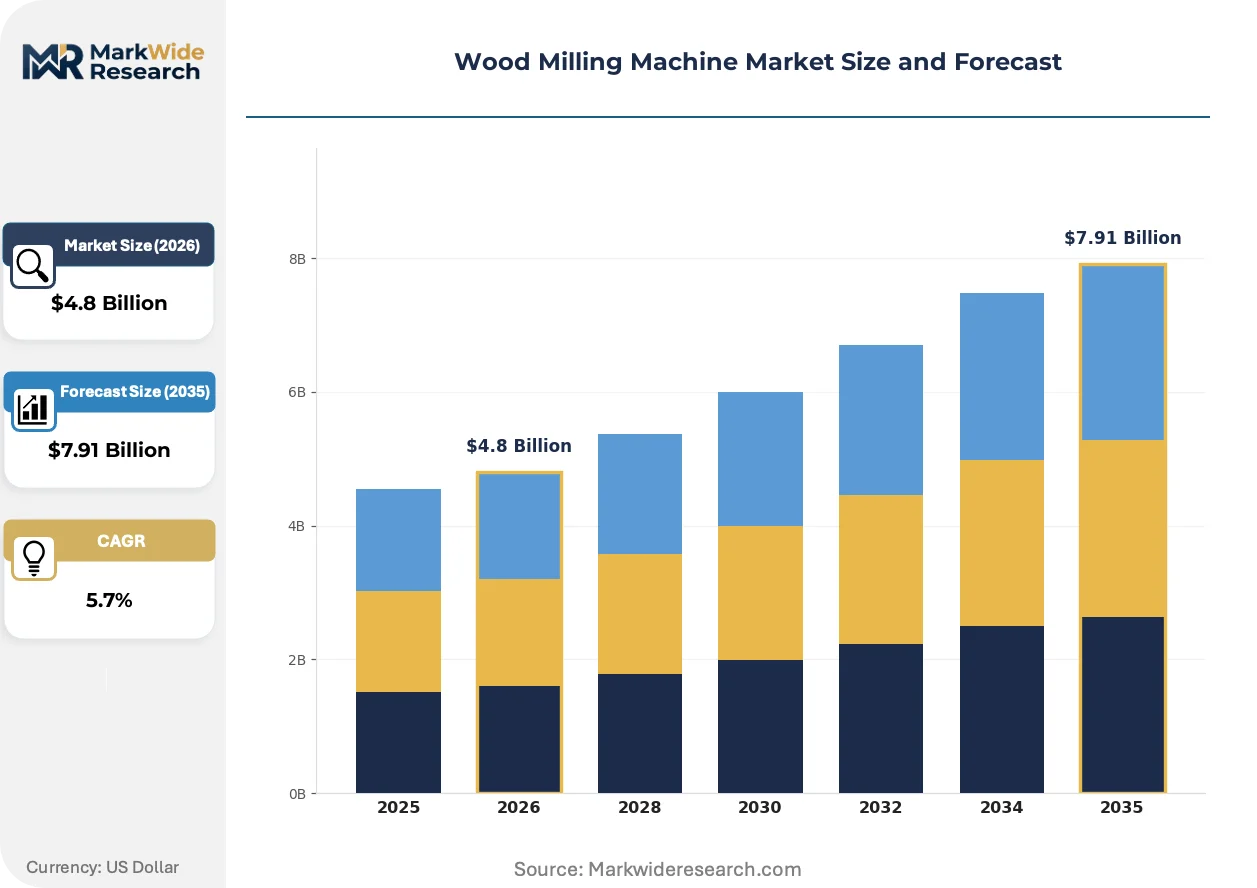
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Milling Machines, Vertical Milling Machines, Horizontal Milling Machines, Planer Mills End User: Furniture Manufacturers, Construction Companies, Woodworking Shops, Cabinet Makers Technology: Automated Systems, Manual Machines, Hybrid Machines, High-Speed Machining Application: Panel Processing, Wood Component Manufacturing, Surface Finishing, Edge Banding |
| Companies Covered | HOMAG Group, SCM Group, Biesse Group, Michael Weinig AG, Holz-Her, IMA Schelling Group, Felder Group, Timesavers, Leadermac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Milling Machine Market Evolving Landscape
Software-hardware integration is displacing standalone machine sales as the dominant commercial model. Vendors now bundle spindle control, toolpath optimization, and production scheduling into subscription-tiered platforms.
Edge-mounted sensor arrays for real-time tool wear monitoring are modularizing maintenance workflows for high-volume panel processors. Mid-size cabinet makers in northern Italy are adopting these systems fastest, compressing unplanned downtime intervals from shift-based to continuous monitoring. This capability is modularizing service contract structures around uptime guarantees rather than scheduled technician visits.
The EU AI Act risk classification framework is reshaping software validation requirements for autonomous toolpath adjustment algorithms. Machine learning-based feed rate optimization now faces conformity assessment procedures previously applied to safety-critical industrial systems. German CNC control developers are responding by segregating AI-enabled features into separately certifiable software modules.
Equipment-as-a-service contracting is displacing outright purchase among capital-constrained job shops. Austrian and Swiss distributors now offer spindle-hour-based billing with bundled maintenance, transferring residual value risk to OEM balance sheets. This model concentrates most visibly in Alpine regions where seasonal order volatility makes fixed capital commitments prohibitive.
Wood Milling Machine Market Segmentation
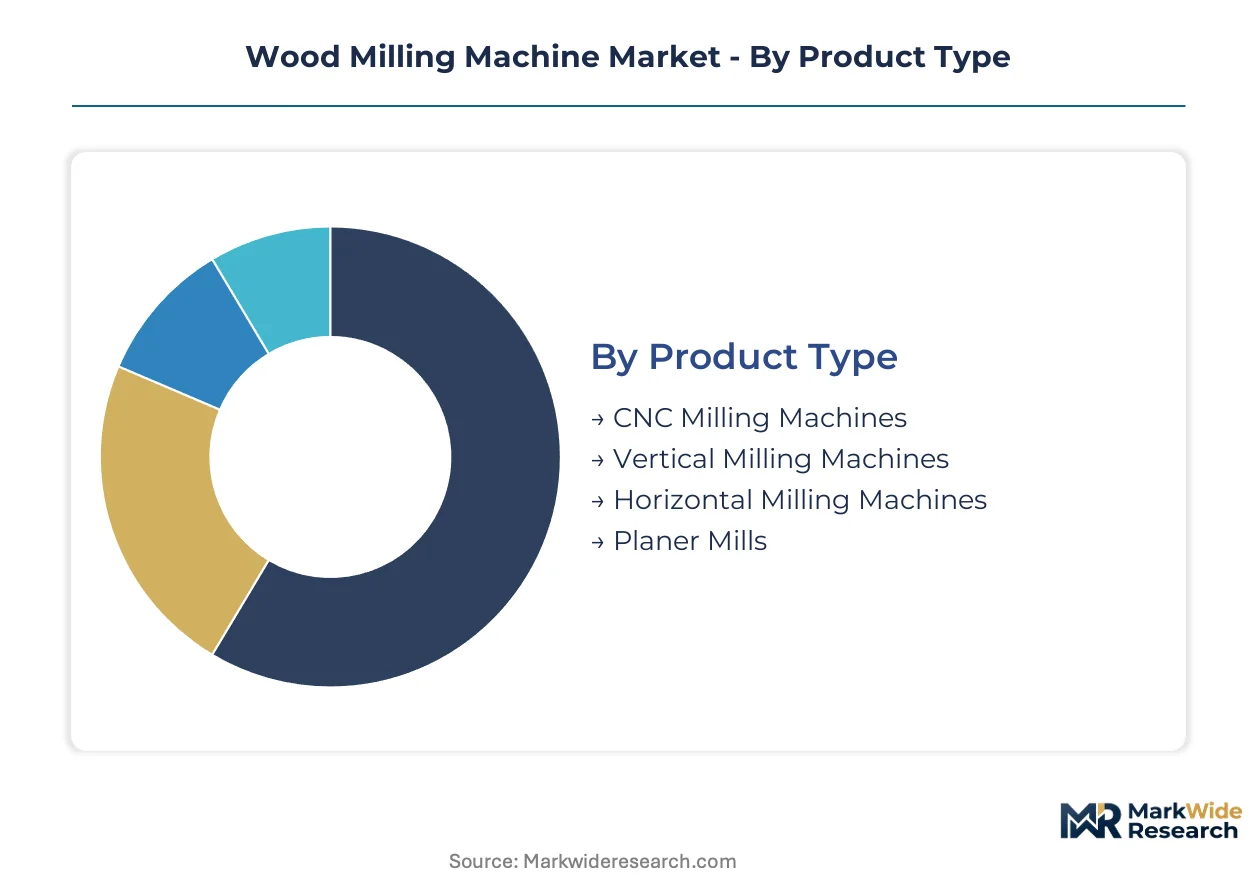
Wood milling equipment segments diverge sharply by automation intensity and capital requirements. Procurement patterns in furniture manufacturing clusters favor integrated systems over standalone units, while construction contractors entering mass timber markets drive specification fragmentation.
Product Type:
Capital-intensity varies by an order of magnitude across this category, with five-axis CNC configurations demanding tenfold the upfront investment of manual planer mills.
- CNC Milling Machines:Computer-numerical control platforms achieve spindle speeds to 24,000 RPM with repeatability tolerances below 0.01mm. German Black Forest OEMs and job shops co-locate around these systems to compress commissioning timelines for flat-pack furniture manufacturers.
- Vertical Milling Machines:Z-axis dominance suits face-milling operations on glued-laminated timber panels. Austrian mass timber contractors specify these for cross-laminated timber dimensioning where horizontal clearances are constrained by existing hall footprints.
- Horizontal Milling Machines:Arbor-mounted cutters excel at heavy stock removal in beam and post processing. Swiss Alpine distributors bundle these with spindle-hour-based service contracts to transfer residual value risk from capital-constrained job shops.
- Planer Mills:Single-purpose surfacing equipment retains niche demand in hardwood lumber mills. Japanese METI energy-efficiency labeling influences motor specifications for machines exported to East Asian markets.
CNC milling machines absorb the bulk of installed capacity; hybrid configurations bridging manual and automated workflows are expanding most quickly.
End User:
Volume concentration tracks the downstream construction and furniture supply chains, with order volatility dictating equipment procurement timing.
- Furniture Manufacturers:Automated panel processing lines handle custom order volumes through software-integrated nesting algorithms. EU Green Deal embodied carbon tracking requirements compress equipment replacement cycles among exporters maintaining supplier qualification status.
- Construction Companies:Mass timber building codes in Austria and Switzerland pull precision dimensioning demand from contractors outside traditional woodworking. CLT and glulam specifications require tolerances previously unseen in rough carpentry.
- Woodworking Shops:Job shops in northern Italy adopt edge-mounted sensor arrays for real-time tool wear monitoring fastest. Modular retrofit kits allow phasing in automation without full machine replacement.
- Cabinet Makers:Mid-size operators upgrade from manual equipment to compact CNC configurations. Used three-axis machines from decommissioned European furniture plants compete aggressively on price.
Furniture manufacturers command the largest share of capital deployment; construction companies are gaining share fastest as mass timber codes proliferate.
Technology:
Margin structures invert across this category, with subscription-tiered software-hardware platforms capturing recurring revenue streams unavailable to manual equipment vendors.
- Automated Systems:Fully integrated lines bundle spindle control, toolpath optimization, and production scheduling. EU AI Act risk classification frameworks now subject machine learning-based feed rate optimization to conformity assessment procedures.
- Manual Machines:Pneumatic clamping and hand-fed tables persist in specialty millwork and restoration. Legacy pneumatic system integration complicates hybrid retrofit scoping for shops with dated infrastructure.
- Hybrid Machines:Open-architecture CNC controllers and sensor packages phase in automation gradually. Equipment-as-a-service contracting concentrates visibly in Alpine regions where seasonal order volatility makes fixed capital commitments prohibitive.
- High-Speed Machining:Spindle speeds exceeding 20,000 RPM demand ceramic or diamond-coated tooling. High-alloy steel input volatility compresses margins for cutting tool suppliers serving this segment.
Automated systems anchor revenue concentration; hybrid machines climb the fastest as budget-constrained buyers defer full replacement.
Application:
Specification depth correlates with downstream assembly complexity, with flat-pack furniture demanding dimensional precision that rough construction tolerances do not require.
- Panel Processing:Nesting software optimizes yield from engineered wood substrates for modular furniture and construction systems. Demand concentrates in Germany's automated production corridors where OEMs and tier-one suppliers co-locate.
- Wood Component Manufacturing:Turned, profiled, and joined parts for windows, doors, and stair systems require multi-axis capability. EPA wood dust exposure limits in the United States drive demand for enclosed milling centers with integrated extraction.
- Surface Finishing:Final pass operations achieve aesthetic grades for visible millwork. CE machinery directive compliance shapes operator safety enclosure designs for equipment sold across Europe.
- Edge Banding:Post-milling tape application integrates with panel processing lines. EU F-Gas Regulation coolant system redesign mandates accelerate demand for enclosed centers with thermal management.
Panel processing holds the dominant installed base; wood component manufacturing shows the steepest expansion trajectory as mass timber construction scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision ball screws and linear motion components that supply equipment builders worldwide, while furniture manufacturers in Italy and construction contractors in Austria absorb the bulk of installed capacity.
Germany
Flat-pack furniture OEMs in Baden-Württemberg drive demand for five-axis CNC configurations with repeatability tolerances below 0.01mm. The EU F-Gas Regulation mandates coolant system redesigns for CE machinery directive compliance. The Black Forest machining cluster concentrates OEMs and job shops to compress commissioning timelines for automated panel processing lines.
Italy
Mid-size cabinet makers in Lombardy and Veneto upgrade from manual equipment to compact CNC configurations. The EU AI Act risk classification framework subjects machine learning-based feed rate optimization to conformity assessment procedures. Northern Italian woodworking shops adopt edge-mounted sensor arrays for real-time tool wear monitoring faster than other European regions.
Austria
Mass timber contractors specify vertical milling machines for cross-laminated timber dimensioning where horizontal clearances are constrained. The country's national building codes for CLT and glulam require tolerances previously unseen in rough carpentry. Alpine distributors bundle horizontal milling equipment with spindle-hour-based service contracts to transfer residual value risk from capital-constrained job shops.
Switzerland
Construction contractors outside traditional woodworking pull precision dimensioning demand as mass timber building codes proliferate. Swissmedic-equivalent machinery safety standards shape operator enclosure designs for equipment sold domestically. Equipment-as-a-service contracting concentrates visibly in Alpine regions where seasonal order volatility makes fixed capital commitments prohibitive.
United States
Enclosed milling centers with integrated extraction gain share as EPA wood dust exposure limits tighten. OSHA machinery guarding requirements intersect with state-level building code adoptions for mass timber construction. The Pacific Northwest timber processing corridor sees specification fragmentation as construction contractors enter precision dimensioning markets.
Wood Milling Machine Market Competitive Landscape
The competitive structure tilts toward integrated software-hardware platforms over standalone machine sales. German and Italian equipment builders anchor the premium tier through bundled production scheduling and toolpath optimization systems. Mid-tier specialists compete on retrofit automation kits and sensor packages for budget-constrained job shops. Dominant competitive moves include strategic partnerships between control software developers and spindle motor suppliers, plus geographic expansion through distributor-owned service networks in Alpine and Nordic regions.
Among German-based platform builders, HOMAG Group and SCM Group exemplify the integrated-systems archetype through subscription-tiered software-hardware bundles. Biesse Group, an Italian specialist, occupies a position within the compact CNC segment serving mid-size cabinet makers upgrading from manual equipment. These three represent divergent strategic postures: platform breadth versus application-focused configuration flexibility.
| Leading Market Players |
|---|
| HOMAG Group |
| SCM Group |
| Biesse Group |
| Michael Weinig AG |
| Holz-Her |
| IMA Schelling Group |
| Felder Group |
| Timesavers |
| Leadermac |
| Others |
Value Network & Pricing Analysis
Specialty steel price indices cascade through spindle and cutting tool tiers, compressing margins at the mid-market level while premium German OEMs absorb volatility through captive forging capacity and long-term alloy contracts. This input-cost architecture stratifies equipment pricing across three performance tiers, with carbon border adjustment exposure now filtering into contract terms for exporters serving EU markets.
Pricing Analysis
Spindle-hour-based service contracting anchors value-based pricing for capital-constrained Alpine job shops, transferring residual value risk to OEM balance sheets. Three-tier pricing structure across premium, standard, and economy levels separates fully integrated five-axis platforms from compact CNC upgrades and refurbished manual equipment. Cost compression in the standard tier is intensifying because used three-axis machines from decommissioned European furniture plants flood secondary markets. Cabinet makers upgrading from manual equipment exhibit highest price sensitivity; mass timber contractors specifying vertical milling machines for CLT dimensioning show lowest sensitivity due to code-mandated precision requirements.
Supply Chain Analysis
Precision ball screw and linear motion component supply rests on Baden-Württemberg production clusters, with secondary sourcing from Swiss and Japanese specialty manufacturers. High-alloy steel for cutting tools, ceramic spindle bearings, and energy-efficient motor laminations constitute critical input dependencies. Single-region concentration in Germany exposes buyers to geographic supply risk amplified by EU F-Gas Regulation compliance timelines. Distribution runs through distributor-owned service networks in Alpine and Nordic regions, with direct OEM relationships dominating large furniture manufacturer accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty steel forging capacity constraints prop pricing power for vertically integrated German OEMs, while mid-tier suppliers face margin compression from alloy input volatility and refurbished equipment competition.
For Market Incumbents: Extend software-hardware platform bundling to capture recurring revenue streams from subscription-tiered production scheduling and toolpath optimization systems. Backward integration into precision ball screw production mitigates Baden-Württemberg supply concentration risk. Invest in open-architecture CNC controller certification to preempt EU AI Act conformity assessment bottlenecks for machine learning-enabled feed rate optimization. For New Entrants and Emerging Players: The price-point gap between premium five-axis CNC configurations and economy-tier refurbished three-axis machines creates entry space for modular retrofit automation kits. Target northern Italian woodworking shops adopting edge-mounted sensor arrays for real-time tool wear monitoring, where phasing in automation without full machine replacement addresses budget constraints. Lead with equipment-as-a-service contracting to transfer residual value risk from seasonally volatile Alpine job shops. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier compact CNC specialists with established distributor networks in Austria and Switzerland. Long-term viability hinges on software validation capabilities for EU AI Act compliance and carbon border adjustment readiness. Watch for embodied carbon disclosure rule enforcement as the inflection trigger accelerating equipment replacement cycles among EU-exporting furniture manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Components | Captive ball screw production in Baden-Württemberg insulates margins from alloy volatility. |
| Equipment-as-a-Service Launch | Spindle-hour billing transfers residual value risk from Alpine job shops with seasonal volatility. |
| EU AI Act Software Certification | Segregated AI-enabled modules preempt conformity assessment delays for feed rate optimization. |
| Retrofit Automation Kit Development | Sensor packages and open-architecture controllers capture budget-constrained cabinet maker demand. |
| Carbon Border Adjustment Readiness Program | Energy-efficient model portfolios position exporters for anticipated embodied carbon tariffs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers at furniture manufacturers, procurement leads at mass timber contractors, aftermarket service heads at distributor networks, and technical directors at CNC control developers. VDMI production statistics, EU ETS emissions disclosures, CE machinery directive conformity databases, and Japanese METI energy-efficiency labeling registries provided quantitative foundations. Bottom-up equipment shipment analysis and top-down construction and furniture sector capex triangulation validated market sizing.
Segment-level modeling deployed product type, end user, technology, and application dimensions across the projection horizon, with automation intensity and capital requirements as cross-cutting variables. CAGRs derived from regression against macroeconomic indicators and sector-specific demand drivers including EU Green Deal embodied carbon tracking implementation, mass timber building code adoptions in Austria and Switzerland, and METI labeling program expansion timelines. Spindle speed specifications, repeatability tolerances, and software-hardware integration penetration served as industry-specific forecast inputs.
Inputs from OEM production disclosures and distributor shipment reports were available through the study window; gaps in real-time order book visibility from private job shops introduce uncertainty bands around near-term demand inflection points. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and alloy price trajectory stability. Supply chain disruption from German supplier concentration, technician training pipeline gaps, and carbon border adjustment mechanism implementation pace warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Track Loader Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Global Skid Steer Attachments Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Part Feeder Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Suction Excavator Market
Construction Equipment
Heavy Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Mini Cranes Market
Construction Equipment
India Construction Equipment Market