
 Organic Pesticides Market | 2026-2036
Organic Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Pesticides Market Intelligence
Production capacity for microbial-based bio-pesticides in Europe is expanding to meet stricter agricultural standards. Large-scale producers like BASF leverage extensive R&D infrastructure to develop novel formulations. Niche specialists such as Koppert differentiate through integrated pest management solutions for controlled environment agriculture. Meanwhile, Corteva Agriscience positions its biologicals portfolio to complement its conventional crop protection offerings.
Organic pesticides are crop protection agents derived from natural sources, including microorganisms, plant extracts, and minerals. Their mechanisms of action are highly specific, often targeting a narrow range of pests without harming beneficial insects. Bio-insecticides and bio-fungicides represent the dominant product types by revenue. Application in high-value fruit orchards and vegetable gardens continues to drive volume, especially for growers targeting premium consumer markets.
Regulatory frameworks such as the USDA's National Organic Program and the EU's stringent approval process for plant protection products are pivotal. These standards, along with Japan's JAS certification, dictate which active ingredients are permissible for organic use. Successfully aligning product development with this evolving and fragmented global regulatory landscape is essential for market participants.
Market Dynamics
Regulatory pressure for sustainable agriculture, particularly from frameworks like the European Union's Green Deal, is the central force shaping the organic pesticides market. This creates a powerful, non-cyclical demand pull for non-synthetic crop protection agents across high-value agricultural sectors.
Growth Catalysts
- Consumer Demand for Organic Foods:Heightened consumer preference for produce free from synthetic chemical residues directly stimulates demand from growers targeting premium retail channels, especially in North America and Europe.
- Regulatory Mandates:The EU's Farm to Fork strategy, which sets targets for reducing conventional pesticide use, acts as a significant catalyst, compelling growers to adopt biological alternatives to maintain market access.
- Advancements in Microbial Science:Innovations in fermentation and formulation technologies are improving the efficacy, stability, and shelf-life of microbial-based pesticides, making them more competitive against synthetic counterparts for a wider range of applications.
Market Restraints
- Higher Input Costs:Organic pesticides often have a higher per-acre treatment cost compared to conventional synthetic chemicals, creating a barrier for adoption in price-sensitive, large-scale commodity crop cultivation.
- Performance Variability:The efficacy of many biological agents is highly dependent on environmental conditions such as temperature and humidity, leading to inconsistent field performance compared to broad-spectrum synthetic products.
- Fragmented Regulatory Approvals:Navigating the disparate and lengthy approval processes of bodies like the USDA, the EU's EFSA, and Japan's authorities creates significant compliance burdens and delays market entry.
Strategic Opportunities
- Expansion into Broad-Acre Crops:Developing cost-effective and stable formulations for commodity crops like corn, soy, and wheat represents a substantial untapped market beyond the current focus on horticulture.
- Latin American Market Penetration:Brazil and Argentina, with their vast agricultural sectors and growing export focus on sustainability, offer significant expansion potential for biopesticide manufacturers.
- Climate-Adaptive Formulations:There is an emerging opportunity to develop biopesticides specifically designed to protect crops against pests and diseases that are becoming more prevalent due to climate change-induced stress.
Industry Challenges
- Production Scalability:Consistently manufacturing live microbial-based products at an industrial scale while maintaining quality and viability presents significant technical and logistical hurdles for producers.
- Farmer Education and Training:Effective use of biologicals requires a deeper understanding of pest life cycles and application timing, creating a need for extensive training and support for growers transitioning from synthetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Pesticides Market |
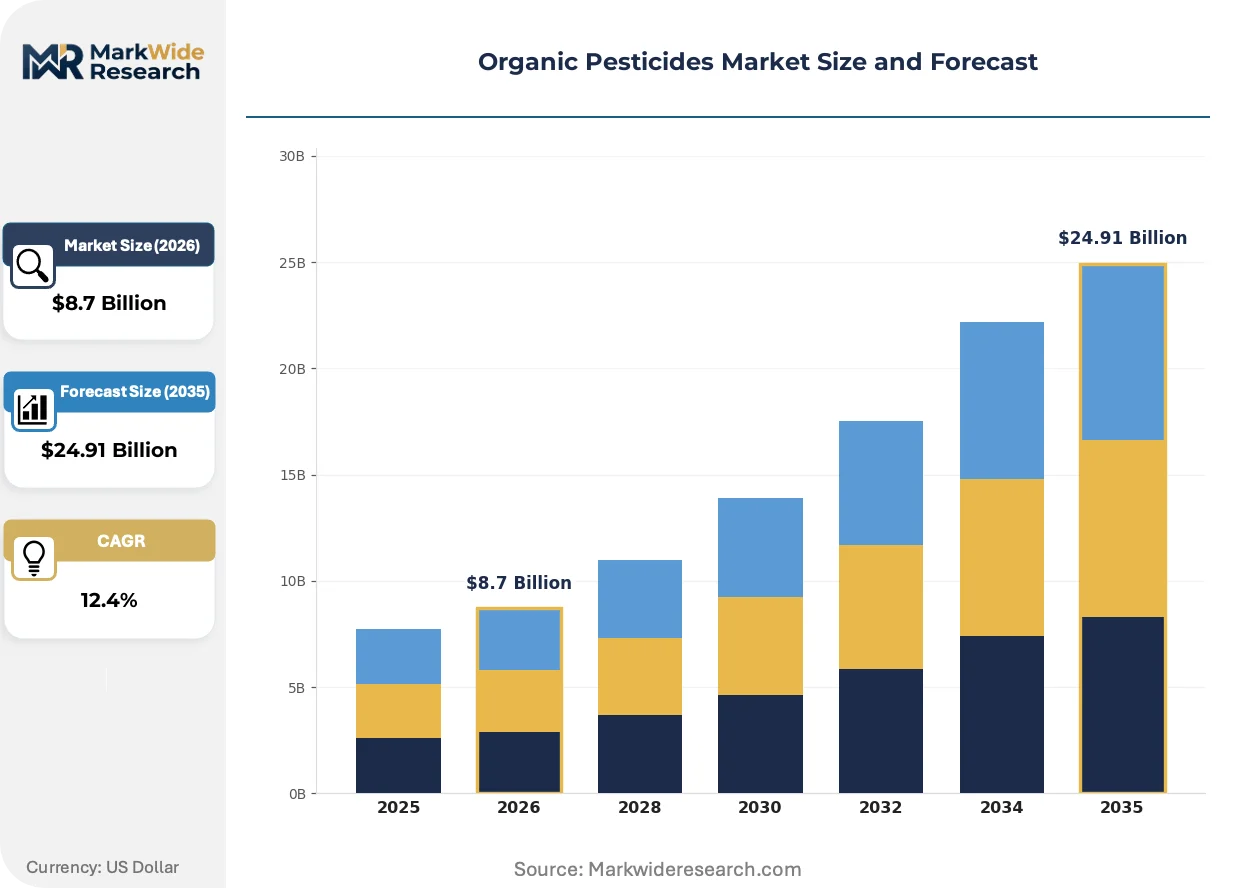
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-insecticides, Bio-fungicides, Bio-herbicides, Bio-nematicides, Plant Extracts Application: Cereal Crops, Vegetable Gardens, Fruit Orchards, Plantation Crops, Turf Management Formulation: Liquid Concentrates, Wettable Powders, Granules, Emulsifiable Concentrates, Dusts Customer Type: Smallholder Farmers, Agribusinesses, Horticulturists, Landscape Contractors, Organic Growers |
| Companies Covered | Marrone Bio Innovations, Koppert, BASF, Nufarm, Valent BioSciences, Syngenta, Certis Biologicals, Corteva Agriscience, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Pesticides Market Strategic Shifts & Innovations
Product innovation is shifting from simple substitution of synthetic chemicals to the development of highly targeted, mode-of-action-specific biologicals. This evolution is driven by advancements in biotechnology and a deeper understanding of pest and pathogen biology, enabling more precise interventions.
RNA interference (RNAi) technology provides a novel mechanism for ultra-specific pest management by silencing essential genes. Its adoption is accelerating within controlled environment agriculture and for high-value specialty crops where precision is paramount. This development is electrifying the research pipeline, promising a new generation of biopesticides that are non-toxic to non-target organisms, including beneficial insects and pollinators.
The European Union's stringent approval process for plant protection products is a primary regulatory driver. It actively filters out older, less safe chemical active ingredients, which creates a direct market void that new biological solutions are positioned to fill. Fruit and vegetable growers in Germany, France, and Spain are most impacted, rapidly integrating bio-fungicides and bio-insecticides into their crop management programs.
Agricultural purchasing behavior is moving away from single-product buys toward integrated solution packages. This trend disrupts commodity distribution models and favors suppliers who can bundle diagnostic tools, beneficial insects, and tailored biopesticide regimens. The shift is most pronounced in the high-tech greenhouse horticulture sector, particularly for vegetable and ornamental production in the Netherlands.
Organic Pesticides Market Segmentation
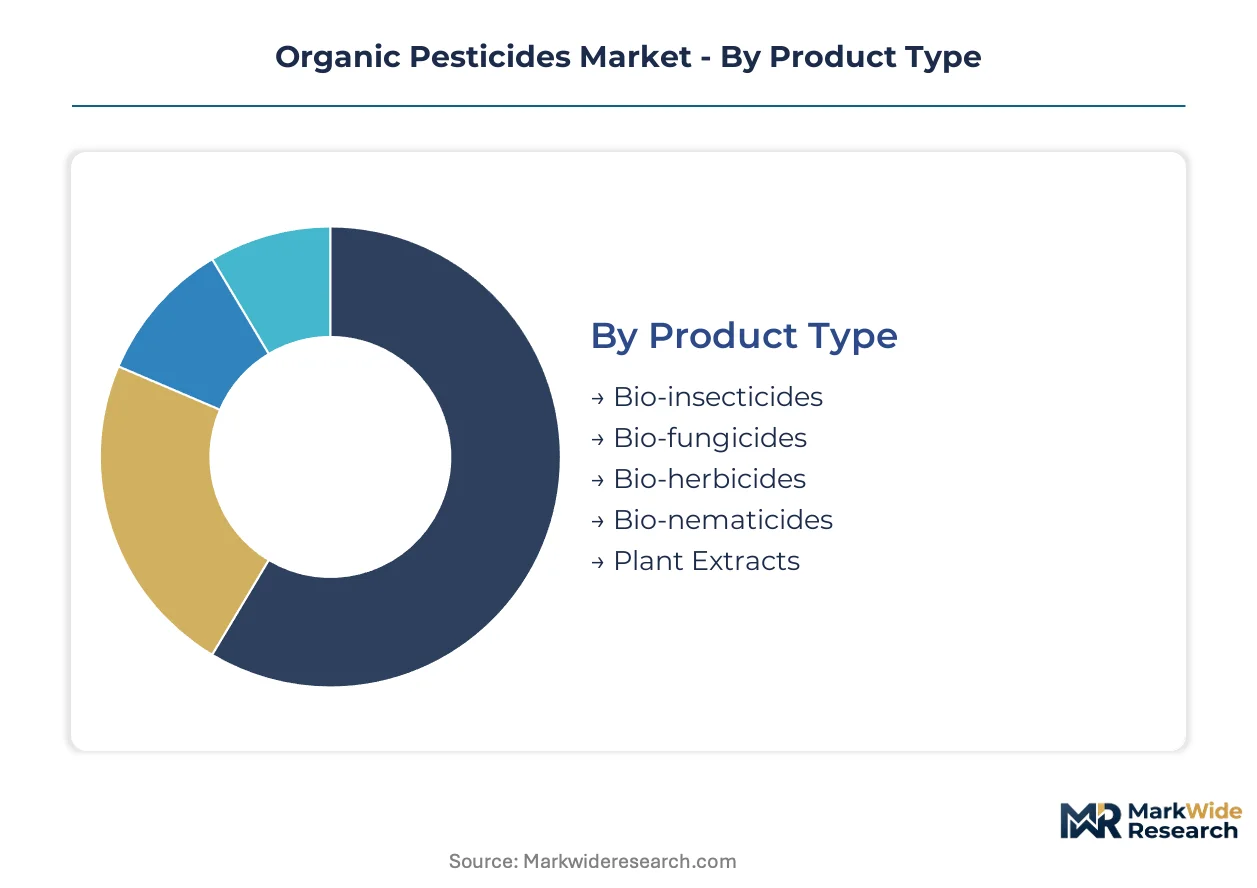
The segmentation analysis illuminates the nuanced demand patterns and supply-side capabilities within the organic pesticides market. Understanding these distinct segments is crucial for market participants to align product development with specific grower needs and regulatory requirements. This granular view enables strategic resource allocation and targeted market entry.
Product Type:
The product type segmentation reveals a clear split between high-volume foundational solutions and premium, highly specialized biological agents.
- Bio-insecticides:These biological agents specifically target insect pests through various mechanisms, including microbial toxins or growth disruption. Demand concentrates in high-value fruit orchards and vegetable gardens, driven by the need for residue-free produce for premium consumer markets.
- Bio-fungicides:These products control fungal diseases using beneficial microorganisms or natural compounds, often preventing spore germination or inhibiting pathogen growth. Application in European fruit and vegetable sectors is significant, compelling growers to adopt alternatives to synthetic chemicals due to stringent EU regulations.
- Bio-herbicides:Derived from natural sources like fungi or bacteria, these products suppress weed growth.
- Bio-nematicides:These biologicals manage nematode populations in soil, protecting plant roots from damage.
- Plant Extracts:Naturally occurring compounds from botanical sources offer pest deterrent properties for various crops.
Mature deployment sits with Bio-insecticides. Newer deployment is concentrated in Bio-herbicides.
Application:
This category highlights the diverse end-use environments where organic pesticides are deployed, ranging from large-scale agriculture to specialized horticulture.
- Fruit Orchards:Organic pesticides protect high-value fruit crops like apples, grapes, and citrus from various pests and diseases. European and North American growers increasingly use these solutions to meet organic certification standards and consumer demand for premium, residue-free produce.
- Vegetable Gardens:These applications involve protecting a wide array of vegetables in both commercial and home garden settings. Demand is particularly high in regions with strong consumer preference for locally grown and organic vegetables, driven by food safety concerns.
- Cereal Crops:Large-scale cultivation of grains like wheat and corn presents a vast potential market for cost-effective organic solutions.
- Plantation Crops:Coffee, tea, and oil palm plantations utilize organic pesticides for sustainable pest management practices.
- Turf Management:Professional and residential turf areas employ biologicals for disease and pest control, particularly in golf courses.
Expansion potential is highest in Cereal Crops. Market penetration is currently strongest in Fruit Orchards.
Formulation:
The formulation segment defines the physical forms in which organic pesticides are delivered, impacting their stability, shelf-life, and application methods.
- Liquid Concentrates:These formulations offer ease of mixing and application, typically requiring dilution before spraying. Advancements in fermentation and stabilization technologies are improving the shelf-life and efficacy of microbial-based liquid concentrates, making them more competitive.
- Wettable Powders:Comprising active ingredients mixed with inert carriers, these powders disperse in water to form a suspension for spraying. Their solid nature often provides better stability for microbial agents, reducing degradation during storage and transport.
- Granules:These solid, granular forms are often used for soil application or slow-release pest control.
- Emulsifiable Concentrates:Active ingredients are dissolved in solvents and emulsifiers, forming an emulsion when mixed with water.
- Dusts:Fine powder formulations applied directly to plants or soil, often used for specific pest control scenarios.
Shelf-life considerations are critical for Wettable Powders. Efficacy optimization is a primary driver for Liquid Concentrates.
Customer Type:
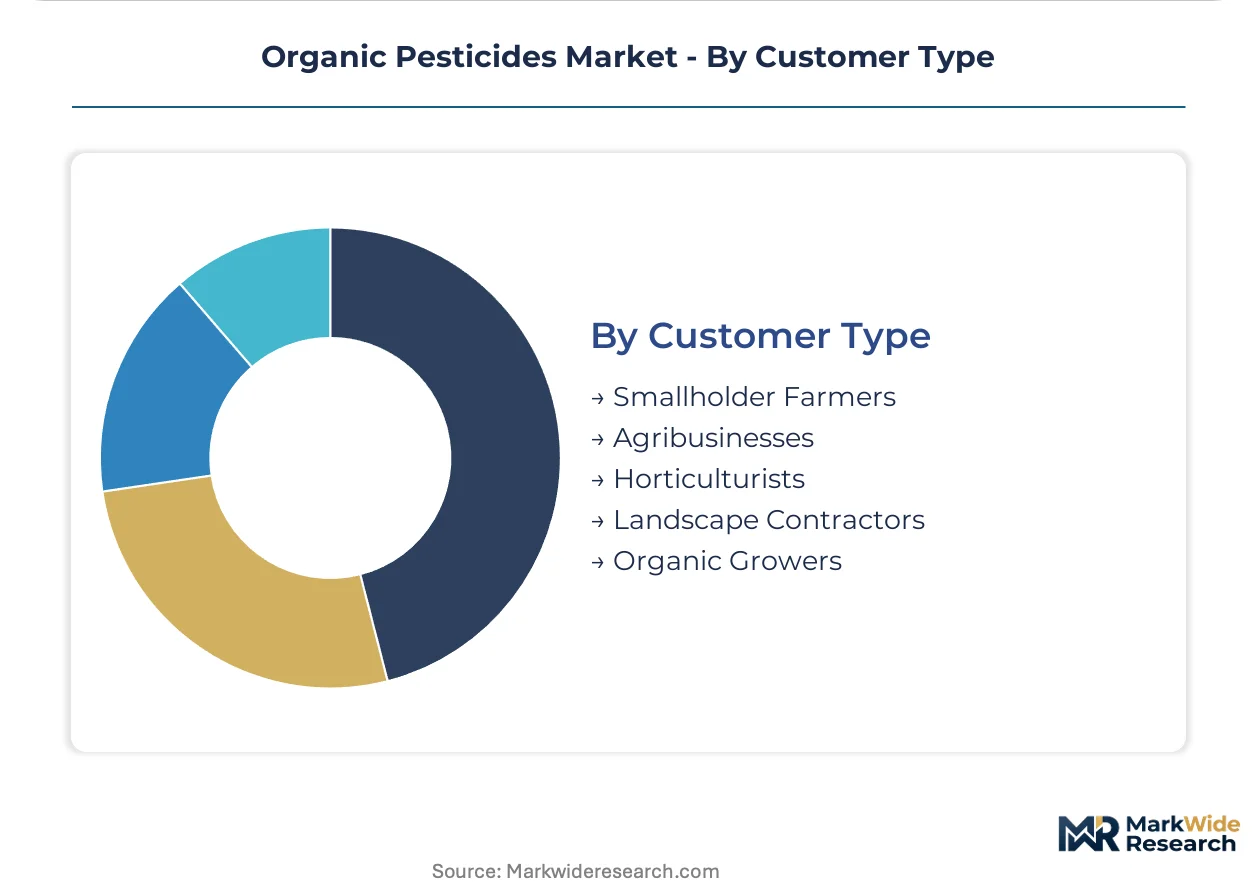
This segmentation differentiates the diverse end-users of organic pesticides, highlighting varied purchasing behaviors and operational scales.
- Agribusinesses:Large-scale commercial farming operations, often focused on commodity crops, are increasingly integrating biologicals into their pest management programs. Their adoption is driven by regulatory pressures and the desire for sustainable practices across vast agricultural areas.
- Organic Growers:Farmers specifically adhering to organic certification standards rely exclusively on approved organic pesticides. Their purchasing decisions are primarily influenced by stringent regulatory frameworks like the USDA's National Organic Program and the EU's approval process.
- Smallholder Farmers:These farmers operate smaller plots, often with limited resources, seeking cost-effective and environmentally friendly solutions.
- Horticulturists:Specialists in ornamental plants, nurseries, and greenhouses utilize organic pesticides for precise pest control.
- Landscape Contractors:Professionals managing public and private green spaces employ biologicals for sustainable maintenance and aesthetic appeal.
Market influence is significant among Agribusinesses. Support requirements are highest for Smallholder Farmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe, with its stringent environmental directives, anchors the regulatory push for organic pesticides. Regulatory frameworks like the EU Green Deal significantly influence product adoption and market development across various agricultural sectors. This regional emphasis on sustainable practices creates a consistent demand pull for biological alternatives.
Germany
German growers demand bio-fungicides and bio-insecticides to comply with strict national and European Union regulations. The EU's Farm to Fork strategy directly impacts pesticide use, compelling farmers to seek non-synthetic options. Research and development hubs in the Rhine-Main region actively innovate novel biological formulations for agricultural applications.
United States
Consumer preference for organic food drives significant demand for organic pesticides in the United States. The USDA National Organic Program sets the standards for permissible inputs, guiding grower choices. California's Central Valley, a major agricultural region, leads in adopting biological solutions for high-value fruit and vegetable crops.
Brazil
Brazil's vast agricultural sector presents substantial expansion potential for organic pesticides, particularly in export-oriented commodity crops. ANVISA, the national health surveillance agency, continues to refine its biopesticide approval processes, streamlining market access. The state of Mato Grosso, a leading producer of soy and corn, increasingly evaluates biological solutions for sustainable farming.
Japan
Japanese agriculture emphasizes food safety and quality, fostering demand for organic pesticides under JAS certification standards. METI, Japan's Ministry of Economy, Trade and Industry, supports research into advanced agricultural technologies, including biological pest control. Hokkaido, a key agricultural prefecture, integrates bio-insecticides into its specialty crop cultivation practices.
France
French agricultural policy, heavily influenced by the EU Green Deal, mandates reductions in synthetic pesticide use. The country's national agency, ANSM, rigorously approves plant protection products, favoring biologicals. Growers in the Loire Valley, renowned for viticulture and fruit orchards, are rapidly adopting bio-fungicides to meet sustainability targets.
Organic Pesticides Market Key Industry Players
Global majors compete with regional champions across product innovation and market penetration in the organic pesticides sector. The market structure shows a tiered landscape, with established chemical companies diversifying into biologicals. Strategic archetypes include diversified agricultural solution providers, specialized biopesticide developers, and integrated pest management innovators. Portfolio diversification and strategic partnerships drive competitive moves.
At the scale-driven end, BASF, a global chemical company, exemplifies broad portfolio integration into biologicals, leveraging extensive research infrastructure. Koppert, a Dutch specialist, occupies a position as an integrated pest management solution provider, particularly for controlled environment agriculture. Corteva Agriscience, an American agricultural giant, anchors its biologicals portfolio to complement existing conventional crop protection offerings.
| Leading Market Players |
|---|
| Marrone Bio Innovations |
| Koppert |
| BASF |
| Nufarm |
| Valent BioSciences |
| Syngenta |
| Certis Biologicals |
| Corteva Agriscience |
| Bayer |
| Others |
Cost & Logistics Intelligence
Heightened consumer preference for residue-free produce drives demand for certified organic inputs. This pressure compels suppliers to invest in specialized production and navigate complex regulatory pathways, directly influencing premium pricing for compliant biologicals.
Pricing Analysis
Integrated solution packages often bundle diagnostic tools, beneficial insects, and tailored biopesticide regimens for growers. Value-based pricing dominates for specialized biologicals, differentiated by certification level and volume scale. Pricing softness affects broad-acre commodity crop applications due to higher per-acre treatment costs. Smallholder farmers remain highly price-sensitive, whereas organic growers prioritize product efficacy and regulatory compliance.
Supply Chain Analysis
Stringent regulatory approvals, including the EU's EFSA process and USDA's National Organic Program, gate market access for organic pesticide active ingredients. Supply concentration centers on European microbial production and US-based R&D for novel formulations. Raw material dependencies include specific microorganisms, plant extracts, and mineral sources. Fragmented global regulatory approvals pose a structural risk, while distribution models shift towards integrated solution packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organic pesticides market is witnessing a vertical-integration race, as companies pursue in-house R&D capabilities to accelerate novel formulation development. This strategy aims to control product innovation and streamline regulatory navigation.
For Market Incumbents:Cement market leadership by investing heavily in R&D for RNAi technology and climate-adaptive formulations. Diversify production capacity in key agricultural regions like Europe to meet increasing regulatory demand. Consolidate smaller niche specialists offering integrated pest management solutions, countering the threat of fragmented market entry. Expand farmer education programs to ensure effective product application and drive adoption against synthetic chemical alternatives.
For New Entrants and Emerging Players:Launch via strategic partnerships with established agricultural distributors in underpenetrated markets like Latin America. Target the broad-acre crop segment with cost-effective, stable biological formulations for corn and soy. Focus on developing highly specific, mode-of-action solutions for high-value specialty crops where precision is paramount. A go-to-market angle emphasizing product efficacy under diverse environmental conditions will resonate with growers.
For Investors and Strategic Acquirers:The window for entry favors vertically integrated mid-cap specialists with proven scalability in microbial production. Seek out firms possessing strong intellectual property in novel biological mechanisms, particularly RNAi. Long-term viability hinges on companies that can consistently navigate fragmented global regulatory approval processes over a 5-10 year horizon. A signal to watch is the increasing market share of biologicals in major commodity crop segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling European microbial production addresses rising demand from stricter agricultural standards. |
| R&D Investment | Developing RNAi technology and climate-adaptive formulations creates ultra-specific pest management solutions. |
| Regulatory Alignment | Successfully navigating EU EFSA and USDA NOP processes ensures market access for new products. |
| Market Penetration | Expanding into Latin American broad-acre crops unlocks substantial untapped agricultural sectors. |
| Portfolio Diversification | Integrating biologicals with conventional offerings strengthens competitive positioning for agribusinesses. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and academic literature underwrites the qualitative findings within this analysis. Primary interviews involved R&D directors, agricultural extension specialists, and farm managers. Secondary validation drew from USDA National Organic Program databases, EU EFSA reports, and company financial statements. This approach ensured robust bottom-up and top-down triangulation of market estimates.
Historical data from comparable periods anchored the forecast window, establishing baseline performance metrics for organic pesticides. Segmentation dimensions modeled include product type, application area, formulation, and customer type. Compound Annual Growth Rates were derived through a proprietary analytical framework incorporating market drivers and restraints. Key forecast inputs included regulatory policy shifts and advancements in microbial science.
Unforeseen regulatory changes, rapid technological breakthroughs, and significant shifts in agricultural commodity prices are the dominant revision risks. Forecasts reflect assumptions documented regarding market dynamics and competitive landscape. A model refresh is warranted upon material change in global agricultural policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Grain Protectant Market
Crop Protection
Iprodione Market
Crop Protection
US Pest Control Market
Crop Protection
Fumigation Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
South America Molluscicides Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
South America Insecticide Market