
 Agricultural Pheromones Market | 2026-2036
Agricultural Pheromones Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Pheromones Market Analysis
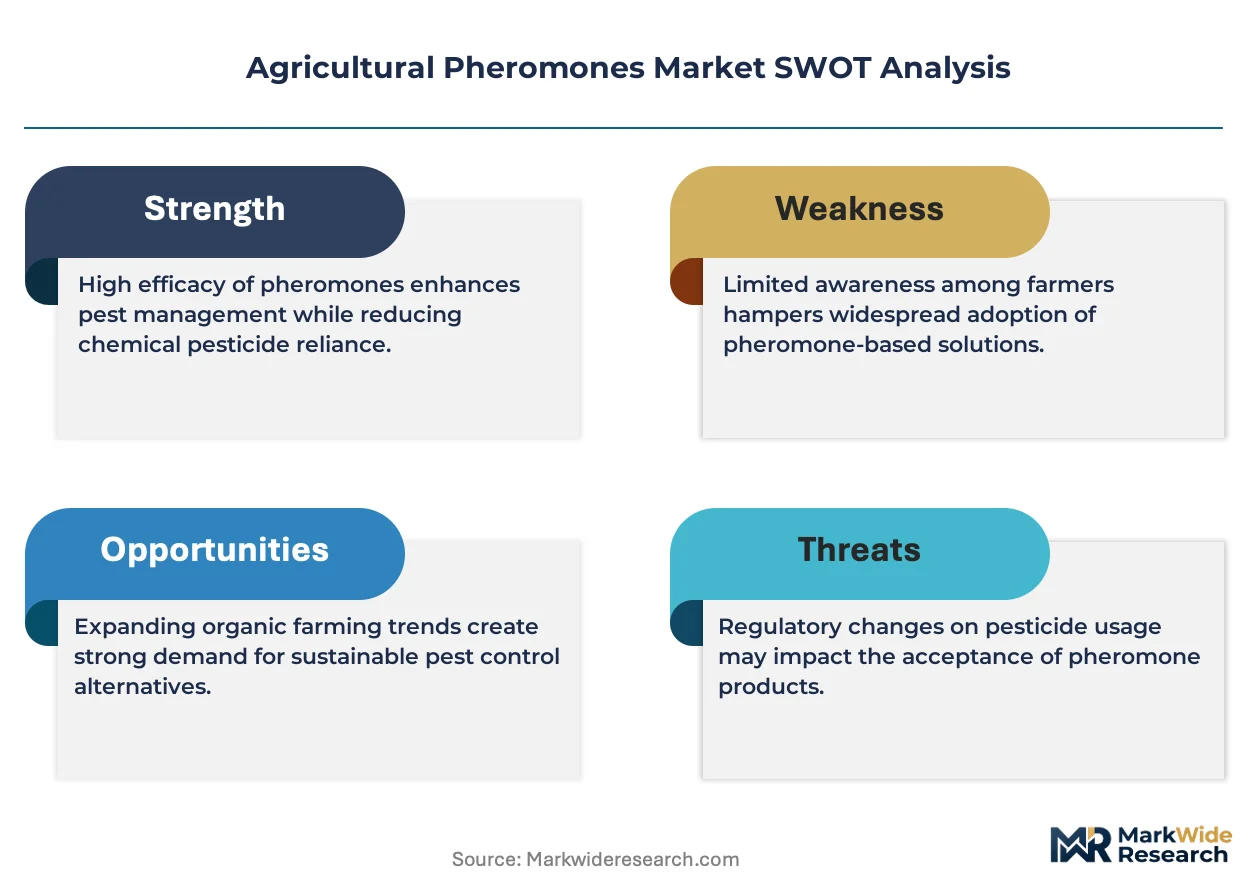
Project finance for distributed pheromone manufacturing is rewriting competitive entry barriers, lowering capital thresholds for regional formulation specialists. Russell IPM Ltd leverages its integrated supply chain from active ingredient synthesis to field delivery, sustaining cost advantages across Mediterranean markets. Provivi, Inc. anchors its position through precision fermentation platforms that reduce synthetic chemistry dependence. BASF SE competes through global distribution reach and bundled crop protection portfolios.
Agricultural pheromones are semiochemical compounds, typically aliphatic hydrocarbons or acetate esters, synthesized to mimic insect sex attractants for species-specific pest management without residual toxicity. These compounds function at nanogram-per-hectare release rates, disrupting mating cycles through confusion or mass trapping protocols that eliminate chemical resistance pathways. Mating disruption formulations dominate value pools due to recurring seasonal application requirements and premium pricing tied to crop-specific customization. Monitoring applications represent the fastest-expanding segment as precision agriculture platforms integrate trap-count data with automated decision-support systems. Solid matrix dispensers lead form-factor adoption in orchards and vineyards, while liquid formulations gain traction in row-crop aerial application.
EPA biopesticide registration pathways under FIFRA Section 3(c)(5) shape product development timelines and label claims for US market entry, while REACH compliance in Europe governs active substance authorization and environmental fate testing. USDA organic certification standards and EU Organic Regulation 2018/848 create parallel demand channels where synthetic pheromones qualify as allowed substances. Stakeholders must monitor evolving residue tolerance frameworks and pollinator risk assessments that could reclassify semiochemicals relative to conventional insecticide benchmarks.
Market Dynamics
The EU Farm to Fork Strategy's 50% pesticide reduction mandate is compressing substitution timelines for biocontrol alternatives, forcing rapid reconfiguration of crop protection procurement across Mediterranean agriculture.
Growth Catalysts
- REACH authorization pathways:ECHA's streamlined biopesticide substance approval is accelerating pheromone active ingredient market entry for European formulators.
- Neonicotinoid phase-outs:California's Central Valley nut growers face tightening carbamate and neonicotinoid restrictions, redirecting integrated pest management budgets toward mating disruption systems.
- Precision fermentation platforms:Biosynthesis methods for aliphatic hydrocarbon pheromones are reducing synthetic chemistry feedstock dependence and stabilizing production costs.
Market Restraints
- Active ingredient supply concentration:Synthesis of (Z)-11-hexadecenal and related acetate esters relies on a narrow base of specialized chemical manufacturers clustered in China and India.
- Seasonal revenue compression:Mating disruption applications concentrate in narrow pre-bloom windows, creating working capital intensity for distributors holding inventory across dormant periods.
- Species specificity limits:Each pheromone formulation targets a single pest species, requiring portfolio breadth that multiplies R&D overhead relative to broad-spectrum insecticides.
Strategic Opportunities
- USDA organic certification expansion:EU Organic Regulation 2018/848 and parallel US standards qualify synthetic pheromones as approved substances, opening premium pricing channels in certified stone fruit and nut operations.
- Drone-based aerial dispensing:Liquid formulation compatibility with unmanned aerial application systems is enabling row-crop penetration beyond traditional orchard boundaries.
- Polish and Romanian orchard development:Eastern European stone fruit acreage expansion lacks established mating disruption supplier networks, creating first-mover positioning potential.
Industry Challenges
- Semiochemist talent scarcity:Expertise in insect chemical ecology and formulation stability engineering concentrates in academic institutions rather than commercial R&D pipelines.
- Field efficacy validation timelines:Multi-season mating disruption efficacy studies delay label expansion and crop-specific product claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Pheromones Market |
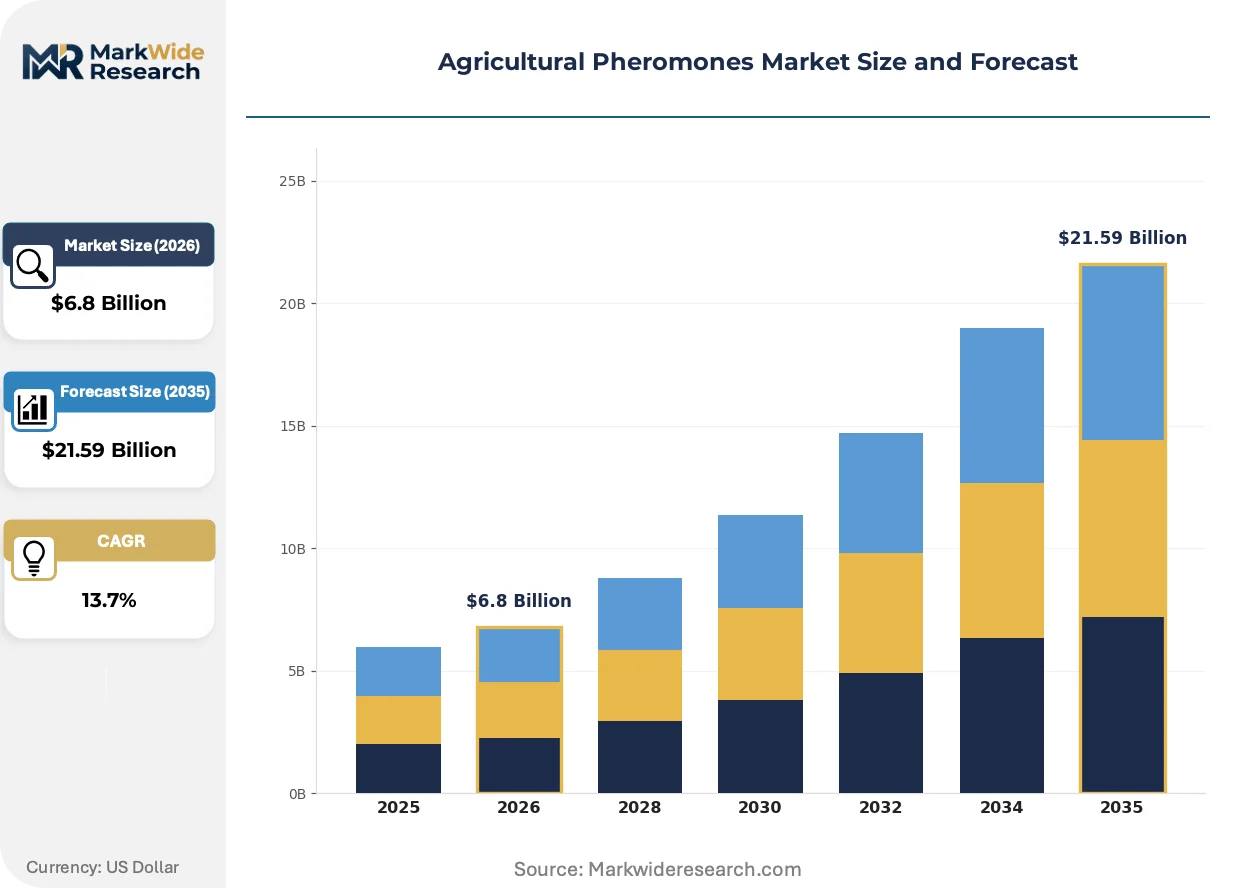
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mating Disruption, Mass Trapping, Monitoring, Attractants End Use Industry: Crops, Horticulture, Turf, Orchard Distribution Channel: Online, Retail, Direct Sales, Distributors Form: Liquid, Solid, Aerosol, Gel |
| Companies Covered | Russell IPM Ltd, Provivi, Inc., Shin-Etsu Chemical Co., Ltd., ISCA Technologies, Inc., Bayer AG, Suterra LLC, Biobest Group NV, BASF SE, Koppert Biological Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Pheromones Market Emerging Trajectories
Digital integration of trap monitoring data with automated decision support is compressing the feedback loop between pest detection and biocontrol deployment across precision agriculture platforms.
Precision agriculture sensor networks are digitizing pheromone trap count collection, replacing manual scouting labor with automated image recognition systems. Large-scale vineyard operators in France and Spain are deploying these systems at hectare-scale density. The technology is digitizing pest pressure mapping and enabling variable-rate dispenser placement that reduces chemical load while maintaining disruption efficacy.
EPA biopesticide registration under FIFRA Section 3(c)(5) is tightening residue tolerance frameworks for semiochemicals relative to conventional insecticide benchmarks. The agency's evolving pollinator risk assessment protocols now require expanded non-target arthropod testing for mating disruption products. California specialty crop registrants are responding by front-loading environmental fate data packages to secure accelerated review timelines.
Integrated pest management service bundling is displacing standalone pheromone procurement as the dominant buyer-seller relationship model. Major nut and vine cooperatives in California and Italy are contracting full-season pest management outcomes rather than purchasing dispensers directly. This shift concentrates purchasing authority with technical service providers and compresses margins for formulation-only suppliers.
Agricultural Pheromones Market Segmentation
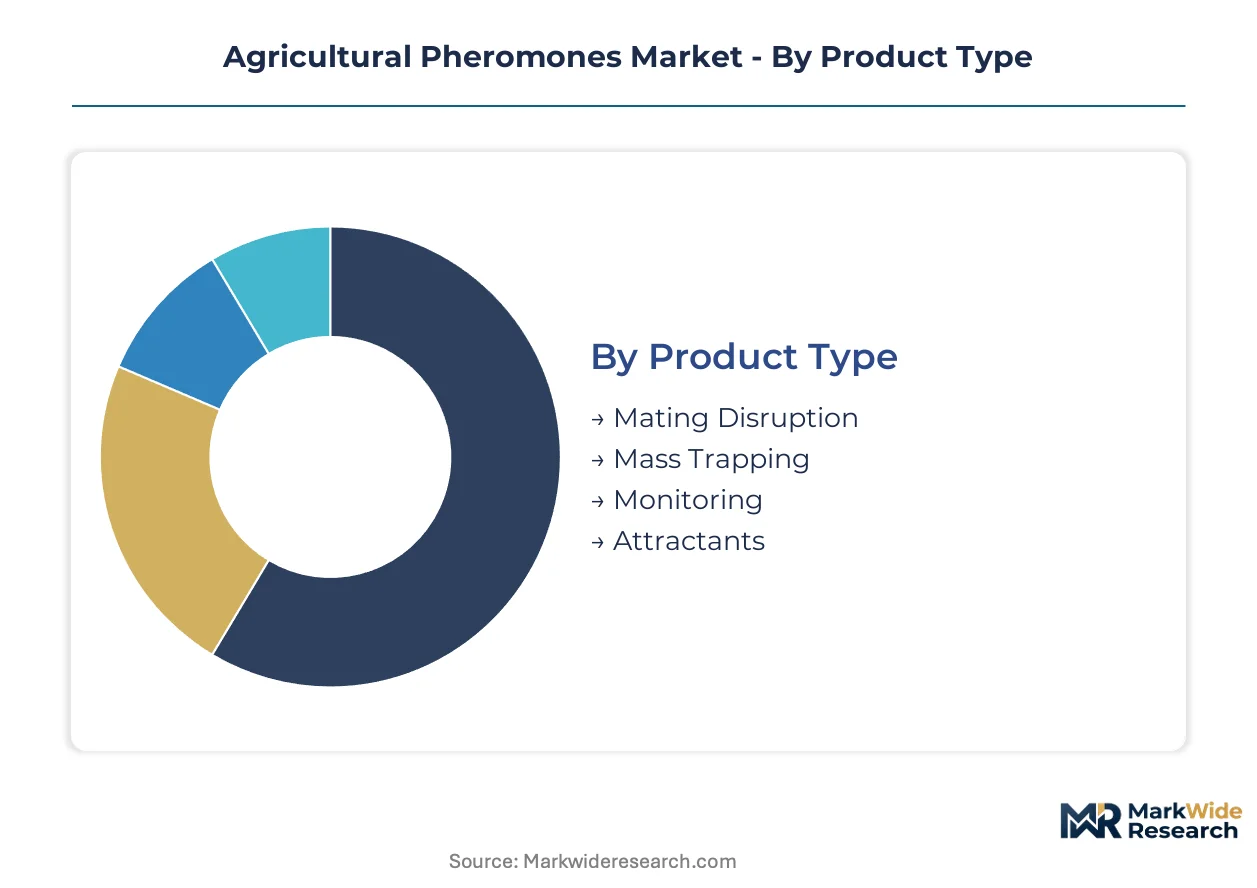
Pheromone applications span distinct functional roles from population suppression to early warning systems, each commanding different price points and technical service intensity. Segmentation reveals how formulation chemistry and delivery mechanisms align with crop-specific pest pressure cycles and grower operational constraints.
Product Type:
The use-case spectrum ranges from preventive population control through reactive detection, with each application mode demanding specialized release kinetics and field deployment protocols.
- Mating Disruption:Saturated airspace with synthetic sex pheromones overwhelms male insect orientation, preventing fertilization across multiple generations. California almond and pistachio growers allocate the largest integrated pest management budgets to this modality under tightening neonicotinoid restrictions.
- Mass Trapping:High-density lure-baited traps physically remove pests from breeding populations, effective against low-density invasions where immigration pressure remains manageable. Italian olive producers deploy these systems along orchard perimeters to intercept olive fruit fly migrations from untreated neighboring plots.
- Monitoring:Trap-based detection enables threshold-triggered intervention timing, reducing unnecessary biocide applications. French vineyard cooperatives integrate automated image recognition with pheromone trap networks for real-time pest pressure mapping.
- Attractants:Food-based kairomones or aggregation pheromones draw pests to lethal exposure points, often combined with insecticide-treated surfaces for species where mating disruption proves ineffective.
The dominant share belongs to Mating Disruption, while Monitoring is closing the gap fastest through precision agriculture platform integration.
End Use Industry:
Customer maturity varies sharply across cultivation systems, with permanent plantings supporting higher per-hectare pheromone investment than annual rotations.
- Orchard:Tree fruit and nut operations with multi-decade production horizons justify upfront pheromone infrastructure costs through multi-year pest suppression benefits. Spain's Extremadura and Aragón regions lead European mating disruption adoption for peach and plum protection.
- Horticulture:Greenhouse vegetable producers deploy pheromones within controlled environments where closed-system containment amplifies disruption efficacy against tomato leafminer and pepper weevil.
- Crops:Row-culture applications remain limited by aerial application compatibility constraints and shorter economic return windows per growing season.
- Turf:Golf course and sod farm managers utilize monitoring lures for billbug and armyworm detection, though mating disruption sees minimal traction in this segment due to high maintenance traffic disrupting dispenser placement.
Orchard commands the largest revenue pool, with Horticulture expanding most quickly through protected cultivation intensification.
Distribution Channel:
Channel selection reflects buyer technical sophistication and the degree of agronomic support required for effective pheromone deployment.
- Distributors:Regional agricultural supply cooperatives aggregate pheromone procurement with conventional crop protection products, offering seasonal credit terms aligned with harvest cash flows. Central Valley nut growers rely heavily on this channel for integrated pest management bundle sourcing.
- Direct Sales:Large vineyard and orchard operators contract directly with formulators for customized dispenser specifications and volume pricing, bypassing distributor markups on high-acreage commitments.
- Retail:Independent garden centers and farm supply stores serve smallholder horticulture operations with pre-packaged monitoring trap kits and seasonal mating disruption dispensers.
- Online:E-commerce platforms enable specialty pheromone access for organic certification-bound producers in regions lacking established distribution infrastructure.
Distributors retain the dominant position, though Direct Sales is gaining share fastest among large cooperative buyers.
Form:
Physical formulation dictates application equipment requirements, field persistence, and compatibility with precision deployment technologies.
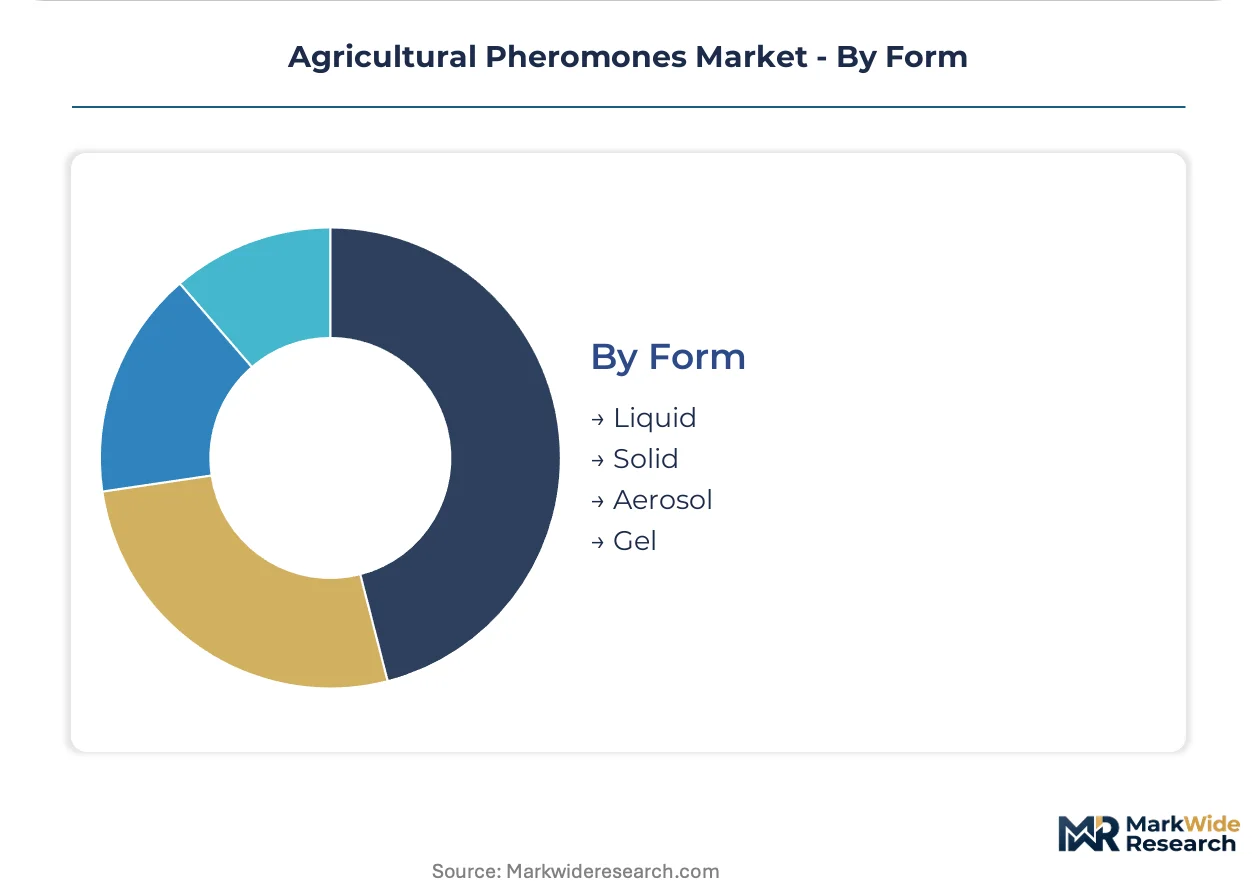
- Solid:Polymer matrix dispensers and twist-tie formulations release pheromones through passive diffusion across 90-180 day field lifespans. Mediterranean stone fruit and grape producers favor these for single-application seasonal coverage.
- Liquid:Microencapsulated sprays and flowable concentrates enable aerial drone application and variable-rate dispensing based on real-time pest pressure mapping. Compatibility with unmanned aerial systems is accelerating row-crop penetration.
- Aerosol:Pressurized pheromone emitters deliver pulsed release for high-value greenhouse applications where immediate airspace saturation proves critical.
- Gel:Viscous formulations applied to tree trunks or structural surfaces provide extended-release point sources for perimeter protection and immigration barrier establishment.
Solid formulations hold the dominant share, while Liquid is climbing the fastest through aerial application technology advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a concentrated supply base in East Asian active ingredient synthesis serving formulation specialists across Mediterranean and North American growing regions. Import dependency for key aliphatic hydrocarbon precursors shapes procurement strategies for European and US formulators.
United States
California's Central Valley nut and vine growers drive mating disruption procurement under tightening EPA neonicotinoid restrictions. FIFRA Section 3(c)(5) biopesticide registration pathways structure product development timelines for domestic market entry. Fresno and Kern counties concentrate aerial application service providers integrating liquid pheromone formulations with drone-based dispensing systems.
Spain
Extremadura and Aragón stone fruit operators expand pheromone-based olive and peach protection programs under EU Farm to Fork pesticide reduction mandates. EU Organic Regulation 2018/848 qualifies synthetic pheromones for certified production channels. Lleida province anchors formulation distribution networks serving Catalan vineyard cooperatives with automated trap monitoring integration.
Italy
Apulia and Sicily olive growers deploy perimeter mass trapping systems against olive fruit fly immigration from untreated neighboring plots. ECHA streamlined biopesticide substance approval accelerates active ingredient market entry for domestic formulators. Emilia-Romagna's stone fruit belt concentrates integrated pest management service bundling contracts with technical providers.
China
Specialized chemical manufacturers in Jiangsu and Zhejiang provinces concentrate synthesis of (Z)-11-hexadecenal and acetate ester precursors for global formulators. The country's national chemical regulator oversees environmental fate testing for export-oriented active ingredient production. Yangtze River Delta clusters supply intermediate feedstocks to Mediterranean and North American mating disruption specialists.
France
Bordeaux and Champagne vineyard cooperatives integrate automated image recognition with pheromone trap networks for real-time pest pressure mapping. REACH compliance governs active substance authorization for domestic and EU-wide distribution. Languedoc-Roussillon's expanding organic wine sector drives premium pricing for certified pheromone applications.
Agricultural Pheromones Market Vendor Landscape
On the supply side, the industry is structured around a tiered constellation of specialized formulators, diversified agrochemical majors, and precision fermentation platform operators. Strategic archetypes include integrated supply chain specialists, biosynthesis technology anchors, and global distribution portfolio bundlers. Dominant competitive moves encompass backward integration into active ingredient synthesis and geographic expansion through regional formulation licensing.
Among UK-based integrated specialists, Russell IPM Ltd exemplifies the captive supply chain archetype spanning synthesis to field delivery. Japanese chemical conglomerates Shin-Etsu Chemical Co., Ltd. occupy positions bridging materials science expertise with agricultural applications. German diversified giant BASF SE anchors the global distribution tier through bundled crop protection portfolios. Precision fermentation platform Provivi, Inc. represents the biosynthesis technology vector reducing synthetic chemistry dependence.
| Leading Market Players |
|---|
| Russell IPM Ltd |
| Provivi, Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| ISCA Technologies, Inc. |
| Bayer AG |
| Suterra LLC |
| Biobest Group NV |
| BASF SE |
| Koppert Biological Systems |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Jiangsu and Zhejiang synthetic chemistry clusters is compressing active ingredient margins and forcing pheromone formulators toward long-term offtake contracts that lock in feedstock pricing power. This utilization dynamic reshapes supplier bargaining positions across Mediterranean and North American formulation networks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across California nut cooperatives and Italian vineyard consortia. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale. Cost compression in economy-tier solid dispensers is intensifying because Chinese feedstock oversupply feeds price erosion. Smallholder horticulture operators through retail channels exhibit highest price sensitivity, while direct-sale vineyard cooperatives with multi-year commitments show lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates risk calculus for (Z)-11-hexadecenal precursor procurement. Synthesis concentrates in Jiangsu and Zhejiang provinces of China, with secondary formulation capacity in Spain and California. Feedstock dependencies rest on acetate ester intermediates, aliphatic hydrocarbon precursors, and polymer matrix substrates. Single-source vulnerability from concentrated Chinese active ingredient manufacturing threatens supply continuity. Distribution runs through regional agricultural supply cooperatives with seasonal credit alignment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial R&D pipelines for insect chemical ecology expertise remain critically thin relative to formulation demand, creating acquisition premiums for specialist talent pools. This scarcity dynamic rewards early capability-building investments.
For Market Incumbents: Pre-empt precision fermentation platform entrants by securing captive supply of aliphatic hydrocarbon feedstocks through backward integration into Jiangsu-based synthesis partnerships. Defend margin position against biosynthesis substitutes by front-loading EPA biopesticide registration data packages under FIFRA Section 3(c)(5) to accelerate label expansion timelines. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian stone fruit acreage where established mating disruption supplier networks remain absent. Target direct sales contracts with expanding Eastern European orchard operators seeking EU Organic Regulation 2018/848 certification compliance. Lead with drone-compatible liquid formulation portfolios to differentiate from incumbent solid dispenser incumbency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation platform operators as biosynthesis methods mature. Long-term viability favors acquisition targets combining semiochemist talent depth with automated trap monitoring technology integration. Watch ECHA biopesticide substance approval velocity as the inflection signal for European formulation market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive supply of (Z)-11-hexadecenal precursors insulates margin from Chinese feedstock volatility. |
| Precision Fermentation Platform Scale-Up | Biosynthesis methods reduce synthetic chemistry dependence and stabilize production cost structures. |
| Drone-Based Aerial Dispensing Partnership | Liquid formulation compatibility with unmanned aerial systems enables row-crop market penetration. |
| Automated Trap Monitoring Integration | Digital pest pressure mapping compresses feedback loops between detection and biocontrol deployment. |
| EU Organic Certification Channel Development | Synthetic pheromone qualification under Regulation 2018/848 opens premium pricing in certified operations. |
Methodological Framework
Desk research of EPA biopesticide registration filings, ECHA substance approval databases, and EU Farm to Fork Strategy implementation reports preceded structured interviews with semiochemist R&D directors, agricultural cooperative procurement managers, and precision fermentation platform operators. Primary fieldwork combined with secondary validation from USDA organic certification records and Yangtze River Delta customs data. Bottom-up acreage deployment estimates and top-down formulation revenue analysis provided triangulation.
Assumptions held fixed include EU pesticide reduction mandate compliance timelines and neonicotinoid restriction enforcement intensity across California. Segmentation dimensions modeled encompass application mode, crop system, formulation chemistry, and distribution channel. CAGRs derived from weighted average of historical deployment trajectories and regulatory substitution elasticity. Industry-specific inputs incorporated mating disruption efficacy study timelines and precision agriculture platform adoption curves.
Sensitivities concentrate around ECHA approval velocity for biopesticide substances and California aerial application regulatory frameworks. Forecasts reflect documented assumptions regarding Farm to Fork implementation pacing and REACH authorization pathway efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Global Termite Control Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Global Insecticide Seed Treatment Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Metamifop Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Miticides Market