
 Language Translation Software Market | 2026-2036
Language Translation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Language Translation Software Market Intelligence
Neural network architectures are broadening the functional economics of language translation software by displacing rules-based statistical models with transformer-based systems that learn contextual patterns across billions of parameters. Smartcat leverages its marketplace model to connect enterprises with vetted linguists while embedding AI pre-translation layers that reduce per-word costs. Lionbridge sustains its position through deep vertical specialization in life sciences and legal localization, where regulatory accuracy requirements command premium pricing. TransPerfect competes on geographic reach, operating delivery centers across more than 100 countries to support round-the-clock project workflows for multinational clients.
Language translation software encompasses machine-driven and human-augmented systems that convert text, speech, and multimedia content across languages using natural language processing engines, neural machine translation models, and computer-assisted translation tools. These systems process source material through tokenization, attention mechanisms, and beam-search decoding to generate target-language output with measurable fluency and adequacy scores for enterprise content management, e-commerce localization, and regulatory document submission. Machine translation and hybrid solutions currently occupy the largest revenue pools, as enterprises balance speed and cost against the quality thresholds required for customer-facing materials. Cloud-based deployment is expanding fastest among mid-market buyers seeking API-accessible translation infrastructure without capital expenditure on on-premises server clusters.
The EU AI Act, GDPR, and ISO 17100 standards collectively shape product development roadmaps by mandating transparency in automated translation outputs, restricting cross-border data flows for linguistic training datasets, and certifying human-in-the-loop quality assurance protocols. The US Food and Drug Administration and the European Medicines Agency impose additional validation requirements on translated clinical trial documentation and pharmaceutical labeling, creating compliance barriers for vendors lacking domain-specific quality management systems. Stakeholders must monitor evolving regulatory divergence between jurisdictions as a primary determinant of localization cost structures and market access eligibility.
Market Dynamics
Transformer-based neural architectures are compressing translation economics by displacing statistical machine translation with context-aware models that learn from billions of multilingual parameters, forcing vendors to restructure pricing around API consumption rather than per-word licensing.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision-making disclosure requirements are accelerating vendor investment in explainable NLP pipelines that document translation confidence scores and source attribution for enterprise audit trails.
- Automotive OEM localization intensity:German industrial exporters are commissioning specialized neural engines for technical documentation, creating captive demand for domain-trained models with embedded terminology management.
- Cloud API accessibility:Mid-market buyers are adopting serverless translation infrastructure through REST endpoints, eliminating capital expenditure on on-premises hardware and compressing deployment cycles from months to days.
Market Restraints
- GPU compute cost volatility:Training and inference for large language models depends on NVIDIA H100 and A100 availability, with cloud rental rates fluctuating based on semiconductor supply constraints and energy pricing in Taiwan and South Korea.
- Cross-border data flow restrictions:GDPR Article 44 limitations on transferring linguistic training datasets outside the European Economic Area are fragmenting model development into jurisdiction-specific silos, raising compliance overhead for global vendors.
- Human-in-the-loop quality certification:ISO 17100 requirements for post-editing by credentialed linguists prevent full automation of regulated content, preserving cost floors for pharmaceutical labeling and clinical trial documentation.
Strategic Opportunities
- India's BFSI localization gap:Domestic banks and insurance providers are underinvested in vernacular customer interfaces, creating first-mover potential for vendors offering Hindi, Tamil, and Marathi neural engines with regulatory-grade accuracy.
- Real-time speech-to-speech convergence:Synchronous integration of automatic speech recognition, neural machine translation, and text-to-speech synthesis is opening simultaneous interpretation markets previously reserved for human conference interpreters.
- CSRD sustainability reporting mandates:European corporates must publish non-financial disclosures in all member-state languages, generating structural demand for automated ESG document localization with controlled terminology consistency.
Industry Challenges
- Computational linguist scarcity:Vendors struggle to hire specialists capable of tuning transformer attention mechanisms for low-resource language pairs, constraining model coverage expansion.
- Legacy TMS integration friction:Enterprise content management systems built on SDL Trados and MemoQ architectures require custom middleware to consume cloud API outputs, extending sales cycles and implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Language Translation Software Market |
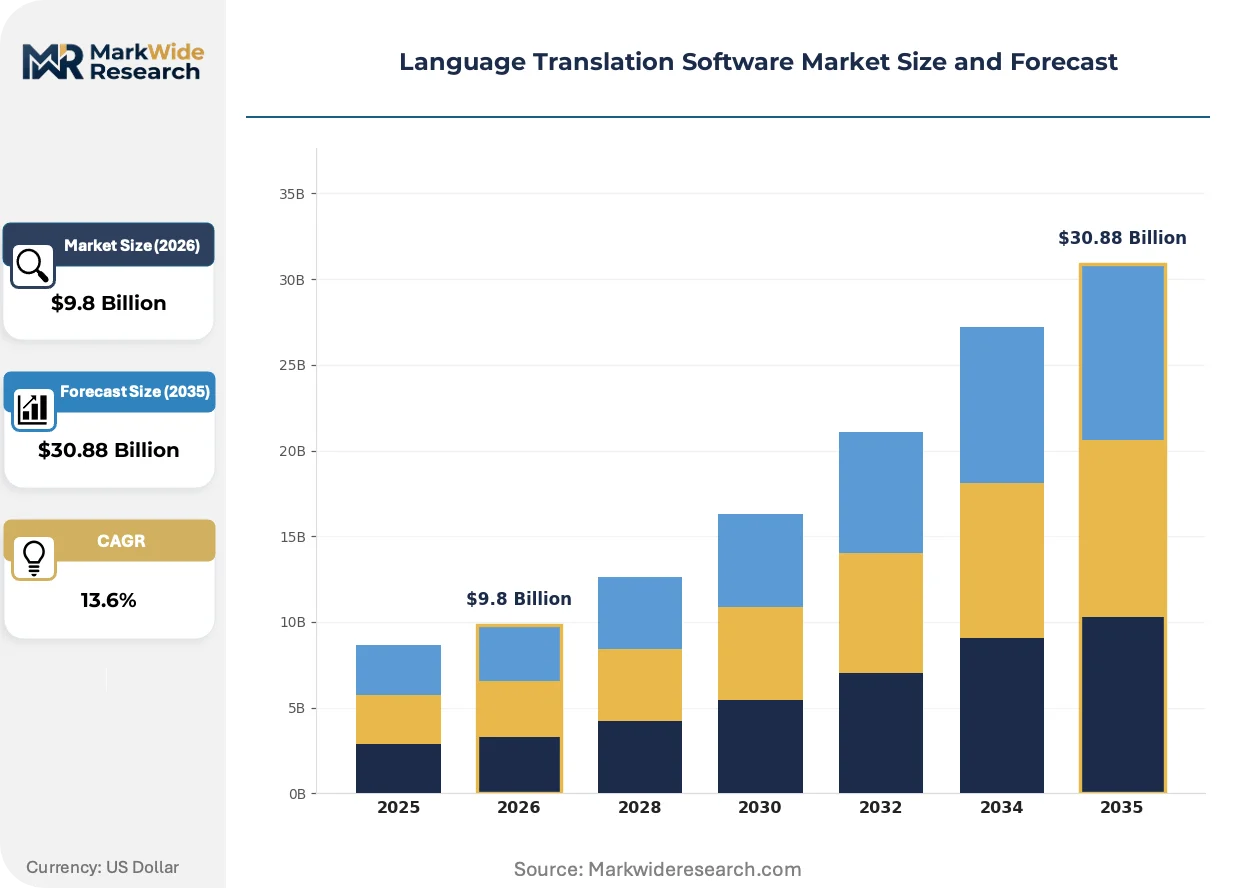
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $30.88 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Translation, Human Translation, Hybrid Solutions, Translation Management Systems End User: Enterprises, Educational Institutions, Government Agencies, Freelancers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile App Technology: NLP, Neural Networks, AI, Statistical Models |
| Companies Covered | Smartcat, Transifex, Smartling, TransPerfect, Lionbridge, Taia, XTM Cloud, Lilt, Lokalise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Language Translation Software Market Strategic Shifts & Innovations
Translation technology is converging around foundation models that unify multiple linguistic tasks, compressing the vendor landscape as scale economies favor providers with proprietary training data and inference infrastructure.
Large language models fine-tuned for translation are consolidating competitive positioning by absorbing terminology management, quality estimation, and post-editing prediction into single inference calls. Pharmaceutical and legal localization teams are piloting these unified systems to reduce toolchain complexity. This consolidation is compressing margins for point-solution vendors lacking model ownership.
The EU AI Act's risk-based classification system is mandating human oversight documentation for high-stakes translation outputs in medical device labeling and financial prospectuses. Vendors must implement logging architectures that trace model versions, training data provenance, and confidence thresholds. Life sciences localization providers are responding by embedding quality management systems that generate audit-ready evidence packages.
Enterprise buyers are unbundling translation from traditional localization service contracts, procuring neural engine capacity directly through metered APIs while retaining human post-editing for final-mile quality assurance. This disintermediation is visible most acutely in Germany, where automotive and industrial machinery exporters are building in-house localization platforms using cloud-native infrastructure rather than outsourcing to full-service agencies.
Language Translation Software Market Segmentation
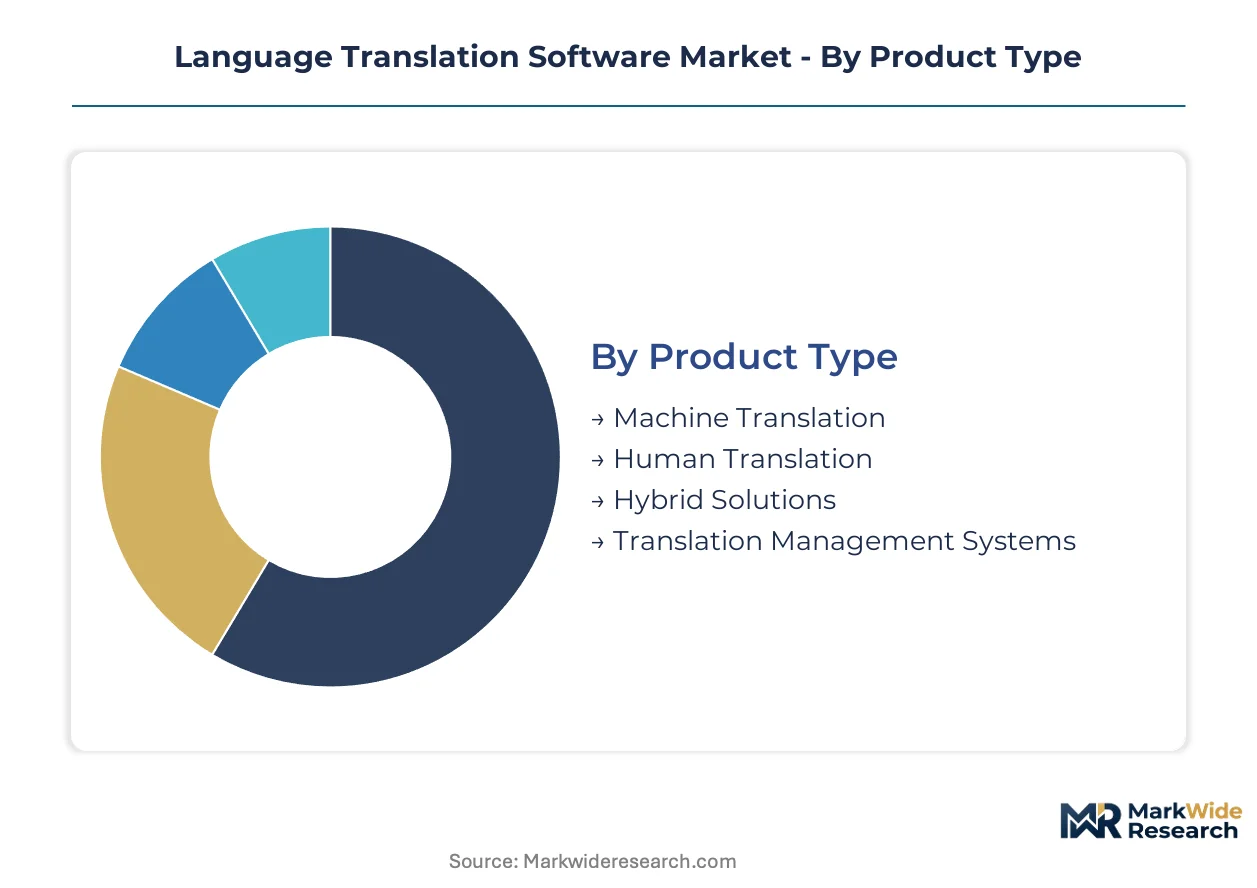
Translation software procurement decisions hinge on balancing automation depth against quality thresholds, with deployment architecture and technology stack determining integration complexity and total cost of ownership. Enterprise buyers segment their spending across these dimensions based on content risk profiles and regulatory exposure.
Product Type:
Upgrade cycles accelerate where neural architectures displace legacy statistical engines, compressing replacement timelines from five-year horizons to eighteen-month refresh intervals.
- Machine Translation:Transformer-based inference engines process source content through attention mechanisms and beam-search decoding. Demand concentrates among German automotive OEMs for technical documentation localization, driven by EU AI Act transparency mandates requiring documented confidence scoring for automated outputs.
- Hybrid Solutions:Architectures combine neural pre-translation with human post-editing workflows certified to ISO 17100 standards. Life sciences localization teams in Switzerland and the United States deploy these systems for pharmaceutical labeling where FDA and Swissmedic validation requirements preserve human-in-the-loop checkpoints.
- Human Translation:Credentialed linguist networks handle high-stakes legal and financial documentation requiring notarized accuracy certification.
- Translation Management Systems:Enterprise platforms orchestrate terminology databases, translation memory, and vendor workflows through centralized dashboards.
Volume placements concentrate in Machine Translation; the faster expansion belongs to Hybrid Solutions.
End User:
Procurement authority and budget scale vary sharply across buyer types, with enterprise IT departments driving API-centric purchasing while government tenders favor on-premises security architectures.
- Enterprises:Multinational corporations consume translation capacity through metered cloud APIs for e-commerce localization and customer support automation. German industrial exporters command specialized neural engines with embedded terminology management for technical documentation at scale.
- Government Agencies:National security and diplomatic institutions require air-gapped deployment with audit trails for classified material processing. India's Ministry of External Affairs and comparable bodies in other jurisdictions drive demand for vernacular language coverage in low-resource pairs.
- Educational Institutions:Universities and research consortia license academic-tier platforms for multilingual corpus development and cross-border collaboration.
- Freelancers:Individual linguists subscribe to computer-assisted translation tools on per-seat SaaS models.
Revenue gravity sits with Enterprises; Educational Institutions are gaining share fastest as research funding for multilingual NLP expands.
Deployment:
Capital expenditure constraints and data sovereignty requirements shape infrastructure choices, with mid-market buyers avoiding hardware ownership while regulated industries retain on-premises control.
- Cloud-Based:Serverless REST endpoints eliminate capital expenditure and compress deployment cycles. Mid-market buyers across France, Italy, and Spain adopt these architectures for rapid e-commerce localization without data center investment.
- On-Premises:Air-gapped server clusters host sensitive translation workflows for defense and intelligence applications. GDPR Article 44 restrictions on cross-border data flows reinforce demand within the European Economic Area for locally hosted inference infrastructure.
- Hybrid:Split architectures route public-facing content through cloud APIs while retaining confidential material on private infrastructure.
- Mobile App:Edge-deployed models enable offline translation for field personnel and travelers in connectivity-constrained environments.
Deployment volumes favor Cloud-Based infrastructure; Mobile App delivery is climbing the fastest as on-device neural compression improves.
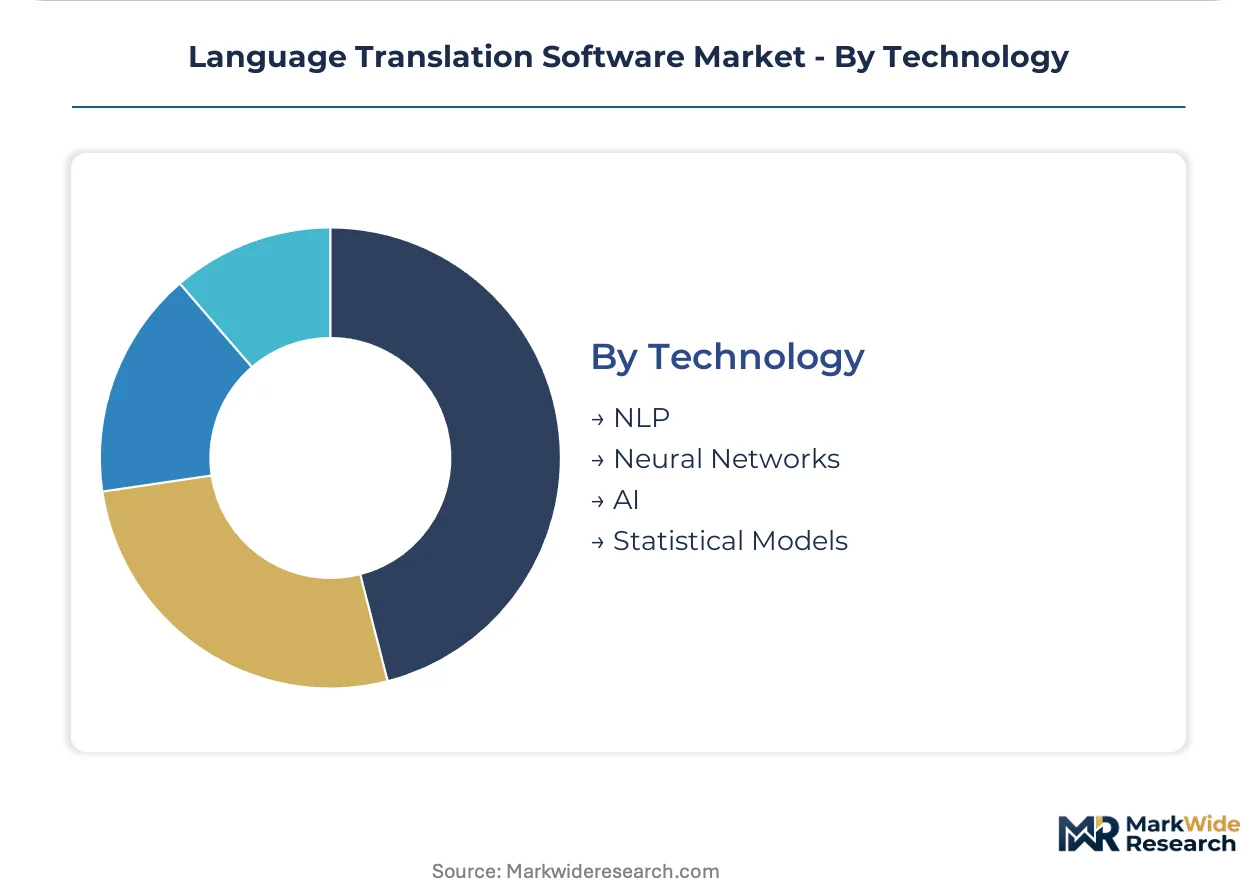
Technology:
Model architecture selection determines inference economics and quality ceilings, with foundation models consolidating previously discrete toolchain components.
- Neural Networks:Transformer architectures with billions of multilingual parameters learn contextual patterns across tokenized corpora. German automotive and industrial machinery exporters commission domain-fine-tuned variants for technical terminology consistency.
- NLP:Natural language processing pipelines handle tokenization, named entity recognition, and syntactic parsing as preprocessing stages. European life sciences localization providers embed these layers for regulatory document structuring compliant with EMA submission formats.
- AI:Broad artificial intelligence frameworks encompass quality estimation, post-editing prediction, and terminology extraction.
- Statistical Models:Legacy phrase-based and hierarchical systems persist in maintenance-mode deployments for specific low-resource language pairs.
Technology investment concentrates in Neural Networks; NLP integration is expanding most quickly as unified foundation models absorb preprocessing functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for language translation software concentrates in Germany, where automotive OEMs and industrial exporters commission specialized neural engines for technical documentation localization.
Germany
Automotive OEMs and industrial machinery exporters drive specialized neural engine procurement for technical documentation. The EU AI Act mandates transparency in automated translation outputs, requiring documented confidence scoring for enterprise audit trails. Stuttgart and Munich host dense clusters of domain-trained model development for embedded terminology management.
United States
Enterprise IT departments and life sciences localization teams consume metered cloud APIs for e-commerce and regulatory document workflows. FDA validation requirements for translated clinical trial documentation preserve human-in-the-loop checkpoints for pharmaceutical labeling. Boston and San Francisco anchor concentrations of NLP infrastructure providers serving multinational corporations.
India
Domestic banks and insurance providers underinvest in vernacular customer interfaces, creating demand for Hindi, Tamil, and Marathi neural engines. RBI guidelines on digital banking accessibility push financial institutions toward localized self-service platforms. Mumbai and Bangalore emerge as development centers for low-resource language pair model training.
Switzerland
Life sciences localization providers deploy hybrid solutions combining neural pre-translation with ISO 17100-certified human post-editing. Swissmedic validation requirements for pharmaceutical labeling reinforce quality assurance protocols with audit-ready evidence packages. Basel concentrates specialist vendors serving pharmaceutical headquarters and contract research organizations.
United Kingdom
Legal and financial services firms procure human-augmented systems for notarized documentation requiring certified accuracy. The Financial Conduct Authority's conduct rules impose documentation standards that favor traceable translation workflows for prospectuses and regulatory filings. London's legal district hosts vendors specializing in cross-border litigation support and arbitration documentation.
Language Translation Software Market Key Industry Players
Strategic partnerships dominate the current landscape as vendors integrate neural engine capacity into enterprise content management workflows. The vendor base organizes into three tiers: full-service agencies with geographic delivery networks, cloud-native platforms with marketplace models, and specialized providers with vertical certifications. Two archetypes anchor competitive positioning: scale-driven API providers competing on inference economics, and domain specialists commanding premium pricing for regulated content. M&A activity and technology licensing agreements constitute the primary competitive moves as scale economies favor providers with proprietary training data.
Within the cloud-native tier, Smartcat exemplifies the marketplace model connecting enterprises with vetted linguists while embedding AI pre-translation layers. Lionbridge occupies a position among vertical specialists with deep life sciences and legal localization capabilities where regulatory accuracy requirements sustain premium pricing. TransPerfect anchors the geographic reach archetype, operating delivery infrastructure across more than 100 countries to support round-the-clock project workflows for multinational clients.
| Leading Market Players |
|---|
| Smartcat |
| Transifex |
| Smartling |
| TransPerfect |
| Lionbridge |
| Taia |
| XTM Cloud |
| Lilt |
| Lokalise |
| Others |
Cost & Logistics Intelligence
NVIDIA H100 cloud rental rates cascade through translation software economics, compressing margins for API providers while concentrating pricing power among vendors with captive inference infrastructure and long-term compute contracts.
Pricing Analysis
Volume placements favor per-word transactional models for high-throughput enterprise localization, while margin capture concentrates in hybrid solutions with ISO 17100-certified human post-editing. Price differentiation hinges on regulatory certification grade and vertical specialization depth, with life sciences and legal tiers commanding substantial premiums over general-purpose API access. Pricing pressure intensifies as transformer commoditization erodes per-word rates, forcing vendors toward consumption-based SaaS tiers. Mid-market buyers exhibit acute price sensitivity, whereas pharmaceutical and automotive OEMs prioritize audit-trail transparency over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced GPU fabrication, constraining training capacity for large language models and fragmenting vendor access to inference hardware. The supply chain draws from NVIDIA and AMD for accelerator chips, SK Hynix and Samsung for HBM memory, and TSMC for foundry services. Tariff exposure on semiconductor imports into the European Union and United States threatens cost predictability for cloud-native providers. Distribution runs through hyperscaler marketplaces and direct enterprise API contracts, with regional data centers in Frankfurt, Dublin, and Singapore anchoring latency-sensitive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue proprietary training data pipelines to escape commodity API pricing and establish defensible model differentiation.
For Market Incumbents: Deepen domain-specific model ownership through acquisition of specialized linguistic corpus providers, particularly in life sciences and automotive technical documentation where regulatory accuracy creates switching costs. Lock in multi-year GPU supply agreements with foundry partners to insulate inference economics from semiconductor volatility. Counter emerging cloud-native entrants by embedding quality management systems that generate EU AI Act-compliant audit trails. For New Entrants and Emerging Players: Enter via India's underpenetrated BFSI vernacular localization gap, where domestic banks lack Hindi, Tamil, and Marathi neural engines with RBI-grade compliance documentation. Target mid-market European industrial exporters seeking alternatives to full-service agency contracts by offering metered API access with embedded terminology management. Lead with CSRD sustainability reporting automation as a wedge application with structural demand tailwinds. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized life sciences localization providers with Swissmedic and FDA validation credentials in Switzerland and the eastern United States, where regulatory barriers sustain premium pricing. Long-term viability hinges on model ownership rather than service-layer aggregation. Watch for inflection signals in automotive OEM procurement patterns, where in-house platform builds versus outsourced localization decisions reveal vendor margin compression trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Training Data Acquisition | Captive linguistic corpora from life sciences and legal verticals insulate model differentiation from commodity transformer architectures. |
| GPU Supply Contracting | Long-term NVIDIA H100 reservations with TSMC-affiliated distributors stabilize inference unit economics against foundry capacity constraints. |
| EU AI Act Compliance Architecture | Embedded logging systems documenting model provenance and confidence scoring unlock regulated pharmaceutical and financial document workflows. |
| Vernacular Language Engine Development | Low-resource pair coverage in Hindi, Tamil, and Marathi addresses RBI-mandated digital banking accessibility gaps in Indian BFSI. |
| Real-Time Speech Integration | Convergence of ASR, neural translation, and TTS layers penetrates simultaneous interpretation markets previously reserved for human conference interpreters. |
Research Approach
Independent corroboration across localization procurement officers at German automotive OEMs, cloud infrastructure architects at hyperscaler platforms, and regulatory affairs leads at Swiss life sciences firms underwrites the qualitative findings. Primary fieldwork encompassed structured interviews with computational linguists, enterprise IT directors, and translation vendor executives alongside secondary validation through SEC filings of publicly traded language service providers, EU AI Act implementation guidance documents, and FDA validation requirement memoranda. Bottom-up segment sizing triangulates against top-down market envelope estimates derived from API consumption metrics and enterprise localization spend surveys.
Comparable-period anchoring to historical neural machine translation adoption curves and statistical engine replacement cycles shaped the projection horizon assumptions. The analytical framework models deployment architecture, end-user scale tier, technology stack, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from fitted growth curves calibrated to observed enterprise adoption velocity and cloud API consumption trajectories. Industry-specific inputs include GPU availability constraints from foundry disclosure patterns and ISO 17100 certification penetration rates across pharmaceutical localization workflows.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU AI Act enforcement or sustained semiconductor supply disruption. The projections reflect assumptions regarding transformer architecture commoditization timelines and enterprise unbundling of translation from full-service contracts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Custom Software Development Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Meditation Management Apps Market
Software & Services
Global DevOps Software Market
Software & Services
User Feedback Software Market
Software & Services
Computer Assisted Coding Software Market
Software & Services
Global Data Recovery Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global App Builder Software Market
Software & Services
Self-Storage Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Global Data Integration and Integrity Software Market