
 Computer Assisted Coding Software Market | 2026-2036
Computer Assisted Coding Software Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Assisted Coding Software Market Analysis
The shift from single-source to multi-source vendor strategies is pivoting how health systems procure coding automation. Optum leverages its payer-provider integration to sustain enterprise contracts across integrated delivery networks. Nuance Communications anchors clinical documentation workflows that feed directly into coding engines, reducing manual abstraction. 3M competes on terminology management depth, while Dolbey Systems specializes in speech-driven coding workflows for mid-size hospital markets.
Computer assisted coding software applies natural language processing algorithms to clinical documentation, automatically mapping physician notes to standardized billing codes such as ICD-10-CM and CPT with accuracy thresholds that reduce denial rates. Cloud-based deployment now leads product type adoption as hospitals prioritize scalable infrastructure over capital-intensive on-premise installations. Natural language processing represents the fastest-growing technology segment, displacing rule-based engines that require excessive manual rule maintenance. Machine learning implementations concentrate margin pools among vendors that train models on proprietary clinical datasets spanning multiple health systems.
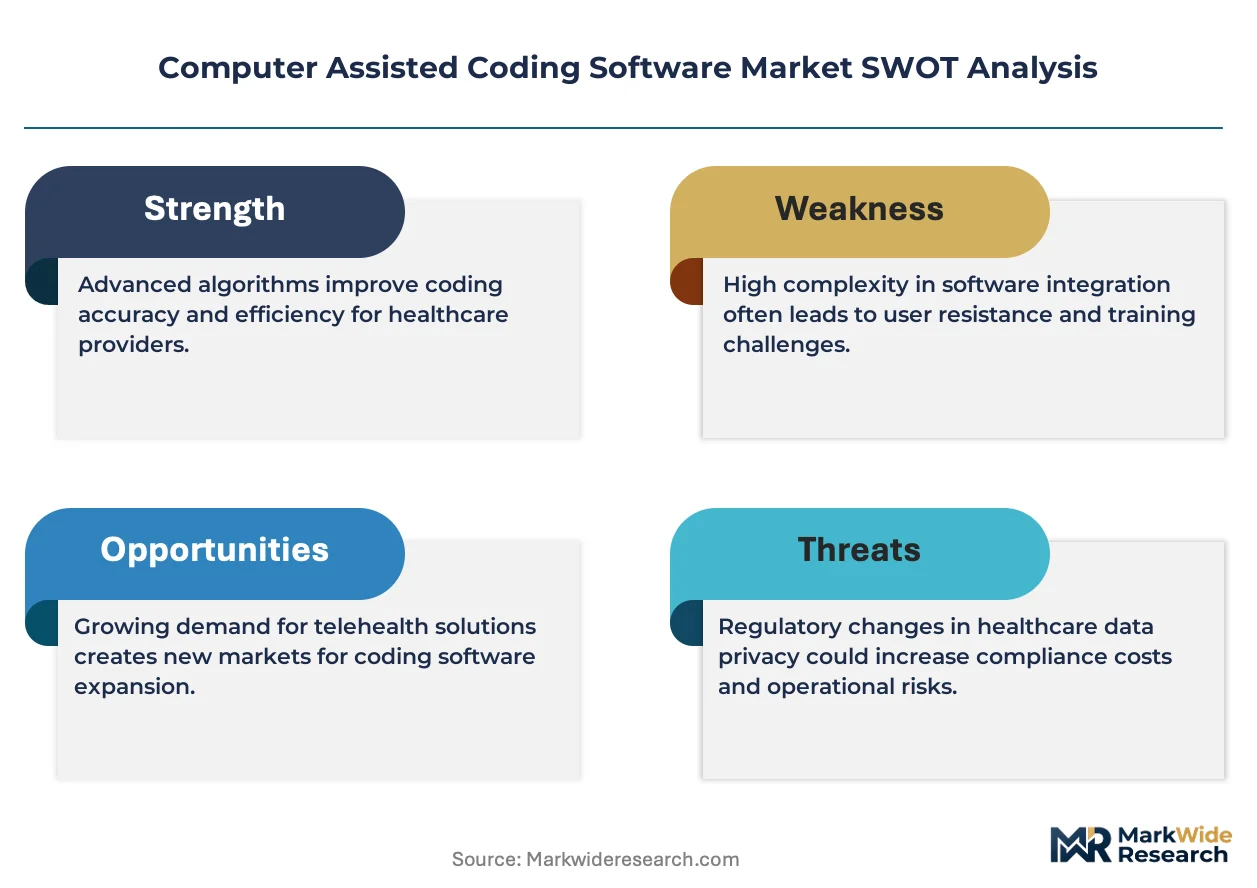
FDA oversight of clinical decision support functions intersects with CMS reimbursement integrity rules to shape product validation requirements and hospital purchasing criteria. HIPAA security standards constrain cloud architecture choices, particularly for public cloud deployments handling protected health information. The EU AI Act and GDPR create parallel compliance burdens for vendors serving European health systems. Stakeholders must monitor how evolving payer audit protocols and coding specificity requirements reshape the technical specifications that determine contract renewals.
Market Dynamics
Natural language processing engines are compressing manual coding workflows across United States hospitals, forcing legacy rule-based systems into accelerated replacement cycles as revenue cycle departments demand real-time code suggestion accuracy.
Growth Catalysts
- CMS Reimbursement Integrity Rules:Audit protocols now mandate coding specificity thresholds that automated platforms satisfy more reliably than manual processes, pulling hospitals toward platform upgrades.
- Cloud Infrastructure Scalability:Health systems prioritize operational flexibility over capital-intensive server farms, accelerating migration to SaaS deployment models that reduce IT maintenance burdens.
- ICD-10-CM Complexity:The expanded diagnosis code set creates abstraction bottlenecks that natural language processing algorithms resolve through automated physician note interpretation.
Market Restraints
- HIPAA Cloud Architecture Constraints:Protected health information handling requirements limit public cloud configurations, forcing hybrid infrastructure investments that extend implementation timelines.
- Proprietary Training Data Concentration:Machine learning model accuracy depends on multi-health-system datasets controlled by established vendors, creating barriers for new market entrants.
- EU AI Act Compliance Burden:European health system deployments face dual GDPR and artificial intelligence validation requirements that fragment product development resources.
Strategic Opportunities
- Mid-Size Hospital Underservice:Community hospitals and regional medical centers lack dedicated clinical documentation improvement staff, creating white space for speech-integrated coding workflows.
- Specialty Clinic Expansion:Ambulatory surgical centers and oncology practices generate complex procedure documentation that automated coding engines can standardize for billing accuracy.
- Interoperability Mandates:CMS-promoted data exchange standards are forcing electronic health record vendors to open application programming interfaces, enabling deeper coding engine integration.
Industry Challenges
- Clinical Informaticist Shortage:Health systems struggle to recruit staff who bridge physician workflow understanding with coding engine configuration expertise.
- Legacy Health Record Integration:Decades-old electronic health record architectures require expensive middleware development to enable real-time natural language processing data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Assisted Coding Software Market |
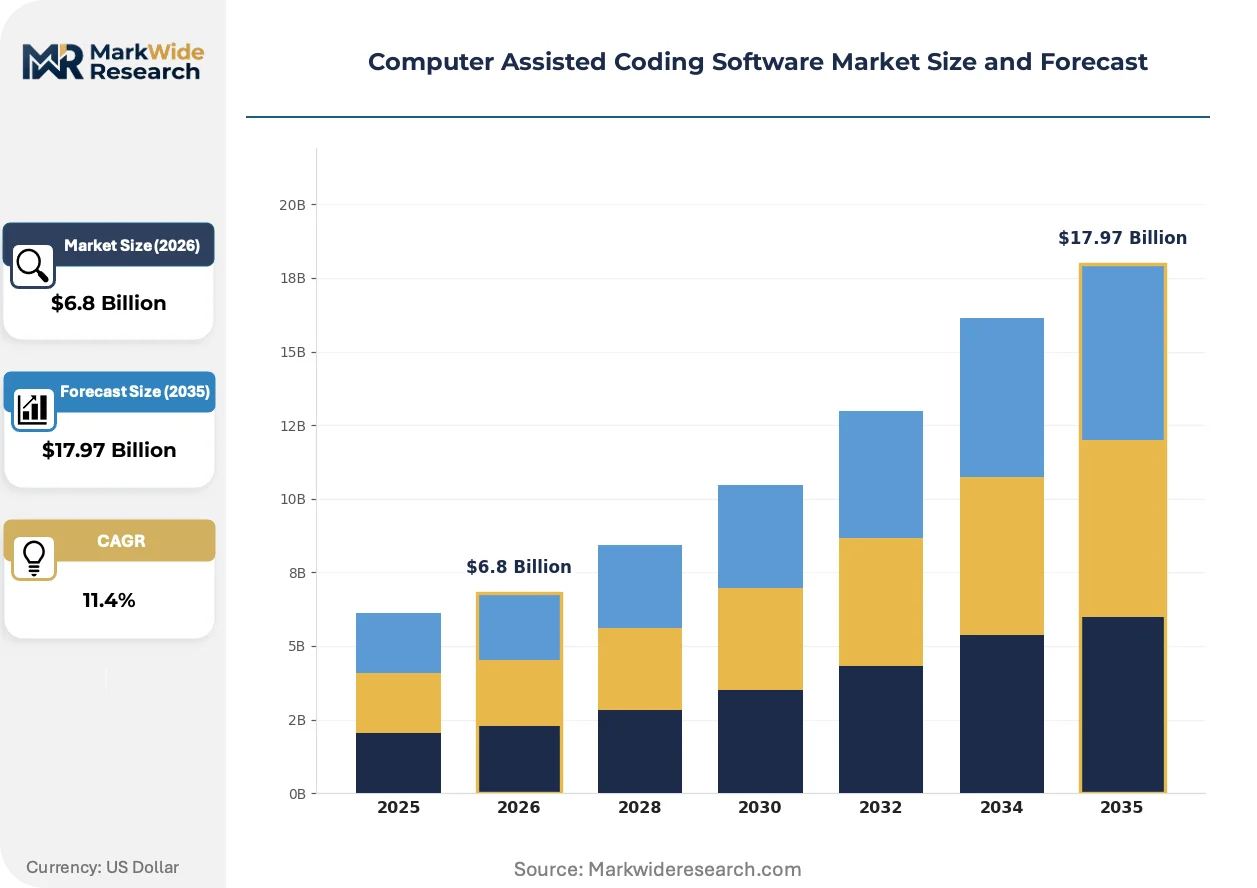
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Software as a Service End User: Hospitals, Clinics, Medical Billing Companies, Health Insurance Providers Technology: Machine Learning, Natural Language Processing, Artificial Intelligence, Rule-Based Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Solventum, Optum, Oracle, AGS Health, Dolbey Systems, R1 RCM, Nuance Communications, 3M, Alpha II, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Assisted Coding Software Market Emerging Trajectories
Automation depth is extending beyond code suggestion into clinical documentation improvement, with vendors competing on physician workflow embedding rather than standalone coding accuracy metrics alone.
Machine learning inference engines are integrating directly into electronic health record interfaces, surfacing ICD-10-CM and CPT suggestions during live note composition rather than post-documentation review. Large health systems in the United States are deploying these embedded workflows across emergency departments and surgical suites where documentation velocity determines revenue capture speed. This integration is compressing the traditional separation between clinical documentation and coding operations into unified revenue cycle workflows.
The EU AI Act risk classification framework is redefining validation requirements for clinical decision support functions that intersect with coding automation, forcing vendors serving European health systems to maintain parallel compliance documentation. Products classified as high-risk artificial intelligence face conformity assessment procedures that extend market entry timelines by twelve to eighteen months. Vendors are responding by segregating European product architectures from United States deployments to isolate regulatory friction.
Hospital purchasing committees are consolidating vendor relationships around integrated platform suites rather than best-of-breed point solutions, privileging vendors that span clinical documentation, coding automation, and revenue analytics. This concentration is displacing standalone coding specialists who lack adjacent workflow tools. The pattern is most visible in United States integrated delivery networks where procurement standardization across member hospitals reduces contract management overhead.
Computer Assisted Coding Software Market Segmentation
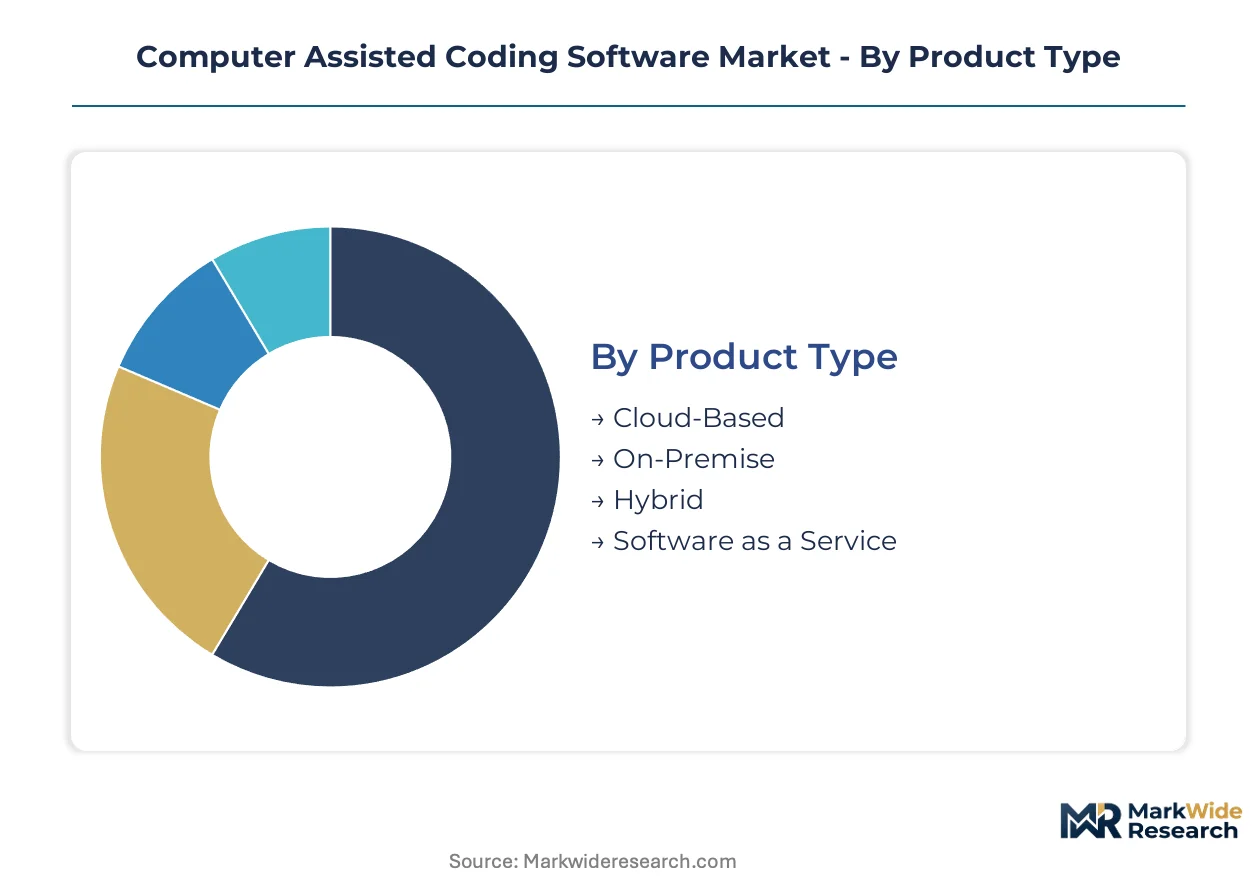
Segmentation in computer assisted coding software reveals how procurement priorities diverge across health system infrastructure constraints and clinical workflow requirements. Understanding these splits enables vendors to align product architectures with specific compliance burdens and integration environments.
Product Type:
Supply concentration in cloud infrastructure is pulling procurement decisions away from capital-intensive ownership models toward operational expenditure frameworks.
- Cloud-Based:Multi-tenant architectures enable health systems to offload server maintenance and security patching to vendor-managed data centers. Large United States health systems with distributed hospital networks are concentrating procurement here to standardize deployments across dozens of facilities without on-site IT expansion.
- Software as a Service:Subscription licensing eliminates upfront capital allocation while embedding automatic regulatory updates. Mid-size community hospitals lacking dedicated revenue cycle IT staff are migrating fastest to this model to access enterprise-grade NLP engines without infrastructure investment.
- On-Premise:Legacy installations persist in health systems with strict data sovereignty requirements or decades-old EHR architectures requiring custom middleware.
- Hybrid:Split configurations process protected health information on-premises while pushing anonymized analytics to cloud environments for model training.
Cloud-Based deployments absorb the bulk of installed capacity; Software as a Service is expanding most quickly.
End User:
Procurement authority is fragmenting across revenue cycle stakeholders with divergent technical requirements and budget ownership structures.
- Hospitals:Acute care facilities generate the highest documentation volume and coding complexity, driving demand for real-time NLP integration into emergency and surgical workflows. United States integrated delivery networks are consolidating vendor contracts across member hospitals to reduce procurement overhead.
- Medical Billing Companies:Third-party revenue cycle specialists process claims across dozens of client health systems, requiring multi-tenant platforms with rapid payer rule updates. These vendors prioritize automated denial prediction and appeal workflow tools over clinical documentation improvement features.
- Clinics:Ambulatory settings generate lower documentation volume but face proportionally higher coder staffing constraints relative to revenue.
- Health Insurance Providers:Payer-side deployment focuses on pre-authorization automation and claims auditing rather than physician workflow integration.
Hospitals command the dominant share of platform deployments; Medical Billing Companies are gaining share fastest as outsourcing accelerates.
Technology:
Model accuracy differentiation is concentrating investment in training data access and inference speed optimization.
- Natural Language Processing:Transformer-based architectures parse unstructured physician notes into structured billing codes with context awareness for clinical specificity. United States vendors with multi-health-system training datasets are pulling ahead on accuracy benchmarks for complex surgical documentation.
- Machine Learning:Supervised learning models improve suggestion relevance through continuous feedback from coder acceptance and correction patterns. These implementations require substantial proprietary clinical data pipelines that entrench established vendors against new entrants.
- Artificial Intelligence:Broader AI frameworks encompass NLP and ML while adding clinical decision support intersections that trigger FDA oversight.
- Rule-Based:Legacy deterministic engines require manual rule maintenance for each payer policy update and are entering replacement cycles.
Natural Language Processing anchors current revenue; Machine Learning is climbing the fastest as feedback loops sharpen model performance.
Deployment:
Infrastructure configuration choices directly determine HIPAA compliance architecture and implementation timeline constraints.
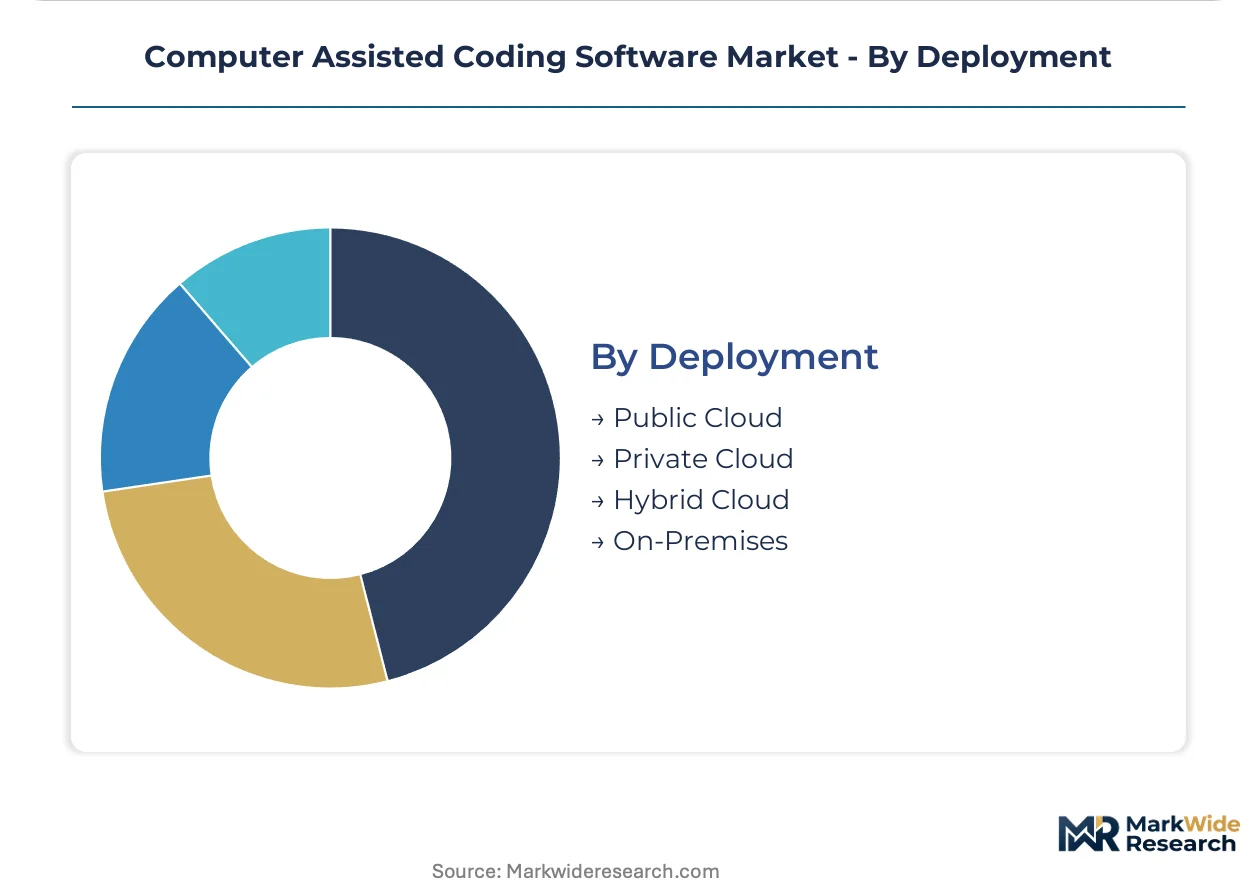
- Private Cloud:Single-tenant environments isolate protected health information within health system-controlled boundaries while retaining vendor-managed infrastructure. Large United States health systems with dedicated security operations centers are standardizing on this model to satisfy internal risk committees.
- Hybrid Cloud:Segregated workloads process PHI in private environments while leveraging public cloud compute for non-sensitive analytics. This architecture extends implementation timelines but satisfies compliance officers demanding data residency controls.
- Public Cloud:Shared infrastructure delivers lowest cost per transaction but faces HIPAA business associate agreement complexity and limited adoption for PHI-heavy workflows.
- On-Premises:Fully client-controlled installations persist in health systems with legacy EHR architectures incompatible with external data feeds.
Private Cloud carries the majority of new deployments; Hybrid Cloud is gaining share fastest as compliance and flexibility requirements converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems command the dominant share of computer assisted coding software procurement, with large integrated delivery networks consolidating vendor contracts across dozens of member hospitals to reduce procurement overhead and standardize revenue cycle operations.
United States
CMS reimbursement integrity rules and ICD-10-CM complexity drive hospital procurement of NLP-enabled coding platforms. HIPAA security standards constrain cloud architecture choices for protected health information handling. Major health systems in Texas and California are consolidating vendor relationships around integrated clinical documentation improvement tools.
Germany
Hospital digitization programs and statutory health insurance billing reform accelerate automated coding adoption. The EU AI Act risk classification framework imposes conformity assessment procedures on clinical decision support functions. Healthcare clusters in Bavaria and North Rhine-Westphalia are deploying cloud-based coding engines to streamline reimbursement workflows.
United Kingdom
NHS efficiency targets and coding backlogs push trusts toward automated abstraction platforms. GDPR requirements intersect with NHS data security standards to shape vendor selection criteria. London and Greater Manchester hospital networks are piloting real-time NLP integration into electronic health record systems.
Japan
Aging demographics and medical coder workforce shortages create automation urgency in acute care facilities. METI digital health initiatives promote AI adoption in clinical documentation workflows. Hospital clusters in Tokyo and Osaka are implementing speech-driven coding interfaces to reduce manual abstraction burdens.
India
Medical tourism revenue cycle demands and health insurance expansion drive coding accuracy investments. CDSCO oversight of clinical decision support software shapes product validation requirements. Healthcare IT hubs in Bengaluru and Hyderabad are developing export-oriented coding automation platforms for international hospital clients.
Computer Assisted Coding Software Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors integrate coding engines with electronic health record workflows and revenue cycle management suites. The vendor base clusters around three archetypes: enterprise platform consolidators spanning documentation-to-billing workflows, specialized NLP engine developers licensing technology to health IT suites, and mid-market specialists targeting community hospital speech-coding integration. Competitive positioning hinges on proprietary clinical dataset access for machine learning training and regulatory compliance architecture spanning FDA, HIPAA, and EU AI Act requirements.
Within the enterprise platform tier, Optum and Nuance Communications anchor integrated delivery network procurement decisions through adjacent workflow tool penetration. Oracle represents the cloud infrastructure consolidator archetype, leveraging database and analytics assets to bundle coding automation with broader health IT modernization contracts. 3M occupies a position in terminology management depth, competing on medical coding standard authority rather than front-end physician workflow embedding.
| Leading Market Players |
|---|
| Solventum |
| Optum |
| Oracle |
| AGS Health |
| Dolbey Systems |
| R1 RCM |
| Nuance Communications |
| 3M |
| Alpha II |
| Others |
Supply Flow & Price Mechanics
Hospital procurement committee consolidation around integrated platform suites is compressing vendor margins and forcing supply-side specialization into narrower technical domains. United States integrated delivery networks now demand bundled clinical documentation-to-coding workflows, compelling standalone engine developers to embed within larger health IT ecosystems or accept royalty-based licensing terms that erode pricing autonomy.
Pricing Analysis
Volume concentration among large health systems splits the market into enterprise subscription contracts and per-seat SaaS arrangements for mid-size facilities. Three-tier pricing structure across premium, standard, and economy levels reflects NLP engine accuracy thresholds and EHR integration depth. Cost compression in the standard tier is intensifying because cloud infrastructure commoditization has eliminated server maintenance differentiation. Medical billing companies exhibit highest price sensitivity due to thin claim processing margins, while academic medical centers prioritize accuracy benchmarks over per-transaction costs.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital risk committees mandate qualified backup vendors for critical revenue cycle functions, fragmenting procurement across multiple NLP engine providers. Supply concentrates in the United States for proprietary clinical training datasets, India for medical coding labor arbitrage in training data annotation, and Ireland for European cloud hosting to satisfy GDPR data residency. Raw material dependencies span GPU compute capacity from NVIDIA-dominated foundries, annotated clinical corpora from health system partnerships, and open-source transformer architectures from academic research institutions. Single-source vulnerability in specialized medical terminology ontologies creates concentration risk. Distribution runs through direct enterprise sales teams for large health systems and channel partnerships with EHR vendors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computer assisted coding software is consolidating toward platform suites as hospital procurement standardization and machine learning data requirements squeeze standalone specialists. HIPAA compliance architecture costs and proprietary training data access are forcing weaker vendors into acquisition or exit.
For Market Incumbents: Anticipate FDA oversight expansion into clinical decision support functions that intersect with coding automation by segregating product architectures for United States and European deployments. Deepen vertical integration into clinical documentation improvement tools to defend against EHR-native coding modules from Epic and Cerner. Proprietary multi-health-system training datasets remain the critical lever for model accuracy differentiation. For New Entrants and Emerging Players: The price-point gap between premium NLP engines and economy rule-based systems creates entry space for speech-integrated coding workflows targeting community hospitals with limited clinical documentation improvement staff. Target ambulatory surgical centers and oncology practices where complex procedure documentation generates billing accuracy pain points. A channel partnership strategy with regional EHR implementers bypasses direct procurement committee barriers. For Investors and Strategic Acquirers: The window for entry favors vendors with HIPAA-compliant cloud architectures and existing health system training data partnerships. Mid-stage specialists with speech recognition-coding integration and 50-200 hospital client bases represent optimal acquisition profiles. Watch CMS audit protocol changes tightening coding specificity requirements as the signal for accelerated platform replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding NLP engines directly into Epic and Cerner workflows captures physician documentation velocity. |
| Strategic Partnership | Alliances with medical billing companies extend reach into outsourced revenue cycle operations. |
| Acquisition of Specialist Firm | Buying speech recognition vendors adds voice-driven coding capabilities for surgical documentation. |
| Geographic Expansion | EU AI Act compliance investments open German and UK hospital procurement channels. |
| Product Launch | Real-time ICD-10-CM suggestion modules during live note composition differentiate from post-review tools. |
Methodological Framework
Document review covered FDA 510(k) filings for clinical decision support software, CMS Medicare claims data, and health system procurement databases, complemented by interviews with revenue cycle executives, clinical documentation improvement directors, health IT procurement officers, and biomedical informaticists. Secondary validation drew from hospital GPO contracts, EHR vendor partnership announcements, and EU AI Act implementation guidance. Bottom-up sizing triangulated vendor-reported hospital client counts against average contract values, while top-down validation cross-checked against total addressable hospital expenditure on revenue cycle automation.
Segment-level projections across deployment models, end-user categories, and technology types were generated through a structured analytical framework. The modeling period incorporated NLP engine adoption curves, cloud infrastructure migration patterns, and ICD-10-CM code set expansion impacts. CAGRs were derived from regression analysis of historical platform replacement cycles and health system IT budget allocation trends. Key forecast inputs included CMS reimbursement integrity rule enforcement intensity and medical coder workforce shortage projections from Bureau of Labor Statistics data.
Inputs from health system procurement databases and vendor client disclosures were available through the study window; gaps in private cloud infrastructure cost structures and proprietary training data valuation introduce uncertainty bands around SaaS pricing trajectory assumptions. Deviation in FDA clinical decision support enforcement timelines or CMS audit protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software License Management (SLM) Market
Software & Services
CAM Software Market
Software & Services
Taxi Booking Software Market
Software & Services
Global Electronic Dictionary Market
Software & Services
Global Home Inspection Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Virtual Fitting Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Global MSP Software Market
Software & Services
Mobile Speech Recognition Software Market
Software & Services
Credit Management Software Market
Software & Services
Data Compression Software Market
Software & Services
Software Market
Software & Services
Computer Engineering Market
Software & Services
Consignment Software Market
Software & Services
UI Design Software Market