
 Meditation Management Apps Market | 2026-2036
Meditation Management Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Meditation Management Apps Market Analytics
Subscription renewal revenue is narrowing as a dependable margin pool as users churn between platforms and freemium alternatives proliferate. Calm leverages its content library depth and celebrity partnerships to sustain premium pricing power across English-speaking markets. Headspace Inc. anchors its position through corporate wellness contracts with Fortune 500 employers, competing directly against traditional employee assistance programs. Insight Timer differentiates through its community-driven model, offering free access to thousands of guided sessions while monetizing teacher subscriptions and live events.
Meditation management apps constitute software platforms that deliver structured mindfulness protocols through audio, visual, and haptic interfaces, typically incorporating session timers, progress tracking, and biometric feedback loops to modulate user experience. Their primary commercial purpose centers on reducing measurable stress markers and improving attention regulation for individual consumers, healthcare systems, and organizational clients. Guided meditation and sleep aid content categories now command the largest subscriber bases, while wearable integration represents the fastest-expanding technology segment as Apple Watch and Oura Ring APIs enable real-time heart rate variability feedback. Corporate wellness delivery models are maturing fastest, though freemium user-to-paid conversion remains the dominant margin pool for platform economics.
The Federal Trade Commission scrutinizes health claims in digital wellness advertising, while the FDA exercises oversight when apps cross into regulated medical device territory for anxiety or insomnia treatment. GDPR and the EU AI Act impose strict limits on emotion recognition algorithms and biometric data processing, directly constraining product feature development for European deployments. Stakeholders must monitor evolving digital therapeutics classification criteria, as reclassification could trigger premarket review requirements and reshape competitive barriers across major jurisdictions.
Market Dynamics
Corporate wellness procurement is concentrating buying power into multi-year platform contracts, compressing margins for standalone consumer subscriptions while elevating biometric-integrated solutions that satisfy HIPAA compliance requirements for employer health data handling.
Growth Catalysts
- Employer wellness mandates:Fortune 500 benefits administrators now require mental health tool integration within existing HRIS platforms, creating pull-through demand for enterprise-grade meditation APIs.
- Wearable ecosystem expansion:Apple Watch and Oura Ring heart rate variability APIs enable real-time biofeedback loops that demonstrably improve session completion rates.
- GDPR Article 9 clarity:EU health data processing guidelines have stabilized, allowing developers to deploy emotion recognition features with compliant consent architectures.
Market Restraints
- Cloud infrastructure concentration:AWS and Azure dominance in healthcare-compliant hosting creates single-point vulnerability for biometric data storage across mid-tier platforms.
- FDA device classification uncertainty:Anxiety treatment claims trigger premarket review requirements, freezing feature development for therapeutic-positioned apps.
- Freemium substitution saturation:YouTube and podcast platforms deliver comparable guided content without subscription friction, eroding willingness-to-pay among price-sensitive cohorts.
Strategic Opportunities
- Germany corporate wellness gap:Works councils mandate mental health provisions under Betriebsräte agreements, yet platform penetration lags US benchmarks by several years.
- Dual-use therapeutic positioning:Prescription digital therapeutics pathways through FDA 510(k) clearance enable reimbursement eligibility and provider prescribing workflows.
- Voice-first interface convergence:Alexa and Google Assistant native integrations remove friction for bedside sleep aid usage, capturing ambient computing moments.
Industry Challenges
- Clinical validation talent scarcity:Randomized controlled trial design expertise for digital health outcomes remains concentrated among academic medical center spinouts.
- Cross-border data residency complexity:Schrems II rulings invalidate Privacy Shield alternatives, forcing costly EU-US data architecture bifurcation.
- Content licensing fragmentation:Teacher-owned intellectual property requires per-session royalty structures that resist platform-scale economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meditation Management Apps Market |
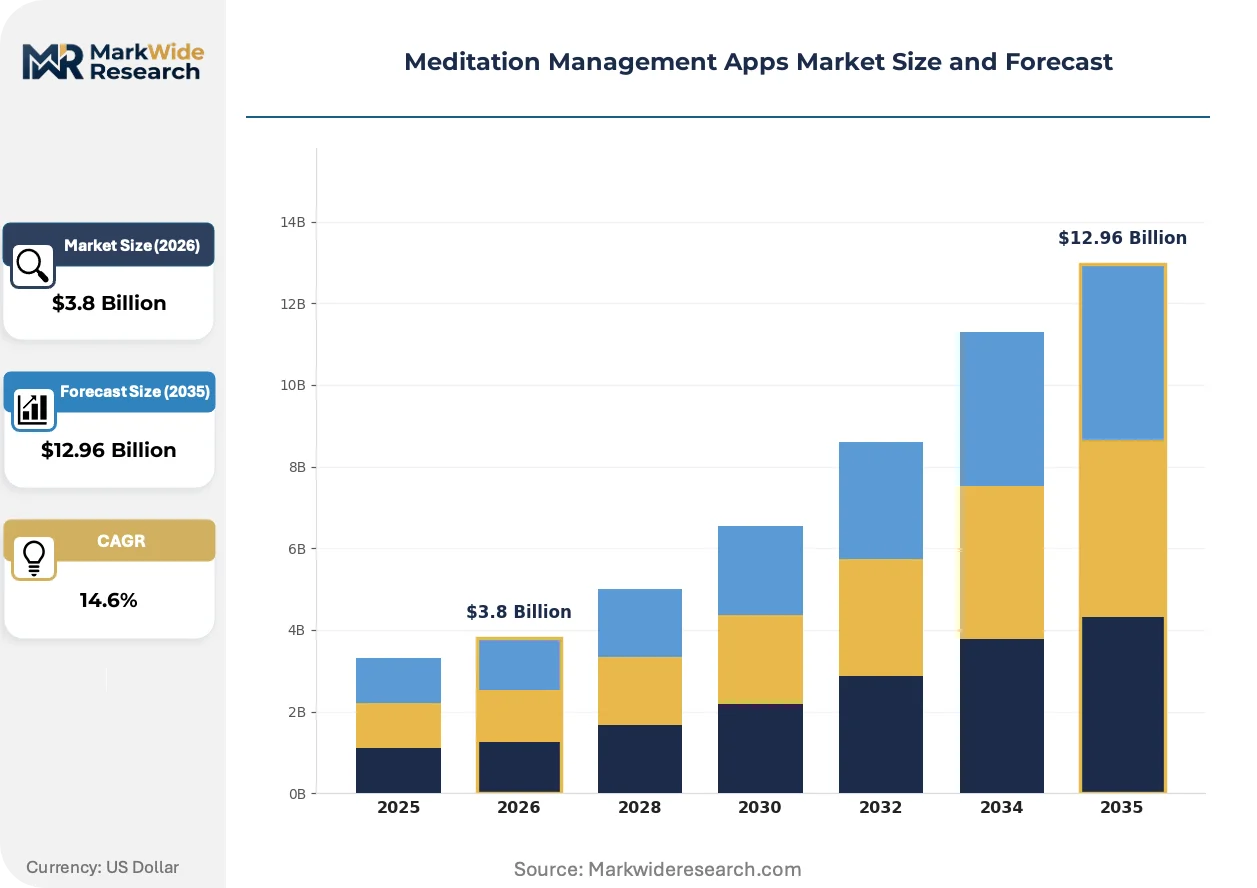
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guided Meditation, Timer-Based, Sleep Aid, Mindfulness Technology: Mobile Apps, Wearable Integration, Virtual Reality, Audio Streaming Delivery Model: Subscription-Based, Freemium, One-Time Purchase, Corporate Wellness User Type: Individuals, Health Professionals, Corporates, Schools |
| Companies Covered | Calm, Headspace Inc., Insight Timer, Simple Habit, Breethe, Aura Health, Ten Percent Happier, Meditopia, InnerExplorer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meditation Management Apps Market Evolving Landscape
Biometric feedback loops are merging with generative audio to create adaptive meditation experiences that respond to physiological state rather than following fixed scripts, fundamentally altering content production economics.
Heart rate variability sensors embedded in wearables now stream continuous autonomic nervous system data to meditation platforms. Corporate wellness buyers prioritize these integrations for measurable stress reduction claims. The technology is hybridizing content delivery with physiological state detection, collapsing the distinction between guided instruction and biofeedback therapy.
The EU AI Act emotion recognition prohibitions for workplace surveillance are forcing developers to rearchitect employer-facing dashboards. Systems must now aggregate anonymized cohort data rather than individual emotional state tracking. European deployments face the strictest constraints, with vendors stripping biometric identifiers before cloud transmission.
Subscription fatigue is compressing consumer willingness to maintain multiple wellness apps simultaneously. Users consolidate spending into single platforms with broad content libraries. This behavioral shift concentrates revenue among established players with celebrity content partnerships, squeezing niche providers dependent on specialized meditation traditions.
Meditation Management Apps Market Segmentation
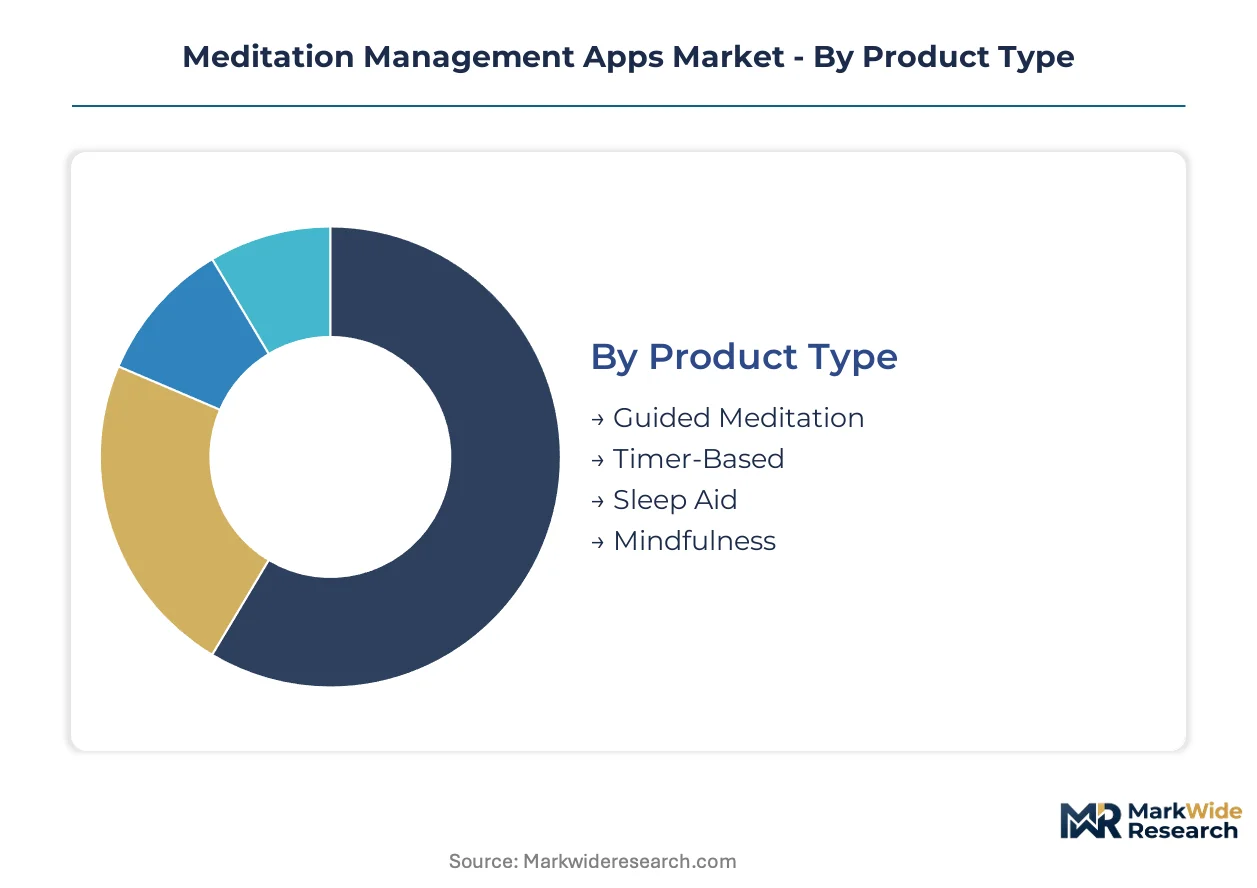
Meditation management apps fragment across four intersecting dimensions that determine monetization mechanics and user retention profiles. Product type governs content production costs, while delivery model shapes customer lifetime value calculations for platform economics.
Product Type:
User needs span from structured instruction to ambient sleep support, with content format driving engagement depth and subscription stickiness.
- Guided Meditation:Narrated sessions led by instructors through breathing exercises, body scans, and visualization protocols. Corporate wellness contracts in the United States prioritize this format for measurable stress reduction programs.
- Sleep Aid:Ambient soundscapes, sleep stories, and wind-down narratives designed for bedtime usage. Bedroom-integrated smart speakers and Oura Ring data streams are accelerating adoption for this segment.
- Timer-Based:Minimalist interval bells and session clocks without instructional content. Experienced practitioners favor this stripped-down approach.
- Mindfulness:Present-moment awareness exercises drawn from contemplative traditions. Healthcare systems integrate these protocols into pain management and anxiety treatment pathways.
The dominant share belongs to Guided Meditation, while Sleep Aid is closing the gap fastest.
Technology:
Interface modality determines data capture potential and hardware ecosystem lock-in for platform vendors.
- Wearable Integration:Apple Watch and Oura Ring APIs stream heart rate variability data to modulate session intensity in real time. Employer wellness budgets are concentrating procurement on biometric-validated solutions.
- Mobile Apps:Native iOS and Android applications delivering audio content through headphone or speaker output. Consumer subscription revenue still concentrates here despite feature saturation.
- Virtual Reality:Immersive environments for guided practice using Meta Quest and Apple Vision Pro headsets. Hardware penetration limits addressable market.
- Audio Streaming:Platform-agnostic content delivery through Spotify, Apple Music, and dedicated podcast feeds. Freemium substitution pressure is most acute in this channel.
Wearable Integration commands premium pricing, though Mobile Apps retain the widest user base.
Delivery Model:
Revenue architecture separates consumer discretionary spending from institutional procurement with divergent margin profiles.
- Corporate Wellness:Enterprise licenses integrated into HRIS platforms and employee assistance programs. Multi-year contracts with Fortune 500 employers are displacing standalone consumer subscriptions as the primary growth vector.
- Freemium:Base content access supported by advertising and premium tier upsells. YouTube and podcast platform competition is compressing conversion rates.
- Subscription-Based:Recurring monthly or annual fees for full content library access. Churn between platforms is eroding lifetime value assumptions.
- One-Time Purchase:Perpetual licenses for specific content packs or lifetime memberships. This model resists recurring revenue economics.
Corporate Wellness is expanding most quickly, while Subscription-Based retains revenue concentration.
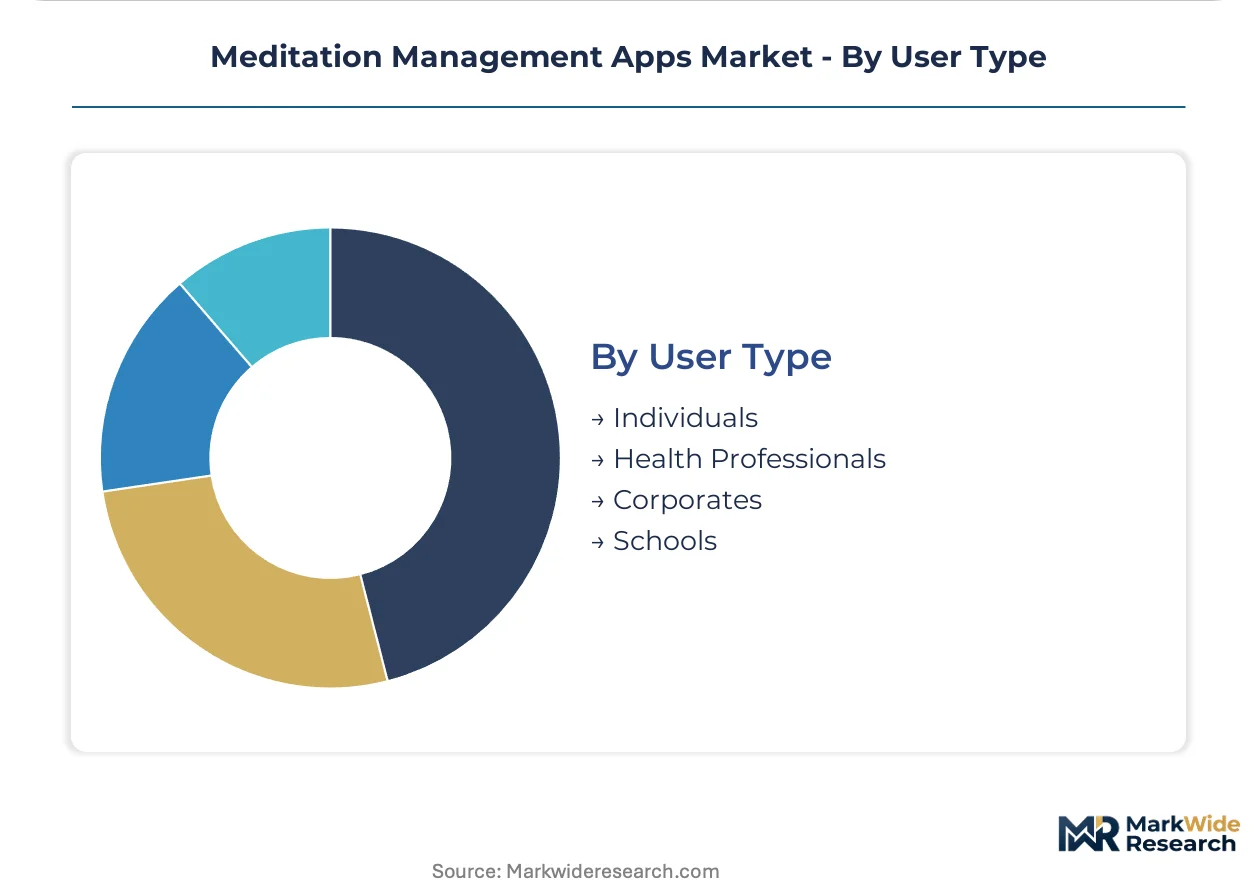
User Type:
End-user identity shapes compliance requirements, pricing tolerance, and content customization needs.
- Corporates:HR departments procuring mental health benefits for workforce populations. HIPAA compliance and aggregate reporting capabilities are non-negotiable procurement criteria.
- Individuals:Direct-to-consumer subscribers seeking personal stress management tools. Price sensitivity and platform switching dominate this cohort.
- Health Professionals:Clinicians prescribing meditation as adjunct therapy for anxiety, insomnia, and chronic pain. FDA digital therapeutics classification would unlock reimbursement pathways.
- Schools:K-12 and university administrators integrating mindfulness into student services. COPPA compliance and parental consent architectures constrain product design.
Corporates drive contract value, though Individuals still represent the largest addressable population.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates employer-sponsored wellness procurement, while Germany and Japan exhibit divergent adoption patterns shaped by works council mandates and aging demographics respectively.
United States
Fortune 500 benefits administrators drive enterprise contract volume through HRIS-integrated mental health platforms. The FTC exercises oversight on health claims in digital wellness advertising, constraining therapeutic positioning. Silicon Valley and New York City host the densest concentration of platform developers competing for corporate wellness budgets.
Germany
Works councils mandate mental health provisions under Betriebsräte agreements, creating structural demand for compliant workplace solutions. GDPR Article 9 health data processing guidelines require emotion recognition features to deploy with explicit consent architectures. Berlin and Munich emerge as corporate wellness platform penetration lags US benchmarks by several years.
United Kingdom
NHS digital therapeutics procurement pathways create reimbursement eligibility for clinically validated anxiety and insomnia applications. The UK Information Commissioner's Office enforces GDPR biometric data limits on workplace surveillance deployments. London anchors health technology venture capital concentration for meditation platform scaling.
Japan
Corporate stress management tool adoption accelerates among manufacturers addressing workforce aging and productivity metrics. METI guidelines on workplace mental health promotion shape employer procurement specifications. Tokyo and Osaka metropolitan areas concentrate platform localization efforts for Japanese-language content libraries.
Australia
Private health insurance rebate eligibility for mental health applications drives consumer subscription uptake in urban markets. The Therapeutic Goods Administration evaluates digital therapeutics classification for anxiety treatment claims. Sydney and Melbourne host regional headquarters for Asia-Pacific platform expansion strategies.
Meditation Management Apps Market Competitive Landscape
Capability concentration sits with content production specialists; scale advantage sits with platform-integrated wellness providers. The market structures around three tiers: celebrity-content aggregators, corporate wellness contractors, and community-driven freemium platforms. Strategic moves concentrate on biometric API integrations and enterprise HRIS partnerships.
Within the content-library tier, Calm and Headspace Inc. exemplify divergent monetization architectures. Calm represents premium consumer subscription positioning through audio depth and entertainment partnerships. Headspace Inc. anchors corporate wellness contract procurement with HIPAA-compliant employer solutions. Insight Timer occupies a community-driven position, monetizing teacher subscriptions rather than end-user fees.
| Leading Market Players |
|---|
| Calm |
| Headspace Inc. |
| Insight Timer |
| Simple Habit |
| Breethe |
| Aura Health |
| Ten Percent Happier |
| Meditopia |
| InnerExplorer |
| Others |
Value Network & Pricing Analysis
Single-source dependency on AWS and Azure for HIPAA-compliant hosting infrastructure determines both premium tier spreads and supply chain resilience architecture across meditation management platforms.
Pricing Analysis
Long-term enterprise contracts with Fortune 500 employers anchor the highest pricing tier, while freemium consumer subscriptions face compression from YouTube and podcast substitution. Three-tier pricing structure across premium, standard, and economy levels separates biometric-integrated corporate solutions from basic mobile app access and ad-supported content libraries. Pricing pressure stems from content licensing fragmentation requiring per-session royalty payments to teacher-owned intellectual property. Individual consumers exhibit the greatest price sensitivity, whereas corporate wellness buyers prioritize HIPAA compliance and aggregate reporting capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China for consumer electronics components constrains wearable hardware cost structures for biometric-integrated platforms. Cloud infrastructure concentrates in the United States through AWS and Azure, while content production studios span the United States, United Kingdom, and Australia for English-language talent pools. Raw material dependencies include semiconductor chips for wearable sensors, lithium-ion batteries for device power, and licensed audio compression codecs. Distribution runs through mobile app stores, direct enterprise sales teams, and HRIS platform integrations for corporate wellness procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's emotion recognition prohibitions for workplace surveillance constitute a regulatory inflection that will bifurcate product architectures between European and non-European deployments.
For Market Incumbents: Harden enterprise contract retention by deepening HRIS platform integrations and accelerating biometric API partnerships with Apple Watch and Oura Ring. Invest in FDA 510(k) clearance pathways for prescription digital therapeutics positioning against emerging clinical validation competitors. Prioritize GDPR Article 9 compliant consent architectures to preempt enforcement actions from EU data protection authorities. For New Entrants and Emerging Players: Mid-market German employers under Betriebsräte works council mandates represent the most penetrable entry point for corporate wellness platform penetration lagging US benchmarks. Voice-first sleep aid integrations for Alexa and Google Assistant native deployments capture ambient computing moments with minimal content library investment. Pursue teacher subscription monetization models rather than consumer freemium conversion to bypass established platform content depth advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with clinical validation infrastructure and enterprise distribution density. Five-to-ten year viability hinges on reimbursement pathway establishment through FDA digital therapeutics classification and NHS procurement eligibility. Monitor FDA premarket review determinations for anxiety treatment claims as the critical signal for therapeutic-positioned platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric API Integration | Oura Ring and Apple Watch partnerships validate measurable stress reduction claims for corporate wellness buyers. |
| FDA 510(k) Clearance Pathway | Premarket review unlocks prescription digital therapeutics reimbursement and provider prescribing workflows. |
| GDPR Article 9 Compliance Architecture | Explicit consent frameworks enable emotion recognition feature deployment in European workplace deployments. |
| HRIS Platform Partnership | Integration with Workday and SAP SuccessFactors streamlines Fortune 500 procurement and deployment workflows. |
| Voice-First Interface Development | Alexa and Google Assistant native integrations capture bedside sleep aid usage in ambient computing environments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with corporate wellness benefits administrators, meditation platform product managers, digital health regulatory consultants, and wearable device ecosystem partners. Secondary validation drew from FDA 510(k) submission databases, EU AI Act implementation guidance, App Store and Google Play revenue estimates, and corporate wellness procurement disclosures. Bottom-up segment sizing triangulated against top-down market value reconstructions across product type, technology, delivery model, and user type dimensions.
Calibration against historical subscription renewal rates and corporate contract expansion patterns anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated deployment architecture, organization size, content format, biometric integration depth, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation moderated by adoption ceiling estimates and competitive displacement dynamics. Forecast inputs included employer wellness budget growth rates, wearable hardware penetration curves, and digital therapeutics reimbursement pathway progression.
Practitioners should monitor FDA device classification determinations, Schrems II data residency ruling evolution, and corporate wellness procurement standardization for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
File Analysis Software Market
Software & Services
Global ITSM Software Market
Software & Services
Stock Control Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
POS Software Market
Software & Services
Global Recruiting Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
House Cleaning App Market
Software & Services
Global Decision Support Software Market
Software & Services
Category Management Software Market
Software & Services
Application Virtualization Market
Software & Services
Global App Store Optimization Software Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Streaming Server Software Market
Software & Services
Europe HR Payroll Software Market
Software & Services
3D Animation Software Market