
 Entity Management Software Market | 2026-2036
Entity Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Entity Management Software Market Insights
ISO 27001 certification is reorganizing competitive entry in entity management software, as enterprise procurement teams mandate audited information security management systems before vendor qualification. Thomson Reuters ONESOURCE leverages its regulatory content heritage to anchor compliance workflows across Fortune 500 legal departments. TMF Group sustains geographic dominance through localized entity administration capabilities spanning over 80 jurisdictions. Athennian specializes in cloud-native architecture designed for law firms managing high volumes of subsidiary governance data.
Entity management software comprises digital platforms that centralize corporate record maintenance, registered agent coordination, beneficial ownership tracking, and jurisdictional filing deadlines through automated workflow engines and document repositories. These systems integrate statutory calendar calculations, e-signature capture, and audit trail generation to reduce administrative burden and penalty exposure for legal and compliance teams. Cloud-Based deployment leads segment momentum as multi-tenant architectures reduce infrastructure overhead for mid-market legal departments. Single-Tenant configurations retain margin strength among financial services clients with data residency restrictions. The Legal vertical anchors industry demand, though Healthcare compliance teams are expanding procurement as state-level reporting obligations proliferate.
SEC disclosure rules, GDPR data governance standards, and state corporate registry requirements collectively shape product roadmaps and client retention dynamics in this sector. The SEC's beneficial ownership reporting mandates under the Corporate Transparency Act compel platform enhancements for beneficial ownership information collection and submission workflows. Stakeholders must monitor evolving state-level registered agent regulations and cross-border data transfer restrictions to anticipate platform interoperability investments.
Market Dynamics
Cloud migration is compressing deployment cycles for entity management platforms as legal departments abandon on-premise infrastructure to meet ISO 27001 audit requirements and reduce capital expenditure exposure.
Growth Catalysts
- Corporate Transparency Act mandates:SEC beneficial ownership reporting rules compel Fortune 500 legal teams to automate entity data collection workflows or face penalty exposure.
- Healthcare vertical expansion:State-level reporting obligations for physician practice entities and hospital subsidiaries drive procurement from compliance teams managing multi-jurisdictional registrations.
- GDPR cross-border data governance:European data residency requirements accelerate platform investments for US-based multinationals maintaining EU subsidiary records.
Market Restraints
- Data residency compliance costs:Single-tenant configurations for financial services clients with jurisdiction-specific storage mandates inflate infrastructure expenditure by 40-60% versus multi-tenant alternatives.
- Concentrated cloud infrastructure dependency:AWS, Microsoft Azure, and Google Cloud dominate hosting options, creating vendor lock-in risk for mid-market legal departments.
- Legacy system integration friction:Decades-old corporate record databases in established enterprises resist API connectivity, extending implementation timelines.
Strategic Opportunities
- Private equity portfolio company penetration:Buyout firms managing hundreds of special purpose vehicles per fund require automated subsidiary governance tools underserved by current vendor configurations.
- AI-powered document extraction:Natural language processing convergence with optical character recognition is enabling automated parsing of historical minute books and shareholder agreements.
- India market entry:Ministry of Corporate Affairs digitization initiatives and ROC compliance automation create whitespace for cloud-native platform providers.
Industry Challenges
- Cybersecurity certification timelines:ISO 27001 audit preparation consumes 12-18 months for emerging vendors, delaying enterprise procurement qualification.
- Entity data standardization gaps:Inconsistent state registry formats across Delaware, Nevada, and Wyoming impede automated filing workflow development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Entity Management Software Market |
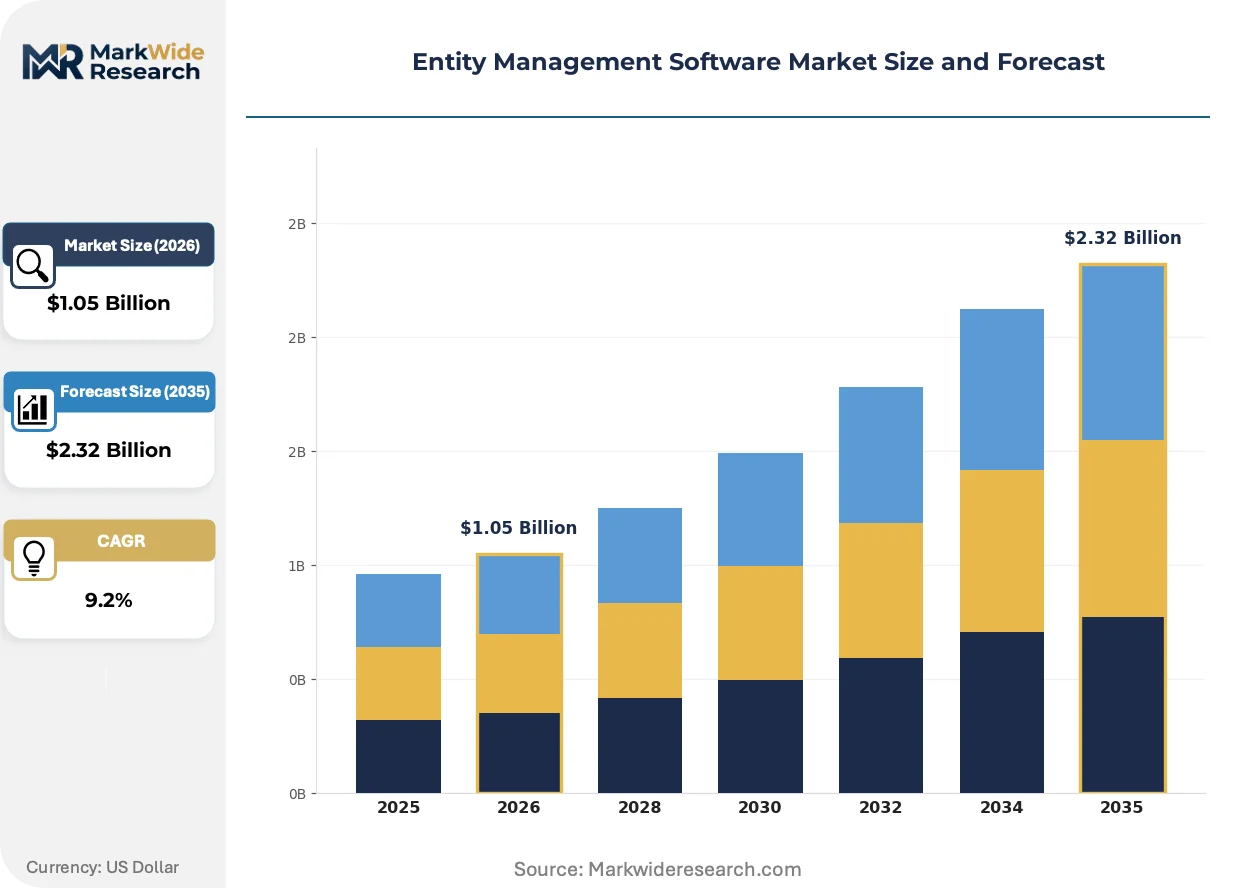
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Hybrid, SaaS Deployment: Single-Tenant, Multi-Tenant, Private Cloud, Public Cloud End User: Corporations, Non-Profits, Startups, Enterprises Industry Vertical: Legal, Finance, Healthcare, Real Estate |
| Companies Covered | Thomson Reuters ONESOURCE, TMF Group, Athennian, Filejet, CSC (Corporation Service Company), Diligent Entities, Vistra, CorpNet, CT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Entity Management Software Market Trends and Innovations
Artificial intelligence and machine learning capabilities are reconfiguring how corporate legal teams interact with entity data, shifting competitive advantage toward platforms with native document intelligence rather than bolt-on features.
Natural language processing engines trained on corporate governance documents are displacing manual data entry workflows for subsidiary maintenance. Mid-market law firms with 50-200 active entities are adopting these tools fastest, compressing administrative hours per filing by 60-70% and enabling leaner legal operations staffing models.
CSRD sustainability reporting mandates in Europe are extending entity management platform scope beyond traditional corporate records. The directive requires granular subsidiary-level emissions and governance disclosures, forcing vendors to integrate ESG data modules or lose continental European financial services clients to compliance-focused competitors.
Subscription pricing with usage-based tiers is replacing perpetual license models for cloud deployments. Legal departments at technology companies with volatile entity counts prefer consumption-aligned contracts, while established manufacturing enterprises with stable subsidiary portfolios resist the shift, creating a bifurcated vendor landscape across buyer segments.
Entity Management Software Market Segmentation
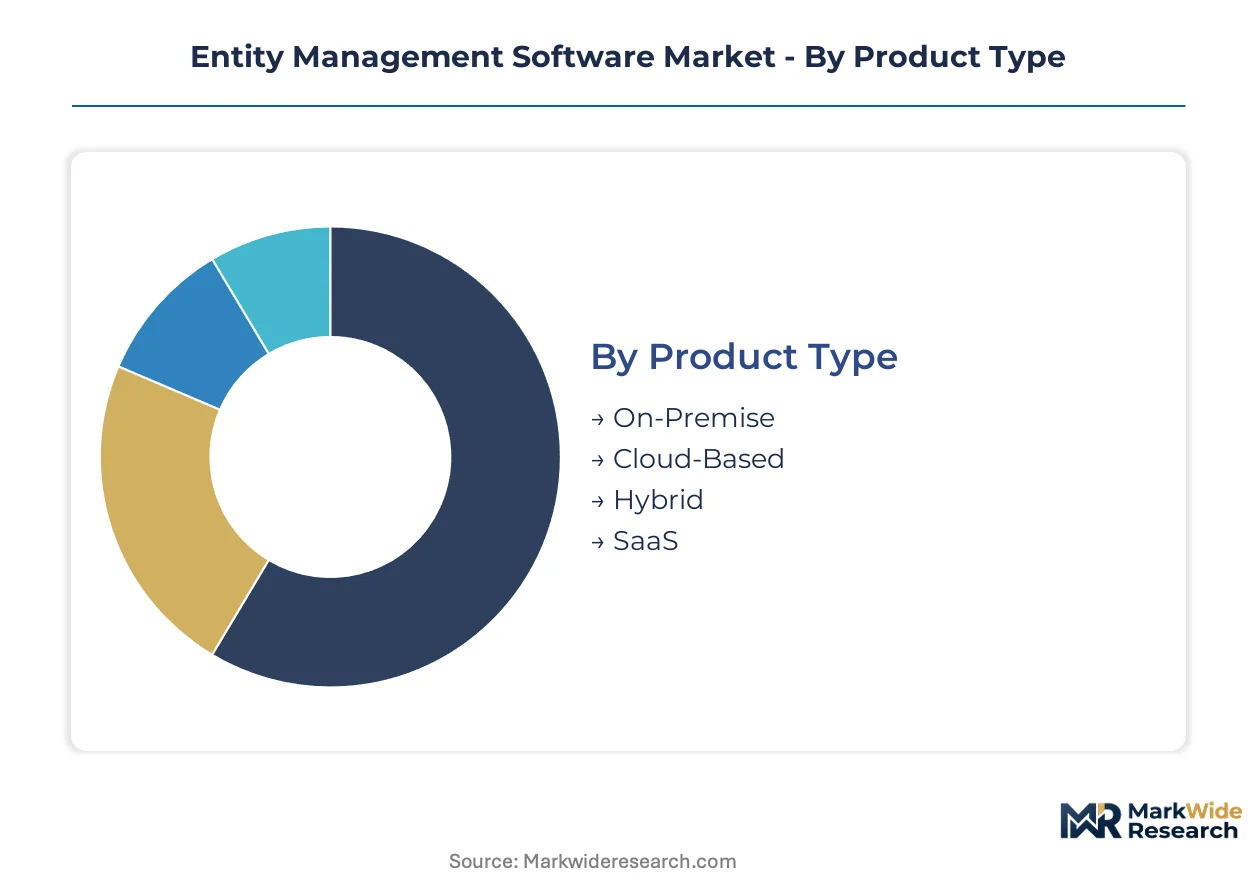
Entity management software procurement diverges sharply across deployment architectures and organizational scale. Buyers with stringent data residency mandates select fundamentally different technical configurations than lean legal teams prioritizing rapid implementation.
Product Type:
Cloud-Based solutions face the most intense substitution pressure as hybrid architectures and specialized SaaS offerings fragment the addressable base.
- On-Premise:Legacy infrastructure requiring dedicated server installations and internal IT maintenance. Financial services institutions in Delaware and New York with SEC audit requirements sustain procurement despite higher total cost of ownership.
- Cloud-Based:Multi-tenant platforms delivered through browser interfaces with automatic vendor-managed updates. Mid-market law firms in Texas and California adopt these fastest as ISO 27001 certification becomes a procurement gate.
- Hybrid:Split architectures keeping sensitive beneficial ownership data on-premise while routing routine filings through cloud workflows. Healthcare systems managing physician practice entities across state lines favor this configuration for HIPAA alignment.
- SaaS:Subscription-native platforms with API-first designs for ecosystem integration. Technology sector legal departments with volatile subsidiary counts prefer consumption-based pricing models.
Cloud-Based retains volume leadership; SaaS holds the steepest expansion curve.
Deployment:
Cost tier stratification separates enterprise-grade single-tenant implementations from mid-market multi-tenant alternatives.
- Single-Tenant:Dedicated instance isolation with jurisdiction-specific data residency controls. Private equity firms managing special purpose vehicles across Luxembourg and Cayman Islands require these configurations for cross-border compliance.
- Multi-Tenant:Shared infrastructure with logical tenant separation reducing per-user costs by half or more. Regional law firms in Illinois and Florida standardize here for routine corporate maintenance workflows.
- Private Cloud:Vendor-managed dedicated environments hosted within client-specified regions. German automotive multinationals with GDPR exposure select these for EU subsidiary record management.
- Public Cloud:Standardized offerings running on AWS, Azure, or Google Cloud infrastructure. Startup legal teams without compliance specialists default to these for speed-to-deployment.
Multi-Tenant dominates transaction volume; Private Cloud is climbing the fastest as data localization mandates proliferate.
End User:
Customer type maturity determines feature complexity requirements and implementation timeline tolerance.
- Corporations:Established entities with 50-plus subsidiaries requiring automated registered agent coordination and beneficial ownership tracking. Fortune 500 legal departments in Virginia and Massachusetts drive premium module adoption.
- Non-Profits:Mission-driven organizations with lean administrative staff prioritizing donor-facing compliance over internal governance automation. State filing deadline management remains the core use case.
- Startups:Venture-backed companies with rapid entity formation and dissolution cycles. Delaware incorporation pipelines for pre-IPO technology companies create concentrated demand spikes.
- Enterprises:Complex multi-jurisdictional operations with dedicated subsidiary governance teams. Cross-border data transfer restrictions between US and EU operations shape platform selection criteria.
Corporations anchor revenue concentration; Startups are gaining share fastest as venture formation accelerates.
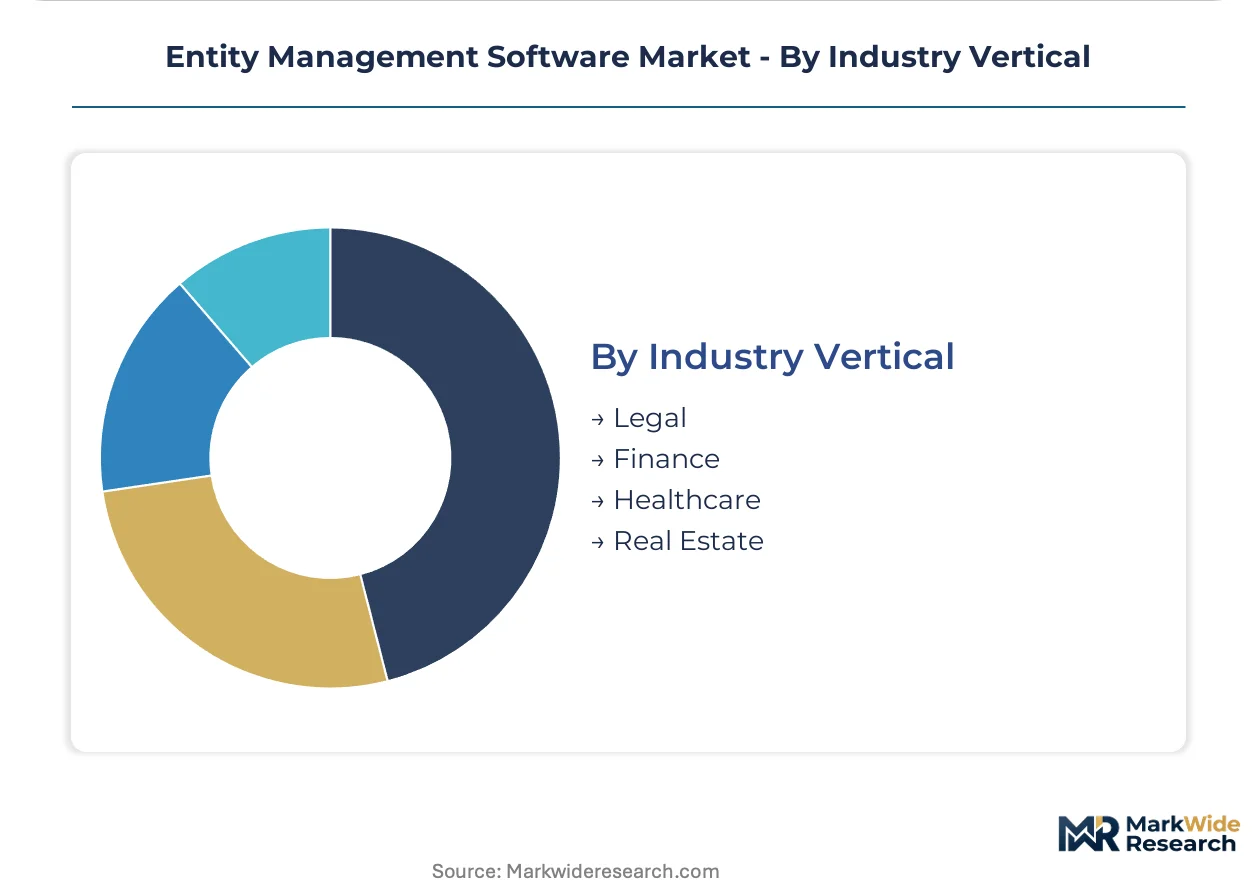
Industry Vertical:
Application-specific compliance intensity separates high-investment legal and finance segments from emerging healthcare adopters.
- Legal:Law firms managing client subsidiary portfolios with fiduciary liability exposure. AmLaw 200 practices in Washington DC and Chicago deploy these platforms for minute book digitization and shareholder meeting automation.
- Finance:Banks, insurers, and asset managers subject to SEC disclosure rules and state insurance regulator filings. Beneficial ownership collection workflows for Corporate Transparency Act compliance dominate procurement rationale.
- Healthcare:Hospital systems and physician practice management companies navigating state-level entity reporting for medical licensing. Texas and California compliance teams expand fastest as ownership disclosure requirements multiply.
- Real Estate:Property holding companies and REITs managing title-holding subsidiaries across municipal jurisdictions. Delaware limited liability company maintenance drives seasonal filing volume spikes.
Legal vertical commands the largest installed base; Healthcare shows the steepest adoption acceleration as regulatory scope widens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legal departments at multinational corporations concentrate procurement in jurisdictions with the most complex beneficial ownership disclosure regimes. Enterprise buyers prioritize platforms that automate SEC filings, GDPR-compliant data residency, and state-level registered agent coordination.
United States
Fortune 500 legal teams in Virginia and Massachusetts drive premium module adoption for Corporate Transparency Act compliance. SEC beneficial ownership reporting mandates compel automated data collection workflows. Delaware corporate registry volumes sustain registered agent service demand.
United Kingdom
AmLaw 200 practices in London deploy entity management platforms for minute book digitization and shareholder meeting automation. GDPR cross-border data governance requirements accelerate platform investments for US-based multinationals maintaining EU subsidiary records. The City of London financial services cluster anchors compliance technology procurement.
Germany
German automotive multinationals with GDPR exposure select private cloud configurations for EU subsidiary record management. CSRD sustainability reporting mandates extend platform scope beyond traditional corporate records to granular subsidiary-level emissions disclosures. Bavaria's industrial headquarters concentration drives enterprise-grade deployment.
India
Ministry of Corporate Affairs digitization initiatives and ROC compliance automation create whitespace for cloud-native platform providers. SEBI disclosure requirements for listed entities propel procurement from legal departments managing complex subsidiary structures. Mumbai and Bangalore technology corridors concentrate emerging vendor development.
Canada
Ontario-based pension funds and asset managers require automated special purpose vehicle governance for infrastructure investment holdings. Provincial securities regulator harmonization with SEC rules shapes cross-border platform selection criteria. Toronto's financial services cluster sustains mid-market legal department adoption.
Entity Management Software Market Competitive Landscape
Player mix skews toward regulatory content heritage providers and geographic administration specialists. The vendor base concentrates around three strategic tiers: established compliance data publishers with embedded workflow tools, jurisdictional service networks with technology overlays, and cloud-native challengers targeting mid-market law firms. Dominant competitive moves include ISO 27001 certification acceleration and AI-powered document extraction capability integration.
Within the regulatory content tier, Thomson Reuters ONESOURCE leverages statutory database heritage to anchor compliance workflows. TMF Group exemplifies geographic administration specialists through localized entity capabilities spanning multiple jurisdictions. Athennian occupies a position among cloud-native challengers with architecture designed for high-volume subsidiary governance.
| Leading Market Players |
|---|
| Thomson Reuters ONESOURCE |
| TMF Group |
| Athennian |
| Filejet |
| CSC (Corporation Service Company) |
| Diligent Entities |
| Vistra |
| CorpNet |
| CT Corporation |
| Others |
Pricing and Supply Chain Analysis
Multi-tenant cloud infrastructure scale economies compress per-seat delivery costs below on-premise alternatives, concentrating supply-side power among hyperscale platform operators while anchoring SaaS price floors to ISO 27001 audit overhead rather than raw compute costs.
Pricing Analysis
Cost-plus contracts with CPI indexation dominate enterprise procurement for single-tenant configurations, while consumption-based SaaS tiers serve mid-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates ISO 27001-certified vendors from uncertified competitors and basic automation-only entrants. Price differentiation centers on certification grade and geographic data residency controls. Pricing pressure stems from hyperscaler infrastructure cost pass-throughs, with startup legal departments showing highest sensitivity and Fortune 500 compliance teams least responsive to tier adjustments.
Supply Chain Analysis
Implementation lead times for custom single-tenant deployments extend 40-60% beyond multi-tenant alternatives due to jurisdiction-specific infrastructure provisioning. Cloud infrastructure supply concentrates in the United States, Ireland, and Singapore for data residency compliance. Software development draws from specialized labor pools in India, Poland, and Canada for compliance workflow engineering. Single-source vulnerability runs through AWS, Microsoft Azure, and Google Cloud dominance. Distribution runs through direct vendor sales for enterprise accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Entity management software demand follows regulatory filing cycles, with Corporate Transparency Act implementation driving current upgrade momentum as compliance deadlines compress procurement timelines.
For Market Incumbents: Consolidate around ISO 27001 certification acceleration and AI-powered document extraction capability integration to defend against cloud-native challengers. Acquire specialized jurisdictional service networks in Luxembourg and Cayman Islands to fortify cross-border data residency offerings. Vertical integration into private cloud infrastructure reduces hyperscaler dependency for financial services clients with strict storage mandates.
For New Entrants and Emerging Players: Differentiate on India market entry timing and private equity portfolio company automation workflows. Target SEBI disclosure automation for Mumbai and Bangalore technology corridors as the most penetrable whitespace. Pursue partnership-first go-to-market with AmLaw 200 practices seeking minute book digitization without legacy system migration costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platforms serving mid-market law firms with 50-200 entity portfolios. Long-term viability hinges on regulatory content heritage depth and jurisdictional coverage breadth. Monitor Corporate Transparency Act penalty enforcement intensity as the signal indicating enterprise procurement acceleration or deceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acceleration | Enterprise procurement teams mandate audited security management before vendor qualification. |
| AI-Powered Document Extraction | NLP engines trained on corporate governance documents displace manual subsidiary data entry workflows. |
| India Market Entry | Ministry of Corporate Affairs digitization creates whitespace for cloud-native platform providers. |
| Private Equity Workflow Specialization | Buyout firms managing hundreds of SPVs per fund require automated subsidiary governance tools. |
| CSRD ESG Module Integration | European sustainability reporting mandates extend platform scope beyond traditional corporate records. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across legal departments, compliance officers, and entity administration specialists. Primary interviews captured procurement criteria from Fortune 500 legal teams, AmLaw 200 practices, and private equity operations heads. Secondary validation drew from SEC disclosure filings, state corporate registry statistics, GDPR implementation guidance, and cloud infrastructure provider compliance documentation. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the analysis window, the forecasting framework modeled deployment architecture, organization scale, vertical compliance intensity, and geographic regulatory cluster. CAGRs derived from segment-level growth rate blending and adoption curve positioning. Forecast inputs incorporated Corporate Transparency Act implementation pace, ISO 27001 certification penetration timelines, and healthcare vertical expansion velocity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory filing complexity or hyperscaler infrastructure cost stability would require recalibration. Forecasts reflect documented assumptions regarding compliance deadline adherence and cloud migration momentum. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Recruitment Software Market
Software & Services
Multi-Cloud SDN Market
Software & Services
Audit Management Software Market
Software & Services
Global Disk Imaging Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Core Banking Software Market
Software & Services
Poultry Farm Management Software Market
Software & Services
App Building Software Market
Software & Services
Global Survey Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Automation Test Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Collaboration Software Market
Software & Services
Medical Equipment Repair Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Lead Management Software Market