
 Global Franchise Management Software Market | 2026-2036
Global Franchise Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Franchise Management Software Market Foresight
The EU AI Act is broadening compliance automation requirements for multi-unit franchise operators, forcing platform upgrades that embed audit trails and algorithmic transparency. FranConnect leverages deep workflow specialization across quick service chains to sustain its competitive position. Zenput anchors its growth through mobile-first operational tools that dominate field execution for distributed franchise networks. Operandio differentiates by concentrating on task management and daily operations for hospitality and retail franchisees.
Franchise management software constitutes an integrated technology platform that orchestrates multi-unit operations through centralized data architectures, API-connected modules, and real-time synchronization across dispersed locations. The primary commercial purpose is to standardize brand compliance while enabling local operational autonomy across franchisee networks. Cloud-based deployment leads the infrastructure mix due to lower capital barriers and faster rollout cycles for emerging franchise systems. Inventory management and marketing automation within the solution layer capture disproportionate margin pools as operators prioritize revenue optimization and waste reduction. Quick service chains represent the most mature end-user segment, while fitness centers and educational services exhibit the fastest expansion trajectories as franchising models penetrate service sectors.
FDA food safety modernization rules, the EU AI Act, and ISO 27001 data security standards collectively shape product development priorities and market access conditions for franchise software vendors. These frameworks mandate traceable documentation, risk-based preventive controls, and certified information governance that platforms must embed natively. Stakeholders should monitor how emerging digital identity regulations across multiple jurisdictions will reshape franchisee onboarding and cross-border royalty settlement architectures.
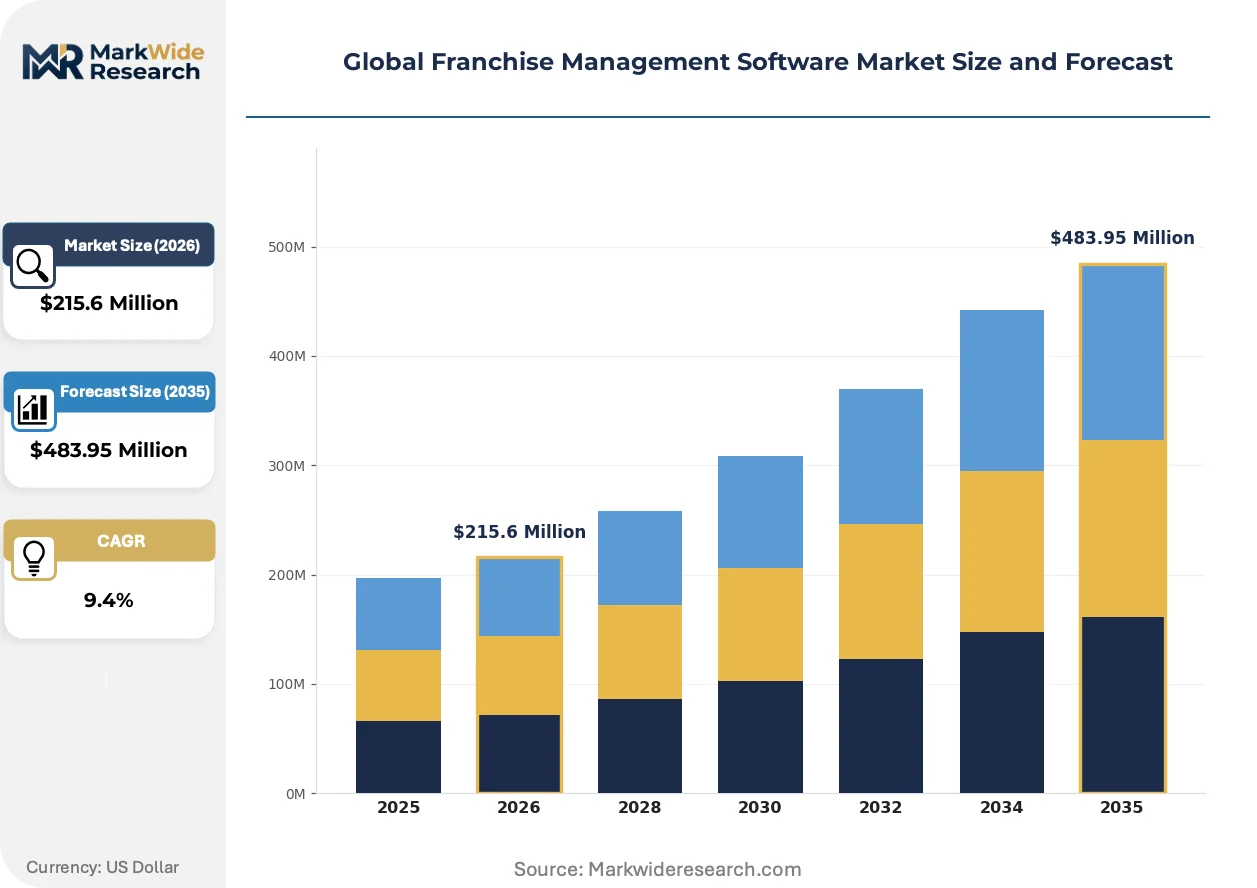
Market Dynamics
Cloud-native architectures are compressing deployment timelines for franchise networks while the EU AI Act forces algorithmic transparency into compliance modules, creating a dual pressure on vendors to deliver speed and auditability simultaneously.
Growth Catalysts
- EU AI Act compliance mandates:Multi-unit operators across Germany, France, and Italy must embed automated audit trails and explainable AI into franchise management platforms, accelerating replacement cycles for legacy systems.
- Quick service restaurant digitization:Southeast Asian chains in Indonesia, Vietnam, and Thailand are deploying cloud-based royalty tracking and supply chain coordination modules to manage rapid franchisee expansion.
- API-first integration standards:Open banking protocols and unified logistics interfaces are enabling real-time data synchronization between franchisors and dispersed franchisee locations.
Market Restraints
- Data localization requirements:India's draft Digital Personal Data Protection Act and China's Cybersecurity Law mandate in-country server infrastructure, fragmenting vendor architectures and raising operational costs.
- Legacy system entrenchment:Mature quick service chains in the United States operate deeply customized on-premise deployments with decade-old configurations, creating switching friction.
- Skill scarcity in franchise operations:Shortages of personnel capable of configuring multi-module platforms across inventory, marketing, and field execution slow implementation velocity.
Strategic Opportunities
- Fitness and wellness franchising:Boutique gym chains and recovery studios in Australia and South Korea represent underpenetrated end-use segments with limited incumbent vendor relationships.
- Embedded finance convergence:Integration of lending, insurance, and payment processing modules into franchise management platforms creates new revenue pools for vendors serving capital-constrained franchisees.
- India's domestic franchise boom:Local retail and food service networks digitizing royalty collection and supply chain visibility offer first-mover advantages for platforms with vernacular language support.
Industry Challenges
- ISO 27001 certification timelines:Vendors targeting European multi-unit operators face extended security audit cycles that delay market entry and strain engineering resources.
- Interoperability with proprietary POS systems:Franchisees operating mixed technology stacks require complex middleware development to synchronize transactional data with centralized management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Franchise Management Software Market |
| Market Size in 2026 | $215.6 Million |
| Market Size in 2035 | $483.95 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution/Offering: Inventory Management, Customer Relationship Management, Employee Scheduling, Financial Reporting, Marketing Automation Use Case: Franchisee Onboarding, Royalty Tracking, Performance Analytics, Supply Chain Coordination, Compliance Management End User: Quick Service Chains, Retail Outlets, Educational Services, Hospitality Groups, Fitness Centers |
| Companies Covered | Operandio, Jolt, FranConnect, Ouranos Technologies, Chetu, Claromentis, FranchiseSoft, Zenput, BrandWide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Franchise Management Software Market Shifts & Advancements
Artificial intelligence is penetrating operational decision layers while regulatory pressure hardens data governance requirements, compressing the window for vendors to deliver compliant innovation.
Generative AI is rewriting how franchise networks handle field execution and quality assurance. Quick service chains in Singapore and Malaysia are deploying large language models to automate incident reporting and standardize corrective action protocols across hundreds of locations. The technology is compressing response times from days to hours while reducing district manager travel requirements.
The EU AI Act is mandating risk classification and documentation for algorithmic tools used in franchisee performance scoring and automated marketing allocation. Vendors serving European multi-unit operators must now embed technical documentation and human oversight mechanisms into product roadmaps. Fitness and education franchisors face the steepest compliance curves given their reliance on predictive member retention models.
Subscription-based pricing models are displacing perpetual license structures as emerging franchise systems prioritize operational expenditure flexibility. Cloud-native vendors in India and Brazil are capturing mid-market chains that lack capital for upfront deployment. The shift is most visible among domestic food service networks with rapid unit expansion timelines and limited IT infrastructure.
Global Franchise Management Software Market Segmentation
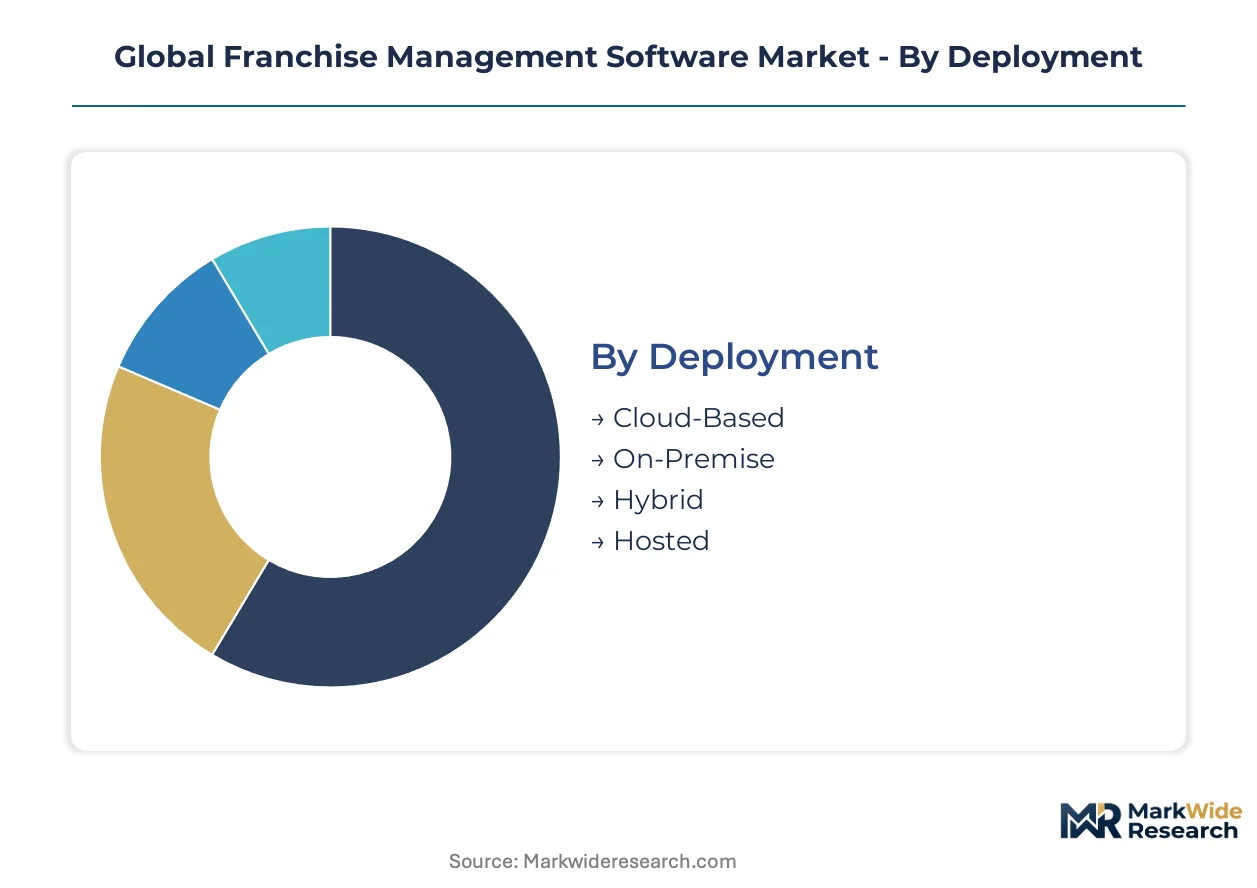
Segmentation in franchise management software reveals how capital deployment, operational complexity, and regulatory exposure shape purchasing decisions across franchisor networks. Deployment architecture determines upfront infrastructure investment, while solution modules reflect which operational pain points command premium pricing.
Deployment:
Capital-intensity varies sharply across deployment modes, with on-premise installations requiring server hardware, dedicated IT staffing, and multi-year amortization schedules that strain emerging franchise systems.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure for server infrastructure while enabling rapid rollout across dispersed franchisee locations. Southeast Asian quick service chains in Indonesia and Vietnam prioritize this model to accelerate unit expansion without proportional IT headcount growth.
- On-Premise:Dedicated single-tenant installations within franchisor data centers deliver maximum data sovereignty and customization depth. Mature US quick service chains with decade-old ERP integrations maintain these deployments despite higher total cost of ownership.
- Hybrid:Split architectures keep sensitive financial data on-premise while pushing field operations to cloud instances. European multi-unit operators adopt this configuration to satisfy EU AI Act audit trail requirements without sacrificing edge computing performance.
- Hosted:Third-party managed infrastructure offloads operational maintenance while preserving single-tenant isolation. Mid-market fitness franchises in Australia select hosted deployments to balance compliance rigor against limited internal technical capacity.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as European regulatory pressure intensifies.
Solution/Offering:
Module selection tracks operational maturity, with revenue optimization tools commanding priority in saturated markets and cost-control functions dominating emerging franchise systems.
- Inventory Management:Real-time stock synchronization across distributed locations reduces waste and automates reorder triggers based on consumption velocity. Quick service chains in Thailand deploy these modules to coordinate perishable supply chains across hundreds of franchisee kitchens.
- Marketing Automation:Centralized campaign orchestration with local customization preserves brand consistency while enabling geographic personalization. US retail outlets leverage these tools to coordinate seasonal promotions across heterogeneous regional markets.
- Customer Relationship Management:Unified guest profiles spanning online ordering, loyalty programs, and in-store interactions. Hospitality groups in South Korea integrate CRM with mobile payment platforms to capture repeat visitation patterns.
- Employee Scheduling:Labor optimization algorithms match staffing levels to forecasted demand while respecting jurisdictional labor regulations. Educational services franchises use these tools to coordinate part-time instructor availability across multiple campus locations.
- Financial Reporting:Consolidated royalty calculation, franchisee profitability tracking, and automated remittance workflows. Domestic Indian retail networks deploy these modules to digitize previously manual collection processes.
Revenue concentration sits with Inventory Management. Gaining share fastest is Marketing Automation as franchisors prioritize same-store sales growth.
Use Case:
Functional priorities diverge by franchise lifecycle stage, with early-stage networks emphasizing onboarding velocity and mature systems concentrating on compliance automation.
- Franchisee Onboarding:Digital document collection, training module delivery, and initial site certification workflows compress time-to-revenue for new unit openings. Brazilian food service networks accelerate expansion through automated onboarding pipelines.
- Royalty Tracking:Automated calculation and collection of recurring fees based on point-of-sale data feeds with dispute resolution protocols. Indian domestic franchises digitize these processes to reduce collection friction and improve cash flow predictability.
- Performance Analytics:Benchmarking dashboards comparing franchisee unit economics against network averages with drill-down diagnostic capabilities. Fitness center franchisors in Australia use these insights to identify underperforming locations for operational intervention.
- Supply Chain Coordination:Centralized procurement negotiation with distributed fulfillment tracking and quality assurance documentation. Quick service chains across Malaysia coordinate multi-tier supplier networks through these modules.
- Compliance Management:Automated documentation for food safety, labor law, and data protection requirements with audit trail preservation. EU AI Act mandates are driving replacement demand for legacy systems lacking algorithmic transparency features.
Transaction volume concentrates in Royalty Tracking. Steepest expansion trajectory belongs to Compliance Management as regulatory complexity compounds across jurisdictions.
End User:
Vertical-specific requirements shape feature prioritization, with food service demanding real-time operational synchronization and service sectors emphasizing appointment scheduling and member retention.
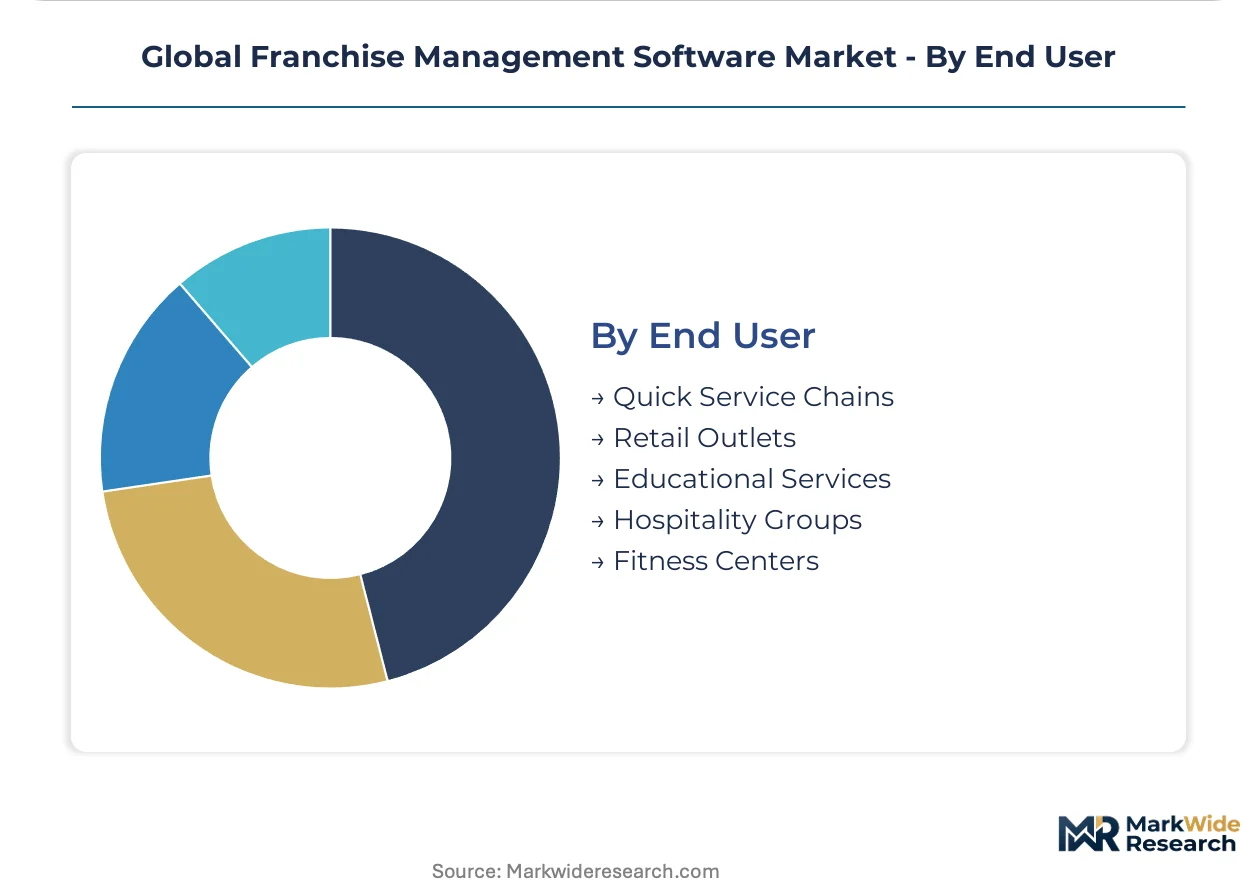
- Quick Service Chains:High-velocity transaction processing with kitchen display integration and drive-thru timing optimization. This segment represents the most mature adopter category with established vendor relationships and complex legacy integration requirements.
- Fitness Centers:Member lifecycle management with class scheduling, personal training coordination, and predictive churn intervention. Boutique gym chains in South Korea and Australia exhibit the steepest adoption growth as franchising models penetrate wellness services.
- Retail Outlets:Omnichannel inventory visibility with buy-online-pickup-in-store coordination and unified loyalty program management. Domestic networks in India digitize these capabilities to compete with organized modern trade.
- Hospitality Groups:Property management system integration with guest service ticketing and revenue per available room optimization. Hotel franchisors prioritize these tools to maintain brand standards across independently operated properties.
- Educational Services:Curriculum delivery tracking, instructor credential management, and parent communication portals. Tutoring and test preparation franchises deploy these modules to standardize learning outcomes across dispersed locations.
Vendor development resources concentrate on Quick Service Chains. Fitness Centers are expanding most quickly as wellness franchising accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Franchise management software emerged from North American quick service restaurant chains during the 1990s ERP expansion, later spreading to European retail networks and Asia-Pacific hospitality groups as cloud infrastructure matured.
United States
Mature quick service chains dominate demand as operators replace decade-old on-premise ERP configurations with cloud-native platforms. FDA food safety modernization rules mandate traceable documentation systems that integrate with franchise management modules. Dallas-Fort Worth and Atlanta host concentrated vendor development clusters serving domestic restaurant networks.
Germany
Multi-unit retail and automotive service franchises drive platform adoption to coordinate complex supply chains across federal states. EU AI Act compliance requirements force algorithmic transparency into performance scoring modules, accelerating replacement cycles for legacy systems. Munich and Stuttgart industrial corridors concentrate vendor engineering resources.
India
Domestic retail and food service networks digitize royalty collection and supply chain visibility as franchising models penetrate tier-two cities. Draft Digital Personal Data Protection Act mandates in-country server infrastructure, fragmenting vendor architectures. Mumbai and Bangalore host emerging platform development centers serving vernacular-language franchise systems.
Indonesia
Quick service restaurant chains deploy cloud-based royalty tracking to manage rapid franchisee expansion across archipelago logistics. National data localization regulations require domestic hosting for financial transaction records. Jakarta and Surabaya concentrate implementation activity for Southeast Asian market entry strategies.
Australia
Boutique fitness chains and wellness studios represent underpenetrated demand as franchising models penetrate recovery services and personalized training. TGA medical device regulations influence health-tech integration requirements for wellness platforms. Sydney and Melbourne host specialized vendors serving Asia-Pacific fitness network expansion.
Global Franchise Management Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across workflow specialization depth, with those embedding compliance automation commanding pricing power against generic task management alternatives. The vendor base fragments across deployment architectures and vertical focus areas rather than consolidating around dominant platforms. Three strategic archetypes define positioning: workflow specialists with deep quick service restaurant expertise, mobile-first field execution platforms, and compliance-heavy solutions targeting regulated European markets. M&A activity concentrates on API integration capabilities and regional compliance expertise, while geographic expansion into India and Southeast Asia represents the primary organic growth vector.
Within the workflow specialization tier, FranConnect and Zenput exemplify divergent positioning strategies, with the former anchoring deep operational integration for restaurant chains and the latter occupying mobile-first field coordination for distributed networks. Operandio represents the task management archetype targeting hospitality and retail franchisees with simplified daily operations tools. These three companies collectively illustrate how vendor positioning stratifies across functional depth versus deployment accessibility.
| Leading Market Players |
|---|
| Operandio |
| Jolt |
| FranConnect |
| Ouranos Technologies |
| Chetu |
| Claromentis |
| FranchiseSoft |
| Zenput |
| BrandWide |
| Others |
Supply & Pricing Matrix
Cloud engineering talent concentration in Bangalore and Hyderabad generates labor-cost differentials that widen pricing-tier spreads between premium SaaS vendors and economy-tier domestic platforms serving Indian franchise networks.
Pricing Analysis
Subscription-based SaaS pricing with three-tier differentiation across premium, standard, and economy levels dominates vendor revenue models. Price differentiation rests on ISO 27001 certification status and API integration depth as primary tier-separators. Cost compression in economy tiers intensifies because Indian domestic platforms compete aggressively on implementation fees. Emerging franchise systems in Southeast Asia exhibit highest price sensitivity, while EU multi-unit operators demonstrate lowest sensitivity due to compliance-driven replacement mandates.
Supply Chain Analysis
Freight cost volatility from Southeast Asian data center clusters to European end-users elevates total cost of ownership for cloud-native deployments. Software development concentrates in India, the United States, and Germany as primary engineering hubs. Raw material dependencies span server-grade semiconductors from Taiwan, lithium-ion backup power systems from South Korea, and specialized cooling infrastructure from Japan. Single-source vulnerability in Taiwan semiconductor fabrication creates supply chain risk for hardware-dependent hosted deployments. Distribution runs through direct enterprise sales teams supplemented by regional systems integrators in target markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Franchise Management Software Market functions as a stable compounder, with regulatory compliance mandates across the EU AI Act and India's data localization rules driving predictable replacement cycles and sustained platform upgrade demand.
For Market Incumbents: Lock in competitive position by embedding EU AI Act audit trail automation as a native platform feature before smaller competitors achieve certification. Prioritize backward integration into proprietary POS middleware to reduce franchisee switching flexibility. Defend against cloud-native challengers by accelerating hybrid deployment roadmaps that satisfy European data sovereignty requirements without sacrificing edge performance.
For New Entrants and Emerging Players: Generative AI field execution tools offer a technology-first wedge into boutique fitness and wellness franchising in Australia and South Korea, segments with limited incumbent penetration. Target white-space demand in India's tier-two city retail networks digitizing royalty collection for the first time. Pursue a mobile-first, vernacular-language go-to-market that bypasses complex enterprise sales cycles.
For Investors and Strategic Acquirers: Private equity firms with vertical software portfolios are the most active acquirer in this space, seeking compliance-heavy platforms with sticky franchisee relationships. Long-term viability centers on vendors with embedded finance capabilities and cross-border royalty settlement infrastructure. Watch for inflection signals in India's Digital Personal Data Protection Act finalization, which will trigger accelerated domestic vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Module Development | Algorithmic transparency features satisfy EMA audit requirements and unlock European multi-unit operator contracts. |
| Embedded Finance Integration | Lending and insurance modules capture revenue from capital-constrained franchisees in emerging markets. |
| Vernacular Language Localization | Native Hindi, Bahasa, and Thai interfaces accelerate adoption among India's and Southeast Asia's domestic franchise networks. |
| API-First Platform Architecture | Open banking and logistics protocol compatibility enables real-time data synchronization across dispersed franchisee locations. |
| Hybrid Deployment Infrastructure | Split cloud-on-premise configurations satisfy EU AI Act audit trails while preserving edge computing performance for quick service chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary data collection engaged franchisor CIOs, multi-unit franchisee operations directors, platform integration specialists, and compliance officers at software vendors. Secondary validation drew from SEC filings of publicly traded restaurant chains, EU AI Act regulatory documentation, ISO certification registries, and hyperscaler cloud infrastructure disclosures. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across deployment architecture, solution module mix, and end-user vertical intensity. The analytical framework modeled cloud-based, on-premise, hybrid, and hosted configurations alongside inventory management, marketing automation, CRM, scheduling, and financial reporting modules across quick service, fitness, retail, hospitality, and educational end-use segments. CAGRs derived from franchise unit expansion trajectories, replacement cycle compression from regulatory mandates, and pricing elasticity by buyer tier. Forecast inputs included cloud infrastructure capex disclosures and franchise disclosure document filing trends.
The model holds under stable regulatory enforcement timelines and continued cloud adoption curves; deviation in EU AI Act implementation severity or India's data localization final rules would shift replacement demand timing. Forecasts reflect documented assumptions about franchise network digitization rates and vendor certification completion schedules. A model refresh is warranted upon material change in cross-border data transfer restrictions or major hyperscaler market entry strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Global Archiving Software Market
Software & Services
Ad Creation Software Market
Software & Services
Product Analytics Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
3D Modeling Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Plant Design Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Avionics Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Video Server Software Market
Software & Services
Referral Marketing Software Market
Software & Services
Business Rules Management System Market