
 Global Idea Management Software Market | 2026-2036
Global Idea Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Idea Management Software Market Foresight
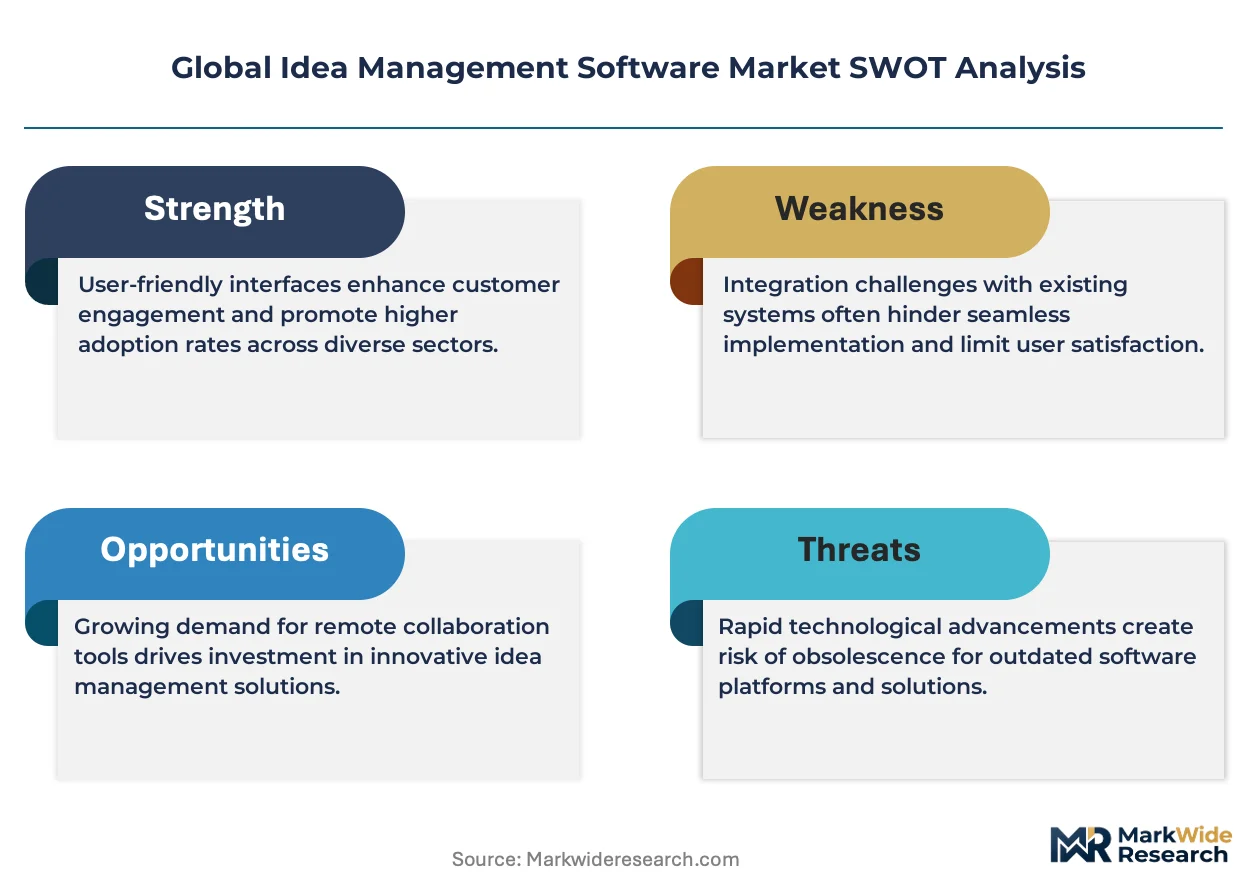
GDPR is pivoting the cost-of-entry calculus for vendors serving European enterprises, forcing substantial investments in data residency and consent management architectures. Brightidea leverages its established enterprise footprint to sustain compliance-heavy deployments across multinational clients. Qmarkets anchors its competitive stance through deep workflow automation integrations that reduce implementation friction for IT administrators.
Idea management software comprises digital platforms that capture, evaluate, and prioritize user-submitted concepts through configurable scoring algorithms, multi-stage review pipelines, and real-time collaboration interfaces. These systems serve the primary commercial purpose of institutionalizing innovation by converting unstructured employee or customer input into trackable, resourced development projects. Cloud-based deployment dominates current adoption as organizations prioritize elastic scalability and reduced infrastructure overhead, while on-premise configurations retain traction among financial services entities with stringent data sovereignty mandates. Workflow automation within solution offerings commands the strongest margin pools due to complex integration requirements with existing enterprise systems.
The EU AI Act and ISO management standards collectively shape product development trajectories, requiring algorithmic transparency documentation and auditable decision trails for automated idea scoring modules. HIPAA constrains deployment architectures for U.S. healthcare-adjacent users, necessitating encrypted transmission protocols and granular access controls. Stakeholders must monitor evolving jurisdictional requirements for automated decision-making disclosures before committing to platform architectures that lack modular compliance layering.
Market Dynamics
Cloud migration mandates from enterprise IT departments are compressing deployment cycles for idea management vendors, forcing architectural pivots toward containerized microservices that satisfy data residency requirements across multiple jurisdictions simultaneously.
Growth Catalysts
- EU AI Act compliance frameworks:Automated idea scoring modules require algorithmic transparency documentation, creating upgrade demand for legacy platforms lacking auditable decision trails.
- Germany's industrial conglomerates:Distributed engineering teams across Siemens, Bosch, and automotive suppliers deploy innovation management platforms to coordinate R&D across plant networks.
- Natural language processing engines:Semantic analysis capabilities now extract structured concepts from unstructured employee submissions, reducing manual categorization overhead.
Market Restraints
- GDPR data residency costs:European enterprises demand region-locked cloud instances, forcing vendors to maintain redundant infrastructure across Frankfurt, Dublin, and Stockholm zones.
- ISO 27001 certification timelines:Security audit cycles extend 8-14 months, delaying enterprise procurement decisions and inflating pre-revenue engineering overhead.
- Legacy ERP integration complexity:SAP and Oracle environments require custom API development, concentrating implementation risk with specialized systems integrators.
Strategic Opportunities
- India's PLI scheme beneficiaries:Electronics and automotive component manufacturers building local R&D centers need idea capture systems compliant with BIS data localization norms.
- Healthcare adjacent deployments:HIPAA-constrained U.S. providers seek encrypted, on-premise configurations for clinician-driven innovation programs.
- CSRD reporting integration:Sustainability-linked idea pipelines that track carbon-reduction concepts are becoming procurement evaluation criteria for EU-based buyers.
Industry Challenges
- Enterprise architecture skill scarcity:Vendors struggle to hire solution architects proficient in both legacy SAP landscapes and modern Kubernetes orchestration.
- Multi-jurisdiction compliance layering:Simultaneous satisfaction of GDPR, HIPAA, and BIS requirements demands modular permission architectures that fragment development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Idea Management Software Market |
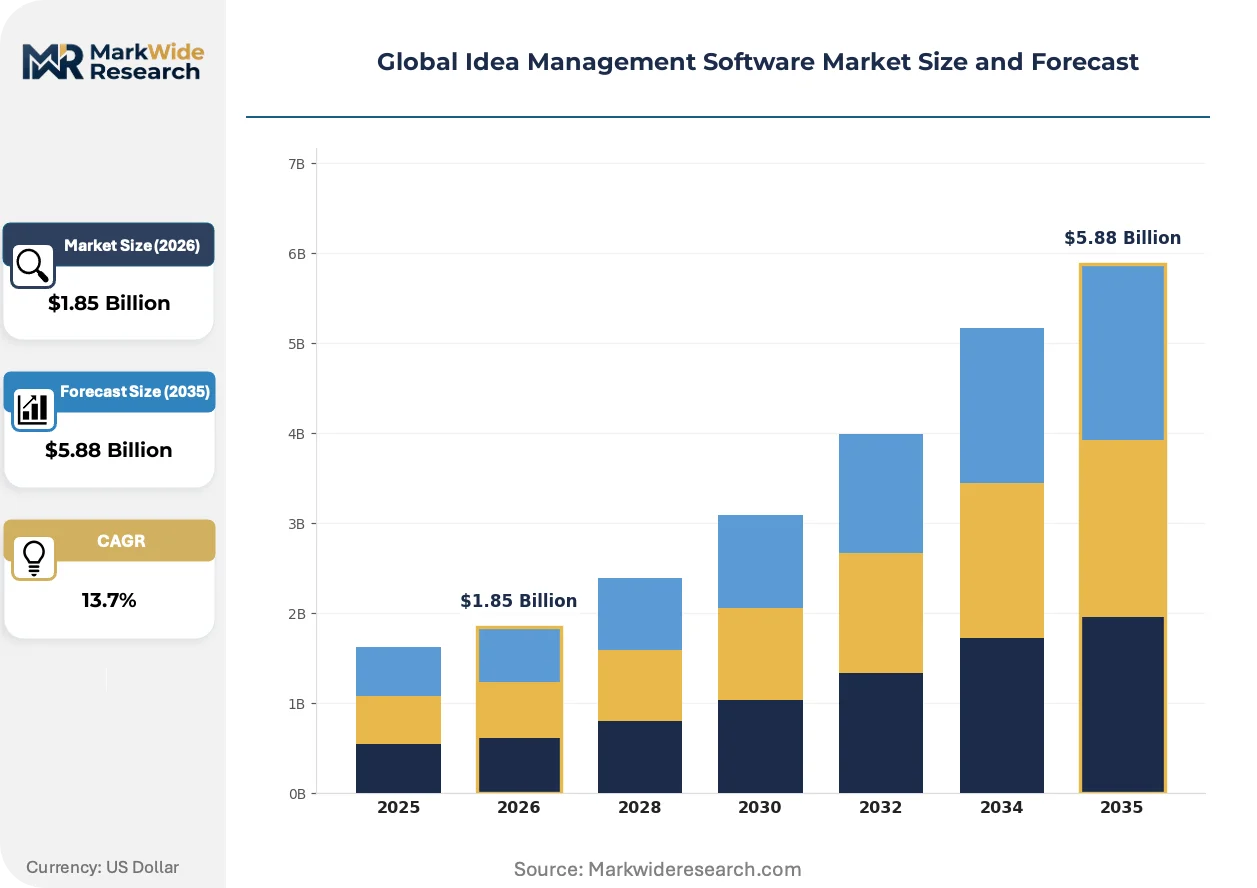
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted, SaaS Solution Offering: Collaboration Tools, Workflow Automation, Analytics & Reporting, Idea Crowdsourcing, Innovation Management Application: Product Development, Process Improvement, Employee Engagement, Customer Feedback, Market Research End User Industry: Technology Firms, Financial Services, Manufacturing Companies, Educational Institutions, Government Agencies |
| Companies Covered | Brightidea, IdeaScale, HYPE Innovation, Qmarkets, Spigit, Planbox, Wazoku, ITONICS, Ideawake, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Idea Management Software Market Shifts & Advancements
Generative AI capabilities are absorbing into core platform functionality, transforming idea management from passive collection systems into active synthesis engines that generate derivative concepts from employee submissions.
Large language models are absorbing semantic clustering tasks previously performed by manual taxonomists, compressing concept categorization from days to minutes. Financial services and pharmaceutical buyers in the U.S. and Switzerland are piloting these capabilities for competitive intelligence synthesis. The structural consequence is collapsing differentiation between mid-tier and premium vendors, as baseline AI features commoditize across price tiers.
The EU AI Act is mandating human-in-the-loop requirements for automated scoring of employee submissions, forcing vendors to redesign evaluation pipelines. Industrial consequences include mandatory explanation interfaces and appeal mechanisms for rejected concepts. German automotive and French pharmaceutical enterprises are most affected, with procurement teams now requiring algorithmic impact assessments as standard contract addenda.
Subscription-to-outcome contracting is displacing seat-based pricing among Fortune 500 buyers, with procurement teams demanding metrics linkage between platform usage and filed patents or product launches. Channel disruption is concentrating deal flow through specialized innovation consultancies rather than generalist software resellers. This pattern is most visible in the U.S. healthcare and German industrial machinery verticals, where innovation outcomes carry direct revenue attribution.
Global Idea Management Software Market Segmentation
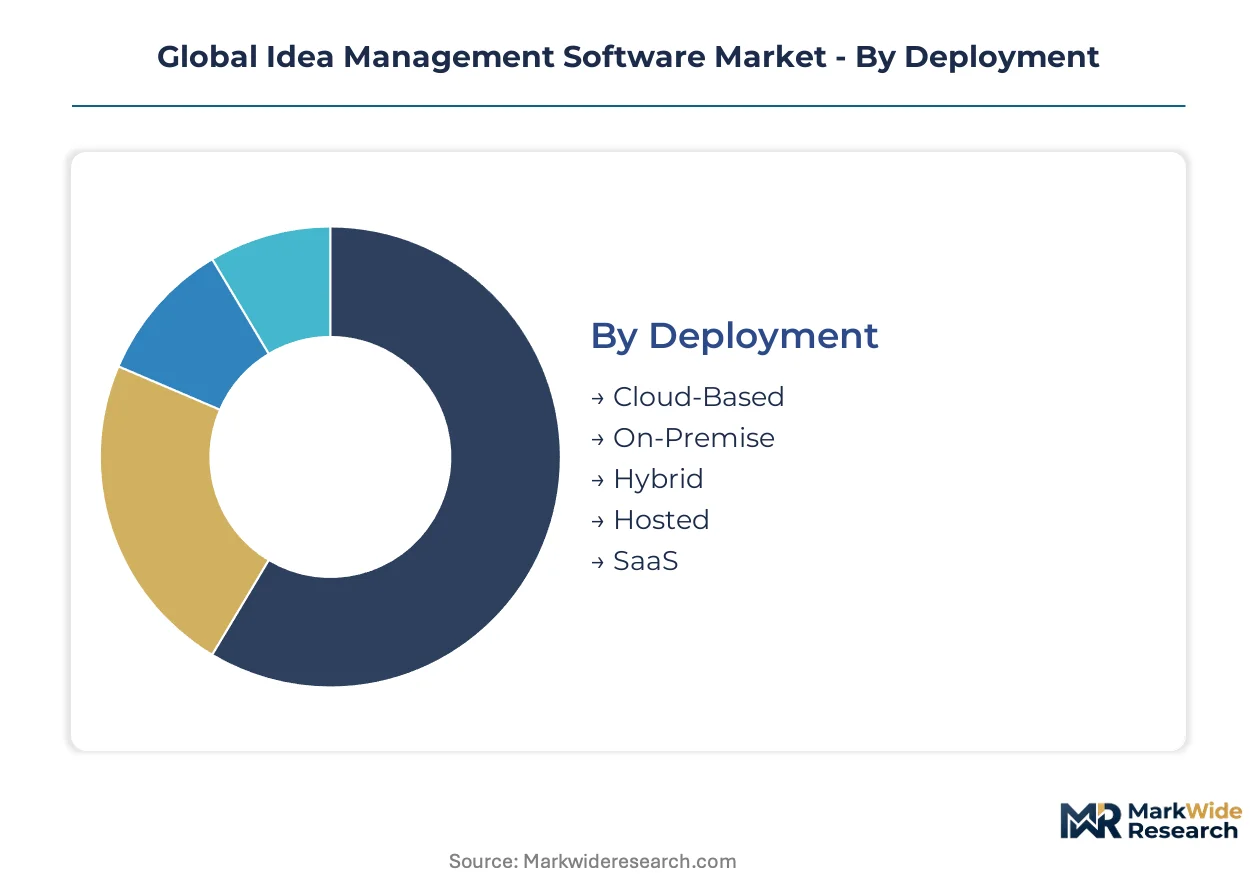
Idea management software segments reflect divergent technical architectures and organizational maturity levels. Deployment mode determines infrastructure investment and compliance posture. Solution offerings map to specific innovation workflow stages, while end-user industry shapes feature prioritization and integration complexity.
Deployment:
The customization-vs-standardization spectrum runs from fully managed cloud environments to internally controlled on-premise installations, with hybrid configurations occupying the middle ground where data sovereignty meets scalability demands.
- Cloud-Based:Multi-tenant architectures deliver elastic compute and storage through region-specific data centers. German automotive suppliers and French pharmaceutical groups favor Frankfurt and Paris zones to satisfy GDPR residency requirements without capital expenditure.
- On-Premise:Self-hosted deployments run on customer-managed hardware behind corporate firewalls. U.S. healthcare systems constrained by HIPAA deploy these configurations to maintain physical control over patient-adjacent innovation data.
- Hybrid:Split architectures process sensitive workflows on-premise while leveraging cloud burst capacity for analytics. Financial services firms in Switzerland use this model to isolate proprietary trading algorithms from public infrastructure.
- Hosted:Single-tenant dedicated instances managed by vendors but isolated from multi-tenant pools. Government agencies in India specify hosted deployments to meet BIS data localization mandates for public sector innovation programs.
- SaaS:Fully managed subscription services with zero infrastructure ownership. Technology startups across Israel and Singapore adopt SaaS for rapid deployment without IT headcount expansion.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated industries seek architectural compromise.
Solution Offering:
Cost tier segmentation separates commodity collaboration features from premium workflow automation modules that command implementation premiums and recurring integration fees.
- Workflow Automation:Engineered rule sets route ideas through multi-stage approval pipelines with conditional logic and SLA tracking. Manufacturing conglomerates in Germany deploy these modules to synchronize R&D gates across distributed engineering centers.
- Collaboration Tools:Real-time commenting, threaded discussions, and synchronous editing environments support distributed team ideation. Technology firms in California and Tel Aviv prioritize these features for remote product development teams.
- Analytics & Reporting:Dashboards visualize pipeline velocity, contributor participation rates, and outcome attribution. Corporate innovation labs in London and New York use these tools to demonstrate ROI to executive sponsors.
- Idea Crowdsourcing:Campaign-based collection interfaces with gamification and social voting mechanics. Consumer goods companies in Japan leverage these platforms for customer co-creation initiatives.
- Innovation Management:Comprehensive suites integrating portfolio tracking, resource allocation, and stage-gate methodology. Industrial machinery producers in Italy adopt these end-to-end systems for structured product line extensions.
Revenue concentrates in Workflow Automation due to integration complexity. Gaining share fastest is Innovation Management as enterprises seek consolidated platforms over point solutions.
Application:
Volume patterns correlate with organizational function maturity, where product development represents established practice and market research applications remain emergent.
- Product Development:Structured capture of feature concepts feeding agile backlogs and roadmap planning. Automotive suppliers in Stuttgart and software houses in Bangalore dominate this application segment.
- Process Improvement:Lean and Six Sigma methodology support for operational efficiency initiatives. Logistics operators in the Netherlands and chemical processors in Belgium deploy these tools for continuous improvement programs.
- Employee Engagement:Cultural initiatives using idea platforms to measure participation and sentiment. Retail chains in Australia and hospitality groups in the UAE prioritize engagement metrics for workforce retention.
- Customer Feedback:External-facing portals collecting product suggestions from consumer bases. Electronics brands in South Korea and apparel retailers in Sweden integrate these with CRM systems.
- Market Research:Early-stage concept testing and trend identification through structured crowdsourcing. CPG innovators in Brazil and fintech ventures in Nigeria experiment here with limited procurement commitment.
Procurement volume skews toward Product Development. Climbing the fastest is Process Improvement as industrial firms digitize operational excellence programs.
End User Industry:
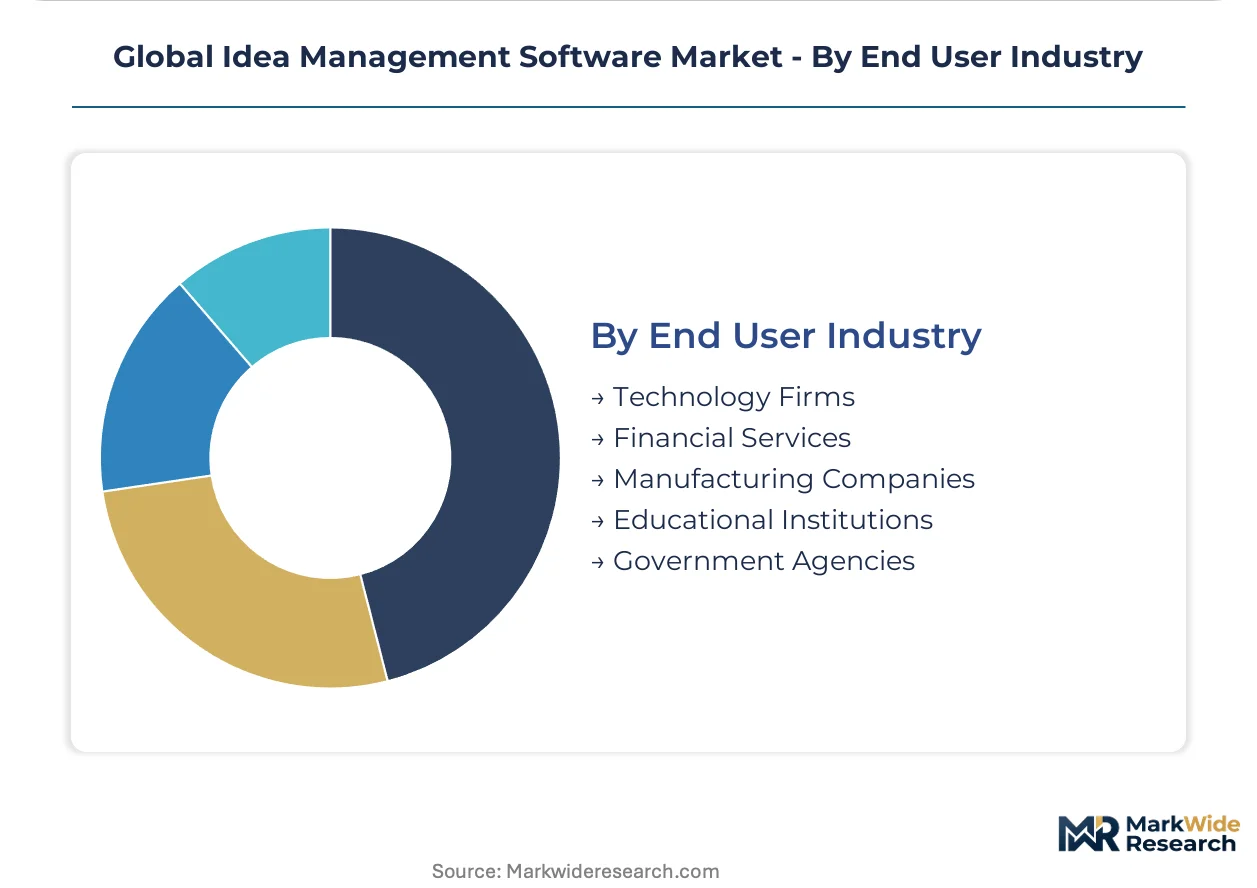
Customer type segmentation reveals divergent compliance burdens and integration depths, with financial services demanding the most stringent security architectures.
- Financial Services:Banks, insurers, and asset managers requiring encrypted transmission and granular access controls. Swiss private banks and Singaporean wealth managers lead procurement for compliance-heavy deployments.
- Technology Firms:Software and hardware developers with native cloud adoption and API-first integration requirements. Israeli cybersecurity vendors and Estonian SaaS providers represent high-velocity buyers.
- Manufacturing Companies:Industrial conglomerates with legacy ERP environments and plant-level deployment needs. German machinery builders and Japanese automotive groups drive demand for SAP-integrated solutions.
- Educational Institutions:Universities and research institutes managing intellectual property disclosure and tech transfer workflows. MIT spinout programs and ETH Zurich innovation offices pilot academic-specific configurations.
- Government Agencies:Public sector bodies with procurement transparency mandates and citizen participation goals. Dubai's smart city initiatives and Estonia's e-government programs deploy open innovation platforms.
Deployment scale peaks within Manufacturing Companies. Steepest expansion trajectory belongs to Financial Services as regulatory pressure forces platform upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The idea management software industry traces its commercial origins to Silicon Valley's enterprise SaaS wave of the early 2000s, with subsequent scaling through German industrial engineering networks and Israeli cybersecurity clusters.
United States
Technology firms in California and Massachusetts drive procurement for cloud-native collaboration tools with API-first architectures. HIPAA constrains deployment options for healthcare systems in Boston and Minneapolis, pushing demand toward encrypted on-premise configurations. Corporate innovation labs in New York and Seattle pilot outcome-based contracting models that tie subscription fees to patent filings.
Germany
Industrial conglomerates including Siemens and Bosch anchor European demand for SAP-integrated workflow automation modules. The EU AI Act mandates algorithmic transparency documentation for automated scoring systems, forcing architectural upgrades across Stuttgart and Munich engineering centers. Automotive suppliers in Baden-Württemberg deploy innovation platforms to coordinate R&D gates across distributed plant networks.
United Kingdom
Financial services firms in London and Edinburgh prioritize ISO 27001-certified platforms with granular access controls for trading floor ideation. GDPR residency requirements drive demand for UK-specific cloud instances managed through Slough and London data centers. Fintech ventures in Manchester experiment with generative AI synthesis engines for competitive intelligence applications.
India
Electronics and automotive component manufacturers expanding under the PLI scheme require BIS-compliant data localization for R&D center operations. IT services firms in Bangalore and Hyderabad embed idea management modules into client digital transformation contracts. Multinational captives in Pune and Chennai deploy platforms to capture process improvement concepts from distributed delivery teams.
Israel
Cybersecurity vendors in Tel Aviv and Herzliya adopt SaaS configurations for rapid product development cycle acceleration. The country's national data protection authority enforces strict cross-border transfer protocols for defense-adjacent innovation data. Startup accelerators in Beersheba integrate idea platforms with tech transfer workflows for university spinout programs.
Global Idea Management Software Market Competitive Landscape
The competitive structure tilts toward workflow automation specialists with deep ERP integration capabilities. Vendor concentration remains moderate, with differentiation collapsing as baseline AI features commoditize across price tiers. Two strategic archetypes dominate: established enterprise platforms with compliance-heavy deployment expertise, and agile cloud-native entrants prioritizing rapid implementation. Consolidation pressure manifests through strategic partnerships with systems integrators and geographic expansion into India and Southeast Asia.
Among the named vendors, Brightidea and Qmarkets occupy positions within the established enterprise tier, while HYPE Innovation exemplifies the European workflow automation specialist archetype. These companies represent contrasting approaches to the compliance layering challenge—Brightidea leveraging multinational deployment scale, Qmarkets emphasizing IT administrator experience, and HYPE Innovation anchoring its stance through industrial sector specialization. Each sits within a distinct competitive vector without overlapping positioning.
| Leading Market Players |
|---|
| Brightidea |
| IdeaScale |
| HYPE Innovation |
| Qmarkets |
| Spigit |
| Planbox |
| Wazoku |
| ITONICS |
| Ideawake |
| Others |
Supply & Pricing Matrix
Workflow automation premium tiers diverge sharply from basic collaboration modules, with the former commanding implementation premiums due to SAP and Oracle integration complexity while the latter faces commoditization from generative AI feature parity. This bifurcation concentrates margin capture among vendors maintaining certified ERP connector libraries, whereas pure-play SaaS entrants compete on deployment velocity at compressed price points.
Pricing Analysis
Bundled workflow automation suites separate from unbundled point solutions across the competitive landscape. Three-tier pricing structure across premium, standard, and economy levels reflects integration depth, with premium tiers mandating ISO 27001 certification and dedicated solution architects. Cost compression in the standard tier intensifies because generative AI capabilities commoditize semantic clustering features previously reserved for premium contracts. Small and mid-market technology firms exhibit highest price sensitivity, while German automotive conglomerates and Swiss financial services buyers prioritize compliance architecture over per-seat economics.
Supply Chain Analysis
Freight costs for on-premise hardware deployments remain negligible compared to cloud infrastructure provisioning expenses, which concentrate margin pressure on vendor data center strategies. Software development labor pools concentrate in India, Israel, and Germany, with Bangalore and Tel Aviv feeding engineering talent into platform R&D centers. Intellectual property licensing for NLP engines and encryption protocols draws from U.S. and European technology holdings. Single-source vulnerability emerges from hyperscaler dependency for GPU compute clusters serving generative AI features. Distribution runs through direct enterprise sales teams and specialized innovation consultancies rather than generalist software resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement teams shift evaluation criteria from feature breadth toward algorithmic auditability and multi-jurisdiction compliance certification.
For Market Incumbents: Acquire specialized systems integrators with deep SAP and Oracle connector expertise to defend against cloud-native entrants exploiting API-first architectures. Consolidate position by embedding EU AI Act documentation workflows as standard platform modules, creating switching costs for German and French enterprise accounts. Prioritize certification investment in ISO 27001 and BIS data localization to maintain procurement eligibility in regulated verticals. For New Entrants and Emerging Players: Launch via outcome-based contracting models that tie subscription fees to measurable innovation outputs such as filed patents or product launches. Target India's PLI scheme beneficiaries in electronics and automotive components, where BIS-compliant localization requirements disadvantage incumbent hyperscaler dependencies. Penetrate through innovation consultancy channel partnerships rather than direct enterprise sales, leveraging advisory relationships in U.S. healthcare and German industrial machinery verticals. For Investors and Strategic Acquirers: Asymmetric upside sits with workflow automation specialists possessing pre-built ERP connector libraries and established compliance documentation practices. Long-term viability hinges on sustained R&D differentiation as generative AI commoditizes baseline semantic analysis features. Monitor procurement contract structures for subscription-to-outcome conversion rates as inflection indicator of buyer maturity and pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built SAP connectors reduce German automotive deployment cycles from months to weeks. |
| Compliance Certification | ISO 27001 and EU AI Act documentation unlock Fortune 500 procurement pipelines. |
| Geographic Expansion | India PLI scheme compliance captures electronics and automotive R&D center demand. |
| Strategic Partnership | Innovation consultancy alliances displace generalist resellers in U.S. healthcare vertical. |
| Acquisition of Specialist Firm | Systems integrator buyouts concentrate ERP implementation risk and margin capture. |
Research Methodology
Direct dialogue with CTOs, IT procurement officers, platform engineers, and integration specialists grounded qualitative findings in deployment friction and compliance architecture priorities. Secondary validation drew from SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and enterprise software procurement databases. Bottom-up and top-down triangulation cross-checked vendor-reported deployment metrics against buyer-side budget allocation patterns.
Bottom-up modeling aggregated segment-level adoption curves across deployment mode, organization size, vertical specialization, and regional regulatory cluster. Top-down constraints applied macroeconomic boundary conditions and cross-referenced technology spending surveys. CAGRs derived from logistic diffusion curves fitted to historical adoption rates, with inputs including cloud infrastructure cost trajectories and compliance timeline data from ISO certification bodies.
Several conditions sit outside the modeled scope, including sovereign data localization mandates beyond India BIS and EU GDPR, and generative AI capability breakthroughs that could compress semantic analysis differentiation timelines. Forecasts reflect assumptions about sustained enterprise cloud migration and regulatory stability across the analysis window. Stakeholders should weight assumptions against their own operating context and monitor EU AI Act enforcement patterns for trajectory revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Equipment Management Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global ITSM Software Market
Software & Services
Lead Scoring Software Market
Software & Services
Global Content Management Software Market
Software & Services
Interactive Digital Signage Software Market
Software & Services
Global App Builder Software Market
Software & Services
Global Email Software Market
Software & Services
Global Linux Operating System Market
Software & Services
Computer Backup Software Market
Software & Services
Global Application Development Software Market
Software & Services
Workstation Software Market
Software & Services
Machine Translation Software Market