
 Text-To-Speech (TTS) Market | 2026-2036
Text-To-Speech (TTS) Market Size, Share, and Industry Trends Forecast 2026-2036
Text-To-Speech (TTS) Market Analytics
Modular API-first voice stacks are repositioning buyer choice away from monolithic platforms toward composable speech pipelines. Amazon.com Inc. leverages its cloud infrastructure to embed TTS within broader conversational AI workflows, while Microsoft Corporation anchors enterprise demand through Azure Cognitive Services integrations with productivity suites. Google LLC competes on multilingual neural model breadth, sustaining developer mindshare across mobile and web ecosystems.
Text-to-speech technology synthesizes human-like speech from textual input through acoustic modeling, neural vocoding, and prosody prediction, typically rendering output at 16-24 kHz sampling rates for commercial applications. Neural TTS architectures now dominate product roadmaps due to superior naturalness and speaker controllability, while edge computing deployments are gaining traction where latency constraints or data sovereignty requirements block cloud routing. The application dimension shows accessibility tools and IVR systems as established revenue pools, with audiobooks representing a faster-growing segment driven by subscription platform expansion.
The Federal Communications Commission and the U.S. Access Board shape domestic product standards through accessibility mandates and telecommunications quality benchmarks, while the EU AI Act imposes disclosure obligations on synthetic voice outputs that affect cross-border deployment architectures. ISO standards for intelligibility measurement provide baseline comparability across vendor claims. Stakeholders must weigh regulatory compliance costs against the strategic value of voice biometric differentiation in customer-facing channels.
Market Dynamics
Neural vocoding architectures are compressing development timelines from months to weeks, forcing incumbents to abandon statistical parametric speech synthesis entirely. This technological discontinuity is redistributing competitive advantage toward firms with proprietary training datasets and acoustic modeling expertise.
Growth Catalysts
- Section 508 mandates:Federal accessibility procurement rules in the United States require voice-enabled interfaces across government digital services, creating sustained public-sector demand for compliant TTS engines.
- Neural vocoding:End-to-end generative models now render prosody and speaker characteristics from raw text without intermediate linguistic features, slashing compute costs for real-time applications.
- Contact center modernization:Enterprise IVR replacement cycles are accelerating as legacy touch-tone systems reach end-of-life, pulling cloud-native speech pipelines into procurement scope.
Market Restraints
- GPU cluster concentration:Training large-scale neural TTS models requires access to NVIDIA H100 or equivalent accelerators, concentrating capability among hyperscalers with captive silicon supply.
- Phonetic coverage gaps:Low-resource languages lack annotated speech corpora sufficient for neural training, limiting addressable market expansion in Sub-Saharan Africa and parts of Central Asia.
- EU AI Act disclosure friction:Synthetic voice outputs must carry audible or metadata watermarks, adding engineering overhead that slows deployment timelines for cross-border products.
Strategic Opportunities
- Edge deployment architectures:On-device neural TTS is penetrating automotive infotainment and industrial headsets where cloud latency violates safety or responsiveness requirements.
- Audiobook production pipelines:Subscription platforms are consolidating exclusive content rights, creating demand for synthetic narration tools that accelerate title throughput without narrator scheduling constraints.
- Biometric voice differentiation:Custom voice avatars for brand identity are emerging as a premium service tier in customer-facing channels, commanding pricing separation from standard voices.
Industry Challenges
- Phonetic annotation talent scarcity:Linguists with expertise in speech database construction and prosody labeling command premium compensation, constraining training data scaling for mid-tier vendors.
- Legacy telephony integration:SS7 and PSTN protocol stacks in established contact centers require gateway middleware that adds latency and failure modes to cloud TTS deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Text-To-Speech (TTS) Market |
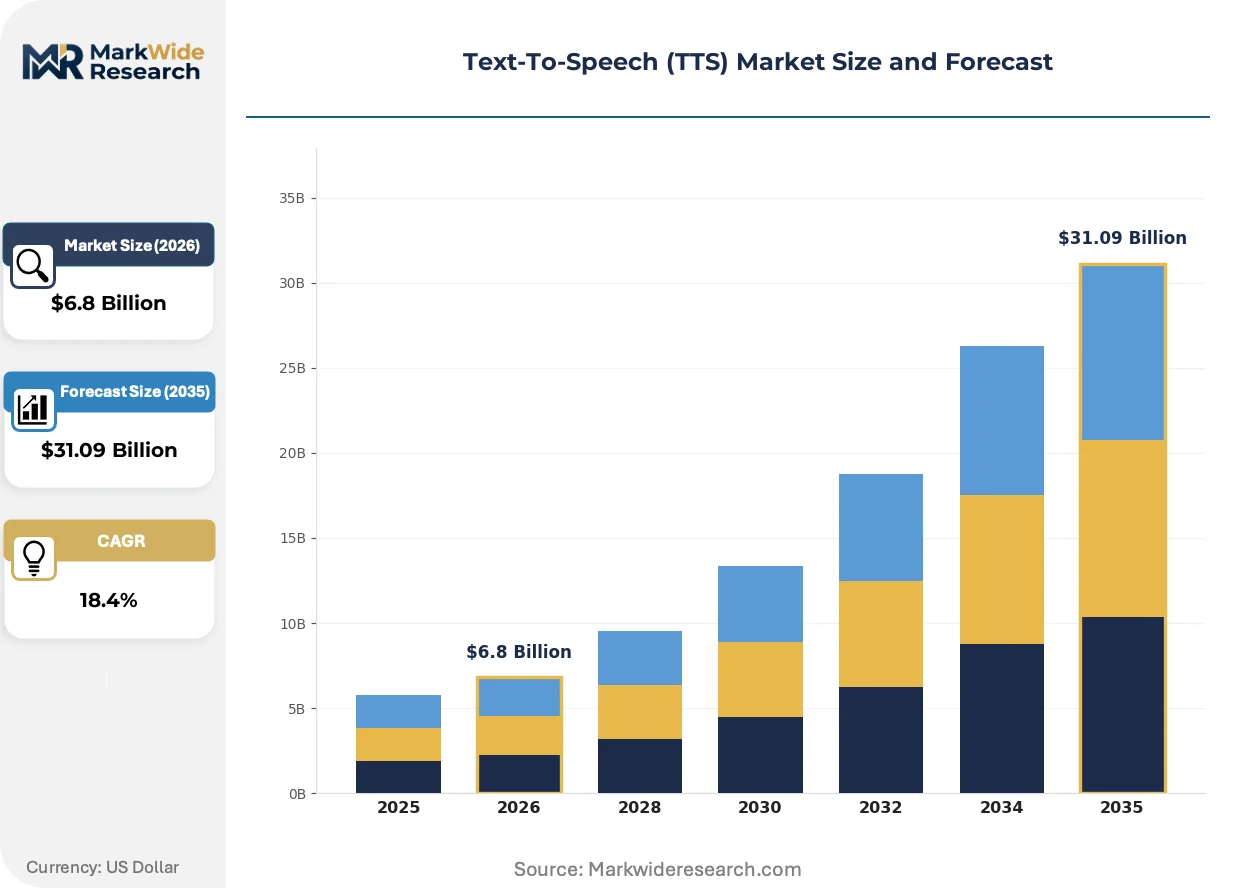
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Neural TTS, Concatenative TTS, Rule-based TTS, Hybrid TTS Deployment Model: Cloud-based, On-premises, Edge computing, Hybrid deployment End User: Education, Healthcare, Entertainment, Customer Service Application: Accessibility Tools, IVR Systems, Audiobooks, Language Learning |
| Companies Covered | Google LLC, Amazon.com Inc., Microsoft Corporation, IBM Corporation, Apple Inc., Baidu Inc., iFLYTEK Co. Ltd., ReadSpeaker B.V, Acapela Group SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Text-To-Speech (TTS) Market Evolving Landscape
Multimodal AI architectures are dissolving boundaries between text, voice, and visual synthesis, creating unified generative pipelines that TTS vendors must integrate or exit. This convergence is compressing standalone speech product margins while opening adjacent revenue pools.
Diffusion-based neural vocoding is converging with transformer text encoders to produce zero-shot speaker cloning from seconds of reference audio. Audiobook platforms are adopting these architectures to reduce narrator dependency for backlist titles. The structural consequence is converging with rights-holder negotiations over synthetic voice licensing terms, reshaping talent contract frameworks.
The EU AI Act's transparency obligations for synthetic media are mandating technical documentation and watermarking protocols that affect cross-border deployment architectures. Vendors must maintain separate model versions for European and non-European routing. Healthcare applications with patient-facing voice interfaces face the steepest compliance engineering burden.
Enterprise buyers are consolidating vendor relationships around conversational AI platforms that bundle TTS with speech recognition and dialog management. Standalone API contracts are giving way to annual platform commitments with volume tiers. This pattern is most visible in United States financial services and telecommunications verticals, where procurement teams prioritize integration depth over point-solution performance.
Text-To-Speech (TTS) Market Segmentation
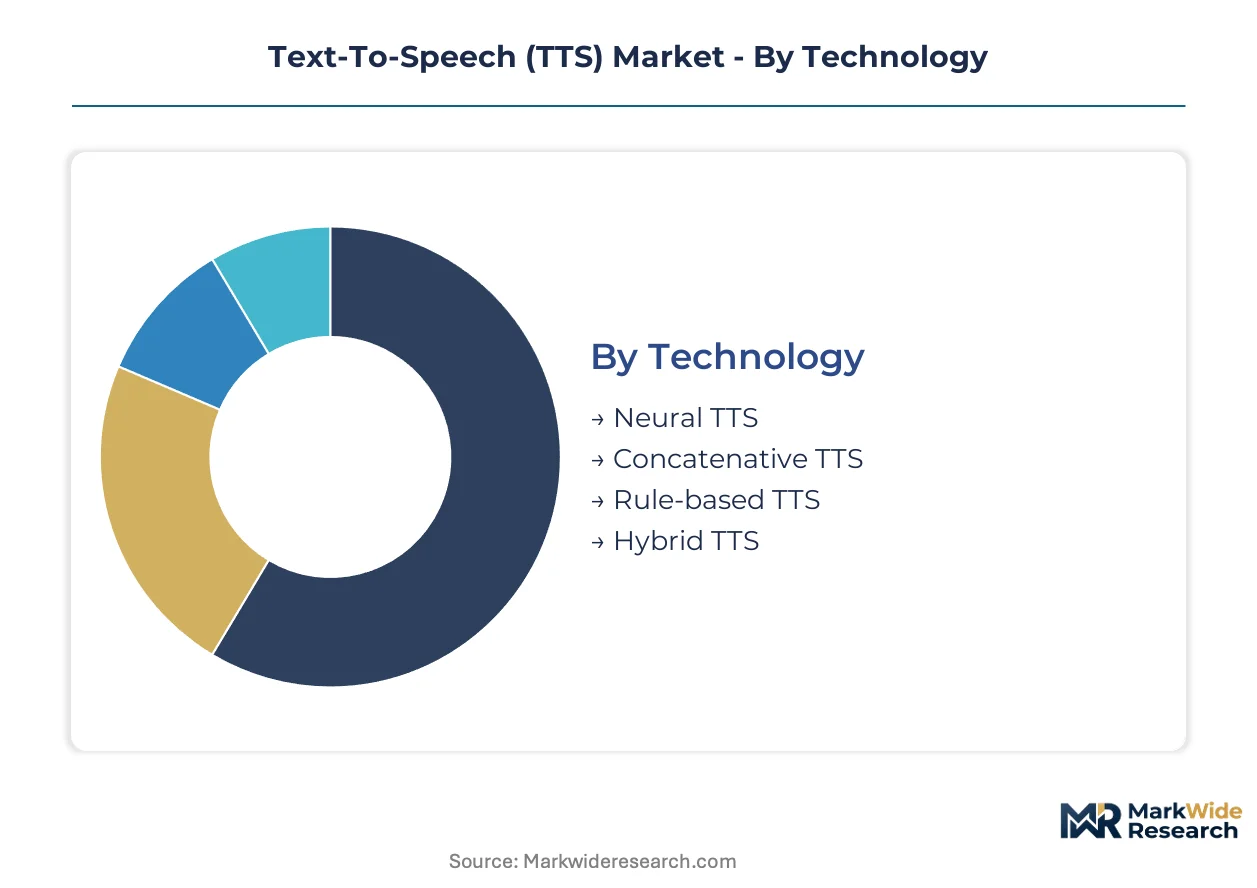
Technology choice in TTS procurement increasingly separates buyers seeking real-time naturalness from those prioritizing cost predictability or legacy compatibility. Deployment architecture and end-use vertical further stratify vendor selection criteria across accessibility mandates, entertainment pipelines, and enterprise contact center refreshes.
Technology:
Buyers differentiate primarily by inference cost tolerance versus output quality requirements.
- Neural TTS:End-to-end deep learning architectures generate spectrograms directly from text, then render waveforms through neural vocoders. Demand concentrates in United States enterprise contact centers and streaming audiobook platforms where prosody naturalness drives engagement metrics.
- Concatenative TTS:Unit selection from prerecorded speech databases delivers deterministic output with predictable compute profiles. Healthcare IVR systems and legacy banking voice portals favor this approach for regulatory audit trails and consistent pronunciation.
- Rule-based TTS:Formant synthesis and diphone concatenation operate without training data dependencies. Embedded automotive announcements and low-cost accessibility hardware in India deploy these systems where silicon constraints block neural inference.
- Hybrid TTS:Statistical parametric front-ends feed neural vocoders to balance customization depth with deployment flexibility. Language learning applications leverage this architecture for rapid speaker adaptation without full model retraining.
Volume sits with Concatenative TTS in legacy infrastructure; growth tilts toward Neural TTS.
Deployment Model:
Latency requirements and data sovereignty rules reshape routing decisions across buyer segments.
- Cloud-based:Hyperscaler APIs deliver elastic capacity for variable workloads. United States federal contractors processing Section 508 compliance audits route through FedRAMP-authorized cloud regions to satisfy procurement rules.
- On-premises:Licensed software deployments run within buyer-controlled data centers. Financial services firms in Germany maintain on-site inference clusters to satisfy BaFin operational resilience guidelines for customer authentication workflows.
- Edge computing:Quantized neural models execute on local silicon without network traversal. Automotive OEMs in Japan integrate edge TTS into head units to meet METI safety response-time standards for driver alerts.
- Hybrid deployment:Dynamic routing between cloud and edge based on connectivity state or content sensitivity. Industrial headset manufacturers serving European warehouse operators adopt this pattern to comply with GDPR data localization while preserving offline fallback.
Cloud-based deployments capture current transaction volume; edge computing climbs the fastest as automotive and industrial safety requirements harden.
End User:
Regulatory pressure and content monetization models create divergent procurement timelines.
- Education:Learning management systems and literacy tools drive institutional procurement. K-12 districts in Texas and California deploy TTS for individualized education plan compliance under federal disability accommodation mandates.
- Healthcare:Patient portals and clinical documentation workflows require HIPAA-aligned voice interfaces. United States hospital systems embed TTS into Epic and Cerner EHR integrations to reduce nursing documentation burden.
- Entertainment:Streaming platforms and game studios synthesize character dialogue and audiobook narration. Subscription services negotiate synthetic voice licensing with talent unions to accelerate backlist title production.
- Customer Service:IVR replacement and conversational AI agent deployment dominate enterprise IT budgets. Telecommunications carriers in the United States refresh legacy touch-tone systems to capture cloud-native speech recognition bundling efficiencies.
Customer Service commands current deployment volume; Entertainment shows the steepest expansion trajectory as content platforms consolidate exclusive rights.
Application:
Use case maturity determines whether buyers prioritize API flexibility or turnkey integration depth.
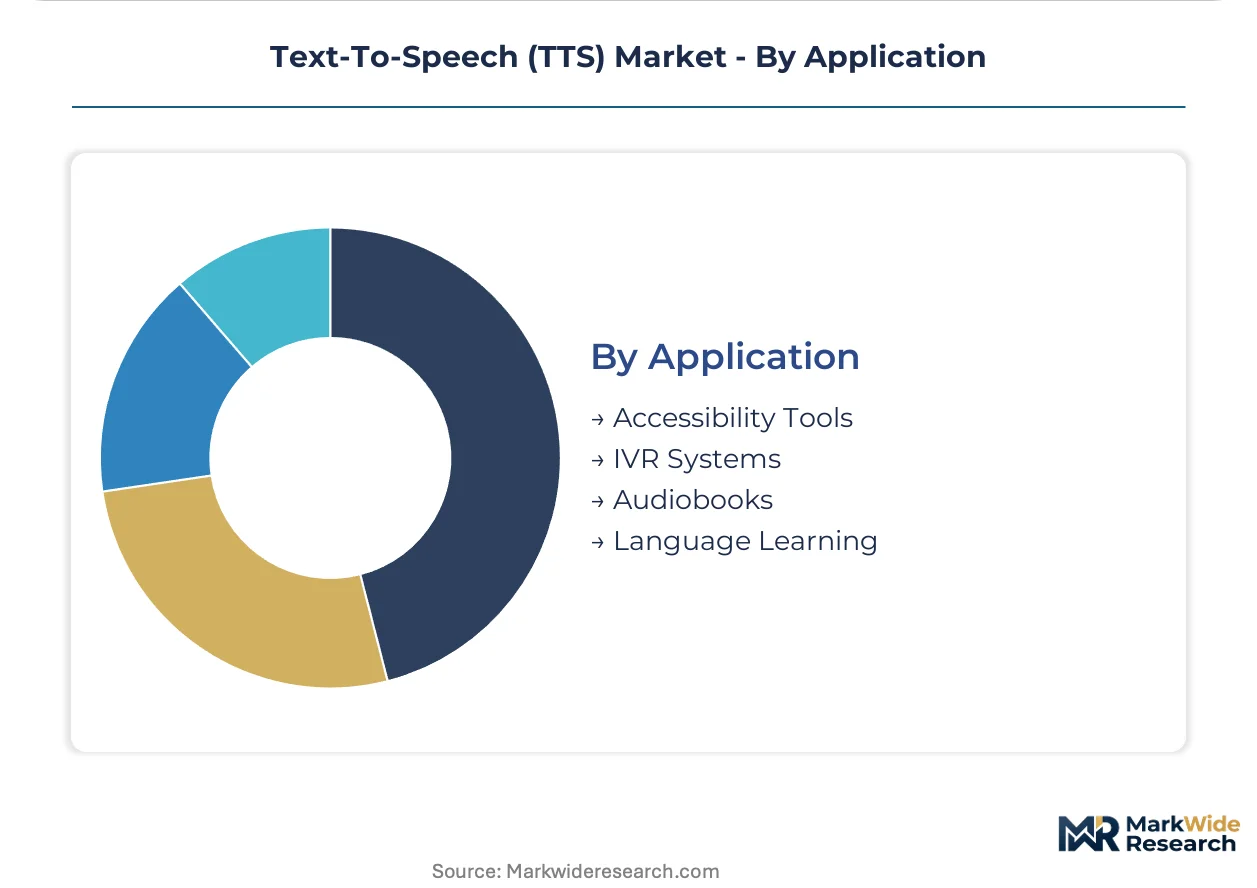
- Accessibility Tools:Screen readers and assistive communication devices constitute the original commercial TTS segment. United States federal procurement under Section 508 sustains demand for WCAG-compliant voice output across government digital services.
- IVR Systems:Interactive voice response modernization pulls TTS into broader contact center transformation programs. Banking and insurance verticals in the United States replace legacy Nuance deployments with cloud-native alternatives during five-year refresh cycles.
- Audiobooks:Synthetic narration pipelines reduce production bottlenecks for backlist and midlist titles. Spotify and Amazon-owned platforms pilot neural voice cloning to bypass narrator scheduling constraints on exclusive content.
- Language Learning:Pronunciation feedback and conversational practice modules require low-latency speech generation. Duolingo and Babbel integrate TTS APIs to scale speaking exercises without human tutor dependency.
Accessibility Tools and IVR Systems anchor installed base; Audiobooks is gaining share fastest as subscription economics reshape content production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of enterprise TTS deployments while China and Germany concentrate neural model training infrastructure. Japan and the United Kingdom anchor specialized demand for edge-computing voice applications in automotive and accessibility verticals.
United States
Federal contractors drive cloud procurement under Section 508 accessibility mandates. The FCC enforces telecommunications quality benchmarks that shape IVR system specifications. Silicon Valley clusters host hyperscaler R&D facilities advancing real-time neural vocoding architectures.
China
Domestic platform operators deploy TTS across super-app conversational interfaces at massive scale. MIIT issues algorithmic recommendation regulations that govern synthetic voice disclosure in consumer applications. Beijing and Shenzhen house the primary training clusters for Mandarin neural speech models.
Germany
Automotive OEMs demand edge-deployable TTS for in-vehicle safety alerts and infotainment. BaFin operational resilience guidelines force on-premises inference for banking voice authentication workflows. Stuttgart and Munich anchor industrial partnerships between Tier-1 suppliers and speech technology providers.
Japan
METI safety response-time standards mandate local execution for driver alert systems in automotive head units. Tokyo and Nagoya clusters specialize in low-latency embedded neural models for industrial headset manufacturers. Domestic semiconductor fabricators supply purpose-built inference silicon for these deployments.
United Kingdom
Creative industries in London pilot synthetic narration for audiobook backlist production. The UK Information Commissioner's Office applies GDPR-derived transparency requirements to synthetic voice outputs. Manchester and Edinburgh host specialized studios negotiating talent union contracts for cloned voice licensing.
Text-To-Speech (TTS) Market Competitive Landscape
The competitive structure tilts toward hyperscaler dominance with specialized regional players occupying niche positions. Cloud infrastructure ownership and proprietary training data access create steep barriers for mid-tier entrants. Two archetypes prevail: vertically integrated platform operators bundling TTS within conversational AI stacks, and voice-specialist vendors selling modular API access. Dominant competitive moves include strategic partnerships with automotive OEMs for edge deployment rights and portfolio diversification into multimodal generative pipelines.
Among hyperscaler platform operators, Amazon.com Inc., Google LLC, and Microsoft Corporation exemplify the integrated-stack archetype. Amazon leverages captive cloud infrastructure to embed TTS within broader conversational AI workflows. Google competes on multilingual neural model breadth across mobile and web ecosystems. Microsoft anchors enterprise demand through productivity suite integrations. These three occupy positions that smaller specialized vendors cannot replicate without comparable infrastructure scale.
| Leading Market Players |
|---|
| Google LLC |
| Amazon.com Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Apple Inc. |
| Baidu Inc. |
| iFLYTEK Co. Ltd. |
| ReadSpeaker B.V |
| Acapela Group SA |
| Others |
Value Network & Pricing Analysis
EU AI Act disclosure mandates for synthetic media gate both qualified supply and premium-tier pricing access, as vendors must engineer separate model versions with audible watermarks and technical documentation to serve European buyers. This compliance burden stratifies the vendor base between hyperscalers with captive legal-engineering resources and mid-tier players forced into channel partnerships.
Pricing Analysis
Margin tightening in standard-tier API access reflects hyperscaler volume bundling with conversational AI platforms. Three-tier pricing structure across premium, standard, and economy levels separates custom voice avatar development from off-the-shelf neural voices and legacy concatenative licenses. Price differentiation rests on ISO-certified intelligibility benchmarking and FedRAMP authorization status. Healthcare systems and federal contractors show lowest price sensitivity due to accessibility mandate compliance requirements, while indie audiobook publishers drive cost-down pressure on per-character inference rates.
Supply Chain Analysis
FedRAMP and ISO certification gating restricts qualified GPU cluster supply to United States, China, and Germany, where hyperscalers maintain captive silicon access and annotated speech corpus libraries. Raw material dependencies center on NVIDIA H100 accelerators, phonetically annotated training databases, and specialized neural vocoder inference chips. Single-source vulnerability concentrates in NVIDIA's foundry relationships for training hardware. Distribution runs through hyperscaler marketplaces and direct enterprise platform contracts, with edge deployment hardware flowing through automotive Tier-1 supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
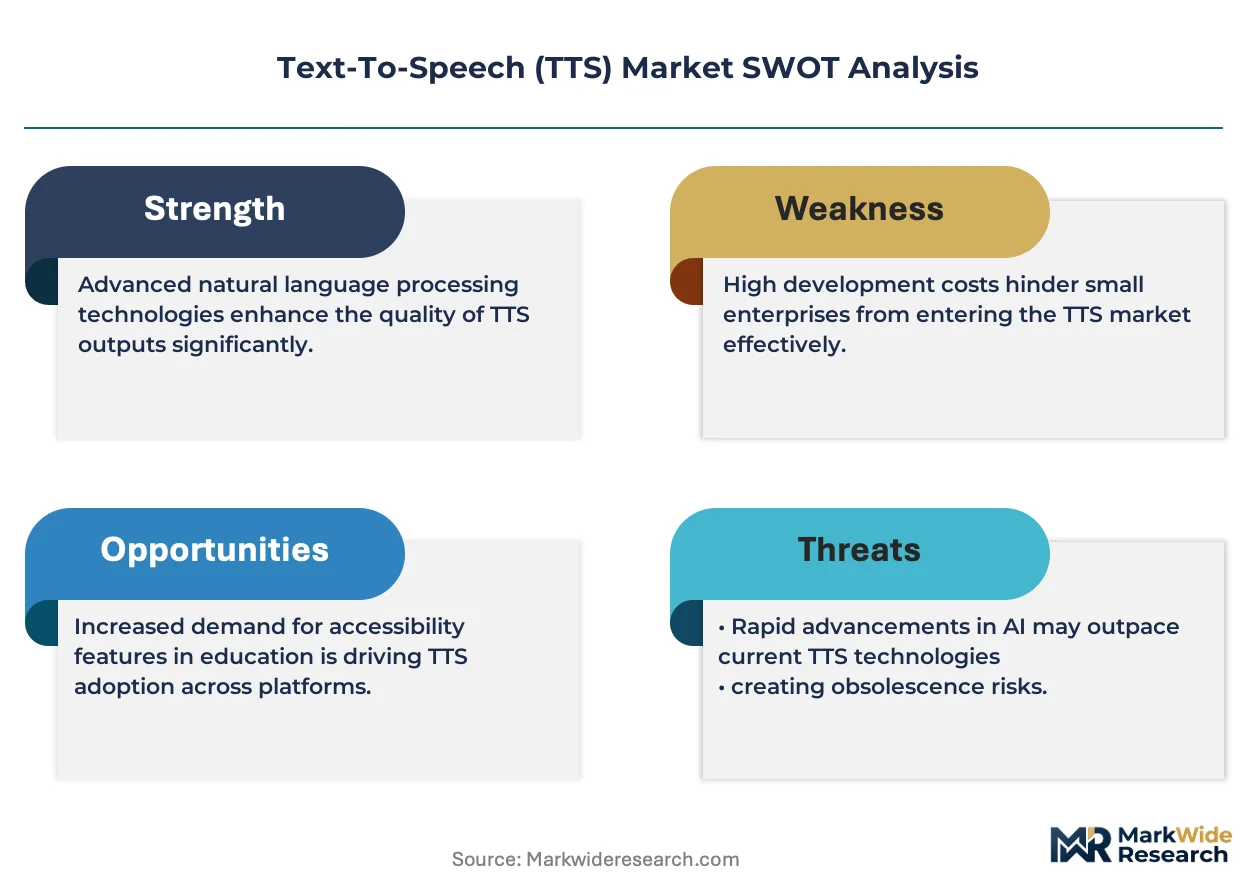
The Text-To-Speech market operates as a cost-of-compliance story where EU AI Act watermarking and documentation requirements create a barrier-to-entry moat for vendors with legal-engineering scale.
For Market Incumbents: Extend proprietary training data moats through exclusive licensing agreements with audiobook publishers and healthcare systems. Consolidate edge deployment partnerships with automotive OEMs before neural model quantization becomes commoditized. Vertical integration into custom voice avatar services captures pricing separation from standard API tiers. For New Entrants and Emerging Players: Low-resource language phonetic coverage gaps offer a technology-first wedge into Sub-Saharan African and Central Asian markets where hyperscaler models underperform. Target educational accessibility mandates in India and Brazil with rule-based TTS optimized for silicon-constrained hardware. Pursue channel partnerships with learning management system integrators rather than direct enterprise sales. For Investors and Strategic Acquirers: Audiobook platform adoption of zero-shot speaker cloning is the leading indicator that synthetic narration pipelines will consolidate around voice-specialist vendors with talent union relationships. Long-term viability favors acquirers of proprietary speech corpus libraries and acoustic modeling teams over API-only operators. Watch for hyperscaler bundling discounts crossing 40% threshold as signal of standalone TTS margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Training Data Acquisition | Exclusive audiobook publisher agreements lock in speaker cloning rights against hyperscaler replication. |
| Edge Computing Partnership | Automotive OEM safety certification for METI-compliant driver alert systems opens Japanese industrial channels. |
| Regulatory Compliance Engineering | EU AI Act watermarking infrastructure separates European-routing products from non-compliant competitors. |
| Multimodal Platform Integration | Unified generative pipelines with visual synthesis capture enterprise conversational AI procurement budgets. |
| Custom Voice Avatar Development | Brand-differentiated synthetic voices command premium pricing in customer-facing IVR and advertising channels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with conversational AI platform engineers, contact center procurement directors, audiobook production executives, and healthcare IT integration specialists. Secondary sources included FCC accessibility mandate documentation, EU AI Act technical standards, ISO intelligibility measurement protocols, hyperscaler capex disclosures, and federal Section 508 procurement databases. Bottom-up TTS deployment counts across enterprise verticals reconciled with top-down conversational AI market sizing.
Data-stream reconciliation across technology type, deployment model, end-user vertical, and application use case generated volume and value outputs over the projection horizon. CAGRs derived from neural TTS adoption curves in enterprise contact centers and subscription audiobook platform expansion. Industry-specific forecast inputs incorporated GPU cluster capacity constraints and phonetic annotation labor scarcity.
Several conditions sit outside the modeled scope, including unforeseen regulatory fragmentation beyond EU AI Act provisions and breakthrough architectures displacing transformer-based neural vocoding. Forecasts reflect assumptions about hyperscaler bundling persistence and edge computing silicon cost trajectories. A model refresh is warranted upon material change in NVIDIA foundry allocation or federal accessibility mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Automotive Predictive Diagnostic System Market
Artificial Intelligence (AI)
Artificial Intelligence of Things (Aiot) Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Global Artificial Intelligence-Emotion Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Japan Edge AI Market